
 Aeronautical Wind Tunnel Market | 2026-2036
Aeronautical Wind Tunnel Market Size, Share, and Industry Trends Forecast 2026-2036
Aeronautical Wind Tunnel Market Insights
Defense procurement priorities are repositioning demand within the aeronautical wind tunnel sector, with military aerospace engineering displacing commercial aviation as the dominant application segment. Boeing Company leverages its captive testing infrastructure across multiple US facilities to reduce third-party facility dependency. Lockheed Martin Corporation anchors its Skunk Works programs with dedicated supersonic wind tunnel access for classified airframe development. Airbus S.A.S. competes through European Transonic Windtunnel partnerships that sustain its civil-military dual-use aerodynamic programs.
An aeronautical wind tunnel is a controlled test facility that accelerates air through a ducted circuit—open or closed—to simulate flight conditions across subsonic through supersonic regimes, typically achieving Mach numbers from 0.3 to 5.0 depending on nozzle configuration and compressor capacity, with force balances, pressure transducers, and particle image velocimetry systems capturing lift, drag, and flow separation data for airframe and propulsion integration validation. Closed wind tunnel designs dominate margin pools due to their energy efficiency and precise environmental control for transonic testing, while supersonic wind tunnel installations represent the fastest-growing product category driven by hypersonic weapons and next-generation interceptor programs. Data acquisition systems within the technology segment are capturing disproportionate investment as stakeholders demand higher-fidelity unsteady pressure measurements and real-time modal analysis.
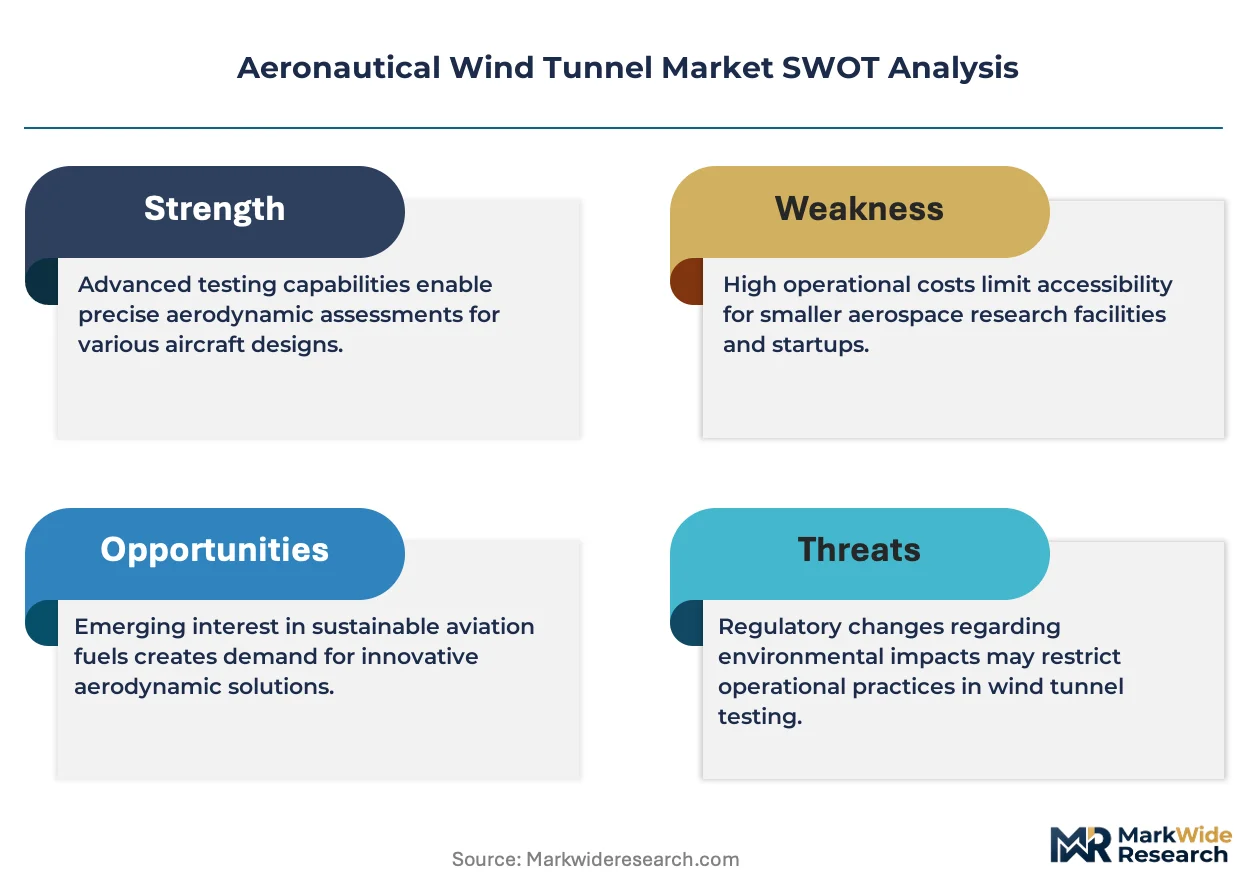
The FAA and EASA impose iterative airworthiness validation requirements that expand wind tunnel test matrices before first flight certification, while the US Department of Defense through NAVAIR and AFLCMC mandates specific Mach-Reynolds correlation standards for military airframe qualification. Germany's KBA and BAM coordinate with DNW operations to maintain CE-compliant facility standards that govern European access protocols. Stakeholders must monitor how evolving hypersonic test standards and export-controlled simulation software reshape facility investment timelines and international collaboration frameworks.
Market Dynamics
Sixth-generation fighter programs and hypersonic weapons development are compressing test cycle timelines while expanding Mach regime requirements beyond legacy facility capabilities.
Growth Catalysts
- Hypersonic weapons programs:Military aerospace engineering now demands supersonic and hypersonic test envelopes that legacy subsonic tunnels cannot replicate, driving facility upgrades across NATO defense infrastructure.
- FAA airworthiness protocols:Expanded aerodynamic validation matrices now precede prototype flight certification, extending wind tunnel utilization rates for commercial airframe programs.
- Computational fluid dynamics integration:Hybrid physical-digital test workflows reduce iteration cycles while increasing data density per tunnel hour, improving capital efficiency for facility operators.
Market Restraints
- Energy cost volatility:Closed-circuit transonic tunnels consume 50-200 megawatts during continuous operation, exposing operators to electricity price swings that compress operating margins.
- Compressor supply concentration:Specialized multi-stage axial compressors for Mach 3+ facilities source from a limited German and US supplier base, creating procurement bottlenecks.
- Reynolds number scaling limits:Full-scale Reynolds simulation remains physically impossible in ground facilities, forcing extrapolation that introduces certification risk for novel airframe designs.
Strategic Opportunities
- India defense modernization:The country's national aerospace regulator is establishing indigenous hypersonic test capability, creating equipment and know-how export potential for established facility builders.
- Urban air mobility certification:eVTOL manufacturers require low-speed rotary aerodynamic validation that repurposes existing subsonic infrastructure for emerging application demand.
- Green hydrogen propulsion testing:Cryogenic hydrogen handling systems and combustion stability measurement represent unaddressed capability gaps in current tunnel instrumentation portfolios.
Industry Challenges
- Specialized aerodynamicist scarcity:Unsteady flow measurement and modal analysis expertise concentrates in aging cohorts at national laboratories, constraining workforce expansion for commercial facility operators.
- ITAR-controlled software integration:Export-controlled computational mesh generation and turbulence modeling codes complicate international collaborative test programs and facility joint ventures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aeronautical Wind Tunnel Market |
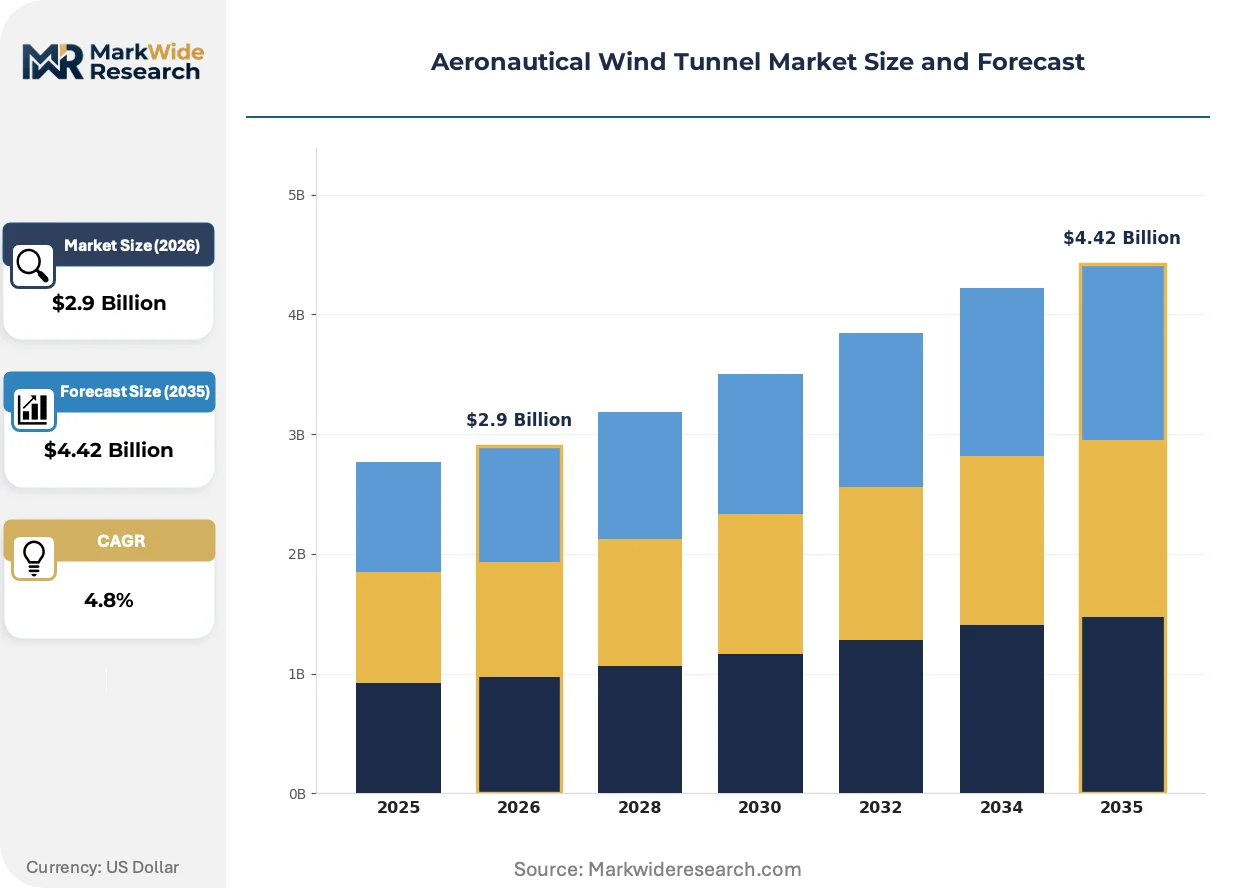
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $4.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Wind Tunnel, Closed Wind Tunnel, Subsonic Wind Tunnel, Supersonic Wind Tunnel Application: Aerospace Engineering, Automotive Testing, Research & Development, Educational Institutions Technology: Testing Equipment, Data Acquisition Systems, Control Systems, Visualization Techniques End User: Aerospace Manufacturers, Automotive Companies, Government Agencies, Research Organizations |
| Companies Covered | Boeing Company, Lockheed Martin Corporation, Airbus S.A.S., Northrop Grumman Corporation, Mitsubishi Heavy Industries, Aerolab LLC, Calspan Corporation, European Transonic Windtunnel, German-Dutch Wind Tunnels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aeronautical Wind Tunnel Market Trends and Innovations
Distributed sensor networks and real-time data fusion are transforming how aerodynamic data is captured, processed, and validated against computational predictions.
Particle image velocimetry systems are absorbing capital investment priority as defense and commercial programs demand spatially resolved unsteady flow field data rather than integrated force measurements alone. Lockheed Martin's Skunk Works programs and Airbus S.A.S. civil-military divisions now specify PIV inclusion in test protocols. This instrumentation shift is absorbing margin from traditional force balance suppliers while expanding the addressable market for high-speed camera and laser subsystem vendors.
EASA's expanding airworthiness validation requirements for novel propulsion architectures now mandate iterative wind tunnel matrices before prototype flight, extending test timelines for clean-sheet aircraft programs. The regulation compresses development schedules while expanding facility booking windows. European transonic infrastructure faces the tightest capacity constraints as a result, with German-Dutch Wind Tunnels facility utilization rates reflecting this pressure.
Defense procurement patterns now favor captive or dedicated facility access over shared commercial infrastructure, reversing decades of outsourcing trends. Prime contractors negotiate long-term block bookings or exclusive test windows rather than spot-market facility access. This preference shift is most visible in US sixth-generation fighter development, where classified airframe programs demand security-cleared personnel and segmented facility operations that commercial tunnels cannot readily supply.
Aeronautical Wind Tunnel Market Segmentation
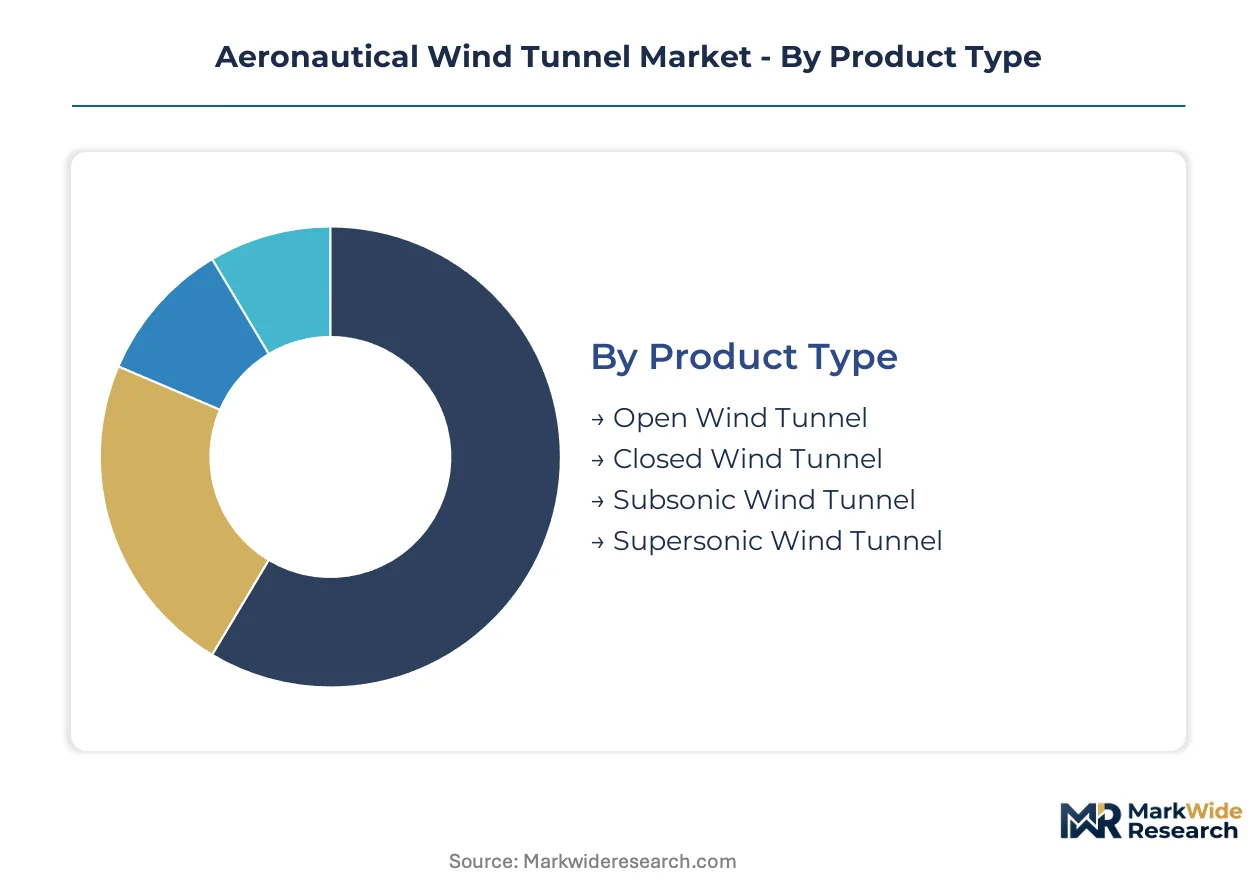
Wind tunnel segmentation reveals how facility operators prioritize capital deployment across divergent technical requirements. Product type distinctions drive energy infrastructure decisions, while application and technology segments expose where instrumentation investment concentrates.
Product Type:
Facility upgrade cycles favor closed-circuit designs for energy efficiency, though supersonic capability expansions now command disproportionate capital allocation.
- Closed Wind Tunnel:Recirculating airflow through a sealed test section delivers precise environmental control and reduced power consumption for transonic regimes. German-Dutch Wind Tunnels facility operations anchor European demand for this configuration, driven by EASA certification protocols requiring repeatable Mach 0.8-1.2 test conditions. Energy cost volatility compresses operating margins for open-circuit alternatives, positioning closed designs at the top of replacement priority lists.
- Supersonic Wind Tunnel:Specialized nozzle configurations and multi-stage axial compressors achieve Mach 3+ test envelopes essential for hypersonic weapons validation. US Department of Defense programs through NAVAIR and AFLCMC mandate specific Mach-Reynolds correlation standards that only dedicated supersonic infrastructure satisfies. Compressor supply concentration between German and US vendors creates procurement bottlenecks for new installations.
- Open Wind Tunnel:Straight-through airflow design suits low-speed aerodynamic screening where energy efficiency matters less than capital cost.
- Subsonic Wind Tunnel:Mach 0.3-0.8 capability supports commercial airframe development and urban air mobility certification requirements.
Closed Wind Tunnel sits at the top of the volume ranking, with Supersonic Wind Tunnel climbing the fastest.
Application:
Defense procurement priorities now concentrate test-hour allocation toward military aerospace programs, displacing commercial aviation from its historical dominance.
- Aerospace Engineering:Airframe and propulsion integration validation spans subsonic through hypersonic regimes, with force balances and pressure transducers capturing lift, drag, and flow separation data. Sixth-generation fighter programs in the United States and Europe compress test cycle timelines while expanding Mach regime requirements. Boeing Company and Lockheed Martin Corporation leverage captive testing infrastructure to reduce third-party facility dependency.
- Research & Development:National laboratory and university programs advance unsteady flow measurement and modal analysis techniques that migrate toward commercial facility standards. Aging cohorts of specialized aerodynamicists at these institutions constrain workforce expansion for commercial operators. FAA and EASA iterative validation requirements extend wind tunnel utilization rates for clean-sheet aircraft programs.
- Automotive Testing:Aerodynamic drag reduction for electric vehicle range optimization drives low-speed tunnel bookings.
- Educational Institutions:Undergraduate engineering programs utilize scaled demonstration tunnels for curriculum-based fluid mechanics instruction.
Aerospace Engineering commands the dominant share of facility hours, while Research & Development exhibits the steepest expansion trajectory as hybrid physical-digital workflows mature.
Technology:
Instrumentation investment disproportionately favors data density improvements over traditional force measurement systems.
- Data Acquisition Systems:Real-time unsteady pressure measurement and modal analysis capabilities now specify minimum performance thresholds in defense procurement contracts. Higher-fidelity sampling rates and channel densities absorb disproportionate R&D budgets as stakeholders demand validation against computational predictions. Particle image velocimetry integration exemplifies this shift toward spatially resolved flow field data.
- Testing Equipment:Force balances and pressure transducers remain foundational for integrated aerodynamic coefficient derivation, though margin pools shift toward optical and laser-based alternatives. Traditional suppliers face pricing pressure as prime contractors specify PIV inclusion in test protocols.
- Control Systems:Automated Mach number regulation and sting positioning reduce test cycle duration and operator error.
- Visualization Techniques:Schlieren photography and oil flow surface tracing supplement quantitative measurement with qualitative flow feature identification.
Testing Equipment retains the largest installed base, with Data Acquisition Systems gaining share fastest through defense program specification changes.
End User:
Captive facility preference among prime contractors reshapes demand concentration away from shared commercial infrastructure.
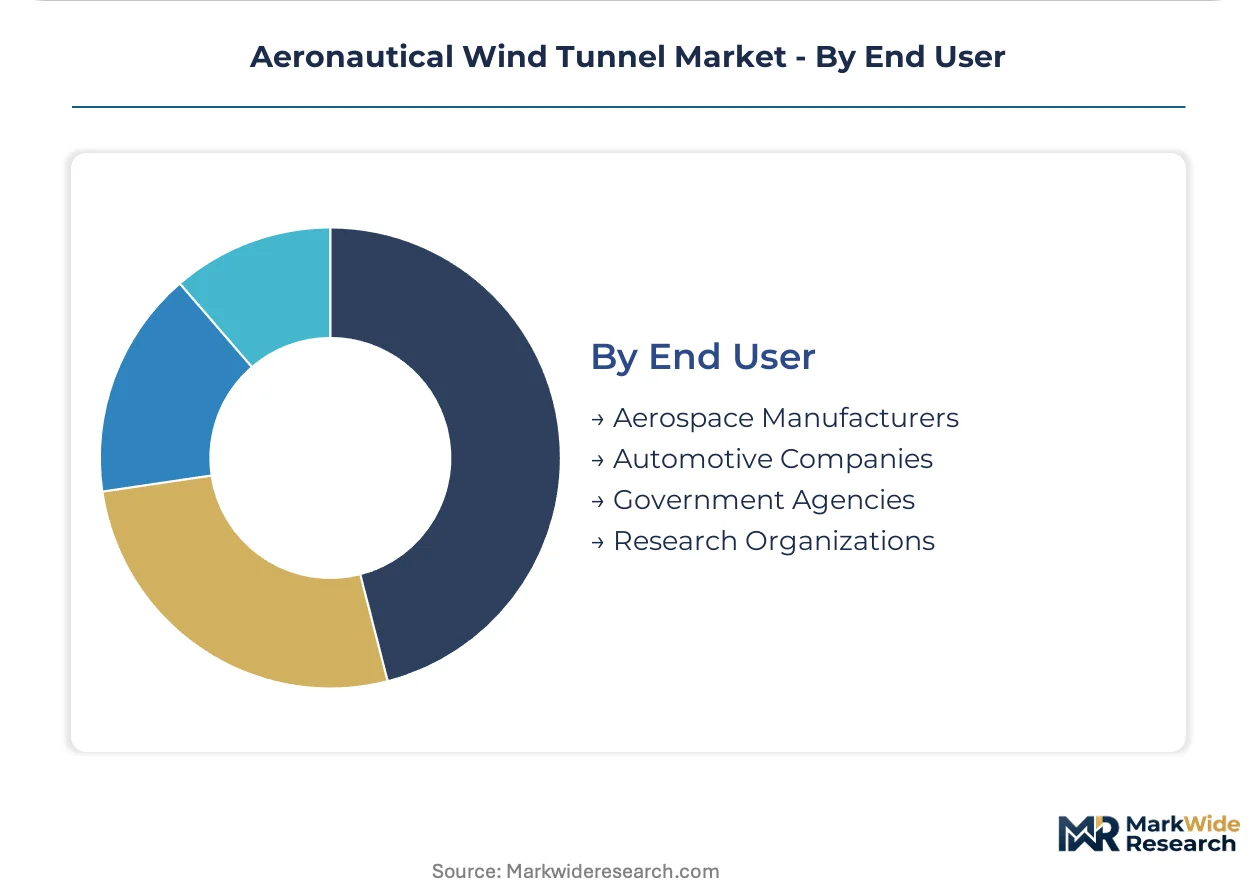
- Government Agencies:National aerospace regulators and defense research establishments maintain sovereign test capability for classified programs and certification standard-setting. US Department of Defense block bookings and exclusive test windows reverse decades of outsourcing trends. India's national aerospace regulator is establishing indigenous hypersonic test capability, creating equipment export potential.
- Aerospace Manufacturers:Airbus S.A.S. competes through European Transonic Windtunnel partnerships that sustain civil-military dual-use aerodynamic programs. Long-term facility access negotiations prioritize security-cleared personnel and segmented operations that commercial tunnels cannot readily supply.
- Automotive Companies:Electric vehicle programs drive aerodynamic efficiency validation through external tunnel contracts.
- Research Organizations:Independent institutes and consortia access shared facilities for pre-competitive and academic research programs.
Government Agencies anchor the volume ranking, with Aerospace Manufacturers expanding their captive infrastructure fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility operators migrate capital toward jurisdictions where defense procurement offsets energy compliance costs, creating divergent investment trajectories across national aerospace ecosystems. The FAA and EASA regulatory divergence on airworthiness validation timelines reshapes where prime contractors book test hours. Sovereign hypersonic programs in multiple countries now anchor regional infrastructure decisions.
United States
Sixth-generation fighter development through NAVAIR and AFLCMC compresses test cycle timelines while mandating Mach-Reynolds correlation standards that only dedicated supersonic infrastructure satisfies. The FAA imposes iterative airworthiness validation matrices that extend wind tunnel utilization for commercial programs. Boeing Company and Lockheed Martin Corporation leverage captive testing infrastructure across California and Texas facilities to reduce third-party dependency.
Germany
The German-Dutch Wind Tunnels facility anchors European transonic and supersonic research infrastructure, with KBA and BAM coordinating CE-compliant standards that govern regional access protocols. EASA certification requirements for novel propulsion architectures mandate expanded test matrices before prototype flight. Airbus S.A.S. operations in Hamburg and Munich sustain civil-military dual-use aerodynamic programs through European Transonic Windtunnel partnerships.
United Kingdom
BAE Systems plc anchors national hypersonic test capability development, with defense procurement patterns favoring captive facility access over shared commercial infrastructure. The country's national aerospace regulator coordinates with EASA on airworthiness validation protocols while maintaining sovereign standards for classified programs. Industrial clusters in Lancashire and Bristol concentrate airframe development expertise that demands localized test capacity.
Japan
Mitsubishi Heavy Industries anchors indigenous fighter development programs that drive domestic wind tunnel investment, with METI coordinating national aerospace technology roadmaps. The country's national aerospace regulator maintains sovereign test standards that diverge from FAA-EASA harmonization efforts. Industrial concentration in Nagoya and Tokyo sustains captive testing infrastructure for civil-military dual-use programs.
India
The country's national aerospace regulator is establishing indigenous hypersonic test capability, creating equipment and know-how export potential for established facility builders. Defense modernization programs compress procurement timelines while expanding Mach regime requirements beyond legacy infrastructure. Industrial clusters in Bangalore and Hyderabad concentrate aerospace engineering expertise that demands expanded ground test validation.
Aeronautical Wind Tunnel Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense primes capturing captive infrastructure while independent operators serve commercial and research markets. The vendor base concentrates around three strategic archetypes: sovereign facility operators, aerospace manufacturer captives, and independent test service providers. Consolidation pressure runs through defense procurement preferences for dedicated access. Capacity expansion and strategic partnerships dominate competitive moves as operators secure long-term block bookings.
Among defense contractor captives, Boeing Company and Lockheed Martin Corporation exemplify the captive infrastructure archetype, each maintaining proprietary test facilities that reduce third-party dependency for classified programs. Airbus S.A.S. occupies a hybrid position, combining European Transonic Windtunnel partnership access with in-house capability. Independent operators including Calspan Corporation and Aerolab LLC represent the contract research tier, serving programs where prime contractors lack dedicated infrastructure or require specialized test envelopes.
| Leading Market Players |
|---|
| Boeing Company |
| Lockheed Martin Corporation |
| Airbus S.A.S. |
| Northrop Grumman Corporation |
| Mitsubishi Heavy Industries |
| Aerolab LLC |
| Calspan Corporation |
| European Transonic Windtunnel |
| German-Dutch Wind Tunnels |
| Others |
Pricing and Supply Chain Analysis
Multi-stage axial compressor procurement costs from German and US suppliers cascade through facility construction quotes, segmenting the installed base between premium transonic installations and economy-grade subsonic alternatives. Energy consumption during continuous 50-200 megawatt operations then stratifies operating cost structures across captive defense infrastructure and shared commercial facilities.
Pricing Analysis
Direct-to-OEM contracting eliminates distributor margins for prime contractors like Boeing Company and Lockheed Martin Corporation, while independent test service providers absorb 15-25% facility markup over operating costs. Three-tier pricing structure across premium, standard, and economy levels separates Mach 3+ supersonic capability from transonic validation and low-speed screening services. Pricing pressure stems from electricity cost volatility compressing operating margins for continuous-run facilities. Commercial aviation programs exhibit highest price sensitivity due to outsourced test-hour budgeting, whereas classified defense programs prioritize security-cleared access over unit cost.
Supply Chain Analysis
Specialized multi-stage axial compressor manufacturing rests on a concentrated German and US supplier base, with Siemens Energy and Howden Roots anchoring Mach 3+ facility deployments. High-grade aluminum alloys for test section construction and precision force balance instrumentation feed from Japanese and German specialty metal producers. Single-source vulnerability concentrates in cryogenic hydrogen handling systems for emerging propulsion testing applications. Distribution runs through national laboratory procurement channels and defense prime contractor captive supply agreements rather than open commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aeronautical wind tunnel market functions as a regulatory compounder where FAA and EASA airworthiness validation mandates expand test matrices before prototype flight, embedding demand growth into certification timelines.
For Market Incumbents: Extend captive facility utilization through long-term block bookings with NAVAIR and AFLCMC programs, securing revenue visibility against emerging hybrid physical-digital test workflow substitution. Backward integration into particle image velocimetry subsystems captures margin shifting from traditional force balance suppliers. Capacity expansion in Germany and Texas reinforces proximity to sixth-generation fighter development clusters. For New Entrants and Emerging Players: Urban air mobility manufacturers represent an underserved buyer archetype requiring low-speed rotary aerodynamic validation that repurposes existing subsonic infrastructure. India's indigenous hypersonic capability buildout offers equipment export and technical advisory entry points without direct facility competition. A consulting-led go-to-market model positioning around ITAR-compliant software integration addresses workforce scarcity constraints. For Investors and Strategic Acquirers: Consolidation pressure builds where defense procurement preferences favor dedicated facility access over shared commercial infrastructure, concentrating value in captive infrastructure operators. Long-term viability centers on sovereign test capability maintenance across NATO defense ecosystems. Acquisition targets include independent test service providers with EASA certification credentials and underutilized supersonic capacity. The signal to watch is India's national aerospace regulator procurement timelines for hypersonic test equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Supersonic Capacity Expansion | Mach 3+ facility upgrades satisfy NAVAIR hypersonic weapons validation requirements. |
| PIV System Integration | Particle image velocimetry inclusion responds to Lockheed Martin Skunk Works test protocols. |
| European Transonic Partnership | ETW access agreements sustain Airbus S.A.S. civil-military dual-use aerodynamic programs. |
| Cryogenic Hydrogen Instrumentation | Green hydrogen propulsion testing capability addresses unaddressed combustion stability measurement gaps. |
| ITAR-Compliant Software Development | Export-controlled mesh generation codes enable international collaborative test program participation. |
Research Methodology
Bottom-up aerospace engineering and research institution modeling reconciled against top-down defense procurement and facility construction tracking forms the analytical core. Primary interviews with wind tunnel facility directors, aerodynamic test engineers at Boeing Company and Lockheed Martin Corporation, EASA certification specialists, and compressor procurement leads at German-Dutch Wind Tunnels combined with secondary validation against FAA airworthiness directives, EASA certification protocols, NAVAIR test standards documentation, and Department of Defense budget justification materials. Triangulation across these sources calibrated segment-level demand estimates.
Historical trendline analysis of facility utilization rates, defense procurement patterns, and commercial aviation certification timelines informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type configuration, application sector, instrumentation technology tier, and end-user captive versus shared facility preference. CAGRs derived from regression analysis of booked test-hour growth against installed capacity expansion. Industry-specific forecast inputs incorporated sixth-generation fighter program timelines and EASA novel propulsion architecture validation requirements.
Underlying measurement precision varies by segment; defense contractor captive infrastructure carries tighter precision than emerging urban air mobility demand estimates. Forecasts reflect documented assumptions regarding energy cost trajectories and compressor supply availability. Regulatory divergence between FAA and EASA certification timelines, export control enforcement shifts, and hypersonic test standard evolution represent specific risk factors warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Business Jets Market
Aircraft
Aircraft Oxygen System Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Winglets Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Latin America Business Jet Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
North America Light and Very Light Jets Market
Aircraft
India Aviation Market
Aircraft
Aircraft Sequencing System Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market
Aircraft
Middle-East and Africa Helicopters Market