
 Global Commercial Aircraft Windows and Windshields Market | 2026-2036
Global Commercial Aircraft Windows and Windshields Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Aircraft Windows and Windshields Market Intelligence
Aerospace glazing technician shortages across North America and Western Europe are unwinding delivery schedules for cabin retrofit programs. PPG Industries sustains upstream control over optical interlayer chemistry for laminated windshields. Saint-Gobain Aerospace dominates advanced glass forming for wide-body cockpit applications. Gentex Corporation specializes in electrochromic dimmable window systems for premium cabin segments.
Commercial aircraft windows and windshields are pressure-bearing transparent structures engineered from stretched acrylic or chemically tempered glass laminates, typically rated for differential pressures exceeding 8.6 psi and bird-strike resistance up to four-pound impacts at approach speeds. These assemblies maintain cabin pressurization integrity while providing optical clarity for flight crews and passengers across operational altitudes. Windshield and cabin window segments command distinct margin pools, with cockpit laminates requiring FAA/EASA-certified fracture mechanics testing that elongates qualification cycles. Multi-layer composite technology is displacing legacy acrylic in next-generation narrow-body programs where weight targets have tightened. Entry door and emergency window categories remain tethered to OEM production rates rather than aftermarket pull.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements mandate specific impact resistance and optical distortion thresholds that shape material selection and testing expenditures for all suppliers seeking market access. The EU REACH framework restricts certain chemical plasticizers used in interlayer bonding, compelling reformulation of edge seal compounds across the supplier base. Stakeholders must monitor evolving bird-strike energy requirements under pending ICAO harmonization proposals, as these technical thresholds will determine which manufacturing platforms remain certifiable without capital-intensive retooling.
Market Dynamics
Fleet renewal cycles at low-cost carriers are compressing replacement windows into concentrated procurement waves, while FAA airworthiness directives on windshield delamination force accelerated compliance spending across operator maintenance programs.
Growth Catalysts
- Narrow-body fleet expansion:Low-cost carriers in India and Southeast Asia are scaling single-aisle operations, driving recurring demand for cabin window replacements at shortened intervals.
- FAA Part 25 amendments:Updated bird-strike energy thresholds are mandating thicker interlayer configurations, expanding addressable content per aircraft.
- Electrochromic retrofit programs:Premium cabin segments are adopting dimmable window systems as a service differentiator on long-haul routes.
Market Restraints
- Optical interlayer supply concentration:North American chemical suppliers control proprietary silane coupling formulations, constraining second-source qualification.
- EU REACH chemical restrictions:Phthalate plasticizer bans are forcing edge seal compound reformulations with 18-24 month revalidation timelines.
- Acrylic substitution pressure:Polycarbonate cabin window trials in regional turboprop programs threaten stretched acrylic's installed base.
Strategic Opportunities
- Saudi Arabia fleet modernization:Riyadh-based carriers are executing wide-body renewal programs with integrated windshield and cabin window package procurement.
- ICAO harmonization proposals:Pending unified bird-strike standards would streamline multi-jurisdiction certification for suppliers with existing FAA-EASA dual approvals.
- Blockchain-enabled provenance tracking:MRO channels are piloting distributed ledger systems for serialized windshield lifecycle documentation.
Industry Challenges
- Aerospace glazing technician scarcity:North American and Western European labor pools lack sufficient trained installers for bonded windshield replacement, extending AOG downtime.
- Fracture mechanics testing bottlenecks:FAA-certified laboratories face 14-month queues for cockpit laminate qualification, freezing new supplier entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Aircraft Windows and Windshields Market |
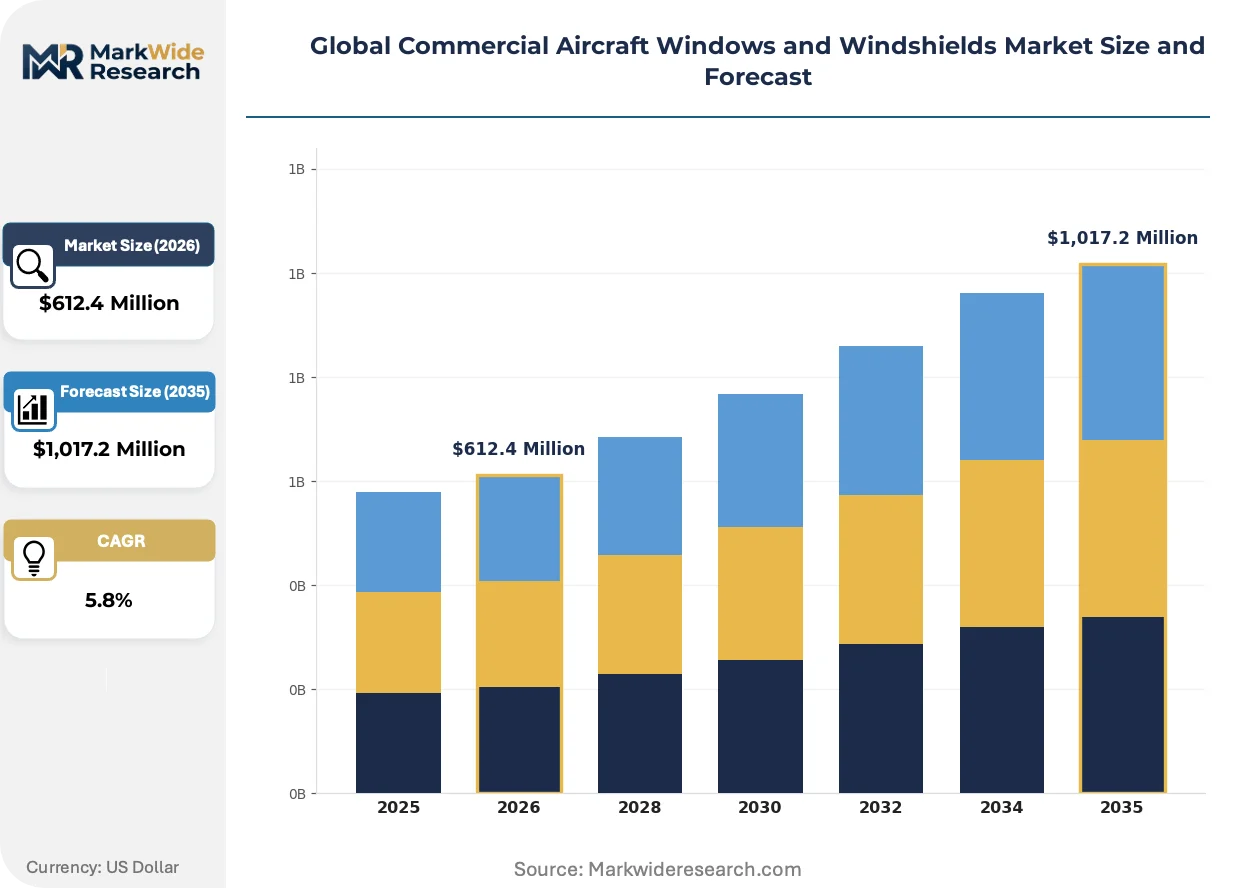
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Windows, Entry Doors, Windshields, Emergency Windows, Cabin Windows Technology: Laminated Glass, Acrylic, Polycarbonate, Tempered Glass, Multi-layer Composite Application: Narrow-body Aircraft, Wide-body Aircraft, Regional Jets, Cargo Aircraft, Business Jets End User: OEMs, Maintenance Repair Organizations, Airlines, Leasing Companies, Modification Centers |
| Companies Covered | NORDAM Group LLC, Lee Aerospace Inc., PPG Industries Inc., Kopp Glass, Triumph Group Inc., Gentex Corporation, Saint-Gobain Aerospace, AIP Aerospace, GKN Aerospace Services Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Aircraft Windows and Windshields Market Strategic Shifts & Innovations
Material science advances and regulatory harmonization efforts are restructuring supplier competitive advantages around certification velocity and chemical formulation control rather than manufacturing scale alone.
Multi-layer composite transparencies are decomposing the traditional acrylic-glass hierarchy in next-generation narrow-body programs. Boeing and Airbus engineering teams specify hybrid laminates with carbon-fiber reinforced interlayers for weight-critical applications. This architecture is decomposing established supply relationships as airframers qualify new chemistry platforms outside legacy vendor portfolios.
REACH chemical restrictions are compelling edge seal reformulations across European supplier operations. ECHA substance-of-very-high-concern listings target phthalate plasticizers used in polycarbonate bonding, forcing reformulation with bio-based alternatives. German and French MRO facilities are absorbing extended curing cycle times while awaiting revised process specifications from material suppliers.
Airline procurement teams are consolidating window and windshield contracts under single-source framework agreements. Full-service carriers in the United States and China are bundling cockpit and cabin transparency replacements to leverage volume pricing. This concentration is compressing margins for specialists lacking portfolio breadth while rewarding integrated suppliers with multi-segment capabilities.
Global Commercial Aircraft Windows and Windshields Market Segmentation
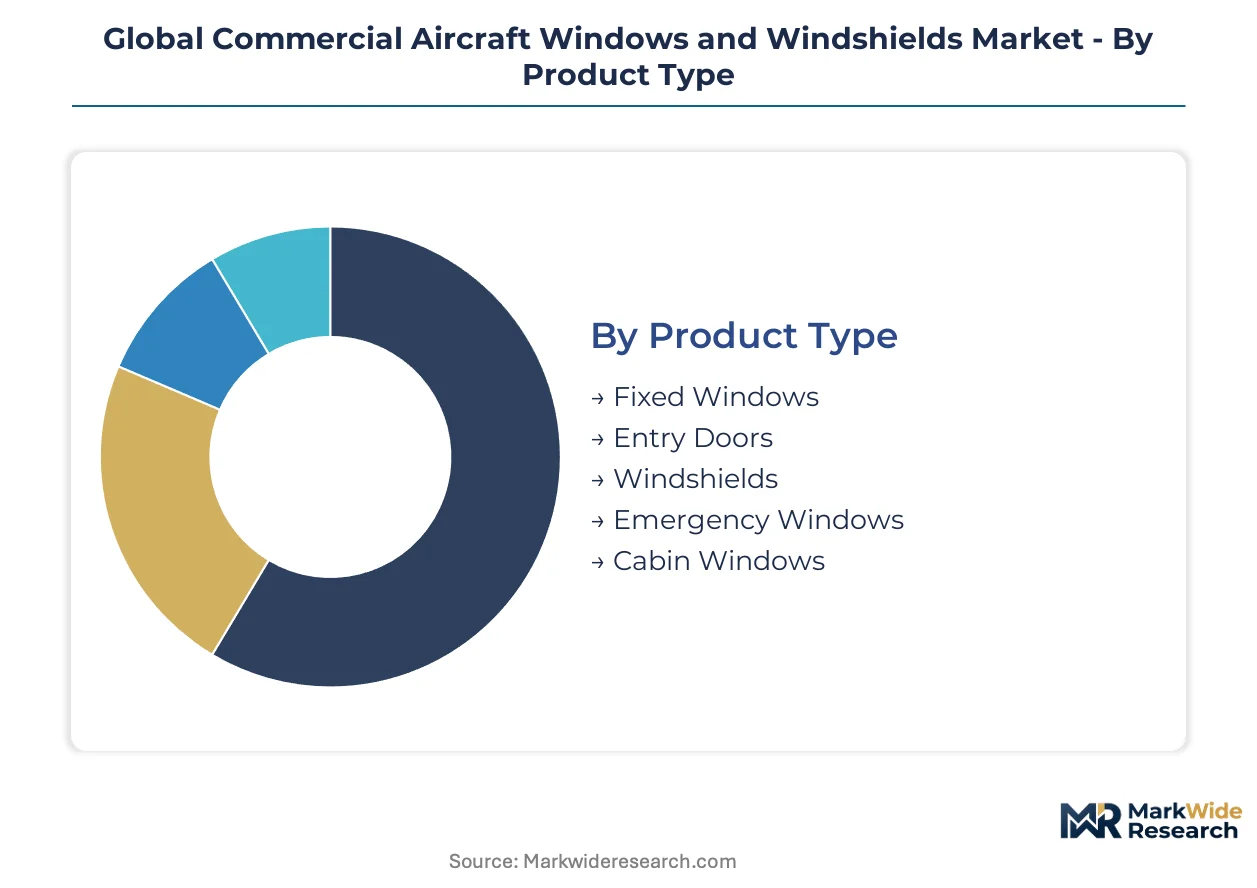
Segmentation in commercial aircraft glazing reveals distinct margin architectures and channel dependencies. Product type and application dimensions govern certification requirements, while technology selection determines supplier qualification barriers and aftermarket replacement cycles.
Product Type:
Cockpit windshields flow predominantly through OEM long-term agreements and airline direct procurement, while cabin windows and emergency exits distribute through fragmented MRO channels with shorter contract horizons.
- Windshields:Laminated glass-carbonate assemblies rated for bird-strike resistance above 350 knots. Demand concentrates at full-service carriers in the United States and Germany executing scheduled replacement under FAA airworthiness directive timelines. Compliance-driven procurement compresses price elasticity.
- Cabin Windows:Stretched acrylic or multi-layer composite panels in standardized sizes for single-aisle and twin-aisle fuselages. Low-cost carriers in India drive replacement volume through accelerated fleet utilization cycles. Aftermarket pull exceeds OEM attachment rates by substantial margins.
- Fixed Windows:Non-opening passenger viewing panels with simplified edge seal requirements.
- Entry Doors:Vision panels integrated into plug-type and outward-opening door structures.
- Emergency Windows:Fracture-critical escape hatches with explosive decompression ratings.
By volume, cabin windows lead. By growth pace, windshields are climbing the fastest.
Technology:
Material chemistry determines which supplier bases qualify for specific airframe programs, with proprietary interlayer formulations creating captive supply relationships.
- Multi-layer Composite:Hybrid laminates combining carbon-fiber reinforced interlayers with optical-grade substrates. Boeing and Airbus engineering specifications for next-generation narrow-body platforms favor this architecture. Weight reduction targets in the 8-12% range drive specification shifts away from legacy materials.
- Laminated Glass:Chemically tempered outer plies bonded with polyvinyl butyral or ionoplast interlayers. Cockpit applications in wide-body aircraft require FAA-certified fracture mechanics documentation. Saint-Gobain Aerospace and PPG Industries maintain formulation control over silane coupling chemistry.
- Acrylic:Stretched polymethyl methacrylate for cabin window applications with established thermoforming supply chains.
- Polycarbonate:Impact-resistant thermoplastic under trial in regional turboprop programs.
- Tempered Glass:Thermally strengthened monolithic glass for non-structural applications with lower certification burden.
By installed base, laminated glass dominates. By specification momentum, multi-layer composites are gaining share fastest.
Application:
Airframe category governs pressure differential ratings, with narrow-body and wide-body programs operating under distinct qualification protocols and aftermarket replacement economics.
- Narrow-body Aircraft:Single-aisle platforms including A320neo and 737 MAX families. Low-cost carriers in Southeast Asia operate these fleets at 14-16 daily flight cycles, accelerating window degradation. Replacement demand concentrates in aftermarket channels rather than OEM production.
- Wide-body Aircraft:Twin-aisle long-haul platforms with premium cabin configurations. Electrochromic dimmable window retrofits cluster in this segment. Full-service carriers in Saudi Arabia and China bundle windshield and cabin window replacements under integrated procurement frameworks.
- Regional Jets:Sub-100 seat turboprops and regional jets with simplified transparency requirements.
- Cargo Aircraft:Converted freighter and purpose-built cargo platforms with reduced passenger window counts.
- Business Jets:Custom cabin configurations with specialized optical and acoustic performance specifications.
By fleet count, narrow-body aircraft lead. By content value per shipset, wide-body aircraft are expanding most quickly.
End User:
Procurement authority splits between airframe manufacturers specifying new-build content and operators controlling aftermarket replacement timing.
- OEMs:Boeing, Airbus, and regional airframers specifying transparency systems at program launch. Long-term supply agreements lock in qualified suppliers for production runs extending 15-20 years. New program entry requires capital-intensive certification investment.
- Maintenance Repair Organizations:Independent and airline-captive MRO facilities executing windshield replacement under AOG pressure. Technician scarcity in North America and Western Europe extends turnaround times. Blockchain-enabled provenance tracking pilots are emerging in this channel.
- Airlines:Direct procurement of cabin window replacements for in-house maintenance programs.
- Leasing Companies:Return condition requirements driving pre-lease transparency refurbishment.
- Modification Centers:STC-approved retrofit programs for cabin reconfiguration and upgrade.
By transaction volume, MROs lead. By contract value concentration, OEMs are advancing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States operators consume cockpit windshields through compliance-driven replacement cycles, while Indian and Southeast Asian carriers burn through cabin windows at accelerated rates from high-utilization narrow-body fleets. This consumption-mix differential shapes regional supplier strategies and MRO capacity investments.
United States
FAA airworthiness directives on windshield delamination compress replacement timelines for legacy fleets at major carriers. The regulator mandates specific fracture mechanics documentation that elongates qualification cycles for new suppliers. Wichita, Kansas hosts concentrated MRO infrastructure where technician scarcity extends AOG downtime for bonded windshield replacements.
Germany
Full-service carriers execute integrated windshield and cabin window procurement under framework agreements with extended contract horizons. ECHA REACH restrictions on phthalate plasticizers force edge seal compound reformulations across supplier operations. Hamburg and Munich industrial clusters absorb extended curing cycle times while awaiting revised process specifications from material suppliers.
China
Low-cost carriers scale single-aisle operations at 14-16 daily flight cycles, accelerating cabin window degradation and aftermarket pull. The country's national aviation regulator enforces bird-strike resistance standards aligned with pending ICAO harmonization proposals. Tianjin and Shanghai manufacturing corridors concentrate MRO facilities executing transparency replacements for rapidly expanding narrow-body fleets.
India
Budget airlines operate A320neo and 737 MAX families at utilization rates exceeding global averages, driving recurring demand for passenger window replacements. Bureau of Civil Aviation Security mandates specific optical clarity thresholds for emergency exit transparency installations. Bangalore and Hyderabad maintenance hubs face glazing technician shortages that unwind delivery schedules for cabin retrofit programs.
Saudi Arabia
Riyadh-based carriers execute wide-body renewal programs with bundled windshield and cabin window package procurement. The General Authority of Civil Aviation aligns certification requirements with FAA-EASA dual approval frameworks to streamline supplier qualification. Jeddah and Dammam aviation clusters concentrate modification centers piloting blockchain-enabled provenance tracking for serialized windshield lifecycle documentation.
Global Commercial Aircraft Windows and Windshields Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with market structure dividing between chemistry-controlled incumbents and manufacturing-scale challengers. The upper tier commands proprietary interlayer formulations that lock in long-term supply relationships with airframe OEMs. Three archetypes populate the competitive terrain: integrated chemical-formulation leaders, multi-segment transparency suppliers, and electrochromic technology specialists. Dominant competitive moves include backward integration into optical interlayer production and geographic expansion through MRO channel partnerships.
Within the integrated chemical-formulation tier, PPG Industries and Saint-Gobain Aerospace exemplify archetypes that combine proprietary silane coupling chemistry with certified manufacturing platforms. Gentex Corporation occupies a position representing electrochromic technology specialization for premium cabin segments. Among North American fabricators, NORDAM Group LLC and Lee Aerospace Inc. sit within the MRO-focused specialist tier serving compliance-driven replacement demand.
| Leading Market Players |
|---|
| NORDAM Group LLC |
| Lee Aerospace Inc. |
| PPG Industries Inc. |
| Kopp Glass |
| Triumph Group Inc. |
| Gentex Corporation |
| Saint-Gobain Aerospace |
| AIP Aerospace |
| GKN Aerospace Services Ltd. |
| Others |
Cost & Logistics Intelligence
Minimum efficient scale in optical interlayer chemistry production concentrates supply among North American chemical suppliers, compressing price floors for qualified windshield laminates while elevating barriers for second-source entrants seeking FAA-EASA dual certification.
Pricing Analysis
Long-term offtake agreements dominate windshield procurement, with full-service carriers in the United States and Germany locking in multi-year framework contracts that bundle cockpit and cabin transparency replacements. Price differentiation rests on certification tier—FAA-certified fracture mechanics documentation commands substantial premiums over standard cabin window grades—and volume scale, where airline fleet consolidation amplifies buyer negotiating leverage. Cost compression in aftermarket channels is intensifying because glazing technician scarcity extends AOG downtime, forcing operators toward premium-priced expedited replacement services. Low-cost carriers in India exhibit highest price sensitivity due to accelerated utilization cycles, while Saudi Arabian wide-body operators demonstrate lowest sensitivity under integrated procurement mandates.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Tianjin ports constrain just-in-time delivery for Chinese narrow-body assembly lines, with container availability fluctuations rippling through MRO channel replenishment schedules. Manufacturing gravity centers on the United States, Germany, and China, with Saint-Gobain Aerospace and PPG Industries anchoring optical interlayer production in North American and European industrial clusters. Raw material dependencies stretch from silane coupling agents to ionoplast interlayers and stretched acrylic substrates. Single-source vulnerability in proprietary chemical formulations poses structural risk, as REACH-mandated edge seal reformulations extend supplier revalidation timelines. Distribution runs through OEM direct channels for new-build content and fragmented MRO networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through airline procurement consolidation, with full-service carriers bundling windshield and cabin window contracts under single-source frameworks that compress specialist margins.
For Market Incumbents: Shield proprietary interlayer formulations through accelerated REACH-compliant reformulation cycles, denying challengers window-of-opportunity entry during 18-24 month revalidation periods. Deepen upstream control over silane coupling chemistry to maintain captive supply relationships with Boeing and Airbus engineering teams specifying next-generation narrow-body platforms. For New Entrants and Emerging Players: MRO glazing technician scarcity in North America and Western Europe presents service-layer white space where incumbents under-serve expedited replacement demand. Target Indian low-cost carrier aftermarket channels through localized stocking partnerships, leveraging 14-16 daily flight cycle degradation rates to establish recurring revenue traction before OEM qualification investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrochromic technology specialists serving premium wide-body cabin segments, where retrofit program longevity exceeds single-aisle replacement cycles. Long-term viability favors suppliers with FAA-EASA dual approval frameworks and multi-segment transparency portfolios. Watch ICAO bird-strike harmonization proposals as inflection indicator—unified standards would streamline certification velocity for pre-qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Interlayer Production | PPG Industries sustains formulation control over silane coupling chemistry for laminated windshields. |
| Multi-Jurisdiction Certification Investment | Dual FAA-EASA approval frameworks streamline supplier qualification for Saudi Arabian wide-body programs. |
| Blockchain-Enabled Provenance Tracking | MRO channels in Jeddah and Dammam pilot distributed ledger systems for serialized windshield lifecycle documentation. |
| Electrochromic Retrofit Program Expansion | Gentex Corporation targets premium cabin segments on long-haul routes as service differentiator. |
| Geographic MRO Channel Partnership | NORDAM Group LLC and Lee Aerospace Inc. position near Wichita maintenance clusters to address technician scarcity. |
Research Approach
Cross-validation between primary interviews with aerospace glazing technicians, MRO procurement managers, airline fleet engineering directors, and FAA certification specialists anchors the qualitative findings against secondary validation from FAA airworthiness directive filings, EASA CS-25 certification records, ECHA REACH substance-of-very-high-concern listings, and customs trade data for optical interlayer imports. Bottom-up triangulation across narrow-body and wide-body fleet counts converges with top-down market sizing from OEM production schedules and aftermarket replacement cycle analysis.
Sensitivity analysis across the projection horizon tests forecast robustness against bird-strike standard harmonization timing, REACH chemical restriction expansion scenarios, and polycarbonate substitution penetration in regional turboprop programs. Segmentation dimensions modeled include product type, material technology, airframe application, and end-user procurement authority. CAGRs derive from fleet renewal cycle phasing, regulatory compliance deadline clustering, and electrochromic retrofit adoption curves calibrated against premium cabin configuration rates.
Material uncertainties—pending ICAO harmonization proposals, ECHA phthalate plasticizer ban enforcement timelines, and aerospace glazing technician training pipeline recovery—sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability and certification queue durations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Europe Aviation Market
Aircraft
UK Military Aviation Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Flight Management Systems Market
Aircraft
Aircraft Seals Market
Aircraft
Europe General Aviation Market
Aircraft
Aircraft Cargo Winches Market
Aircraft
Global Aircraft Tugs Market
Aircraft
Aircraft Landing Gear Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
Europe Business Jet Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
Light Electric Aircraft Market
Aircraft
Europe Helicopters Market