
 Amphibious Aircraft Market | 2026-2036
Amphibious Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Amphibious Aircraft Market Intelligence
Aftermarket service revenue is narrowing toward avionics upgrades and hull refurbishment as original equipment margins compress. ICON Aircraft sustains brand recognition in the light-sport segment through simplified pilot training ecosystems. ShinMaywa Industries anchors Japanese defense and civilian amphibious demand with its US-2 platform. Viking Air Limited dominates the legacy de Havilland turboprop aftermarket, extending airframe life through certified modification programs.
An amphibious aircraft integrates a boat-hull fuselage or pontoon undercarriage with conventional wing and powerplant configurations, enabling water takeoff and landing operations from both marine and terrestrial surfaces. Composite hull construction using carbon-fiber reinforced polymers reduces corrosion susceptibility while maintaining structural buoyancy ratios critical for saltwater operations. Firefighting configurations lead product type demand due to seasonal wildfire suppression contracts in coastal jurisdictions. Electric propulsion technology represents the fastest-expanding segment, though energy density limitations currently restrict operational range below that of turboprop alternatives. Maritime patrol applications within the application taxonomy concentrate procurement budgets, as sovereign coastlines require persistent surveillance coverage.
FAA Part 23 certification standards govern light amphibious aircraft airworthiness in the United States, while EASA CS-23 equivalents shape European market access requirements for manufacturers seeking cross-border sales. The EPA's evolving emissions frameworks for aviation fuels indirectly pressure turboprop operators toward hybrid-electric retrofits or new-build alternatives. Stakeholders must monitor certification reciprocity negotiations between national regulators, as fragmented approval pathways could strand development investments in emerging propulsion architectures.
Market Dynamics
Electric propulsion architectures are compressing development timelines for light-sport amphibious designs while fragmenting certification pathways between traditional FAA Part 23 and emerging MOSAIC frameworks.
Growth Catalysts
- FAA MOSAIC Rule Expansion:The Modernization of Special Airworthiness Certification introduces performance-based standards for light-sport amphibious aircraft, reducing compliance burden for manufacturers targeting recreational pilots.
- Coastal Wildfire Suppression Mandates:State-level firefighting procurement in California, Australia, and Portugal drives seasonal demand for scooping-capable amphibious platforms with rapid turnaround specifications.
- Composite Hull Fabrication:Carbon-fiber reinforced polymer molding processes reduce saltwater corrosion rates while maintaining structural buoyancy ratios critical for maritime patrol endurance.
Market Restraints
- Aviation Fuel Price Volatility:Jet-A and Avgas cost fluctuations compress operating margins for turboprop-powered amphibious fleets dependent on conventional hydrocarbon supply chains.
- Single-Source Avionics Concentration:Garmin and Collins Aerospace dominate integrated flight deck supply for light amphibious platforms, creating procurement bottlenecks during certification cycles.
- Battery Energy Density Ceiling:Lithium-ion cell gravimetric energy storage limits electric amphibious aircraft to sub-300-nautical-mile missions, excluding trans-coastal routes.
Strategic Opportunities
- Indonesian Archipelago Connectivity:The nation's 17,000 islands lack runway infrastructure across outer provinces, creating addressable demand for short-haul amphibious shuttle services.
- EU Green Deal Aviation Alignment:The European Commission's Sustainable Aviation Fuels mandate creates regulatory tailwind for hybrid-electric amphibious platforms operating in Mediterranean coastal zones.
- Direct-to-Consumer Sales Channels:Manufacturers bypass traditional dealer networks through fractional ownership platforms, reducing customer acquisition costs in recreational aviation segments.
Industry Challenges
- Multi-Surface Pilot Certification Complexity:Seaplane rating requirements vary across FAA, EASA, and Transport Canada jurisdictions, fragmenting addressable pilot pools and training standardization.
- Hull-to-Airframe Integration Timelines:Composite bonding processes for amphibious fuselages extend type certification cycles by 18-24 months compared to land-only equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amphibious Aircraft Market |
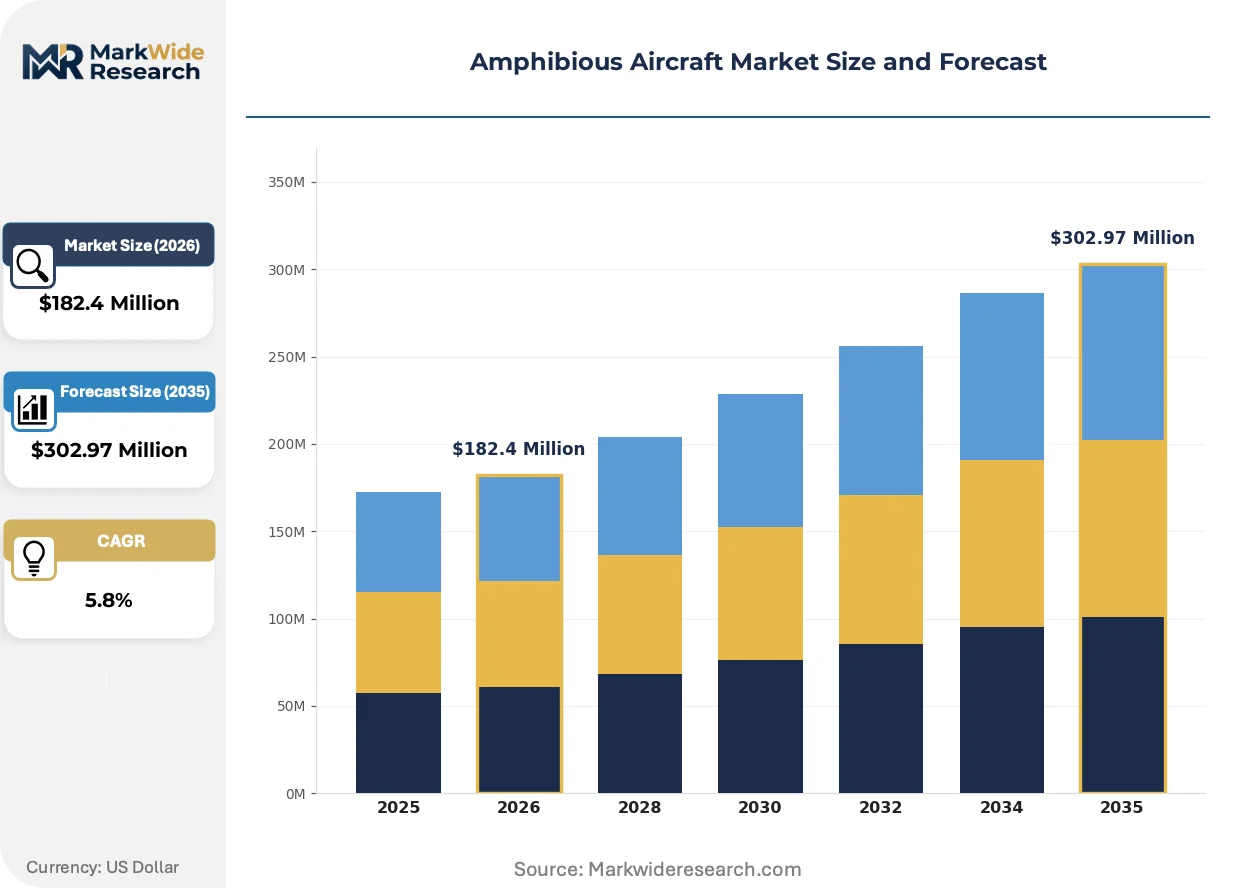
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $302.97 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Twin-Engine, Seaplane, Floatplane, Touring, Firefighting Technology: Propeller, Turboprop, Jet, Electric, Hybrid Application: Search & Rescue, Maritime Patrol, Passenger Transport, Cargo Delivery, Environmental Monitoring End User: Coast Guard, Forestry Departments, Private Operators, Charter Services, Research Institutions |
| Companies Covered | ICON Aircraft, Inc., Seamax Aircraft Ltd., ShinMaywa Industries, Ltd., Evektor-Aerotechnik, a.s., Lake Aircraft, Inc., Viking Air Limited, Progressive Aerodyne, Inc., Aviation Industry Corporation of China, Textron Aviation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amphibious Aircraft Market Strategic Shifts & Innovations
Propulsion electrification and digital flight control integration are compressing the capability gap between light-sport and certified general aviation amphibious platforms.
Hybrid-electric powertrain architectures are hybridizing conventional turboprop reliability with battery-electric efficiency gains. Maritime patrol operators in Norway and New Zealand evaluate these systems for reduced acoustic signatures during coastal surveillance. The technology is hybridizing mission profiles previously split between dedicated land-based and pure-floatplane fleets.
EASA's CS-23 Amendment 5 introduces performance-based certification criteria for electric and hybrid propulsion systems in light aircraft categories. The framework permits alternative means of compliance for energy storage systems, reducing testing burden for European amphibious manufacturers. Light-sport segment applicants in Germany and France leverage this pathway to accelerate market entry.
Coast guard agencies unbundle airframe procurement from integrated sensor packages, selecting bare-aircraft platforms with modular mission system interfaces. This specification shift displaces turnkey system integrators in favor of specialized sensor vendors. The pattern concentrates in Nordic countries where sovereign patrol requirements prioritize rapid technology refresh cycles over platform longevity.
Amphibious Aircraft Market Segmentation
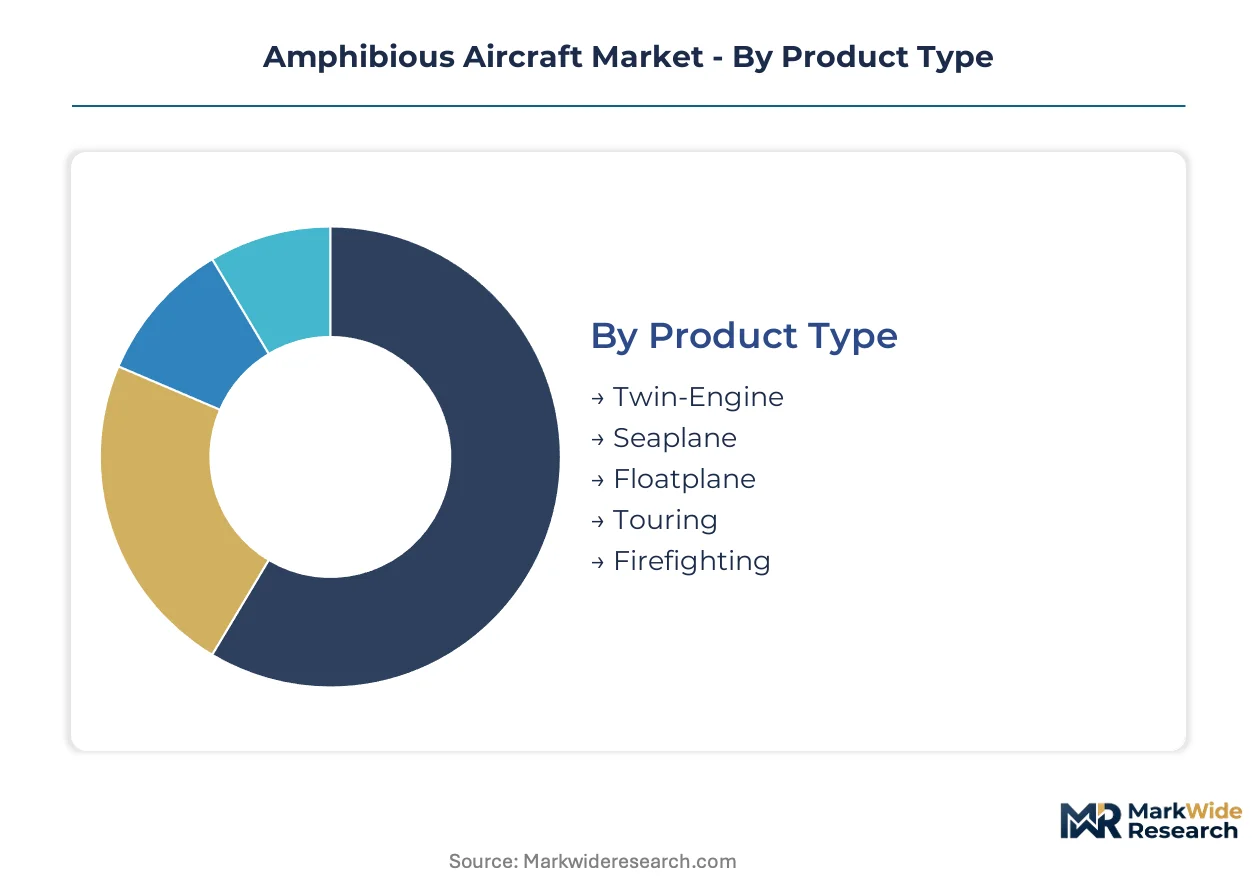
Segmentation reveals divergent aftermarket service intensities across amphibious aircraft categories. Hull corrosion monitoring and powerplant overhaul cycles vary substantially between firefighting platforms and recreational touring models, reshaping manufacturer revenue mix and distributor stocking strategies.
Product Type:
After-sales service intensity peaks with twin-engine and firefighting platforms, where saltwater exposure and seasonal utilization patterns compress maintenance intervals.
- Firefighting:Scooping-capable hulls endure cyclic stress from water impact and retardant chemical exposure. Procurement concentrates in California, Australia, and Portugal where state-level wildfire suppression contracts mandate rapid turnaround specifications.
- Twin-Engine:Redundant powerplant configurations support extended over-water missions for coast guard operators. Maritime patrol fleets in Japan and Norway favor these platforms for search and rescue endurance requirements.
- Seaplane:Integrated boat-hull fuselage designs dominate recreational aviation infrastructure in the United States.
- Floatplane:Removable pontoon undercarriages enable seasonal water-land conversion for private operators.
- Touring:Light-sport certified variants target fractional ownership platforms with simplified pilot training ecosystems.
By volume, floatplane conversions lead. By growth pace, firefighting is ahead.
Technology:
Technology selection determines fuel supply chain exposure and certification pathway complexity for manufacturers entering the sector.
- Electric:Battery-electric architectures face energy density constraints limiting missions to sub-300-nautical-mile ranges. Development timelines compress for light-sport designs under FAA MOSAIC frameworks.
- Hybrid:Turboprop-battery combinations reduce acoustic signatures for coastal surveillance operators in Norway and New Zealand. Maritime patrol agencies evaluate these systems for mission profiles previously split between land-based and pure-floatplane fleets.
- Turboprop:Conventional powerplants retain dominance in heavy-lift firefighting configurations.
- Propeller:Piston-engine designs persist in recreational and training segments.
- Jet:High-speed platforms serve limited military and executive transport niches.
Turboprop captures current volume leadership. Electric platforms are climbing the fastest.
Application:
Application focus shapes sensor integration requirements and airframe modification cycles for mission-specific deployments.
- Maritime Patrol:Persistent surveillance coverage demands drive sovereign coastline procurement budgets. Coast guard agencies in Nordic countries increasingly specify bare-aircraft platforms with modular mission system interfaces.
- Search & Rescue:Rapid response specifications prioritize twin-engine reliability and all-weather avionics. Fleet expansion concentrates in coast guard organizations with expanding amphibious procurement mandates.
- Passenger Transport:Short-haul shuttle services address Indonesia's 17,000-island connectivity gap.
- Cargo Delivery:Remote supply operations serve archipelago and lake district economies.
- Environmental Monitoring:Research institutions deploy sensor-equipped platforms for coastal ecosystem assessment.
Maritime patrol leads by procurement value. Search and rescue is gaining share fastest.
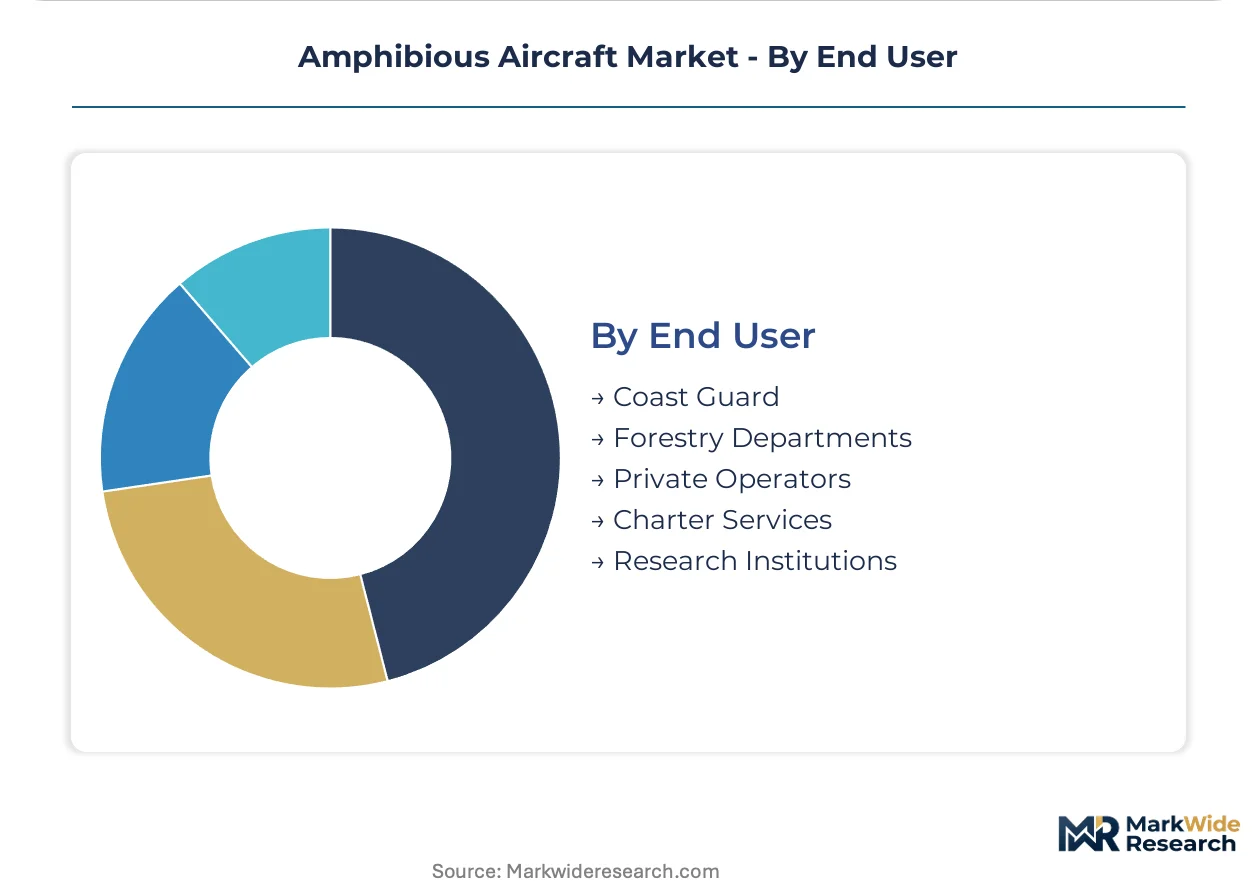
End User:
End user category determines procurement channel structure and financing mechanism preferences across public and private segments.
- Coast Guard:Sovereign fleet procurement follows defense acquisition regulations with extended type certification requirements. Budget concentration in the United States, Japan, and Norway sustains manufacturer order backlogs.
- Forestry Departments:Seasonal contracting patterns in California and Mediterranean jurisdictions create demand spikes for scooping-capable platforms.
- Private Operators:Direct-to-consumer sales channels bypass traditional dealer networks through fractional ownership platforms.
- Charter Services:Tourism-dependent operators concentrate in coastal recreational aviation infrastructure.
- Research Institutions:Grant-funded acquisitions prioritize modular sensor integration capabilities.
Coast guard commands volume leadership. Forestry departments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational buyers in the United States show the lowest price elasticity, absorbing premium light-sport pricing for simplified training ecosystems. Coast guard procurement in Japan and Norway operates on rigid budget cycles with long lead times, dampening demand responsiveness. Emerging shuttle operators in Indonesia face acute capital constraints, driving intense price competition among entry-level platforms.
United States
Coastal patrol requirements from the Department of Homeland Security and recreational aviation infrastructure sustain twin demand streams. FAA Part 23 and emerging MOSAIC certification pathways streamline manufacturer market entry. Seaplane bases in Florida, Alaska, and the Pacific Northwest concentrate operational activity, with ICON Aircraft anchoring light-sport distribution through direct-to-consumer channels.
Japan
Maritime Self-Defense Force search and rescue mandates drive sovereign fleet procurement with extended type certification requirements. METI industrial policy supports domestic aerospace supply chain retention. ShinMaywa Industries anchors civilian and defense amphibious demand from its Komaki facility, with US-2 platforms serving coast guard endurance missions.
Norway
Coastal surveillance requirements for extended maritime boundaries prioritize reduced acoustic signature platforms. EASA CS-23 Amendment 5 performance-based criteria accelerate electric and hybrid propulsion evaluations. Bergen and Tromsø host maritime patrol operator clusters evaluating hybrid-electric architectures for fjord and offshore zone coverage.
Indonesia
Archipelago connectivity gaps across 17,000 islands create addressable demand for short-haul amphibious shuttle services. National infrastructure investment programs prioritize remote province accessibility. Jakarta and Surabaya operator clusters are emerging, with state-owned carriers evaluating bare-aircraft procurement for outer island routes.
Australia
Seasonal wildfire suppression contracts in New South Wales and Victoria drive scooping-capable platform procurement. State-level forestry department budgets concentrate in Queensland and Western Australia. Sydney and Melbourne operator bases support rapid deployment specifications, with federal-state cost-sharing arrangements structuring acquisition timelines.
Amphibious Aircraft Market Key Industry Players
Capability concentration sits with specialized hull-fabrication specialists; scale advantage sits with diversified aerospace conglomerates. The market structures around three tiers: legacy de Havilland platform custodians, light-sport simplification specialists, and state-backed defense contractors. Strategic moves center on composite bonding process certification acceleration and modular mission system interface standardization.
Among North American specialists, ICON Aircraft exemplifies light-sport ecosystem integration, while Viking Air Limited represents legacy platform aftermarket extension. ShinMaywa Industries occupies the sovereign defense contractor archetype, anchoring Japanese coast guard procurement. These three entities illustrate divergent competitive vectors: recreational simplification, legacy airframe life extension, and defense-integrated platform development.
| Leading Market Players |
|---|
| ICON Aircraft, Inc. |
| Seamax Aircraft Ltd. |
| ShinMaywa Industries, Ltd. |
| Evektor-Aerotechnik, a.s. |
| Lake Aircraft, Inc. |
| Viking Air Limited |
| Progressive Aerodyne, Inc. |
| Aviation Industry Corporation of China |
| Textron Aviation Inc. |
| Others |
Cost & Logistics Intelligence
Trans-Pacific composite fiber shipments from Japan to U.S. West Coast fabrication facilities carry freight premiums that cascade into hull production costs, compressing margins for light-sport manufacturers while enabling premium pricing for coast guard-specified platforms with extended corrosion warranties.
Pricing Analysis
After-sales service contracts covering avionics upgrades and hull refurbishment generate lifetime value multiples exceeding original equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates FAA Part 23 certified platforms from MOSAIC light-sport variants and floatplane conversion kits. Pricing pressure stems from lithium-ion battery cost volatility affecting electric propulsion variants. Private recreational operators exhibit highest price sensitivity, while coast guard procurement operates with rigid budget inelasticity.
Supply Chain Analysis
Export controls on carbon-fiber prepreg technologies under U.S. International Traffic in Arms Regulations restrict Japanese and European suppliers from transferring advanced composite formulations to certain jurisdictions. Manufacturing concentrates in the United States, Japan, and Canada. Supply chains draw from aerospace-grade aluminum suppliers, Garmin and Collins integrated flight decks, and specialized marine-grade sealant producers. Single-source avionics concentration creates procurement bottlenecks during certification cycles. Distribution runs through fractional ownership platforms and defense acquisition channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Amphibious aircraft penetration sits at early-cycle expansion, with FAA MOSAIC rule adoption accelerating manufacturer entry into recreational segments previously blocked by certification burden.
For Market Incumbents: Build certification moats around composite hull bonding process patents to block fast-follower entrants. Accelerate EASA CS-23 Amendment 5 compliance investments before European competitors consolidate hybrid-electric market access. Vertical integration into avionics supply reduces Garmin-Collins dependency risks. For New Entrants and Emerging Players: Pursue Indonesian archipelago shuttle services as the most penetrable white-space target, where runway infrastructure gaps exceed 8,000 outer islands. Target bare-aircraft procurement specifications from coast guard agencies unbundling sensor integration. Deploy direct-to-consumer fractional ownership platforms to bypass dealer network establishment costs. For Investors and Strategic Acquirers: Specialized hull-fabrication specialists with certified marine-grade composite processes represent the priority acquisition archetype for platform diversification. Long-term viability hinges on electric propulsion energy density breakthroughs enabling trans-coastal missions. Watch FAA-EASA certification reciprocity negotiations as the inflection signal for stranded development risk.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Hull Certification Acceleration | Reduces type certification timelines by 18-24 months for amphibious fuselage bonding processes. |
| Modular Mission System Interface Standardization | Enables coast guard agencies to unbundle sensor procurement from bare-airframe platforms. |
| Hybrid-Electric Propulsion Development | Addresses Norway and New Zealand maritime patrol requirements for reduced acoustic signatures. |
| Direct-to-Consumer Channel Expansion | ICON Aircraft's fractional ownership model reduces customer acquisition costs in recreational segments. |
| Defense Acquisition Regulatory Compliance | ShinMaywa Industries leverages METI policy support for Japanese coast guard US-2 procurement. |
Research Approach
A spread of perspectives from coast guard fleet procurement officers, composite hull fabrication engineers, FAA certification specialists, and fractional ownership platform operators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FAA type certificate databases, EASA CS-23 amendment filings, and defense acquisition contract disclosures. Bottom-up segment sizing triangulated against top-down macro aerospace production indicators.
Demand-supply balance modeling across the analysis window integrated product type segmentation by firefighting, twin-engine, seaplane, floatplane, and touring categories with technology splits across electric, hybrid, turboprop, propeller, and jet architectures. Application dimensions covered maritime patrol, search and rescue, passenger transport, cargo delivery, and environmental monitoring. CAGRs derived from regression analysis against coastal wildfire suppression contract volumes and archipelago connectivity investment programs.
Macroeconomic conditions sit as an overlay; deviation in aviation fuel price volatility and battery cell commodity costs would shift the trajectory. Forecasts reflect assumptions around FAA MOSAIC implementation timelines and EASA CS-23 reciprocity negotiations. Material shifts in export control regimes or energy storage technology breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Supersonic Jet Market
Aircraft
Europe Helicopters Market
Aircraft
Europe General Aviation Market
Aircraft
South Korea Aerospace and Defense Market
Aircraft
Firefighting Aircraft Market
Aircraft
Manned Evtol Crafts Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Aircraft Cargo Container Market
Aircraft
Middle-East and Africa Helicopters Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
Global LW Sport Aircraft Market
Aircraft
Asia-Pacific Turboprop Aircraft Market
Aircraft
India Winglets Market
Aircraft
Flight Management Systems Market
Aircraft
Airplane and Helicopter Hangar Doors Market