
 North America Light and Very Light Jets Market | 2026-2036
North America Light and Very Light Jets Market Size, Share, and Industry Trends Forecast 2026-2036
North America Light and Very Light Jets Market Analytics
Canadian component suppliers and U.S. airframe integrators are restructuring production footprints to address post-pandemic order backlogs and supply chain recalibration. Embraer SA leverages its Phenom family manufacturing scale to dominate the light jet export segment from its Melbourne, Florida assembly line. Honda Aircraft Company anchors the very light jet tier through the HA-420 program, sustaining a niche focused on owner-flown operations with advanced over-the-wing engine mount technology. Cirrus Design Corporation differentiates through its SF50 Vision Jet, the sole single-engine certified jet in the segment, occupying a unique price-performance position.
Light and very light jets denote aircraft with maximum takeoff weights below approximately 10,000 pounds, typically seating four to eight passengers and powered by turbofan engines with thrust ratings under 5,000 pounds. These airframes employ composite fuselage structures, integrated glass cockpit avionics, and pressurized cabins to deliver point-to-point business aviation service at cruise altitudes exceeding 40,000 feet. The product type dimension shows light jets commanding the largest revenue pool due to charter operator fleet standardization, while very light jets attract the fastest growth from individual owners and small flight departments seeking lower operating costs. Within end user categories, fractional ownership programs generate the most predictable delivery pipelines, whereas private owners represent the highest-margin transactions per unit.
FAA Part 23 reforms and Transport Canada Civil Aviation certification reciprocity agreements shape airworthiness standards and cross-border market access for new entrants. EPA emissions guidelines and emerging noise abatement protocols at metropolitan airports influence engine selection and operational restrictions for fleet operators. Stakeholders must monitor evolving sustainability mandates and alternative propulsion timelines to calibrate product development cycles against regulatory trajectory and customer environmental expectations.
Market Dynamics
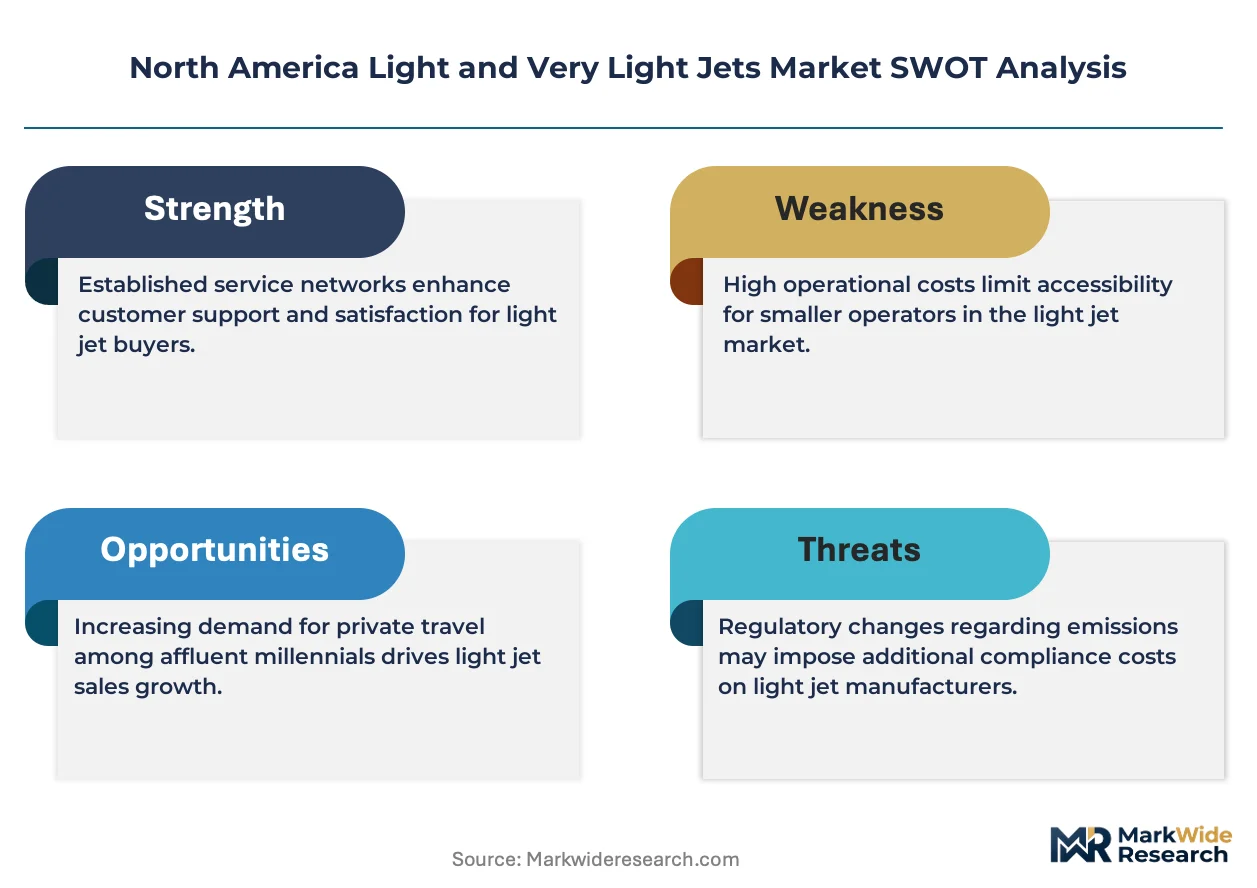
FAA Part 23 certification reforms are compressing airframe approval timelines while fractional ownership programs restructure fleet procurement toward capital-efficient access models.
Growth Catalysts
- FAA Part 23 Reforms:Streamlined approval pathways for new airframe designs reduce certification timelines, enabling faster market entry for innovative aircraft configurations.
- Fractional Ownership Expansion:Corporate flight departments across the United States and Canada are adopting shared-ownership structures to access light jet capability without full capital commitment.
- Sun Belt Infrastructure Clustering:Charter density and private aviation infrastructure concentrate around Florida, Texas, and Arizona, creating operational economies that pull additional fleet investment.
Market Restraints
- Engine Supply Concentration:Turbofan propulsion systems for sub-5,000-pound thrust ratings depend on a limited supplier base, creating vulnerability to production bottlenecks.
- Certification Reciprocity Friction:Transport Canada Civil Aviation and FAA cross-border approval processes still generate timeline delays despite formal agreement frameworks.
- Metropolitan Noise Protocols:Emerging noise abatement requirements at high-density airports restrict operational windows for certain engine configurations.
Strategic Opportunities
- Single-Engine Jet Expansion:Owner-flown operations represent underpenetrated demand, with individual buyers seeking lower direct operating costs than twin-engine alternatives.
- Composite Airframe Advancement:Carbon fiber fuselage technology convergence with automated manufacturing processes enables production scale previously unattainable in this weight class.
- EPA Emissions Alignment:Anticipatory engine selection to meet tightening federal guidelines positions early adopters for operational continuity as restrictions phase in.
Industry Challenges
- Avionics Integration Complexity:Glass cockpit system certification with integrated autopilot and terrain awareness functions demands specialized software engineering talent pools that remain tight.
- Supply Chain Reconfiguration:Post-pandemic component sourcing requires Canadian suppliers and U.S. integrators to rebuild production footprints while managing order backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Light and Very Light Jets Market |
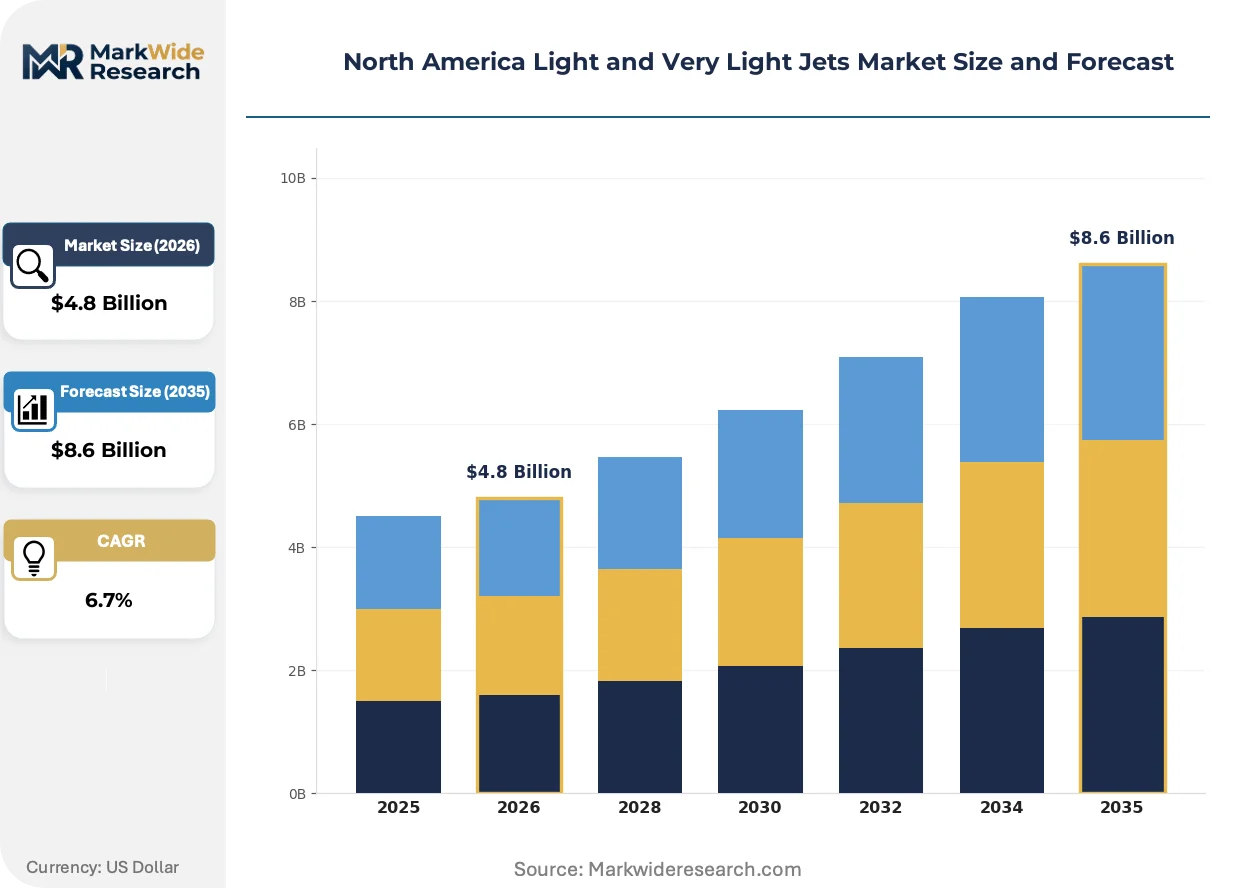
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Jets, Very Light Jets, Mid-Size Jets, Super Mid-Size Jets End User: Private Owners, Corporations, Charter Operators, Fractional Ownership Technology: Avionics Systems, Propulsion Systems, Cabin Management, Safety Systems Application: Business Travel, Air Ambulance, Cargo Transport, Recreational Use |
| Companies Covered | Embraer SA, Honda Aircraft Company, Cirrus Design Corporation, Textron Inc., Pilatus Aircraft Ltd, Bombardier Inc., Stratos Aircraft, SyberJet Aircraft, One Aviation Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Light and Very Light Jets Market Evolving Landscape
Propulsion efficiency improvements and avionics integration are reshaping aircraft performance benchmarks while ownership models fragment traditional fleet structures.
Over-the-wing engine mount architecture is expanding into owner-flown operations as Honda Aircraft Company's HA-420 configuration demonstrates reduced cabin noise and improved aerodynamic efficiency. Individual buyers and small flight departments are adopting this layout at accelerating rates as operational data validates maintenance accessibility advantages. The technology is expanding into adjacent weight classes as competitors evaluate similar configurations for next-generation programs.
FAA Part 23 reforms and Transport Canada Civil Aviation reciprocity agreements are compressing cross-border certification timelines for new airframe entrants. The regulatory convergence reduces duplicate testing requirements, lowering development costs for manufacturers targeting both markets. Light jet programs with composite structures and integrated avionics suites are responding fastest, leveraging streamlined pathways to accelerate delivery schedules.
Charter operators are consolidating fleet standardization around specific airframe families to compress maintenance training and parts inventory overhead. This procurement concentration displaces fragmented multi-type operations as scale economies become decisive in margin-defended segments. The pattern is most visible in the U.S. Sun Belt corridor, where high-density charter markets reward operational homogeneity with reduced turnaround times and simplified crew qualification.
North America Light and Very Light Jets Market Segmentation
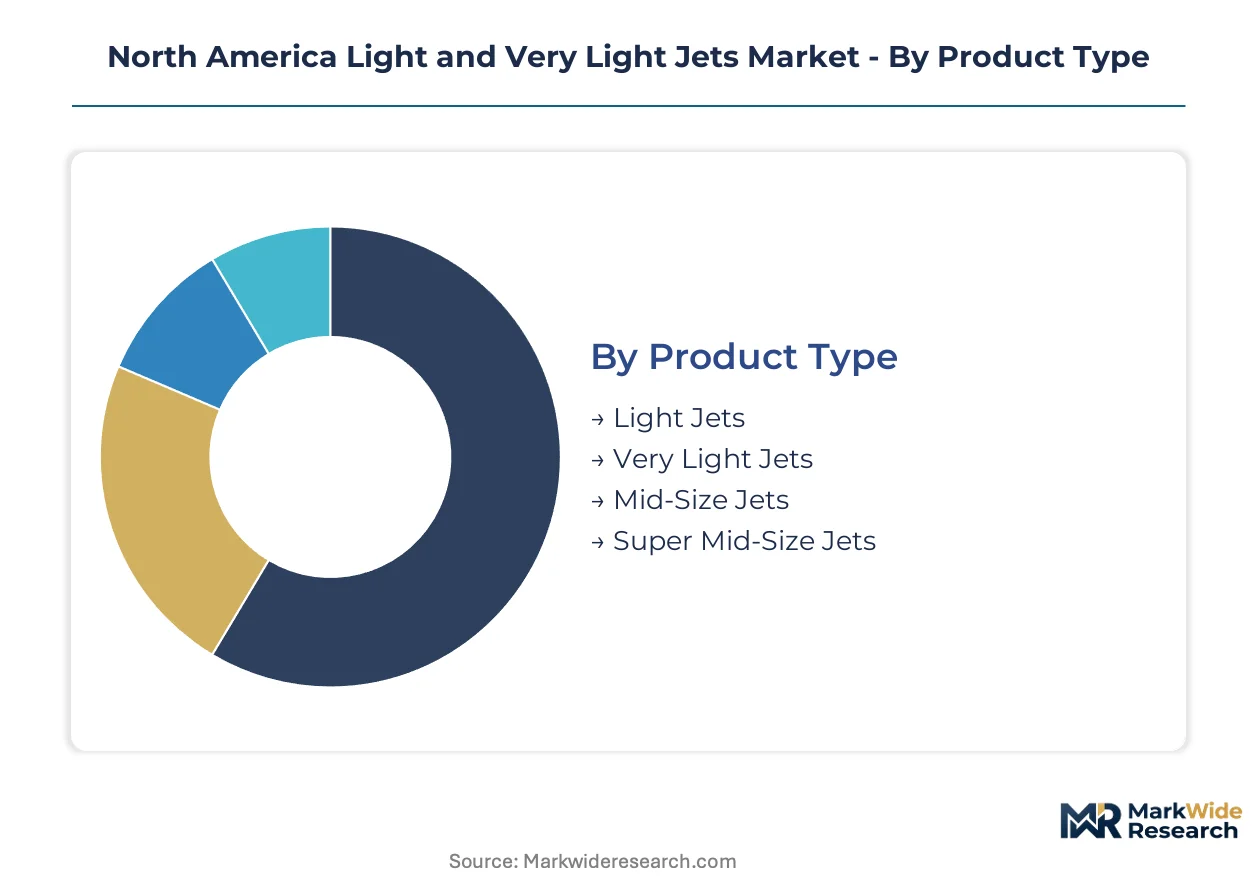
Segmentation in the North America light and very light jets market reveals how procurement priorities diverge across operator types and mission profiles. Understanding these splits enables manufacturers to calibrate product positioning against distinct performance requirements and ownership economics.
Product Type:
Light jets anchor revenue volume through fleet standardization by charter operators, while very light jets command premium margins from individual buyers seeking lower operating costs.
- Light Jets:Twin-engine configurations with maximum takeoff weights approaching 10,000 pounds and seating for six to eight passengers. Demand concentrates among U.S. charter operators in the Sun Belt corridor, where fleet homogeneity compresses maintenance overhead and crew training costs. FAA Part 23 certification reforms have accelerated new model introductions in this tier.
- Very Light Jets:Single-engine or compact twin-engine designs seating four to five passengers, optimized for owner-flown operations with direct operating costs below twin-engine alternatives. Growth is climbing fastest in Texas and Florida, where individual buyers prioritize acquisition price and fuel efficiency over maximum range.
- Mid-Size Jets:Heavier airframes with transcontinental range capability, serving corporate flight departments requiring cabin stand-up height and enclosed lavatory configurations.
- Super Mid-Size Jets:Premium segment bridging light jet agility with large cabin comfort, attracting fractional ownership programs seeking competitive differentiation through interior amenities.
Mature deployment sits with Light Jets. Newer deployment is concentrated in Very Light Jets.
End User:
Procurement patterns separate capital-efficient access models from outright ownership, with margin structures inverting across these divides.
- Private Owners:Individual buyers purchasing aircraft for personal transportation and recreational missions. Transactions generate the highest per-unit margins for manufacturers, particularly in Arizona and Colorado markets where owner-flown operations dominate.
- Corporations:Flight departments managing dedicated aircraft for executive transport. Procurement emphasizes dispatch reliability and brand alignment, with fleet decisions centralized in headquarters states including California and New York.
- Charter Operators:Commercial providers selling flight hours to non-owners. Standardization around specific airframe families is displacing fragmented multi-type operations as scale economies become decisive.
- Fractional Ownership:Shared-ownership structures providing capital-efficient access without full asset commitment. Programs are expanding across the United States and Canada as corporate flight departments seek balance sheet flexibility.
Volume concentration rests with Charter Operators. Margin expansion is strongest with Private Owners.
Technology:
System integration complexity creates competitive moats for suppliers with specialized software engineering capabilities.
- Avionics Systems:Integrated glass cockpit configurations combining primary flight displays, flight management systems, and synthetic vision. Certification demands for autopilot and terrain awareness functions strain specialized engineering talent pools that remain tight across the United States.
- Propulsion Systems:Turbofan engines with thrust ratings under 5,000 pounds, where supply concentration among limited manufacturers creates vulnerability to production bottlenecks.
- Cabin Management:In-flight connectivity, entertainment, and environmental control systems. Differentiation is intensifying as fractional programs compete on passenger experience metrics.
- Safety Systems:Terrain awareness warning systems, traffic collision avoidance, and emergency descent automation. FAA mandates are driving retrofit demand in existing fleets.
Deployment maturity centers on Propulsion Systems. Capability investment is accelerating fastest in Avionics Systems.
Application:
Mission requirements dictate airframe selection, with range-payload tradeoffs varying sharply across use cases.
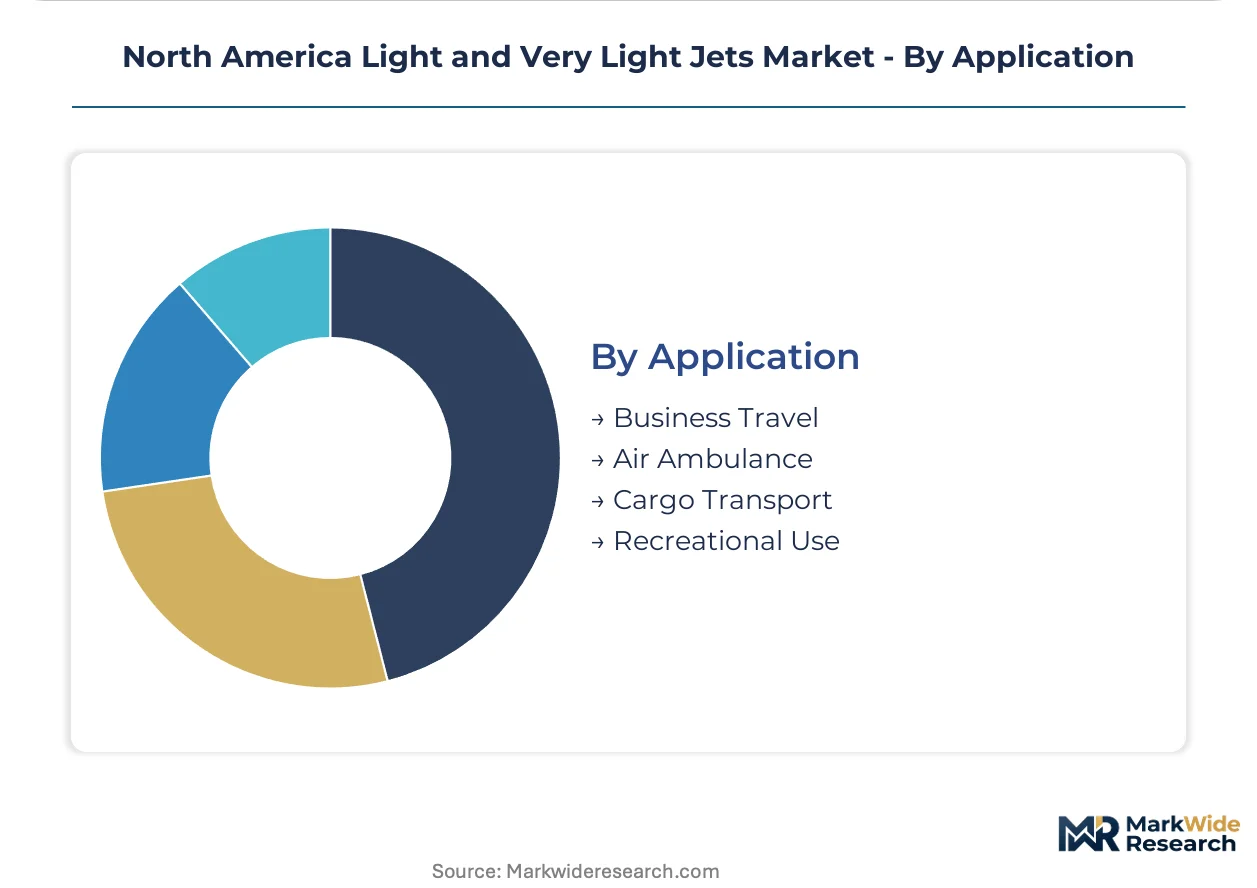
- Business Travel:Point-to-point executive transportation demanding schedule reliability and airport access flexibility. Demand clusters around metropolitan pairs with limited commercial airline service, particularly intra-Texas and Florida-Caribbean routes.
- Air Ambulance:Medical evacuation and organ transport missions requiring rapid response and specialized cabin configurations. Growth is expanding in rural Mountain West corridors where hospital density is low.
- Cargo Transport:Time-critical freight operations utilizing light jet speed for small-package delivery. Niche deployment concentrates in express logistics networks.
- Recreational Use:Personal travel and leisure missions where acquisition cost and operating simplicity outweigh maximum performance specifications.
Established utilization dominates Business Travel. Emerging utilization is expanding most quickly in Air Ambulance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's aerospace-grade aluminum supply corridors and Arizona's composite materials clusters anchor North American light jet manufacturing geography. FAA certification timelines and Transport Canada reciprocity frameworks shape cross-border production economics across the continent.
United States
Texas and Florida dominate charter operator fleet procurement, with Dallas-Fort Worth and Miami-Dade corridors concentrating MRO infrastructure and pilot training academies. FAA Part 23 reforms compress airframe approval timelines from 36 to 18 months for composite-structure submissions. Melbourne, Florida hosts Embraer's Phenom family assembly line, exporting to Canadian fractional programs under bilateral certification agreements.
Canada
Ontario and Quebec component suppliers rebuild post-pandemic production footprints to address U.S. integrator order backlogs. Transport Canada Civil Aviation maintains certification reciprocity with FAA while imposing supplementary noise abatement protocols at Toronto Pearson and Vancouver International. Montreal's avionics engineering cluster supplies integrated glass cockpit systems to airframe programs across the Great Lakes corridor.
Mexico
Baja California and Chihuahua aerospace parks attract tier-two fuselage fabrication contracts from U.S. manufacturers seeking labor cost arbitrage. Mexico's federal aviation authority aligns certification procedures with FAA standards under bilateral safety agreements. Querétaro's aeronautical university corridor feeds specialized composite technician pools to maquiladora operations serving the Sun Belt supply chain.
North America Light and Very Light Jets Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue single-engine and owner-flown niches with differentiated propulsion architectures. The vendor base stratifies across three tiers: multinational airframe integrators with fractional program relationships, specialized very light jet manufacturers, and component subsystem suppliers. Competitive positioning depends on certification speed, production scale, and MRO network density. Primary rivalry vectors include M&A consolidation of fractional ownership platforms and vertical integration into avionics software development.
Within the multinational integrator tier, Embraer SA and Textron Inc. anchor fleet standardization strategies among charter operators. Honda Aircraft Company exemplifies the specialized manufacturer archetype, leveraging over-the-wing engine mount technology for owner-flown market penetration. Cirrus Design Corporation occupies a unique position as the sole single-engine certified jet producer, capturing individual buyer segments seeking lower direct operating costs.
| Leading Market Players |
|---|
| Embraer SA |
| Honda Aircraft Company |
| Cirrus Design Corporation |
| Textron Inc. |
| Pilatus Aircraft Ltd |
| Bombardier Inc. |
| Stratos Aircraft |
| SyberJet Aircraft |
| One Aviation Corporation |
| Others |
Value Network & Pricing Analysis
Charter operator fleet standardization in the U.S. Sun Belt corridor anchors a contract-based long-term offtake model, where volume commitments to Embraer and Textron programs compress per-unit acquisition costs while locking in MRO service bundles.
Pricing Analysis
Warranty and engine coverage programs are unbundled from base airframe transactions, creating aftermarket revenue streams that offset thin manufacturing margins. Three-tier pricing structure across premium, standard, and economy levels separates fully equipped fractional fleet configurations from stripped owner-flown variants and charter-operator volume tiers. Price differentiation hinges on avionics certification grade and geographic delivery cost to remote Mountain West bases. Cost compression in the very light jet tier is intensifying because Honda Aircraft and Cirrus compete for individual buyers with overlapping performance specifications. Private owners in Arizona and Colorado exhibit the highest price sensitivity, while fractional programs in Florida and Texas absorb premium pricing for dispatch reliability guarantees.
Supply Chain Analysis
FAA Part 23 and Transport Canada Civil Aviation certification reciprocity agreements gate supplier qualification, restricting turbofan engine and composite fuselage sourcing to pre-approved manufacturing footprints in the United States, Canada, and Mexico. Canadian component suppliers in Ontario and Quebec feed aluminum and avionics subsystems to U.S. airframe integrators, while Baja California maquiladoras handle tier-two fuselage fabrication. Raw material dependencies center on aerospace-grade aluminum alloys, carbon fiber prepregs, and specialized avionics semiconductors. Single-source vulnerability concentrates in sub-5,000-pound thrust turbofan engines from limited manufacturers. Distribution runs through fractional ownership platform procurement offices and direct OEM sales teams targeting charter operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is mounting as FAA Part 23 reforms accelerate certification timelines, eroding the regulatory moats that previously protected subscale manufacturers from scaled rivals with faster market entry.
For Market Incumbents: Hedge against avionics integration complexity by captive supply of glass cockpit software engineering talent pools through targeted hiring in Montreal's aerospace corridor. Defensive consolidation moves include backward integration into composite fuselage manufacturing in Florida's aluminum supply corridor and certification investment for next-generation over-the-wing engine mount configurations that neutralize Honda Aircraft's aerodynamic differentiation. For New Entrants and Emerging Players: Enter via the air ambulance segment in rural Mountain West corridors, where hospital density gaps and rapid response requirements create specification flexibility for new airframe entrants. The most penetrable white space sits with single-engine jet cargo transport for time-critical freight networks, leveraging lower direct operating costs against twin-engine alternatives. A go-to-market angle through express logistics partnerships bypasses the charter operator procurement concentration that favors established fleet families. For Investors and Strategic Acquirers: The window for entry favors vertically integrated component suppliers with FAA-approved manufacturing footprints and dormant airframe development programs awaiting capital infusion. Long-term viability over the coming decade hinges on positioning for alternative propulsion transition timelines. Acquisition target archetypes include Canadian avionics engineering clusters with Transport Canada certification history and Mexican maquiladora operations with composite technician training pipelines. The signal to watch is EPA emissions guideline advancement, which would force engine selection pivots and strand development programs with non-compliant propulsion architectures.| Strategic Initiative | Industry Significance |
|---|---|
| FAA Part 23 Certification Investment | Accelerates airframe approval timelines from 36 to 18 months for composite-structure submissions. |
| Fractional Ownership Platform Acquisition | Captures predictable delivery pipelines and locks in fleet standardization commitments from corporate flight departments. |
| Composite Manufacturing Scale-Up | Enables production volumes previously unattainable in sub-10,000-pound weight class through automated fiber placement. |
| Avionics Software Development Partnership | Addresses specialized engineering talent scarcity for integrated autopilot and terrain awareness certification. |
| Sun Belt MRO Network Expansion | Reduces turnaround times for charter operators in Florida, Texas, and Arizona through concentrated infrastructure. |
Research Methodology
Document review covered FAA certification filings, Transport Canada Civil Aviation reciprocity agreements, and SEC 10-K disclosures from airframe manufacturers, complemented by interviews with fractional ownership program procurement directors, charter operator fleet managers, Canadian component supplier executives, and avionics systems engineering leads. Secondary validation drew from aircraft production databases, MRO service records, and bilateral aviation safety agreement texts. Bottom-up triangulation against top-down market sizing cross-checked delivery projections against airframe backlog reports.
Unit shipment and revenue estimates across the projection horizon reflect segmentation modeling by product type, end user category, propulsion architecture, and regional regulatory cluster. CAGRs were derived from historical delivery trend extrapolation adjusted for FAA Part 23 reform impact and fractional ownership program expansion trajectories. Industry-specific forecast inputs incorporated turbofan engine supplier production capacity constraints and composite materials lead time fluctuations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained EPA emissions guideline acceleration or prolonged Transport Canada-FAA reciprocity friction. Forecasts reflect assumptions regarding certification timeline compression and supply chain reconfiguration velocity. A model refresh is warranted upon material change in alternative propulsion technology readiness levels or metropolitan noise abatement protocol expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Maritime Patrol Aircraft Market
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
Aero Wing Market
Aircraft
South Korea Aerospace and Defense Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
GCC General Aviation Market
Aircraft
Heavy-Lift Helicopter Market
Aircraft
United States Aerospace and Defense Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Global Aircraft Tugs Market
Aircraft
Aircraft Manufacturing Market
Aircraft
Commercial Aircraft Aerostructures Market
Aircraft
Middle East and Africa Military Helicopters Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Global Ultralight and Light Aircraft Market