
 Turboprop Aircraft Market | 2026-2036
Turboprop Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Turboprop Aircraft Market Outlook
The regional aircraft distribution channel is fragmenting as lessors, national carriers, and specialized cargo operators each build direct procurement relationships with manufacturers. ATR sustains its dominance in the 50-70 seat segment through established European and Asia-Pacific operator networks. Textron Aviation Inc. leverages its Beechcraft King Air lineage to control the high-performance single-engine niche. De Havilland Aircraft of Canada Limited anchors the 40-seat utility segment with ruggedized designs purpose-built for remote runway operations.
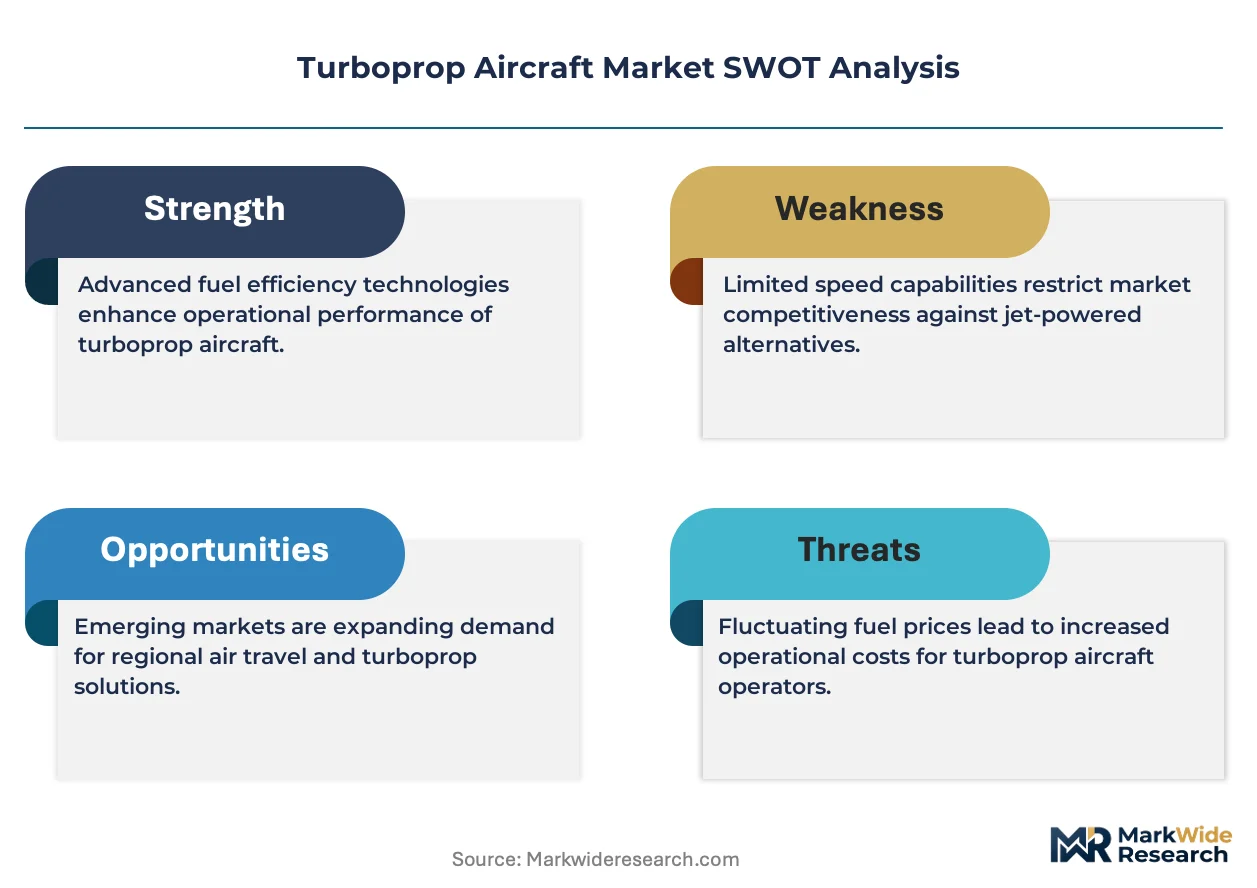
A turboprop aircraft propels itself via gas-turbine engines driving constant-speed propellers, typically operating at altitudes below 25,000 feet with stall speeds engineered for short-field performance below 61 knots in utility configurations. Its primary commercial purpose centers on cost-efficient transport of 9-90 passengers or equivalent cargo loads across stage lengths under 800 nautical miles where jet economics falter. Multi-engine turboprops command the passenger transport segment due to ETOPS relief and passenger confidence, while utility configurations capture outsized margins in special-mission roles including maritime patrol and aerial firefighting. Digital cockpit technology is displacing analog avionics across all product tiers as operators face mounting pressure from insurance underwriters and regulatory mandates for terrain awareness and automated flight data monitoring.
FAA Part 25 and EASA CS-25 certification frameworks govern airworthiness standards, while ICAO Annex 16 Volume I noise standards constrain engine and propeller design choices for new type certificates. Military end users navigate ITAR and national offset requirements that bifurcate procurement pathways from commercial channels. Stakeholders must monitor how emerging sustainable aviation fuel mandates and potential propulsion electrification thresholds reshape fleet planning horizons and residual value assumptions for conventionally powered turboprop platforms.
Market Dynamics
The turboprop aircraft market is experiencing a fundamental restructuring as digital cockpit architectures displace analog systems under mounting pressure from FAA Part 25 and EASA CS-25 certification mandates. Insurance underwriters now demand terrain awareness and automated flight data monitoring as baseline coverage conditions, forcing fleet-wide avionics refreshes.
Growth Catalysts
- Archipelagic Connectivity Demands:Indonesia's geography creates insatiable demand for short-haul operations where runway infrastructure cannot support jet aircraft. Regional carriers expand thin-route networks across the archipelago.
- ETOPS Relief Requirements:Multi-engine configurations satisfy regulatory frameworks for extended overwater operations, making twin-turboprops mandatory for maritime connectivity routes.
- Special-Mission Diversification:Aerial firefighting and maritime patrol applications generate outsized margins through utility configurations purpose-built for ruggedized operations.
Market Restraints
- SAF Supply Constraints:Sustainable aviation fuel availability remains geographically concentrated, with production hubs in North America and Europe failing to reach Southeast Asian operators.
- Propulsion Electrification Uncertainty:Hybrid-electric and hydrogen propulsion timelines threaten residual value assumptions for conventionally powered platforms, freezing long-term fleet planning.
- CS-25 Certification Burden:European airworthiness standards impose escalating compliance costs on new type certificates, compressing development economics for sub-50 seat entrants.
Strategic Opportunities
- Remote Runway Specialization:Papua New Guinea and Pacific Island states present untapped demand for 40-seat utility aircraft with stall speeds below 61 knots.
- Cargo Conversion Pathways:Passenger-to-freighter modifications unlock secondary market value as e-commerce logistics operators seek sub-800 nautical mile stage efficiency.
- Integrated Digital Cockpit Retrofits:Aftermarket avionics packages create recurring revenue streams from installed bases of aging King Air and Dash 8 fleets.
Industry Challenges
- Flight Data Analyst Shortage:Automated monitoring systems require specialized personnel to interpret terrain warnings and engine parameter trends, skills concentrated among legacy airline maintenance divisions.
- Cross-Certification Complexity:ITAR restrictions bifurcate military and commercial procurement pathways, forcing dual supply chains for special-mission variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turboprop Aircraft Market |
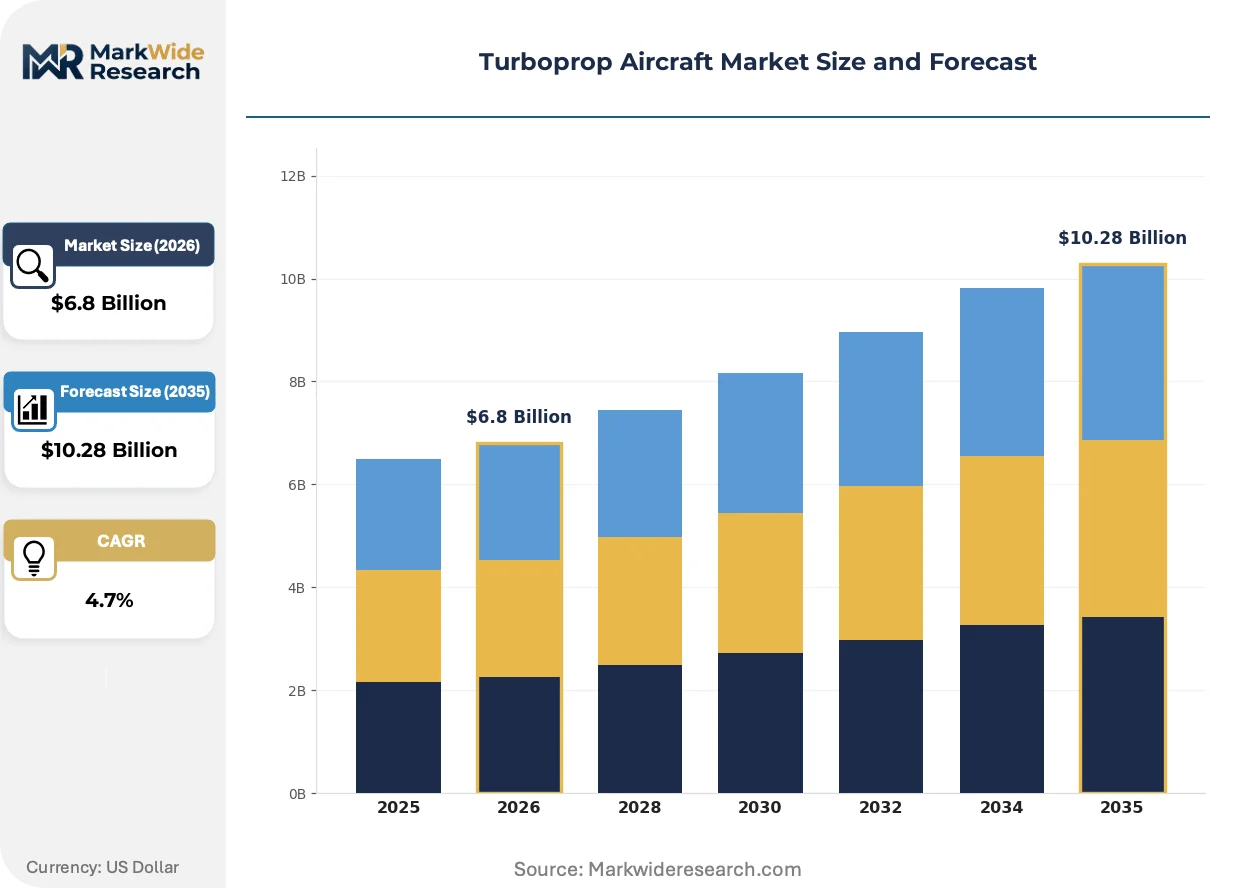
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Engine, Multi-Engine, Utility, Training Application: Cargo Transport, Passenger Transport, Medical Evacuation, Surveillance End User: Commercial Airlines, Charter Operators, Military, Governments Technology: Digital Cockpit, Fly-by-Wire, Enhanced Vision Systems, Noise Reduction |
| Companies Covered | Airbus SE, ATR, Lockheed Martin Corporation, Textron Aviation Inc., Pilatus Aircraft Ltd., Embraer S.A., De Havilland Aircraft of Canada Limited, Daher, Bombardier Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turboprop Aircraft Market Strategic Shifts
Propulsion and avionics architectures are converging around electrification readiness and predictive maintenance capabilities. Manufacturers now engineer platforms for post-2030 sustainable fuel compatibility and modular powertrain swaps.
Integrated flight deck systems are virtualizing traditional analog instruments across all product tiers. Regional carriers in Indonesia and the Philippines adopt glass cockpit retrofits at accelerating pace to satisfy insurance mandates. This virtualization compresses training costs while enabling single-pilot operations in cargo configurations.
EASA CS-25 amendments now mandate automatic dependent surveillance-broadcast (ADS-B) Out capabilities for all new type certificates. European operators face accelerated retrofit deadlines for existing fleets, diverting capital from airframe renewal programs. The 50-70 seat segment absorbs disproportionate compliance burden as lessors demand standardized avionics packages across mixed fleets.
Direct procurement relationships between national carriers and manufacturers are fragmenting traditional lessor-dominated distribution. Specialized cargo operators in Vietnam and Malaysia now negotiate airframe customizations at factory level, bypassing regional distributors. This disintermediation concentrates pricing power with OEMs while compressing aftermarket service margins for third-party maintenance providers.
Turboprop Aircraft Market Segmentation
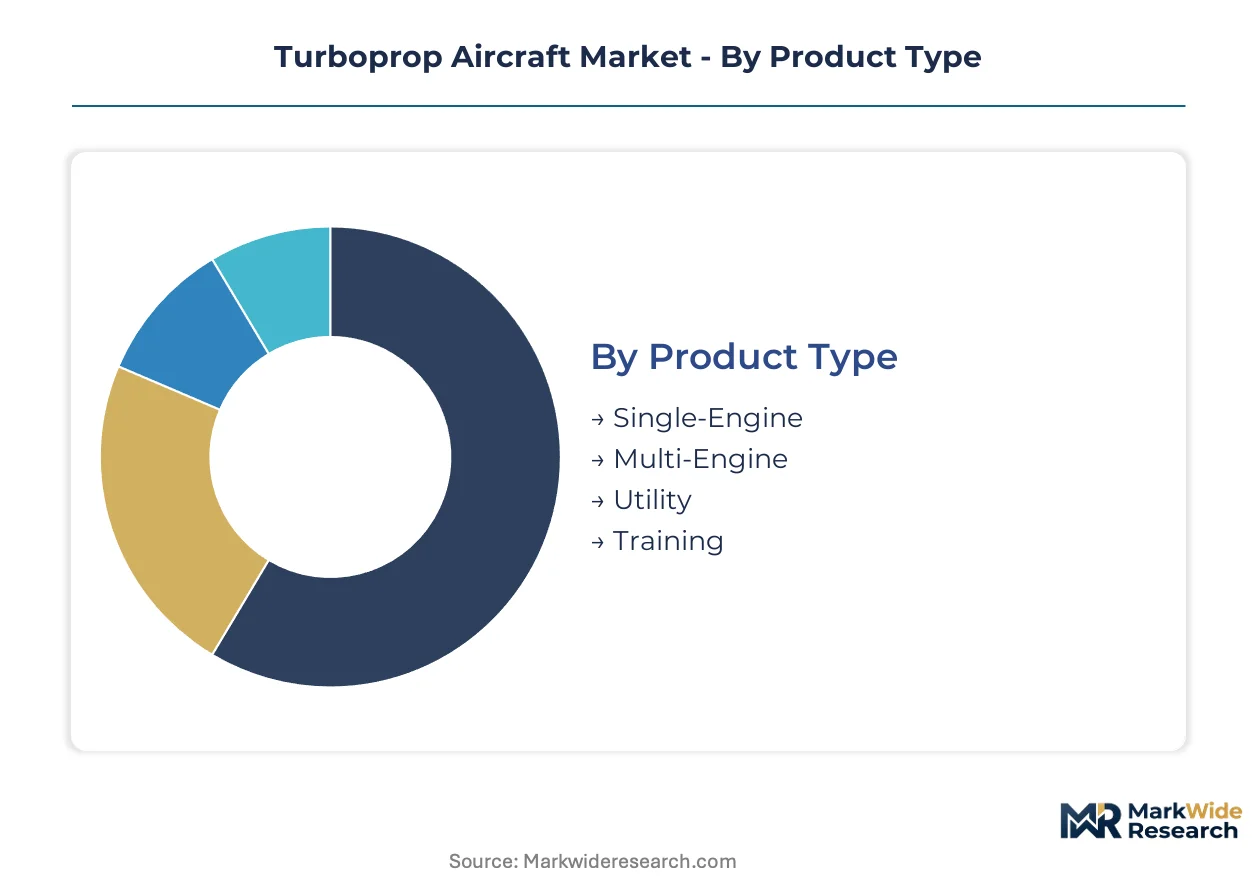
Turboprop segmentation reveals how operational requirements fragment procurement across radically different mission profiles. Product architecture, application intensity, and end-user budget cycles each create distinct competitive arenas with divergent margin structures and technology adoption timelines.
Product Type:
Mature configurations dominate revenue concentration while emerging variants capture specialized niches through performance differentiation.
- Multi-Engine:Twin-turbine architectures power 50-70 seat regional aircraft with ETOPS certification for overwater routes. Demand clusters among Indonesian archipelagic carriers connecting island pairs below 800 nautical miles where jet economics collapse. ETOPS relief mandates from FAA and EASA make this configuration non-negotiable for maritime connectivity.
- Single-Engine:High-performance turboprops like the King Air lineage serve owner-operators and corporate shuttle missions with pressurized cabins and 300-knot cruise speeds. The segment concentrates in North American and European executive aviation markets where operating cost discipline outweighs speed requirements.
- Utility:Ruggedized designs with stall speeds below 61 knots access unimproved runways in Papua New Guinea and Pacific Island states. These platforms command premium pricing for special-mission roles including aerial firefighting and maritime patrol.
- Training:Simplified systems architectures reduce hourly operating costs for flight schools building multi-engine turbine time. Military pilot pipelines in Southeast Asia and the Middle East drive fleet orders with standardized avionics packages.
Multi-engine configurations retain volume leadership; utility variants hold the steepest expansion curve through special-mission diversification.
Application:
Cost tier stratification separates high-frequency scheduled operations from discretionary mission profiles with divergent equipment specifications.
- Passenger Transport:Scheduled regional services operate 40-70 seat aircraft on stage lengths under 500 nautical miles. Indonesian carriers like Wings Air and Susi Air deploy turboprops exclusively for thin-route penetration where runway length and surface conditions exclude jets.
- Cargo Transport:E-commerce logistics operators convert aging passenger airframes for sub-800 nautical mile feeder networks. Vietnamese and Malaysian cargo specialists negotiate factory-level customizations with cargo door modifications and reinforced floors.
- Medical Evacuation:Pressurized cabins with stretcher configurations serve remote healthcare access in archipelagic geographies. Philippine and Indonesian air ambulance operators require short-field performance for island clinic connectivity.
- Surveillance:Maritime patrol and border enforcement missions utilize synthetic aperture radar and electro-optical sensor pods. Military end users navigate ITAR restrictions that bifurcate procurement from commercial channels.
Passenger transport absorbs the largest equipment volumes; cargo conversion pathways are climbing the fastest as e-commerce reshapes regional logistics.
End User:
Customer type determines procurement rhythm, with commercial operators cycling on residual value horizons and government buyers following multi-year appropriation schedules.
- Commercial Airlines:Scheduled carriers in Indonesia, the Philippines, and Nepal prioritize fleet commonality for maintenance efficiency. These operators face insurance mandates for terrain awareness and automated flight data monitoring that accelerate avionics refresh cycles.
- Military:Defense procurement follows national offset requirements and ITAR compliance pathways distinct from commercial channels. Special-mission variants for maritime patrol and signals intelligence carry customized sensor integrations.
- Charter Operators:On-demand services in executive and adventure tourism segments value cabin flexibility and rapid reconfiguration. Papua New Guinea mining sector contracts sustain demand for ruggedized utility platforms.
- Governments:State-owned operators combine passenger transport with dual-use special-mission capability. Pacific Island nation fleets serve inter-island connectivity while supporting fisheries enforcement and disaster response.
Commercial airlines retain volume leadership; charter operators are gaining share fastest through tourism and resource sector contract expansion.
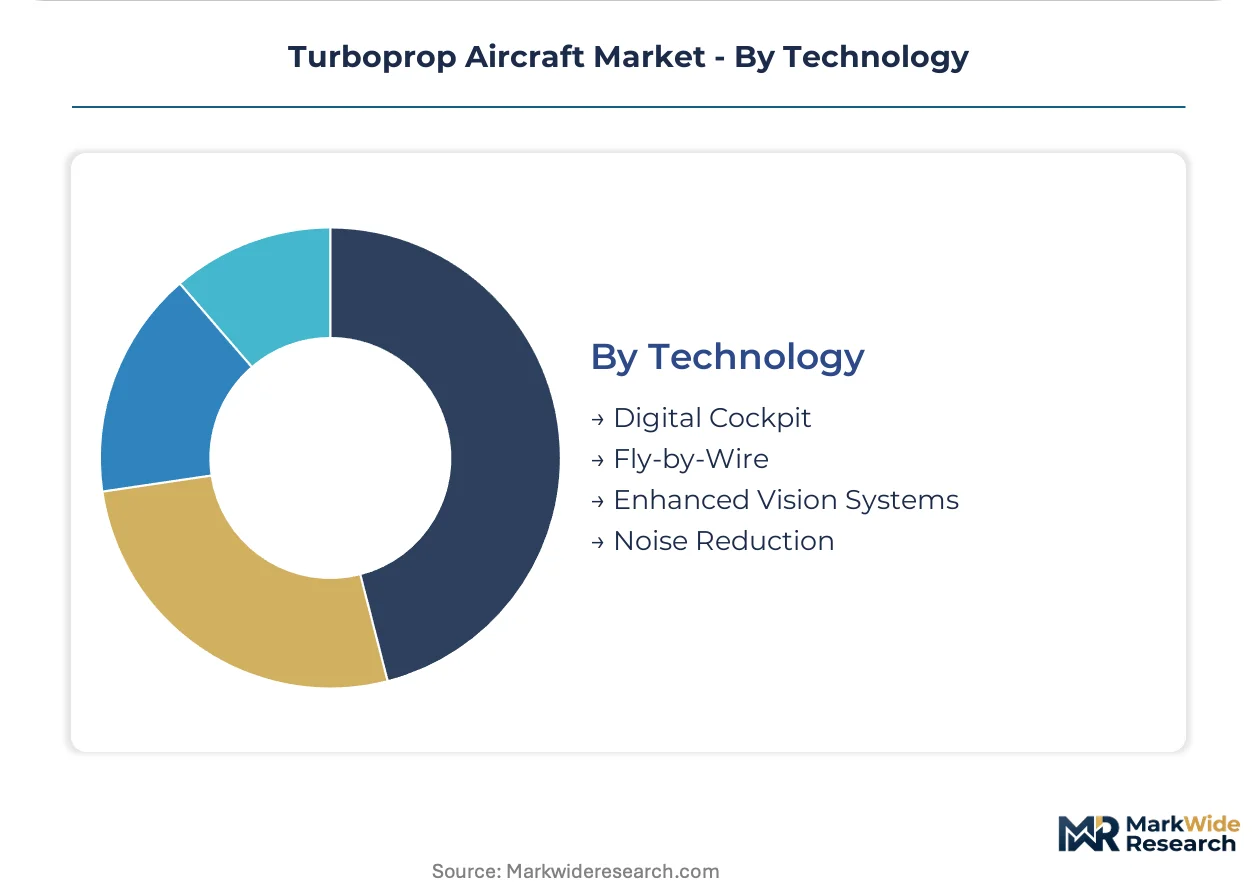
Technology:
Supply concentration in avionics and propulsion subsystems shapes how technology tiers propagate through fleet retrofit cycles.
- Digital Cockpit:Glass cockpit architectures displace analog instruments under FAA Part 25 and EASA CS-25 mandates. Retrofit demand concentrates in aging King Air and Dash 8 installed bases where insurance underwriters deny coverage for legacy avionics.
- Enhanced Vision Systems:Infrared and synthetic vision technologies enable operations in degraded visibility at remote airfields. Indonesian and Philippine operators adopt these systems for monsoon season reliability.
- Noise Reduction:ICAO Annex 16 Volume I compliance drives propeller and nacelle redesign for new type certificates. European noise regulations impose disproportionate burden on sub-50 seat segment entrants.
- Fly-by-Wire:Digital flight control systems remain concentrated in larger turboprops above 50 seats due to certification economics. Military special-mission variants adopt these systems for precision autopilot integration.
Digital cockpit retrofits retain volume leadership; enhanced vision systems hold the steepest expansion curve through weather-critical operational requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian operators command pricing premiums for archipelagic connectivity while North American buyers extract volume discounts through fleet standardization. This asymmetry reshapes manufacturer negotiation strategies across procurement cycles.
Indonesia
Wings Air and Susi Air expand turboprop fleets to penetrate thin-route networks across 17,000 islands where runway length and surface conditions exclude jet operations. The Directorate General of Civil Aviation enforces terrain awareness mandates that accelerate glass cockpit retrofits. Jakarta's Halim Perdanakusuma International Airport anchors maintenance, repair, and overhaul clusters serving the domestic fleet.
United States
Part 135 charter operators and corporate flight departments sustain demand for pressurized cabin configurations with 300-knot cruise capabilities. FAA Part 25 certification requirements push avionics suppliers toward integrated digital architectures. Wichita, Kansas hosts engineering concentrations where Textron Aviation optimizes production lines for the high-performance single-engine segment.
Canada
Remote community access programs subsidize 40-seat utility aircraft for operations into unimproved runways across the Arctic and sub-Arctic. Transport Canada aligns with EASA CS-25 noise standards that constrain new type certificate economics. Calgary and Toronto maintenance bases specialize in passenger-to-freighter conversions for aging Dash 8 fleets entering cargo service.
France
ATR's Toulouse headquarters anchors European turboprop manufacturing with supply chain spillovers into Spain and Italy. EASA CS-25 amendments mandate ADS-B Out capabilities that compress retrofit timelines for regional operators. The Occitanie aerospace cluster concentrates propeller and nacelle suppliers serving the 50-70 seat segment.
Brazil
Amazon basin connectivity demands drive procurement of short-field aircraft for operations into 800-meter strips unreachable by regional jets. ANAC certification pathways run parallel to FAA frameworks, creating dual compliance burdens for imported platforms. São José dos Campos hosts engineering centers where Embraer evaluates turboprop derivatives for defense special-mission applications.
Turboprop Aircraft Market Competitive Environment
European regional specialists and North American diversified aerospace conglomerates split the market through divergent scale logics. The competitive arena consolidates around three strategic archetypes: dedicated turboprop pure-plays, diversified aviation platforms with turboprop divisions, and defense contractors with special-mission variants. M&A activity concentrates in avionics subsystem suppliers, while geographic expansion targets Southeast Asian lessor relationships and Indonesian national carrier direct procurement channels.
Among European pure-plays, ATR and De Havilland Aircraft of Canada Limited exemplify the dedicated regional aircraft archetype with established operator networks. Textron Aviation Inc. occupies a position within the diversified conglomerate tier, leveraging Beechcraft lineage for executive and special-mission positioning. Pilatus Aircraft Ltd. and Daher represent the high-performance single-engine and utility specialization vectors respectively, each anchoring distinct price-performance tiers.
| Leading Market Players |
|---|
| Airbus SE |
| ATR |
| Lockheed Martin Corporation |
| Textron Aviation Inc. |
| Pilatus Aircraft Ltd. |
| Embraer S.A. |
| De Havilland Aircraft of Canada Limited |
| Daher |
| Bombardier Inc. |
| Others |
Value Chain & Pricing Dynamics
The Singapore-Jakarta air freight corridor absorbs disproportionate logistics premiums that cascade through turboprop component sourcing, concentrating pricing power among European propulsion suppliers while forcing Southeast Asian operators into configured-to-order premiums for specialized avionics packages.
Pricing Analysis
The customization-premium spread separates standard multi-engine configurations from utility variants with stall speeds below 61 knots, where ruggedized landing gear and unimproved runway certification command substantial factory-level uplifts. Three-tier pricing structure across premium, standard, and economy levels reflects ETOPS certification tiers, avionics generation, and after-sales service bundling. Cost compression in the sub-50 seat segment is intensifying because EASA CS-25 noise compliance burdens new type certificate economics. Regional carriers in Indonesia exhibit acute price sensitivity due to archipelagic fleet scale requirements, while special-mission military buyers prioritize performance specifications over unit economics.
Supply Chain Analysis
Contract manufacturing concentration for turboprop airframes rests on De Havilland's Toronto facility and ATR's Toulouse assembly lines, with propulsion subsystems anchored in Pratt & Whitney Canada's Montreal engineering cluster. Critical titanium forgings and composite nacelle components draw from Italy, Poland, and Japan. Single-source vulnerability pervades the 50-70 seat digital cockpit segment, where Garmin and Collins Aerospace dominate integrated flight deck supply. Distribution runs through direct procurement relationships between Indonesian national carriers and OEMs, bypassing traditional lessor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turboprop platform economics faces an inflection as digital cockpit standardization creates interoperability layers between avionics subsystems, enabling modular upgrades that reshape residual value calculations across mixed fleets.
For Market Incumbents: Pre-empt hybrid-electric propulsion obsolescence by locking in airframe architectures compatible with post-2030 powertrain swaps, while consolidating aftermarket service capacity in Jakarta and Manila to defend against third-party maintenance disintermediation. Backward integration into composite nacelle production insulates margin pressure from Italian supplier concentration.
For New Entrants and Emerging Players: Build out cargo conversion capabilities for aging Dash 8 and ATR 72 installed bases, targeting Vietnamese e-commerce logistics operators with passenger-to-freighter modification services. Papua New Guinea's unimproved runway access represents the most penetrable geography, with factory-level customization for 40-seat utility configurations offering a direct go-to-market angle bypassing established OEM distribution.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified aerospace conglomerates with underperforming turboprop divisions amid strategic pivot toward electrification. Long-term viability hinges on special-mission diversification and archipelagic connectivity demand durability. Watch Indonesian Directorate General of Civil Aviation mandates for terrain awareness retrofits as an inflection indicator for aftermarket avionics demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Cockpit Retrofit Program | EASA CS-25 mandates force glass cockpit upgrades across Southeast Asian King Air fleets. |
| Cargo Conversion Partnership | Vietnamese logistics operators negotiate factory-level freighter modifications with reinforced floors. |
| Special-Mission Variant Development | Maritime patrol configurations for Pacific Island governments bypass ITAR-restricted procurement channels. |
| Propulsion Electrification Roadmap | Hybrid-electric compatibility engineering preserves residual value against sustainable fuel mandates. |
| Regional MRO Hub Expansion | Jakarta maintenance clusters capture archipelagic fleet density for recurring service revenue. |
Study Parameters
Cross-validation between OEM production disclosures and Indonesian Directorate General of Civil Aviation fleet registration data anchors the qualitative findings, combining primary interviews with turboprop fleet managers, avionics procurement leads, special-mission program officers, and regional lessor executives with secondary validation from FAA type certificate databases, EASA CS-25 amendment filings, ICAO Annex 16 noise compliance records, and customs import manifests for turboprop components. Bottom-up installed base analysis and top-down regional demand modeling triangulate volume estimates.
Calibration against historical delivery cycles and retrofit penetration rates informs the projection framework across the analysis window, with segmentation dimensions spanning product architecture, application intensity, end-user procurement rhythm, and technology adoption tier. CAGRs derive from regression against archipelagic connectivity demand, special-mission diversification trajectories, and regulatory mandate timelines. Forecast inputs incorporate terrain awareness mandate compliance curves and sustainable aviation fuel infrastructure buildout assumptions.
Sensitivities concentrate around propulsion electrification timelines, EASA CS-25 noise standard stringency, and Indonesian airport infrastructure investment cadence. Quarterly review of Jakarta fleet expansion announcements, Toulouse production rate adjustments, and ADS-B Out retrofit completion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Ailerons Market
Aircraft
Middle-East Aviation Market
Aircraft
Airplane Ailerons Market
Aircraft
Aircraft Elevator Market
Aircraft
Military Aircraft Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Search and Rescue Aircraft Market
Aircraft
Onboard Oxygen Generating System (OBOGS) Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
Air Speed Indicator Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
Commercial Aircraft Leasing Market
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
General Aviation Market
Aircraft
Sailplane Market
Aircraft
Evtol Aircraft Market