
 Aircraft Windshield Wiper and Washer System Market | 2026-2036
Aircraft Windshield Wiper and Washer System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Windshield Wiper and Washer System Market Outlook
North American specialty aerospace component manufacturing is shifting toward integrated wiper-washer modules for next-generation flight decks. Eaton Corporation leverages its electromechanical actuator expertise to anchor positions in OEM supply chains for commercial platforms. RTX Corporation through Collins Aerospace competes on integrated flight-deck systems that bundle visibility management with avionics architectures. Safran S.A. specializes in certifying equipment across multiple regulatory jurisdictions, sustaining aftermarket revenue through long-term service agreements with flag carriers.
Aircraft windshield wiper and washer systems are electromechanical or pneumatic assemblies designed to maintain pilot visibility during precipitation, ice accumulation, or foreign particulate contamination, typically operating at blade speeds of 30-45 cycles per minute against aerodynamic loads exceeding 300 knots. Electric wiper configurations dominate new commercial deliveries due to reduced weight and simplified maintenance intervals compared to pneumatic alternatives. The electromechanical technology segment leads in value terms because hydraulic and vacuum-based systems face obsolescence pressure from airline fuel-efficiency targets. Commercial aviation end users generate the largest installation-type revenue pool, though military aviation specifications command premium pricing for hardened, EMI-resistant designs.
FAA airworthiness standards under Part 25.775 mandate optical clarity retention under simulated icing conditions, while EASA CS-25 certification requires European suppliers to demonstrate equivalent performance through the agency's delegated compliance framework. The EPA regulates washer fluid chemical formulations for environmental discharge limits during ground maintenance operations. Stakeholders must monitor evolving CSRD sustainability disclosure requirements from European OEM customers and anticipate how dual-carbon mandates from China's MEE could reshape supplier qualification criteria for exported components.
Market Dynamics
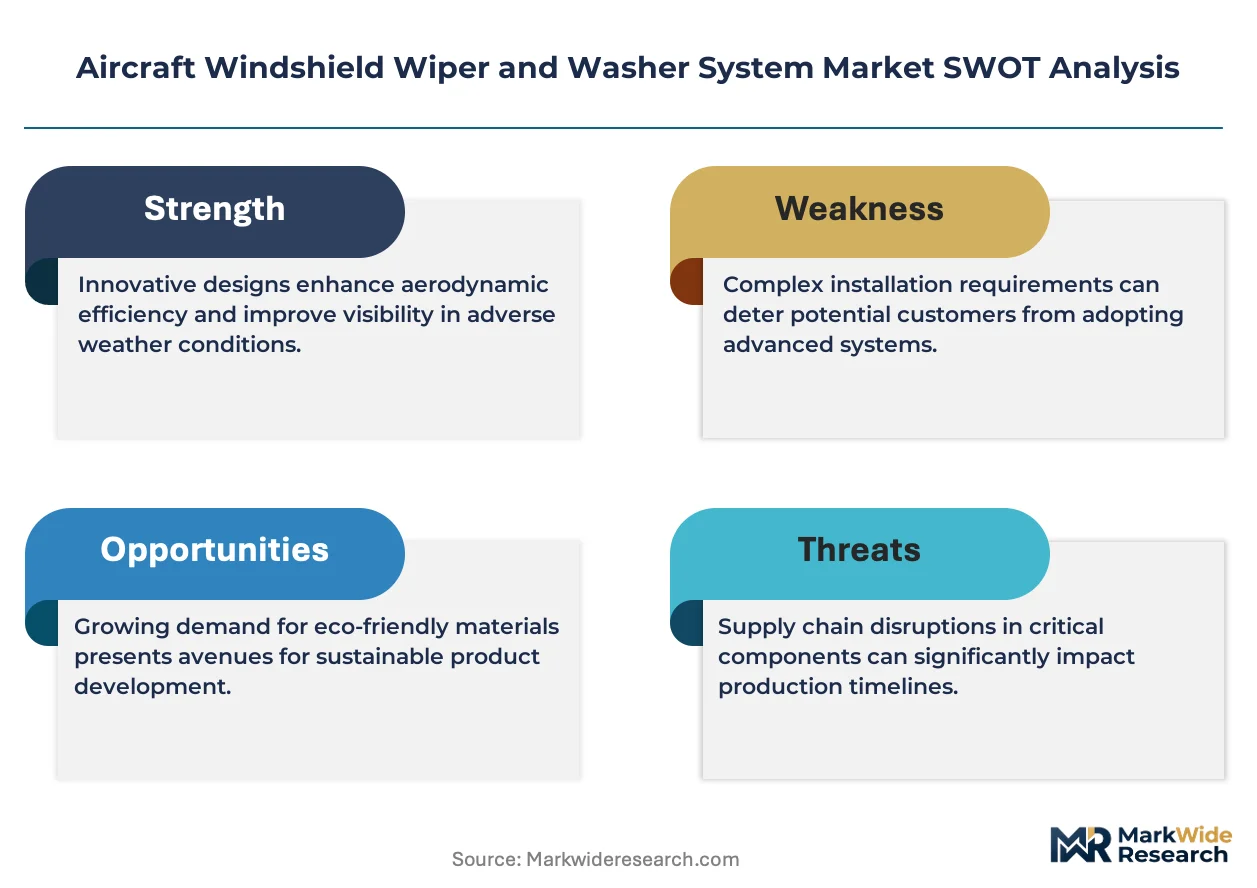
Electromechanical wiper architectures are displacing pneumatic legacy systems across commercial aviation fleets, driven by FAA and EASA fuel-efficiency mandates that penalize weight and maintenance burden. This technology transition concentrates supplier capability among electromechanical actuator specialists while fragmenting pneumatic component vendors into aftermarket-only positions.
Growth Catalysts
- Retrofit mandates:FAA airworthiness directives and EASA CS-25 amendments compel visibility system upgrades on aging narrow-body aircraft, creating sustained aftermarket demand for electromechanical replacement kits.
- Electromechanical weight reduction:Electric motor and carbon-fiber arm assemblies cut system mass by 40% versus pneumatic alternatives, aligning with airline fuel burn reduction targets.
- Flight deck integration:Next-generation avionics architectures bundle wiper-washer control with centralized flight management systems, requiring OEMs to source integrated modules rather than discrete components.
Market Restraints
- Rare earth magnet supply concentration:High-performance brushless wiper motors depend on neodymium supply chains concentrated in China's refining and magnet fabrication sectors.
- Certification timeline friction:EASA delegated compliance framework and FAA Part 25.775 testing protocols extend new product qualification cycles to 18-24 months, freezing design iterations.
- Electromechanical obsolescence risk:Pneumatic system expertise is attriting from maintenance technician training pipelines, stranding legacy fleet support capabilities.
Strategic Opportunities
- Unmanned aerial system expansion:Military and commercial drone platforms require miniaturized, low-power visibility systems without crewed aircraft hydraulic infrastructure.
- CSRD disclosure alignment:European OEM customers now require supplier sustainability documentation for washer fluid formulations and end-of-life component recyclability.
- Predictive maintenance integration:Sensor-embedded wiper assemblies feeding health monitoring data to airline MRO software platforms enable service contract unbundling from hardware sales.
Industry Challenges
- EMI-hardening talent scarcity:Military aviation specifications demand electromagnetic interference-resistant designs, but qualified aerospace electrical engineers with MIL-STD-461 experience are concentrated at legacy defense contractors.
- Legacy fleet integration complexity:Electromechanical retrofits onto 1980s-era aircraft require structural modification of windshield frames and electrical bus reconfiguration, complicating STC approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Windshield Wiper and Washer System Market |
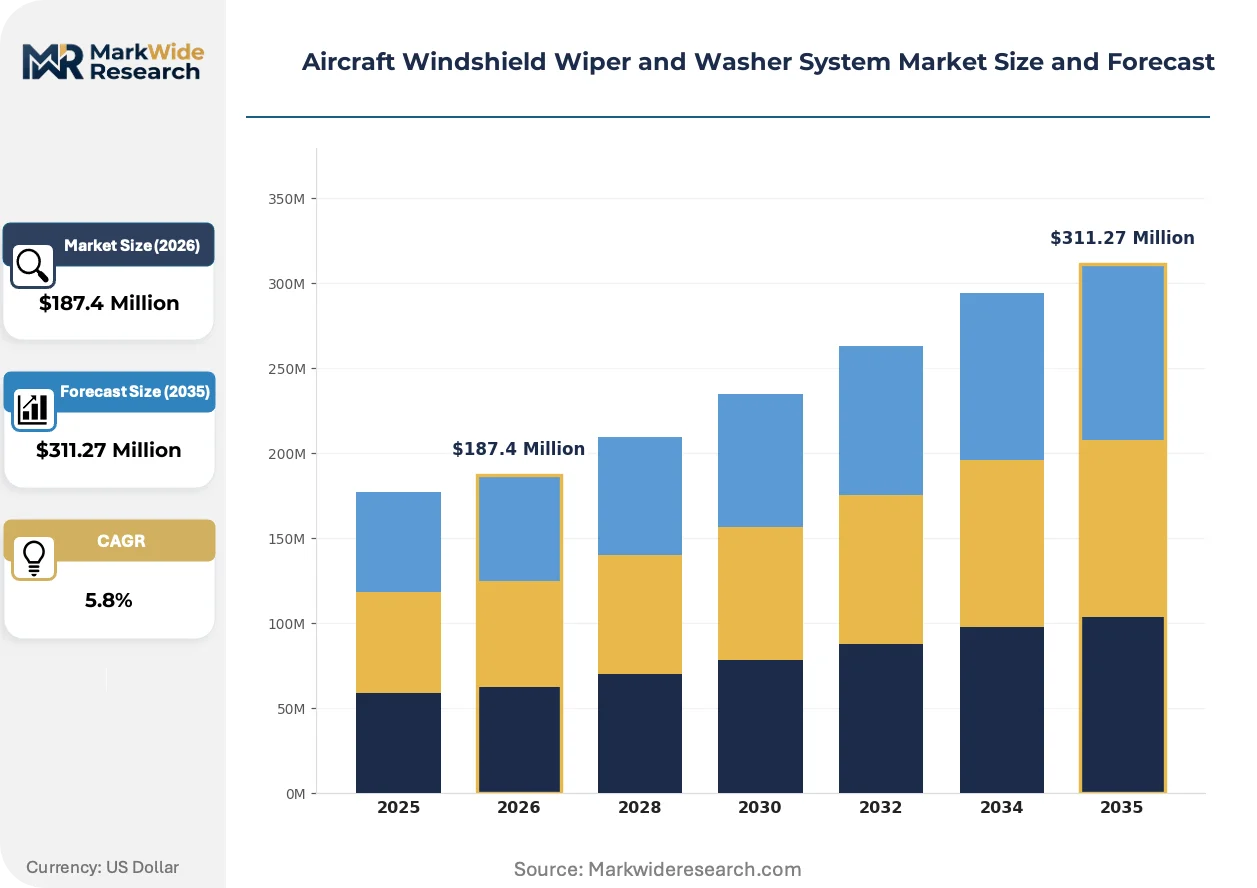
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Wipers, Electric Wipers, Pneumatic Systems, Washer Pumps Technology: Electromechanical, Hydraulic, Vacuum, Electromagnetic End User: Commercial Aviation, Military Aviation, Repair Services, Private Aviation Installation Type: OEM, Aftermarket, Refurbished, Custom Solutions |
| Companies Covered | Eaton Corporation, L3Harris Technologies, RTX Corporation (Collins Aerospace), Meggitt PLC, GKN Aerospace, Honeywell International Inc., Parker Hannifin Corporation, Aerosystems S.r.l., Safran S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Windshield Wiper and Washer System Market Strategic Shifts
Smart material actuation and integrated health monitoring are converging to transform windshield wiper systems from passive mechanical assemblies into active flight deck subsystems. These developments compress maintenance intervals while expanding supplier value capture beyond hardware into data services.
Electroactive polymer actuators are automating blade pressure distribution across curved windshields, eliminating mechanical linkages and reducing part count by 60%. Boeing and Airbus are qualifying these systems for next-generation single-aisle platforms, with adoption timelines accelerating as suppliers demonstrate 100,000-cycle durability. This architecture is automating the transition from scheduled replacement to condition-based maintenance, collapsing MRO revenue predictability for traditional component vendors.
REACH chemical restrictions and EPA washer fluid discharge limits are forcing reformulation of glycol-based de-icing solutions toward biodegradable surfactant alternatives. European suppliers face ECHA substance authorization requirements for legacy corrosion inhibitors, compressing available chemical portfolios. Military aviation end users are responding slowest, as MIL-PRF-23699 compatibility requirements freeze specification changes until alternative fluids complete full airworthiness validation.
Airline procurement departments are consolidating visibility system purchasing under flight-deck integration contracts rather than discrete component tenders. Lufthansa Technik and Delta TechOps now specify wiper-washer performance outcomes in MRO agreements, transferring design accountability to tier-one avionics integrators. This pattern is most advanced in Germany and the United States, where flag carriers have centralized technical procurement functions with systems engineering authority over subsystem specifications.
Aircraft Windshield Wiper and Washer System Market Segmentation
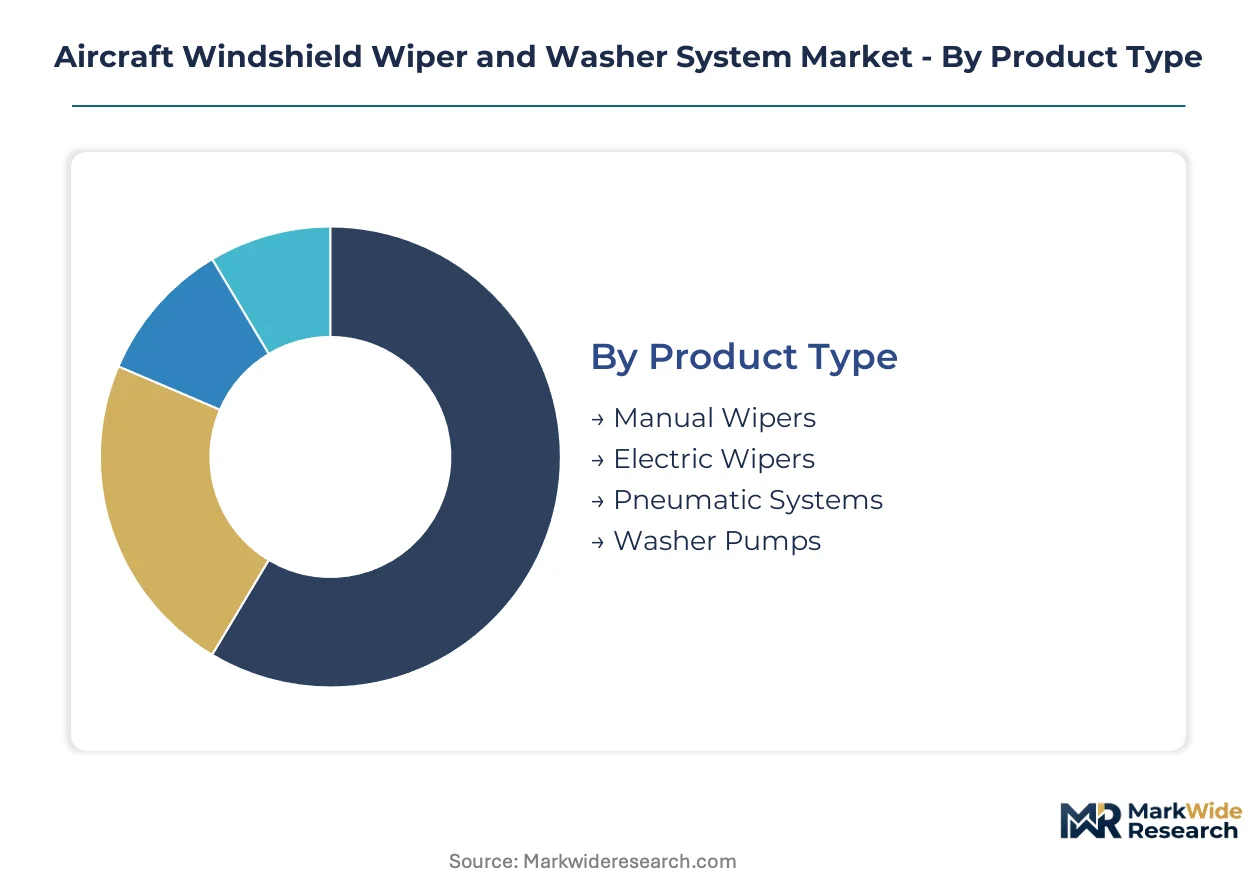
Aircraft windshield wiper and washer systems fragment across four critical dimensions that determine integration depth, certification burden, and supplier margin structures. Each segmentation axis reveals distinct competitive dynamics between standalone component vendors and integrated flight-deck system providers.
Product Type:
Standalone wiper assemblies serve legacy platforms with minimal avionics integration, while embedded modules bundle motor, control logic, and washer delivery into single line-replaceable units for next-generation aircraft.
- Electric Wipers:Brushless DC motor architectures with carbon-fiber wiper arms deliver 30-45 cycles per minute against 300-knot aerodynamic loads. Commercial aviation OEMs in the United States and European Union specify these for new narrow-body deliveries under FAA Part 25.775 and EASA CS-25 fuel-efficiency mandates.
- Pneumatic Systems:Legacy vacuum-actuated designs persist on aging regional jets and cargo conversions where electrical bus reconfiguration costs exceed replacement economics. Aftermarket demand concentrates in Germany, France, and the United Kingdom for narrow-body retrofit programs.
- Manual Wipers:Cable-operated emergency backup systems on select general aviation platforms require no electrical power.
- Washer Pumps:Positive-displacement fluid delivery units integrate with centralized reservoir architectures on integrated flight decks.
Electric wipers lead volumes today; washer pumps are gaining share fastest through flight-deck bundling contracts.
Technology:
Cost tier stratification separates premium electromechanical platforms from legacy hydraulic and vacuum alternatives facing obsolescence pressure.
- Electromechanical:Solid-state motor controllers with Hall-effect position sensing enable variable-speed operation and stall protection. Military aviation specifications command premium pricing for MIL-STD-461 EMI-hardened variants.
- Electromagnetic:Linear actuator designs eliminate rotary-to-reciprocating linkages, cutting part count by 60% for next-generation single-aisle platforms Boeing and Airbus are qualifying.
- Hydraulic:Pressure-fed wiper systems on wide-body legacy platforms require dedicated hydraulic circuits increasingly decommissioned during heavy maintenance checks.
- Vacuum:Engine-bleed actuation survives only on turboprop regional aircraft where pneumatic infrastructure remains standard.
Electromechanical dominates value capture; electromagnetic architectures are expanding most quickly through electroactive polymer qualification programs.
End User:
Volume concentration varies sharply between fleet-scale commercial operators and fragmented private aviation demand.
- Commercial Aviation:Flag carriers and low-cost operators drive OEM specification authority through centralized technical procurement functions. Lufthansa Technik and Delta TechOps now contract for wiper-washer performance outcomes rather than discrete component purchases.
- Military Aviation:Hardened designs for fighter, transport, and rotary-wing platforms require electromagnetic interference resistance and battlefield debris tolerance. Qualified suppliers concentrate at legacy defense contractors with MIL-STD-461 engineering depth.
- Repair Services:Independent MRO facilities in Germany, the United Kingdom, and France source electromechanical replacement kits for aging narrow-body visibility system mandates.
- Private Aviation:Business jet and general aviation operators prioritize weight reduction and STC pathway simplicity over integrated system sophistication.
Commercial aviation leads volumes today; repair services are climbing the fastest as EASA and FAA retrofit directives compound fleet aging effects.
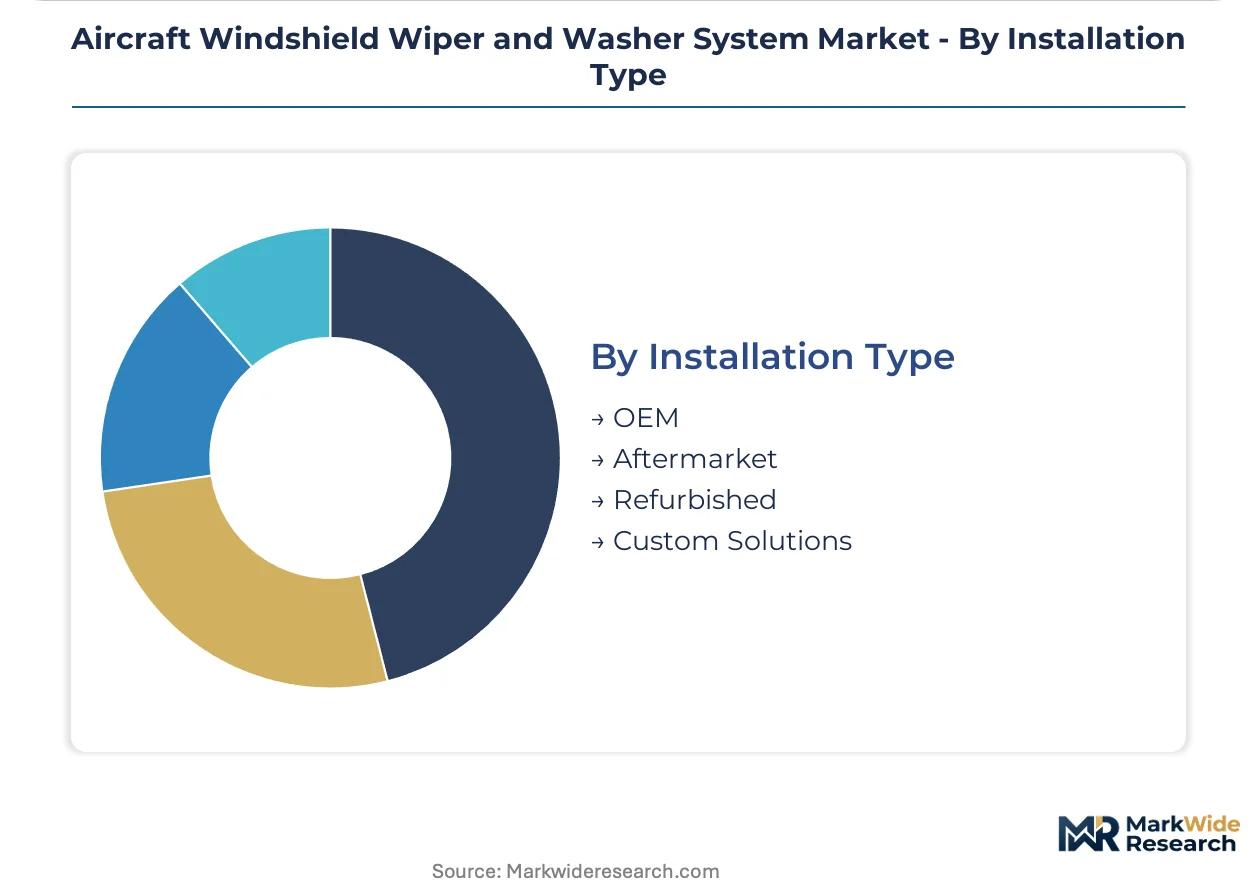
Installation Type:
Margin structure diverges between captive OEM supply chains and fragmented aftermarket channels with distinct certification burdens.
- OEM:Original equipment supply contracts bundle wiper-washer modules with avionics architectures, transferring design accountability to tier-one integrators. Eaton Corporation and RTX Corporation anchor positions through electromechanical actuator and flight-deck system expertise.
- Aftermarket:Electromechanical replacement kit demand concentrates where EASA CS-25 amendments and FAA airworthiness directives compel visibility system upgrades on 1980s-era narrow-body aircraft.
- Refurbished:Overhauled pneumatic components serve cost-sensitive cargo operators extending legacy fleet service life.
- Custom Solutions:Specialized configurations for experimental aircraft and unmanned aerial systems bypass standard certification pathways.
OEM commands value concentration today; aftermarket channels are expanding most quickly through retrofit mandate compliance deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains the largest commercial aviation fleet requiring visibility system retrofits, while Germany concentrates European aftermarket demand through Lufthansa Technik's centralized procurement authority.
United States
Delta TechOps and American Airlines drive electromechanical replacement kit demand for aging narrow-body fleets. FAA Part 25.775 airworthiness directives compel visibility system upgrades on 1980s-era aircraft. Wichita, Kansas anchors specialty aerospace manufacturing clusters where integrated wiper-washer modules undergo qualification testing.
Germany
Lufthansa Technik contracts for wiper-washer performance outcomes rather than discrete component purchases, transferring design accountability upstream. EASA CS-25 amendments mandate equivalent optical clarity standards under the delegated compliance framework. Hamburg and Munich concentrate MRO facilities sourcing electromechanical retrofit solutions for European flag carriers.
France
Airbus qualification programs for electroactive polymer actuators accelerate supplier adoption timelines for next-generation single-aisle platforms. ECHA substance authorization requirements compress available chemical portfolios for washer fluid formulations. Toulouse anchors flight-deck integration engineering where tier-one avionics suppliers bundle visibility management systems.
United Kingdom
BAE Systems and Rolls-Royce procurement specifications influence military aviation hardened designs requiring MIL-STD-461 EMI resistance. REACH chemical restrictions force reformulation of glycol-based de-icing solutions toward biodegradable alternatives. Bristol and Farnborough concentrate defense contractor engineering talent with electromagnetic interference-hardening expertise.
China
Commercial Aircraft Corporation of China qualification criteria for exported components anticipate dual-carbon mandates from the Ministry of Ecology and Environment. Domestic narrow-body production creates captive demand for integrated flight-deck modules. Shanghai and Xi'an anchor aerospace manufacturing clusters where supplier sustainability documentation faces escalating scrutiny.
Aircraft Windshield Wiper and Washer System Market Competitive Environment
United States producers anchor one tier; European specialists hold certification depth across multiple regulatory jurisdictions. The vendor base concentrates among electromechanical actuator fabricators and integrated flight-deck system providers, with pneumatic component vendors fragmenting into aftermarket-only positions. Three archetypes dominate: tier-one avionics integrators bundling visibility management, electromechanical specialists supplying replacement kits, and legacy defense contractors with MIL-STD-461 engineering depth. Competitive moves center on flight-deck integration contracts and long-term service agreements with flag carriers.
Among United States-based corporations, Eaton Corporation and RTX Corporation exemplify the tier-one integrator archetype through electromechanical actuator and flight-deck system positioning. Safran S.A. occupies a position representing European multi-jurisdiction certification specialists sustaining aftermarket revenue through service agreements. These three anchors illustrate how supplier capability concentrates among electromechanical experts while pneumatic vendors face obsolescence pressure.
| Leading Market Players |
|---|
| Eaton Corporation |
| L3Harris Technologies |
| RTX Corporation (Collins Aerospace) |
| Meggitt PLC |
| GKN Aerospace |
| Honeywell International Inc. |
| Parker Hannifin Corporation |
| Aerosystems S.r.l. |
| Safran S.A. |
| Others |
Value Chain & Pricing Dynamics
Neodymium magnet price indices cascade through electromechanical wiper motor supply chains, compressing margins for brushless DC actuator fabricators while amplifying pricing power for rare-earth-integrated tier-one suppliers serving FAA Part 25.775 certification tiers.
Pricing Analysis
Distributor markups on electromechanical replacement kits stratify across premium MIL-STD-461 hardened variants, standard commercial aviation configurations, and economy-grade pneumatic legacy components. Price differentiation hinges on EASA CS-25 certification grade and after-sales service bundling with flag carrier MRO contracts. Cost compression in standard-tier electric wiper assemblies intensifies as Chinese magnet suppliers consolidate refining capacity. Cargo operators running aging narrow-body retrofits exhibit highest price sensitivity, while military procurement specifications tolerate premium positioning for EMI-resistant designs.
Supply Chain Analysis
Domestic-content mandates from China's Ministry of Ecology and Environment reshape sourcing patterns for COMAC qualification programs, compelling foreign suppliers to localize electromechanical actuator production. Manufacturing concentrates in the United States, Germany, and China, with neodymium magnet supply anchored in Chinese refining operations. The supply chain rests on carbon-fiber arm composites, solid-state motor controllers, and Hall-effect position sensors. Single-source vulnerability in rare-earth magnet fabrication exposes tier-two vendors to quota disruptions. Distribution runs through tier-one avionics integrators bundling wiper-washer modules with flight-deck architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EASA CS-25 delegated compliance timelines in Europe stretch 18-24 months against faster FAA Part 25.775 qualification pathways in the United States, creating cost differentials for dual-certified suppliers.
For Market Incumbents: Extend long-term service agreements with Lufthansa Technik and Delta TechOps to lock in aftermarket revenue streams against emerging electroactive polymer actuator substitutes. Deepen backward integration into neodymium magnet supply through offtake arrangements with Chinese refiners, insulating against rare-earth price volatility that threatens standard-tier margin structures. For New Entrants and Emerging Players: The premium-to-economy price gap in military aviation EMI-hardened designs offers white-space entry for qualified electrical engineers with MIL-STD-461 expertise. Target unmanned aerial system visibility modules where crewed-aircraft hydraulic infrastructure is absent, leveraging low-power electromechanical miniaturization as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with electromechanical actuator specialists possessing dual FAA-EASA certification depth and active COMAC qualification pipelines. Over a multi-year horizon, acquisition targets center on tier-two vendors with STC-approved retrofit kits for 1980s-era narrow-body fleets. Watch electroactive polymer durability validation milestones at Airbus as the inflection signal for technology substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Electroactive Polymer Qualification | Airbus validation programs accelerate 100,000-cycle durability thresholds for next-generation single-aisle platforms. |
| Long-Term Service Agreement Expansion | Lufthansa Technik performance-outcome contracts transfer design accountability upstream to tier-one integrators. |
| Dual-Carbon Compliance Investment | China MEE mandates reshape supplier qualification criteria for exported electromechanical components. |
| EMI-Hardening Talent Acquisition | MIL-STD-461 engineering scarcity concentrates competitive advantage at legacy defense contractors. |
| Predictive Maintenance Platform Integration | Sensor-embedded wiper assemblies feed health data to airline MRO software, unbundling service from hardware. |
Study Parameters
Bottom-up commercial aviation fleet modeling reconciled against top-down electromechanical actuator production tracking forms the analytical core of this study. Primary interviews with OEM procurement directors, MRO facility managers, FAA certification engineers, and tier-one avionics integrators combined with secondary validation against EASA delegated compliance framework documentation, EPA washer fluid discharge regulations, and customs trade data for rare-earth magnet flows. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Input-output matrices map electromechanical, electromagnetic, hydraulic, and vacuum technology segments across commercial aviation, military aviation, repair services, and private aviation end users, further disaggregated by OEM, aftermarket, refurbished, and custom installation channels. CAGRs derive from fleet age profiles, retrofit mandate compliance deadlines, and new aircraft delivery schedules across the projection horizon. Industry-specific forecast inputs include EASA CS-25 amendment timelines and COMAC narrow-body production ramp assumptions.
Caveats apply where neodymium supply quota disruptions, REACH chemical authorization delays, or electroactive polymer qualification failures could materially shift the outlook. Forecasts reflect documented assumptions regarding fleet retirement rates and regulatory enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Regional Jet Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
UK Aviation Market
Aircraft
Aviation Crew Management System Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Aircraft Autopilot System Market
Aircraft
North America Light and Very Light Jets Market
Aircraft
Medium and Heavy-Lift Helicopters Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Aircraft Galley Systems Market
Aircraft
Online in-Flight Shopping Market
Aircraft
Middle-East and Africa Helicopters Market
Aircraft
Military Transport Aircraft Market
Aircraft
Aircraft Strut Market