
 Static Synchronous Compensator (STATCOM) Market | 2026-2036
Static Synchronous Compensator (STATCOM) Market Size, Share, and Industry Trends Forecast 2026-2036
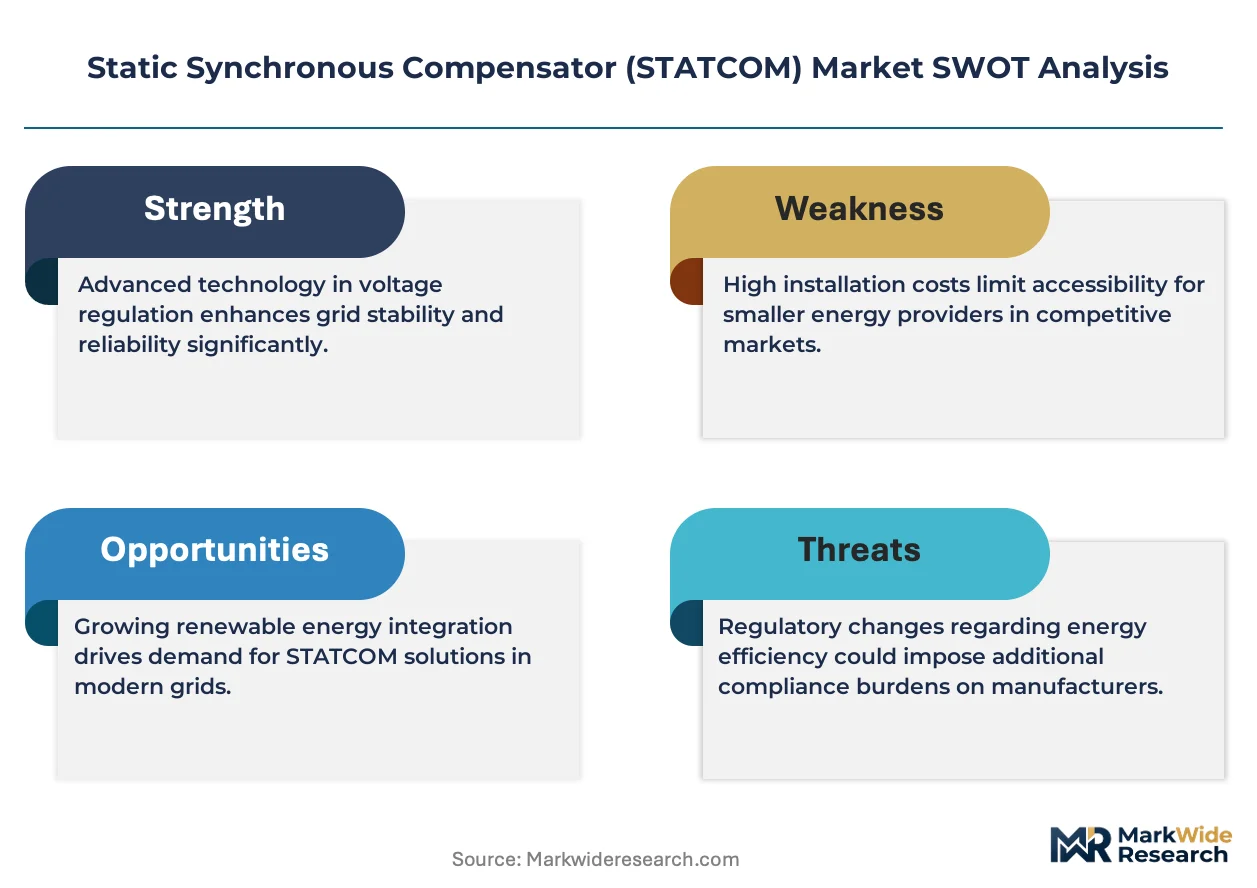
Static Synchronous Compensator (STATCOM) Market Analysis
Utility-scale renewable integration is restructuring STATCOM deployment patterns across transmission networks. Siemens Energy leverages its modular multilevel converter portfolio to anchor European offshore grid projects. GE Grid Solutions sustains manufacturing scale through in-house production of power electronic devices for North American utilities. Rongxin Power Electronic Co. dominates domestic Chinese transmission upgrades while extending controller system exports across Asia.
A static synchronous compensator is a power electronics-based shunt device employing voltage source converter topology with insulated-gate bipolar transistors to inject or absorb reactive current, maintaining grid voltage within operational limits. Modular multilevel converter architectures now lead product configurations due to superior harmonic performance and reduced switching losses. Deployment across transmission networks captures the largest margin pool, while smart grid installations represent the fastest-growing segment as digital monitoring integration expands.
FERC, the EU Green Deal framework, and India's CEA grid codes collectively mandate voltage stability compliance for renewable interconnection, directly shaping STATCOM procurement specifications. IEEE 1547 and IEC 61400-21 standards enforce reactive power capability requirements that manufacturers must satisfy for market access. Stakeholders must monitor evolving grid code harmonization between regions to anticipate certification burdens and localize supply chains accordingly.
Market Dynamics
Modular multilevel converter architectures are compressing deployment timelines for voltage stability projects while forcing incumbent manufacturers to abandon conventional two-level converter designs entirely.
Growth Catalysts
- FERC Order 2023:Grid modernization mandates in the United States require reactive power compensation at renewable interconnection points, mandating STATCOM procurement for utility-scale solar and wind farms.
- India's CEA grid codes:State-level renewable purchase obligations in Maharashtra, Gujarat, and Rajasthan compel transmission utilities to install shunt compensation devices for voltage regulation.
- Silicon carbide power modules:Wide-bandgap semiconductor adoption reduces switching losses in voltage source converters, enabling higher power density designs for offshore wind collector platforms.
Market Restraints
- Copper and rare earth magnet costs:Input price volatility in magnet materials constrains margin expansion for converter stack manufacturers serving price-sensitive Asian utilities.
- IGBT supply concentration:Power semiconductor fabrication capacity clusters in East Asian foundries, exposing project timelines to single-source dependency risks.
- Legacy thyristor SVC substitution:Existing static VAR compensator installations in mature grids delay STATCOM replacement cycles despite superior dynamic response characteristics.
Strategic Opportunities
- Brazil's ANEEL transmission auctions:Underpenetrated grid infrastructure in the Northeast region creates demand for FACTS devices to stabilize weak networks receiving remote wind generation.
- Digital twin integration:Convergence of power electronics with real-time grid simulation platforms enables predictive maintenance contracts for transmission operators.
- EU Green Deal industrial clusters:Hydrogen electrolyzer installations in Antwerp and Rotterdam require dedicated reactive power support, opening dedicated STATCOM product lines.
Industry Challenges
- Power electronics firmware specialization:Scarcity of control systems engineers with grid-forming converter experience delays commissioning schedules for complex MMC projects.
- IEC 61400-21 certification timelines:Type testing for full-scale converter platforms extends product validation cycles, compressing vendor cash conversion periods.
- Legacy SCADA protocol fragmentation:Integration with existing utility communication infrastructure requires custom gateway development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Static Synchronous Compensator (STATCOM) Market |
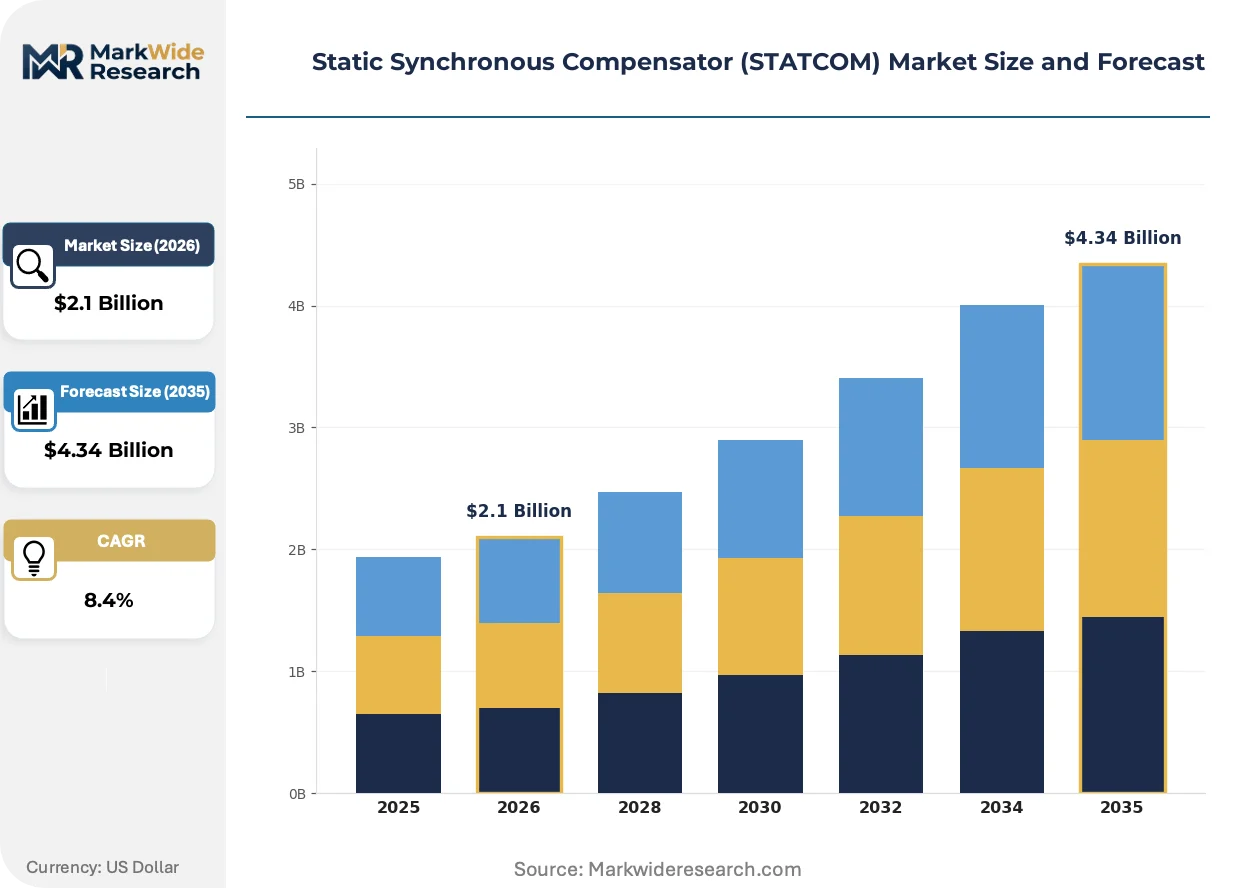
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SVC, Voltage Source Converter, Hybrid System, Modular Multilevel Converter Deployment Model: Onshore, Offshore, Smart Grid, Transmission Network End User: Utilities, Industrial Plants, Renewable Energy, Railways Technology: Power Electronic Devices, Controller Systems, Communication Network, Digital Monitoring |
| Companies Covered | GE Grid Solutions, Rongxin Power Electronic Co., Ltd., Siemens Energy, American Superconductor Corporation (AMSC), NR Electric Co., Ltd., Hitachi Energy, ABB, Hyosung Heavy Industries, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Static Synchronous Compensator (STATCOM) Market Emerging Trajectories
Converter topology evolution and grid code harmonization are compressing product development cycles while elevating software-defined control architectures above hardware-centric competitive advantages.
Silicon carbide MOSFETs is rewriting the thermal and efficiency boundaries for medium-voltage converters. Offshore wind developers in the North Sea and Baltic regions are specifying SiC-based STATCOMs for platform-based collector systems. This semiconductor transition is compressing cooling system footprints and enabling containerized substation designs that slash installation labor at remote locations.
EU F-Gas Regulation phase-down mandates are accelerating dry-air insulation adoption in medium-voltage switchgear coupled to STATCOM installations. Manufacturers must redesign converter enclosures to accommodate gas-free termination systems. German transmission operators and Scandinavian offshore developers are driving this specification change through tender requirements that exclude SF6-dependent designs.
Utility procurement departments are consolidating FACTS device sourcing through framework agreements that bundle STATCOM supply with long-term service contracts. Engineering-procurement-construction firms are displacing direct manufacturer sales in European offshore wind and Middle East transmission projects. This channel shift concentrates negotiation leverage with EPC consortia and compresses vendor direct margins across Nordic and Gulf Cooperation Council markets.
Static Synchronous Compensator (STATCOM) Market Segmentation
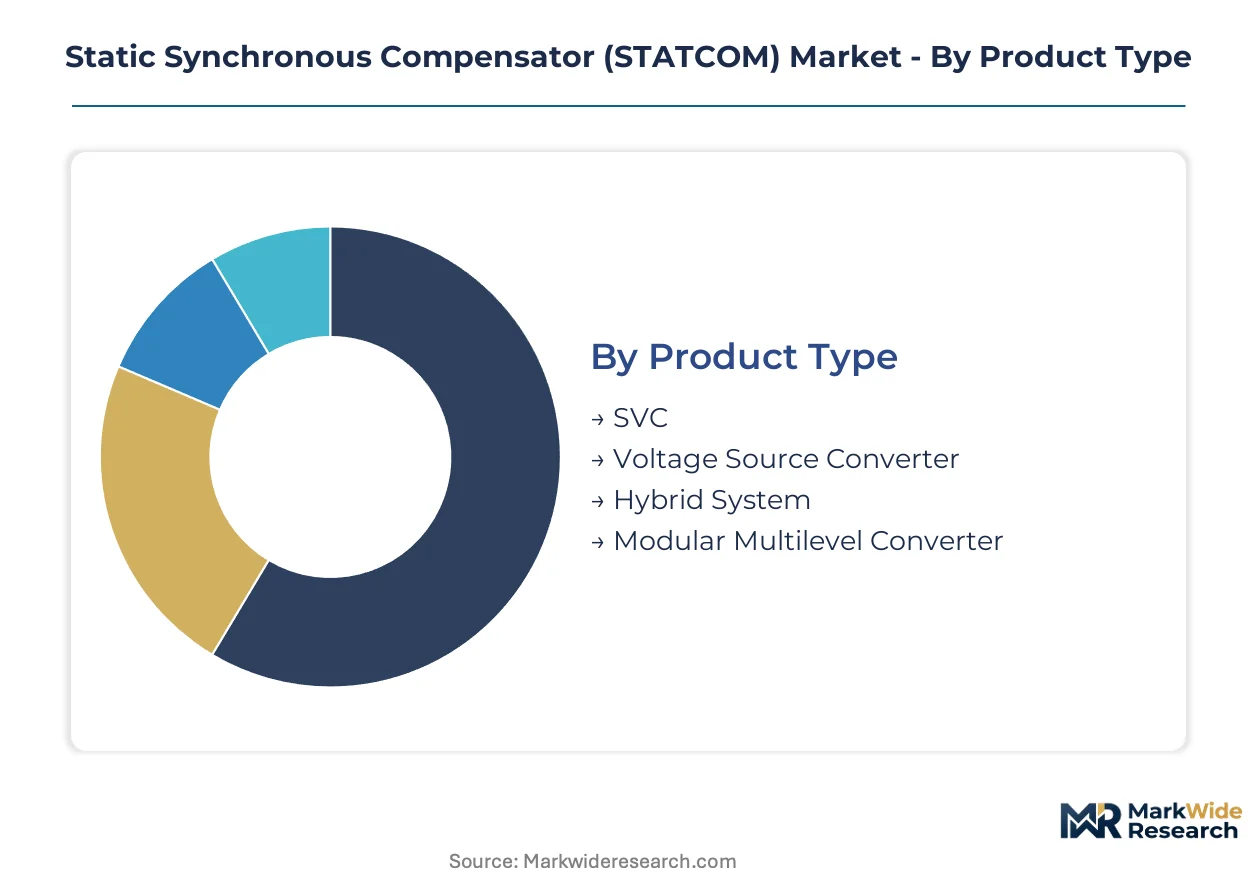
STATCOM procurement varies sharply across voltage levels, grid connection points, and semiconductor architectures. Segment boundaries determine warranty terms, commissioning complexity, and long-term service revenue potential for equipment suppliers.
Product Type:
Capital intensity escalates with converter sophistication, from legacy thyristor assemblies to multilevel semiconductor stacks.
- Modular Multilevel Converter:Stacks of series-connected submodules with distributed capacitors enable direct medium-voltage connection without step-up transformers. Siemens Energy and ABB dominate North Sea offshore tenders specifying MMC platforms for collector system voltage regulation.
- Voltage Source Converter:Two-level or three-level IGBT-based topologies with pulse-width modulation deliver rapid reactive current response for transmission grid stabilization. Indian transmission utilities under CEA mandates favor these units for renewable interconnection corridors in Rajasthan and Gujarat.
- SVC:Thyristor-controlled reactor and capacitor banks provide stepped reactive compensation at lower capital cost for legacy grid reinforcement projects.
- Hybrid System:Combined thyristor and IGBT architectures balance cost and dynamic performance for industrial voltage sag mitigation.
Most installed capacity flows through Voltage Source Converter designs. Expansion is steepest in Modular Multilevel Converter configurations.
Deployment Model:
Installation environment dictates enclosure specifications, cooling system design, and maintenance access protocols.
- Transmission Network:High-voltage substation installations at 220kV and above require outdoor converter halls with oil-immersed or dry-type transformers. Grid operators in Germany and the United States deploy these for inter-regional power flow management.
- Offshore:Platform-based collector systems demand marine-grade enclosures, active cooling, and remote diagnostics for unmanned operation. North Sea wind developers specify these for 66kV and 132kV export cable stabilization.
- Smart Grid:Distribution-level deployments with embedded sensors and two-way communication interfaces enable real-time voltage optimization.
- Onshore:Land-based renewable farm connections at 33kV to 132kV utilize containerized or building-integrated designs.
Transmission Network captures the largest project values. Smart Grid climbs the fastest as distribution operators digitize voltage control.
End User:
Procurement authority and technical specification ownership vary substantially across customer categories.
- Utilities:Transmission and distribution operators with mandated grid code compliance drive bulk procurement through framework agreements. State-owned Power Grid Corporation in India and regional transmission organizations in Texas anchor annual demand.
- Renewable Energy:Wind and solar developers face interconnection requirements that internalize STATCOM costs into project economics. Offshore wind consortia in EU member states negotiate bundled FACTS supply within EPC contracts.
- Industrial Plants:Steel mills, semiconductor fabs, and chemical complexes install dedicated units for power quality assurance.
- Railways:Traction power supply systems use STATCOMs for catenary voltage support and regenerative braking energy recovery.
Utilities command the dominant share of installed base. Renewable Energy shows the steepest expansion trajectory as project pipelines accelerate.
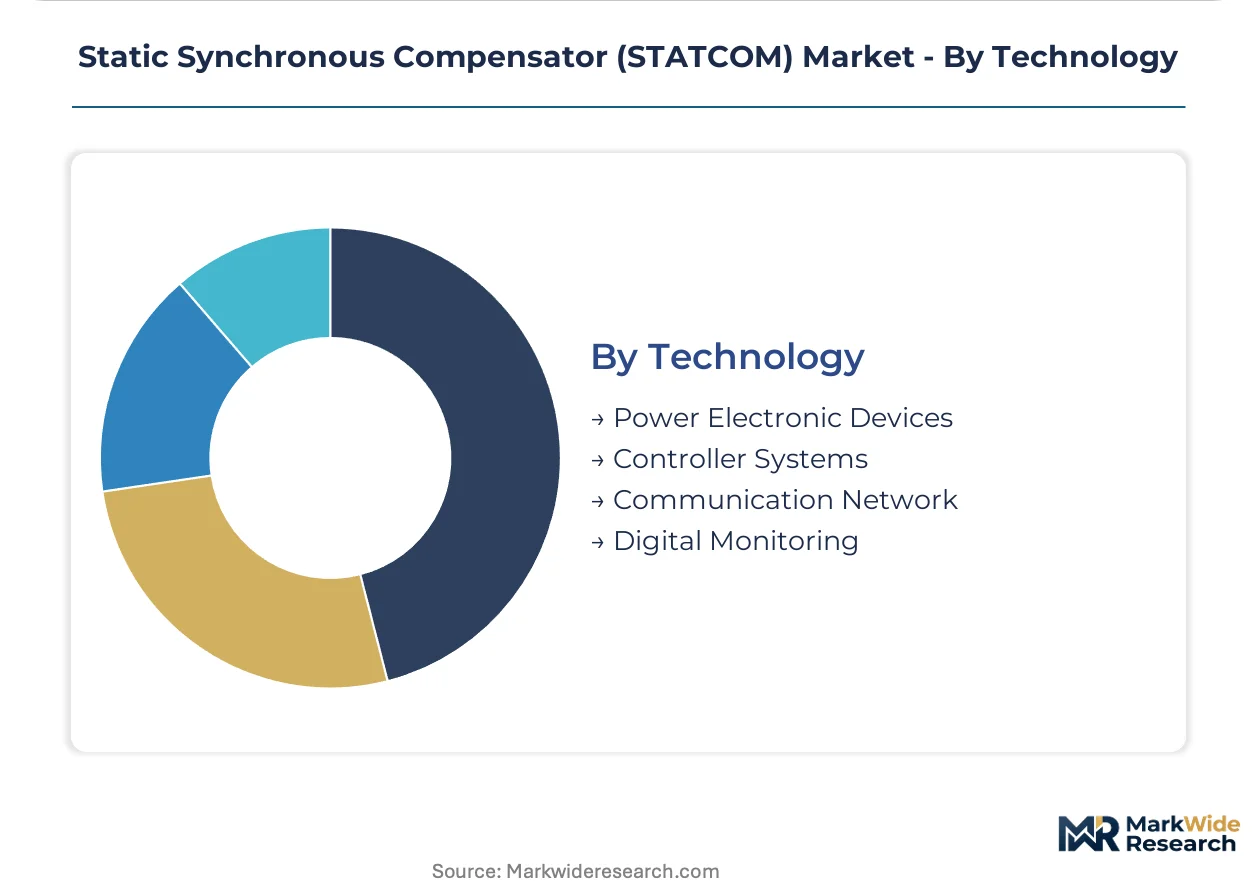
Technology:
Component-level differentiation determines thermal performance, control bandwidth, and cybersecurity posture.
- Power Electronic Devices:Silicon carbide MOSFETs and IGBT modules constitute the core switching fabric. SiC adoption is compressing cooling system footprints for offshore platform constraints.
- Controller Systems:Grid-forming algorithms and model predictive control software execute voltage regulation with sub-cycle response times.
- Digital Monitoring:Embedded phasor measurement units and edge computing platforms enable predictive maintenance and grid event logging.
- Communication Network:IEC 61850 protocol stacks and fiber-optic links integrate with utility SCADA and wide-area monitoring systems.
Power Electronic Devices absorb the greatest capital allocation. Digital Monitoring expands most quickly as operators prioritize asset visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping STATCOM procurement geography as manufacturers relocate assembly capacity to jurisdictions with streamlined grid code certification and lower compliance overhead. Cost-of-compliance gaps between mature European markets and emerging Asian economies are accelerating contract migration toward India and Southeast Asian fabrication hubs.
United States
FERC Order 2023 mandates reactive power compensation at renewable interconnection points, compelling utilities in Texas and California to procure voltage source converters for utility-scale solar farms. The Electric Reliability Council of Texas anchors demand through transmission expansion projects stabilizing weak grid corridors. ERCOT's interconnection queue backlog is forcing developers to internalize STATCOM costs into project economics ahead of regulatory deadlines.
Germany
Transmission system operators TenneT and 50Hertz specify modular multilevel converter platforms for North Sea offshore collector systems under EU Green Deal hydrogen corridor targets. The EU F-Gas Regulation phase-down is accelerating dry-air insulation adoption in converter enclosures. Industrial clusters in Hamburg and Rostock are driving tender requirements that exclude SF6-dependent switchgear designs entirely.
India
Power Grid Corporation transmission expansion and state-level renewable purchase obligations in Maharashtra, Gujarat, and Rajasthan are restructuring utility procurement patterns for voltage stability investments. Central Electricity Authority grid codes mandate shunt compensation devices for renewable interconnection corridors. Manufacturing concentration in Pune and Hyderabad is capturing domestic content requirements through localized controller system production.
China
Rongxin Power Electronic Co. dominates domestic transmission upgrades while extending controller system exports across Asia under Belt and Road infrastructure financing. State Grid Corporation voltage stability mandates for ultra-high-voltage DC links are compressing deployment timelines for MMC projects. Yangtze River Delta fabrication clusters in Shanghai and Suzhou are scaling silicon carbide module assembly for offshore wind export markets.
Brazil
ANEEL transmission auctions in the Northeast region are creating demand for FACTS devices to stabilize weak networks receiving remote wind generation from Rio Grande do Norte and Ceará. Underpenetrated grid infrastructure is forcing concessionaires to specify dynamic reactive compensation for 500kV backbone expansion. São Paulo-based engineering consortia are bundling STATCOM supply within EPC contracts for greenfield substation projects.
Static Synchronous Compensator (STATCOM) Market Vendor Landscape
Technology licensing dominates the current landscape as incumbent manufacturers access wide-bandgap semiconductor IP through cross-border partnerships rather than captive R&D. The vendor base concentrates around three strategic tiers: European integrated energy conglomerates with offshore wind project execution capabilities, Asian power electronics specialists serving price-sensitive transmission utilities, and North American grid solution providers with in-house semiconductor fabrication. Competitive positioning hinges on modular multilevel converter commissioning speed and predictive maintenance contract attach rates.
Within the integrated conglomerate tier, Siemens Energy and Hitachi Energy exemplify offshore project execution archetypes through North Sea and Baltic platform deployments. GE Grid Solutions occupies a position among North American providers with captive power electronic device production. Rongxin Power Electronic Co., Ltd. anchors the Asian specialist segment with domestic Chinese market dominance and controller system export capabilities across Southeast Asian transmission networks.
| Leading Market Players |
|---|
| GE Grid Solutions |
| Rongxin Power Electronic Co., Ltd. |
| Siemens Energy |
| American Superconductor Corporation (AMSC) |
| NR Electric Co., Ltd. |
| Hitachi Energy |
| ABB |
| Hyosung Heavy Industries |
| Mitsubishi Electric Corporation |
| Others |
Supply Flow & Price Mechanics
Copper and rare earth magnet price indices cascade through STATCOM converter stack manufacturing, compressing margins for voltage source converter producers serving price-sensitive Indian utilities while enabling premium pricing for silicon carbide-based modular multilevel converter platforms in North Sea offshore tenders.
Pricing Analysis
Direct-to-utility framework agreements compress distributor margins while elevating engineering-procurement-construction consortia negotiation leverage. Pricing stratifies across premium MMC platforms with SiC power modules, standard IGBT-based voltage source converters for transmission networks, and economy-tier thyristor SVC retrofits for legacy grid reinforcement. Price differentiation hinges on certification grade for IEC 61400-21 compliance and after-sales predictive maintenance bundling. Cost compression in standard-tier units is intensifying because of magnet material volatility and IGBT supply bottlenecks. Renewable energy developers exhibit highest price sensitivity due to project economics internalization, while German transmission operators show lowest sensitivity given EU Green Deal mandate urgency.
Supply Chain Analysis
IGBT and silicon carbide MOSFET supply rests on Japanese, German, and Chinese power semiconductor fabrication clusters, with Yangtze River Delta assembly hubs scaling module production for offshore wind export markets. Converter stack manufacturers draw from copper busbar suppliers, rare earth magnet processors, and insulated-gate bipolar transistor foundries concentrated in East Asia. Single-source vulnerability in wide-bandgap semiconductor wafer supply exposes project timelines to foundry capacity constraints. Distribution runs through EPC contractors bundling STATCOM supply within offshore wind and Middle East transmission project contracts, displacing direct manufacturer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
STATCOM procurement has shifted toward late-cycle quality specifications as grid code harmonization elevates IEC 61400-21 certification and predictive maintenance capabilities above hardware-centric bidding. Premium converter platforms with embedded digital twin integration command sustained margin premiums.
For Market Incumbents: Acquire grid-forming converter firmware engineering teams to address commissioning delays threatening MMC project timelines. Consolidate silicon carbide module supply through captive partnerships with Yangtze River Delta fabrication clusters, defending against emerging Asian power electronics specialists with backward integration into controller system production. Reinforce service contract attach rates through predictive maintenance platform deployment.
For New Entrants and Emerging Players: Enter via Brazil's ANEEL transmission auctions in the Northeast region, where underpenetrated grid infrastructure creates white-space demand for FACTS devices stabilizing weak networks receiving remote wind generation. Target digital twin integration services as the most penetrable segment, offering predictive maintenance software layers atop existing converter hardware installations. Pursue licensing partnerships with established semiconductor suppliers to bypass IGBT supply concentration barriers.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier power electronics specialists with proven MMC commissioning track records and controller system export capabilities across Asian transmission networks. Long-term viability favors vendors with software-defined control architectures and grid-forming algorithm IP. Watch FERC Order 2023 implementation velocity and EU F-Gas Regulation enforcement strictness as inflection indicators for regional demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Scale-Up | Wide-bandgap semiconductor adoption enables higher power density for offshore platform constraints. |
| Digital Twin Platform Integration | Real-time grid simulation convergence unlocks predictive maintenance contract revenue streams. |
| Grid-Forming Firmware Acquisition | Control systems engineering scarcity delays commissioning schedules for complex MMC projects. |
| SF6-Free Enclosure Redesign | EU F-Gas Regulation phase-down mandates dry-air insulation adoption in medium-voltage switchgear. |
| EPC Channel Partnership | Engineering-procurement-construction bundling concentrates negotiation leverage in Nordic and Gulf markets. |
Methodological Framework
Coverage spans the United States, Germany, India, China, and Brazil, with primary inputs from each market's transmission utilities, renewable energy developers, and power electronics manufacturers. The analysis combines structured interviews with utility planning officers, EPC contractors, grid operators, and semiconductor supply specialists with secondary validation from FERC filings, EIA project databases, CEA grid code documentation, and EU Green Deal implementation reports. Bottom-up project pipeline aggregation and top-down regulatory mandate sizing were triangulated to establish market boundaries.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in modular multilevel converter and voltage source converter segments. The analytical framework models deployment by voltage level, grid connection point, semiconductor architecture, and end-user procurement authority, with CAGRs derived from regulatory mandate timelines and renewable interconnection queue backlogs. Forecast inputs include Power Grid Corporation transmission expansion schedules, State Grid Corporation UHV DC link mandates, and ANEEL auction calendars.
The model holds under sustained grid code enforcement and rare earth magnet supply continuity; deviation in IGBT foundry capacity allocation or FERC Order 2023 implementation delays would shift regional demand trajectories. A small set of triggers—silicon carbide wafer supply expansion, EU F-Gas Regulation acceleration, and India CEA code revision cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Canada Power Market
Power
Japan Power Market
Power
Canada Thermal Power Market
Power
North America CHP Market
Power
Resonant Power Converters Market
Power
Asia-Pacific Power Market
Power
Uzbekistan Power Market
Power
Smart PV Inverters Market
Power
North America Power Market
Power
Digital Power Utility Market
Power
Sudan Power Market
Power
Modular PSA Nitrogen Generator Market
Power
Europe Solar Inverter Market
Power
Substation Automation System Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
Italy Power EPC Market