
 Canada Power Market | 2026-2036
Canada Power Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Power Market Outlook
Grid-scale renewable certification is rotating investment priorities across provincial generation fleets. Hydro-Québec leverages its existing hydropower backbone to anchor Quebec's export capacity into U.S. Northeast markets. Ontario Power Generation sustains nuclear refurbishment programs while competing in emerging small modular reactor development. TransAlta Corporation specializes in coal-to-gas transition assets and controls a growing Alberta wind portfolio.
Canada power encompasses electricity generated, transmitted, and distributed across provincially regulated grids operating at voltages from 120 V residential service to 500 kV transmission corridors, with primary purpose of supplying reliable energy to industrial, commercial, and residential end users. Hydropower retains structural dominance due to Quebec and British Columbia reservoir systems, while wind energy claims the fastest expansion trajectory across the Prairie provinces. Distributed installation models are gaining share as remote Indigenous communities and industrial mining sites pursue diesel displacement through solar-battery microgrids.
Environment and Climate Change Canada enforces the Clean Electricity Regulations capping emissions from natural gas plants, while provincial regulators including the Alberta Utilities Commission and Ontario Energy Board set integrated resource plans shaping generation mix decisions. Health Canada and PMRA oversee environmental assessments for new transmission corridors crossing federal lands. Stakeholders must monitor interprovincial transmission cost allocation disputes and the pace of federal investment tax credit disbursement for storage and non-emitting technologies.
Market Dynamics
Federal Clean Electricity Regulations are forcing provincial utilities to accelerate coal-to-gas and gas-to-renewables transitions while simultaneously managing nuclear refurbishment cycles and interprovincial transmission cost allocation disputes.
Growth Catalysts
- Clean Electricity Regulations:Environment and Climate Change Canada's emission caps on natural gas plants are redirecting capital toward wind and solar procurement across Alberta and Saskatchewan.
- Industrial electrification:Quebec's aluminum smelters and Ontario's automotive battery manufacturing are expanding firm electricity demand, anchoring long-term power purchase agreements.
- Small modular reactors:Ontario Power Generation's deployment timeline is creating regulatory precedent and supply chain localization incentives for next-generation nuclear.
Market Restraints
- Copper and rare earth supply concentration:Transmission cable and permanent magnet wind turbine sourcing depends on concentrated overseas processing capacity, exposing project timelines to geopolitical friction.
- Interprovincial transmission cost allocation:Disputes between provincial crown corporations over who bears corridor expansion costs stall cross-border renewable integration.
- Seasonal storage limitations:Lithium-ion battery duration caps at 4-6 hours, leaving winter peak demand gaps unaddressed in jurisdictions without hydro reservoirs.
Strategic Opportunities
- Northern Indigenous microgrids:Remote communities across Nunavut and Northwest Territories are displacing diesel through solar-battery hybrid installations with federal infrastructure funding.
- Carbon capture retrofits:Alberta's natural gas fleet can extend asset life through CCUS integration, qualifying for investment tax credits under federal clean technology incentives.
- U.S. Northeast export corridors:Hydro-Québec's transmission interties to New York and New England markets command capacity value premiums during regional peak events.
Industry Challenges
- Grid interconnection queues:Project developers face multi-year waits for Alberta Utilities Commission and Ontario Energy Board transmission access studies, compressing project returns.
- Nuclear operator certification pipelines:Refurbishment programs at Bruce Power and Candu Energy require specialized welding and reactor physics expertise that training institutions cannot replenish at replacement rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Power Market |
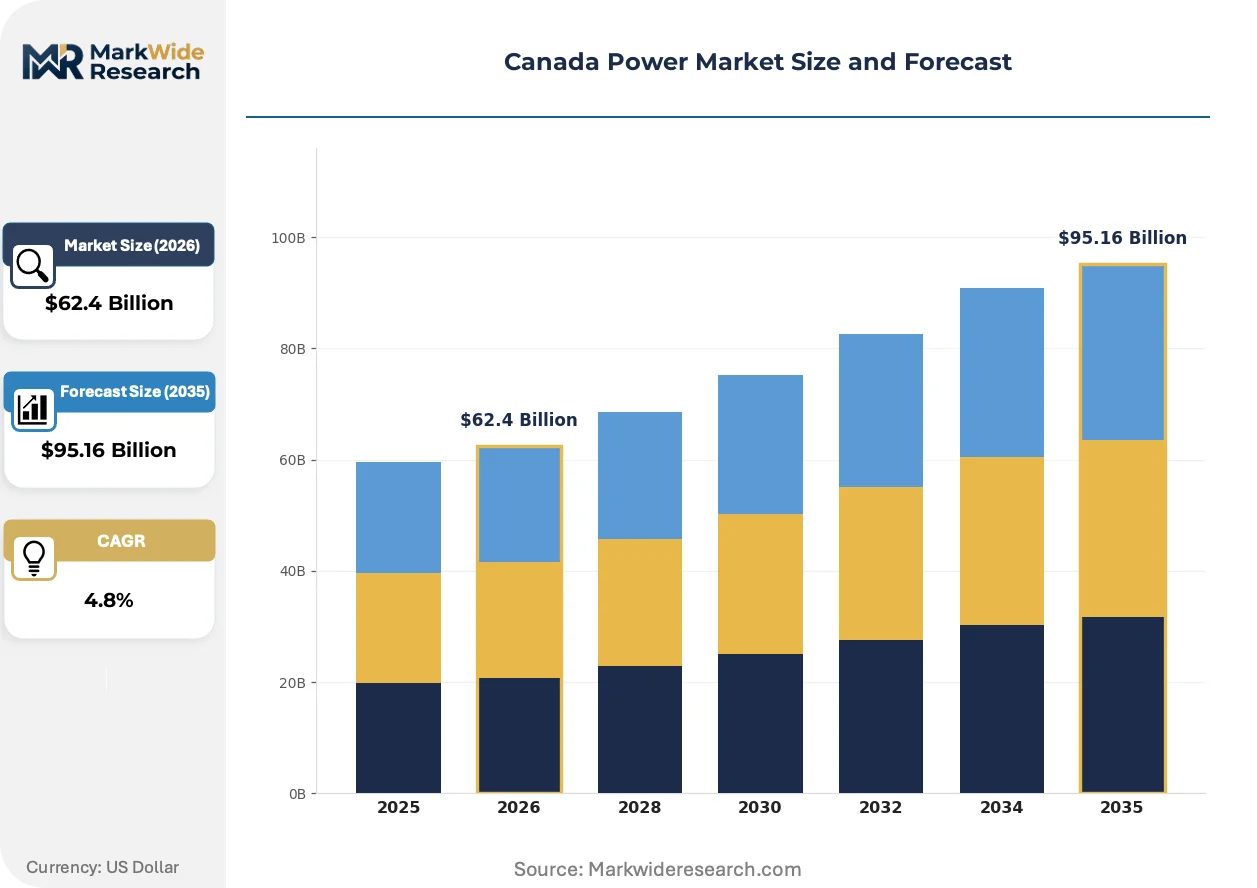
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $95.16 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hydropower, Wind Energy, Solar Energy, Biomass End User: Residential, Commercial, Industrial, Utility Installation: Onshore, Offshore, Distributed, Centralized Technology: PV, CSP, Geothermal, Fuel Cell |
| Companies Covered | Hydro-Québec, Ontario Power Generation, Hydro One Ltd., BC Hydro, Manitoba Hydro, SaskPower, Brookfield Renewable Partners, TransAlta Corporation, Capital Power Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Power Market Strategic Shifts
Technology deployment patterns across Canada's provincial grids are diverging between established hydro-nuclear baseload jurisdictions and fossil-dependent regions pursuing rapid renewable substitution.
Grid-scale battery storage is bifurcating project economics between short-duration frequency regulation services and emerging multi-day hydrogen-linked seasonal storage pilots. Alberta wind developers are pairing 4-hour lithium systems with new interconnection requests to firm output profiles. This technology trajectory is compressing merchant gas plant capacity factors while creating parallel procurement tracks for transmission-scale versus distribution-connected assets.
Environment and Climate Change Canada's Clean Electricity Regulations are mandating emission intensity caps that phase in through 2035, forcing provincial integrated resource plans to exclude unabated natural gas from new build scenarios. The Alberta Utilities Commission has responded by accelerating renewable request-for-proposal timelines while delaying gas plant approval decisions pending carbon capture feasibility studies. Ontario's approach differs, emphasizing nuclear life extension and small modular reactor development within its regulated rate-base framework.
Industrial offtake contracting is consolidating procurement authority under sustainability-linked corporate power purchase agreements. Mining operations in northern Quebec and British Columbia are bypassing traditional utility tariffs to contract directly with renewable developers, locking in fixed-price electrons against volatile diesel and grid tariff exposure. This channel shift is most visible in the aluminum and critical minerals processing verticals, where Scope 3 emission accounting pressures are reshaping supplier selection criteria.
Canada Power Market Segmentation
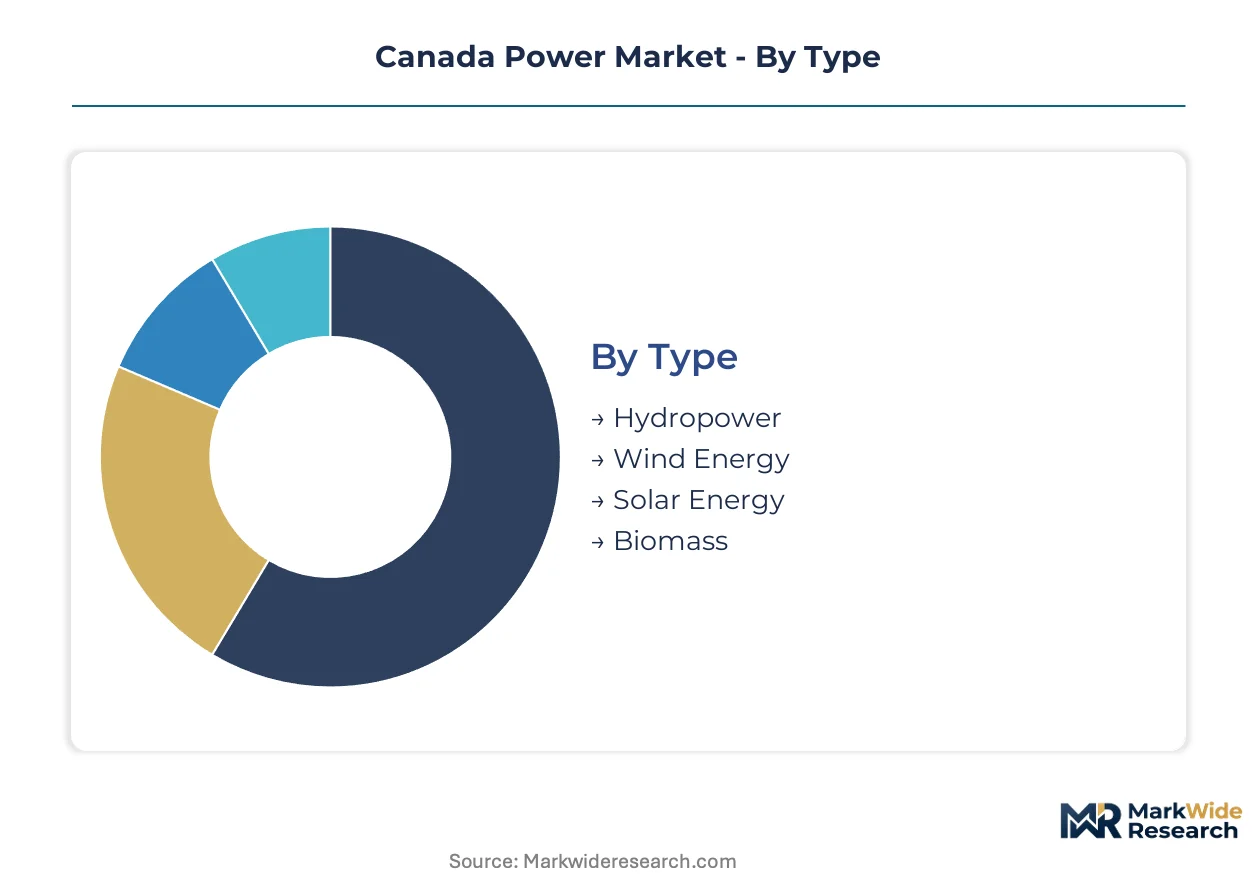
Segmentation reveals how provincial resource endowments and federal emission regulations are reallocating capital across generation technologies and customer classes. Understanding these divisions exposes where substitution pressure is most acute and which contract structures are capturing long-term offtake.
Type:
Hydropower faces intensifying substitution pressure from wind and solar as Clean Electricity Regulations tighten emission standards and procurement auctions favor new-build renewables over reservoir expansion.
- Hydropower:Reservoir and run-of-river systems dominate Quebec and British Columbia generation fleets with dispatchable capacity and multi-day storage. Quebec's aluminum smelters and export contracts to New England anchor firm demand despite limited new site availability.
- Wind Energy:Prairie provinces host the steepest capacity expansion through grid-scale procurement auctions and corporate power purchase agreements. Alberta's Alberta Utilities Commission has accelerated renewable request-for-proposal timelines while coal phase-out deadlines compress project development cycles.
- Solar Energy:Ontario's manufacturing belt and distributed Indigenous microgrids drive photovoltaic deployment with federal investment tax credit support.
- Biomass:Forest residue and agricultural waste-to-energy facilities concentrate in British Columbia and Atlantic provinces with localized feedstock supply chains.
Hydropower anchors the volume base while wind energy gains share at the steepest rate.
End User:
Cost tier differentiation separates price-sensitive residential ratepayers from industrial offtakers seeking fixed-price contracts against volatile grid tariffs.
- Residential:Provincial crown corporations and regulated utilities distribute electricity through standardized tariff structures with seasonal rate variations. British Columbia Hydro and Hydro-Québec maintain vertically integrated supply chains that buffer end users from wholesale price volatility.
- Industrial:Aluminum smelters, automotive battery manufacturers, and critical minerals processors pursue direct renewable contracting to secure Scope 3 emission reductions. Quebec's industrial corridor hosts the densest concentration of sustainability-linked corporate power purchase agreements.
- Commercial:Office and retail loads concentrate in Ontario's Golden Horseshoe and Vancouver's metropolitan core with growing rooftop solar adoption.
- Utility:Provincial integrated resource plans determine procurement authority with Ontario Power Generation and SaskPower managing diversified generation portfolios.
Industrial offtake commands the premium contract tier while residential volumes stabilize rate-base recovery.
Installation:
Geographic deployment patterns split between transmission-scale assets in renewable-rich regions and distributed systems serving remote or behind-the-meter applications.
- Onshore:Wind and solar farms across Alberta and Saskatchewan connect to 240 kV and 500 kV transmission corridors with Alberta Utilities Commission interconnection queue management.
- Offshore:Atlantic Canada holds nascent floating wind potential with Nova Scotia and Newfoundland coastal zones under federal environmental assessment.
- Distributed:Solar-battery microgrids displace diesel in Nunavut and Northwest Territories Indigenous communities with federal infrastructure funding.
- Centralized:Nuclear refurbishment at Bruce Power and new small modular reactor development operate within Ontario's regulated rate-base framework.
Centralized assets retain dispatch authority while distributed installations expand most quickly in remote geographies.
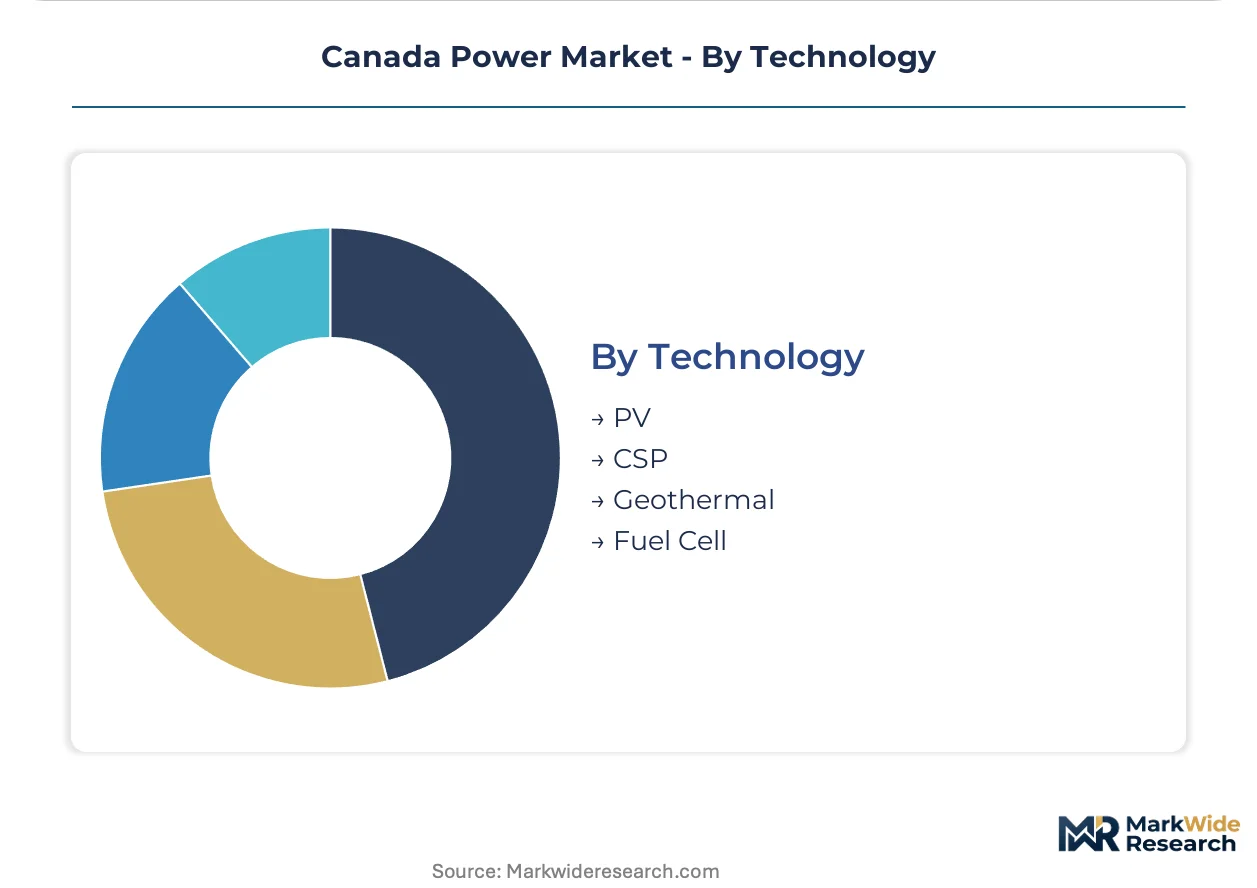
Technology:
Maturity curves separate proven photovoltaic deployment from emerging technologies seeking demonstration-scale validation and supply chain localization.
- PV:Crystalline silicon modules dominate utility-scale and rooftop installations with declining capital costs and established Ontario and Alberta installer networks.
- CSP:Concentrated solar thermal with molten salt storage remains pre-commercial in Canada given limited direct normal irradiance compared to southwestern United States reference projects.
- Geothermal:Sedimentary basin heat resources in Saskatchewan and deep drilling projects in British Columbia pursue direct-use and power generation applications.
- Fuel Cell:Hydrogen-linked stationary power and transportation applications integrate with Alberta's natural gas reforming and emerging carbon capture infrastructure.
PV anchors current deployment while fuel cell technology climbs the fastest on clean hydrogen policy alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's power trade balance tilts heavily toward exports, with Quebec and British Columbia hydro reservoirs supplying clean electrons to U.S. Northeast and Midwest markets while Ontario and Alberta remain net importers during peak winter demand periods.
Ontario
Automotive battery manufacturing in Windsor and St. Thomas anchors surging industrial electricity demand. Ontario Energy Board integrated resource plans prioritize nuclear refurbishment at Bruce Power and small modular reactor development. Toronto's financial district and Golden Horseshoe manufacturing corridor concentrate commercial load growth behind smart grid investments.
Quebec
Aluminum smelters in Saguenay-Lac-Saint-Jean and Abitibi-Témiscamingue consume firm baseload from Hydro-Québec's reservoir fleet. Clean Electricity Regulations tighten emission benchmarks for any new gas peaking capacity. Montreal's data center cluster and export interties to New York and New England markets command capacity value premiums during regional peak events.
Alberta
Coal-to-gas transition accelerates wind and solar procurement through Alberta Utilities Commission competitive auctions. Oil sands operators in Fort McMurray pursue direct renewable contracting to decarbonize extraction processes. Calgary's corporate headquarters cluster hosts sustainability-linked power purchase agreement origination for mining and energy clients.
British Columbia
Critical minerals processing in Kitimat and Prince Rupert drives transmission reinforcement along the northern coast. BC Hydro integrated resource plans balance Site C reservoir completion with distributed solar-battery microgrids for remote Indigenous communities. Vancouver's tech sector and film production studios anchor commercial demand growth with carbon-neutral procurement mandates.
Atlantic Canada
Offshore wind development in Nova Scotia and Newfoundland coastal zones advances through federal environmental assessment. Saint John's industrial port and Halifax's naval shipyard concentrate marine electrification and shore power investments. Prince Edward Island's existing wind fleet and New Brunswick's Point Lepreau nuclear station diversify the regional generation mix beyond fossil imports.
Canada Power Market Competitive Environment
Listed leaders compete with private specialists across provincial rate-base and merchant generation segments. Crown corporations dominate integrated supply chains in Quebec, British Columbia, and Manitoba while investor-owned utilities compete in Alberta's deregulated wholesale market. Three archetypes prevail: vertically integrated provincial monopolies, independent renewable developers, and integrated energy conglomerates with cross-border portfolios. Competitive moves center on interprovincial transmission access negotiations and corporate power purchase agreement origination.
Within the provincial crown corporation tier, Hydro-Québec and Ontario Power Generation exemplify rate-base regulated scale. Among independent renewable platforms, Brookfield Renewable Partners and TransAlta Corporation occupy positions spanning hydro, wind, and transition gas assets. Capital Power Corp. represents the merchant generation archetype with Alberta wind and gas fleet exposure.
| Leading Market Players |
|---|
| Hydro-Québec |
| Ontario Power Generation |
| Hydro One Ltd. |
| BC Hydro |
| Manitoba Hydro |
| SaskPower |
| Brookfield Renewable Partners |
| TransAlta Corporation |
| Capital Power Corp. |
| Others |
Value Chain & Pricing Dynamics
Environment and Climate Change Canada's Clean Electricity Regulations gate both supply qualification and price differentiation by mandating emission intensity caps that phase in through 2035, forcing provincial utilities to exclude unabated natural gas from new build scenarios while rewarding certified renewable and nuclear generation with premium contract terms.
Pricing Analysis
Industrial OEM buyers anchor long-term power purchase agreement pricing across Ontario and Quebec, where aluminum smelters and automotive battery manufacturers lock in fixed-price electrons against volatile grid tariffs. Pricing stratifies across firm baseload, interruptible industrial, and spot merchant tiers with differentiation driven by carbon intensity certification and interconnection priority rights. Cost compression in the merchant gas segment is intensifying because federal emission caps erode capacity factors for unabated plants. Residential ratepayers exhibit highest price sensitivity due to standardized provincial tariff structures, while export-oriented industrial offtakers absorb premiums for Scope 3 compliance.
Supply Chain Analysis
Copper concentrate from Chile and Peru and rare earth processing from China create chokepoint exposure for transmission cable and permanent magnet wind turbine sourcing. Canadian project developers draw from concentrated overseas processing capacity for lithium-ion cells, high-grade steel, and semiconductor power electronics. Single-source vulnerability in permanent magnet supply threatens Prairie wind expansion timelines. Distribution runs through provincial crown corporation procurement channels with Alberta's deregulated wholesale market offering parallel merchant contracting tracks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal Clean Electricity Regulations constitute a high-growth disruption as provincial integrated resource plans pivot capital toward certified non-emitting generation, creating asymmetric opportunity for early movers in nuclear refurbishment and grid-scale storage.
For Market Incumbents: Compound rate-base regulated advantages by accelerating nuclear life extension programs at Bruce Power and securing early small modular reactor site licenses before Ontario Energy Board capacity allocation rounds. Fortify positions against independent renewable developers by controlling interconnection queue priority through Alberta Utilities Commission transmission access negotiations. Vertical integration into battery storage EPC capabilities captures federal investment tax credit disbursement.
For New Entrants and Emerging Players: Anchor in northern Indigenous microgrid deployment across Nunavut and Northwest Territories, where federal infrastructure funding and diesel displacement mandates create penetrable procurement channels outside provincial crown corporation dominance. Target corporate power purchase agreement origination for critical minerals processors in British Columbia and Quebec seeking Scope 3 emission reductions. Pursue direct contracting models that bypass traditional utility tariffs.
For Investors and Strategic Acquirers: The 2035 Clean Electricity Regulations deadline reshapes the acquisition landscape by stranding unabated gas assets while elevating nuclear refurbishment and certified renewable platforms. Long-term viability favors developers with contracted offtake pipelines and interconnection secured positions. Watch Alberta Utilities Commission renewable RFP acceleration rates as the inflection signal for capital rotation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Origination | Quebec aluminum smelters and Ontario battery manufacturers lock in fixed-price baseload against volatile grid exposure. |
| Interconnection Queue Positioning | Alberta wind developers secure 240 kV and 500 kV transmission access ahead of Alberta Utilities Commission study backlogs. |
| Nuclear Life Extension Investment | Bruce Power refurbishment programs capture Ontario Energy Board rate-base recovery with decade-long revenue visibility. |
| Indigenous Microgrid Deployment | Solar-battery hybrid installations in Nunavut access federal infrastructure funding for diesel displacement mandates. |
| Carbon Capture Retrofit Integration | Alberta natural gas fleet extensions qualify for federal clean technology investment tax credits under CCUS feasibility. |
Study Parameters
Cross-validation between utility integrated resource plan filings and Environment and Climate Change Canada regulatory impact assessments anchors the qualitative findings. Primary interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators combined with secondary validation from provincial regulator databases, federal infrastructure funding disclosures, and interconnection queue records. Bottom-up project pipeline aggregation and top-down provincial demand forecasting triangulate volume estimates.
Sensitivity analysis across fuel source, generation capacity tier, and regional grid type dimensions shapes the analytical framework over the projection horizon. CAGRs derive from segmented growth rate blending across hydropower, wind, solar, and nuclear refurbishment trajectories. Forecast inputs incorporate Alberta Utilities Commission auction timelines, Ontario Energy Board rate-case schedules, and Hydro-Québec export contract renewal patterns.
Material uncertainties — federal investment tax credit disbursement pacing, interprovincial transmission cost allocation resolutions, and nuclear operator certification pipeline bottlenecks — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology cost curves. Practitioners should keep alternative scenarios live as Clean Electricity Regulations implementation details and U.S. Northeast export market conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Italy Power EPC Market
Power
Gas Freeing Fan Market
Power
Brazil Power Market
Power
Norway Power Market
Power
Electric Power Sports Market
Power
Power Sled Market
Power
United States Power Market
Power
High Voltage DC Power System Market
Power
Distribution Feeder Protection System Market
Power
Europe Submarine Power Cables Market
Power
Direct Current Power System Market
Power
Europe Microturbine Market
Power
Canada Thermal Power Market
Power
Asia-Pacific Package Substation Market
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
Nigeria Power Market