
 Air Compressor Controller Market | 2026-2036
Air Compressor Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Air Compressor Controller Market Analysis
Edge-native compressor control architectures is tilting development priorities across the supply base. Siemens AG leverages embedded AI inference to differentiate its variable-speed drive integrations. Atlas Copco anchors its portfolio through captive compressor-controller bundling that locks in aftermarket service revenue. Ingersoll Rand competes by extending its IIoT platform into predictive maintenance modules for distributed fleets.
An air compressor controller is an electromechanical or digital device that governs compressor motor operation, discharge pressure, and load/unload cycling through PID loops or model-predictive algorithms, typically managing pressures between 4 and 13 bar in industrial rotary-screw and reciprocating systems. Its primary purpose is to optimize energy consumption, prevent mechanical fault conditions, and synchronize multi-compressor installations. PLC-based architectures still dominate heavy-process installations where deterministic cycle times matter, while IoT-enabled controllers capture the fastest expansion as cloud-connected analytics reshape service contracts and remote diagnostics. Fixed-speed controllers retain volume in cost-sensitive construction and agriculture segments, though margin pools increasingly concentrate in digital and variable-speed units tied to energy-efficiency retrofits.
EU Ecodesign Directive and F-Gas Regulation constrain allowable energy intensity and refrigerant compressor configurations across European manufacturing, forcing controller vendors to embed real-time efficiency logging. In the US, Department of Energy minimum efficiency standards and OSHA compressed air safety protocols shape product certification requirements and installation liability. China's GB standards on motor efficiency and MIIT smart manufacturing mandates accelerate domestic substitution of legacy analog controllers. Stakeholders must weigh regulatory compliance roadmaps against the capital intensity of migrating installed bases to connected architectures.
Market Dynamics
Edge-native control architectures are collapsing the traditional separation between compressor hardware and intelligent management layers. This structural shift forces vendors to embed AI inference directly at the motor-drive interface, compressing margins on standalone controller sales while expanding recurring software revenue pools.
Growth Catalysts
- EU Ecodesign Directive:Mandatory real-time efficiency logging drives replacement cycles across German and Italian manufacturing facilities, accelerating procurement of connected controller platforms.
- Rotary-screw compressor retrofits:Industrial clusters in Shanghai and Shenzhen demand IoT-enabled controllers to synchronize multi-compressor installations with smart factory orchestration systems.
- Variable-speed drive technology:PID algorithm advancement enables precise pressure management between 4 and 13 bar, cutting energy waste in continuous-process chemical and food manufacturing.
Market Restraints
- Semiconductor component volatility:MCU and power transistor shortages constrain controller production timelines, particularly for embedded AI inference modules.
- Legacy analog installed base:Decades of fixed-speed compressor deployment in agriculture and construction segments create high switching costs for digital migration.
- F-Gas Regulation compliance burden:Refrigerant compressor controller configurations face mandatory redesign cycles, extending certification timelines for European market entry.
Strategic Opportunities
- India manufacturing corridors:PLI scheme incentives and BIS motor efficiency standards create procurement windows for IoT-enabled compressor management in automotive supplier parks.
- Predictive maintenance module bundling:IIoT platform convergence with vibration analytics opens service-contract expansion for distributed fleet operators.
- Cloud-connected aftermarket services:Remote diagnostics capability allows controller vendors to capture recurring revenue from compressed-air-as-a-service business models.
Industry Challenges
- Embedded systems engineering scarcity:Shortage of firmware developers with real-time control algorithm expertise constrains product roadmap velocity for edge-native architectures.
- Multi-protocol integration complexity:PLC-based heavy-process installations require deterministic cycle time guarantees that conflict with cloud-connected analytics architectures.
- OSHA compressed air safety certification:US market entry demands extensive validation of emergency shutdown logic and pressure relief integration, extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Compressor Controller Market |
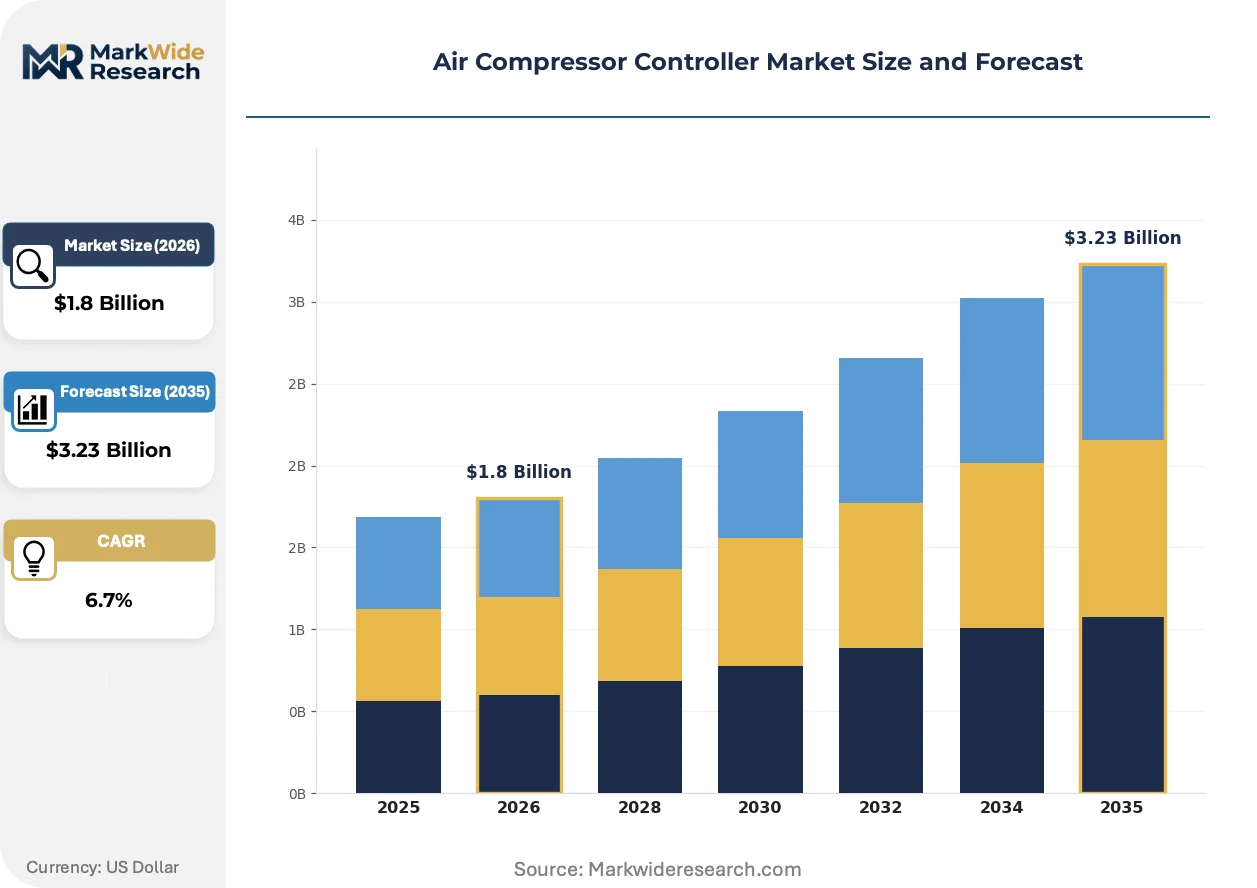
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Speed, Variable Speed, Digital, Portable Technology: PLC-Based, Microcontroller-Based, IoT-Enabled, Analog End User: Manufacturing, Construction, Automotive, Agriculture Installation: Onshore, Offshore, Mobile, Fixed |
| Companies Covered | Siemens AG, Atlas Copco, Ingersoll Rand, Schneider Electric SE, Emerson Electric, Rockwell Automation, Compressor Controls Corporation, Kaeser Compressors, Gardner Denver, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Compressor Controller Market Emerging Trajectories
Model-predictive control algorithms are displacing legacy PID loops across premium compressor installations. This algorithmic shift compresses energy consumption variance while demanding new hardware capabilities at the edge.
Embedded AI inference at the motor-drive interface is collapsing the functional boundary between variable-speed drives and standalone controllers. Automotive and electronics manufacturers in Bavaria and Baden-Württemberg deploy these integrated units to meet EU Ecodesign real-time logging mandates. The technology is compressing the addressable market for discrete controller hardware while expanding software and analytics attach rates.
F-Gas Regulation constraints on refrigerant compressor energy intensity force controller vendors to embed continuous efficiency monitoring. Industrial refrigeration OEMs redesign discharge pressure algorithms to maintain performance within tightening European Commission thresholds. Food processing and cold chain logistics facilities face the steepest compliance curves, driving controller replacement demand ahead of mechanical end-of-life.
Compressed-air-as-a-service procurement models are unbundling capital equipment from operational expenditure. Automotive tier-one suppliers in Michigan and Ohio favor subscription-based compressor management over ownership, forcing controller vendors to embed remote monitoring as standard. This shift is most visible in high-volume stamping and paint shop operations where uptime guarantees outweigh capital budget flexibility.
Air Compressor Controller Market Segmentation
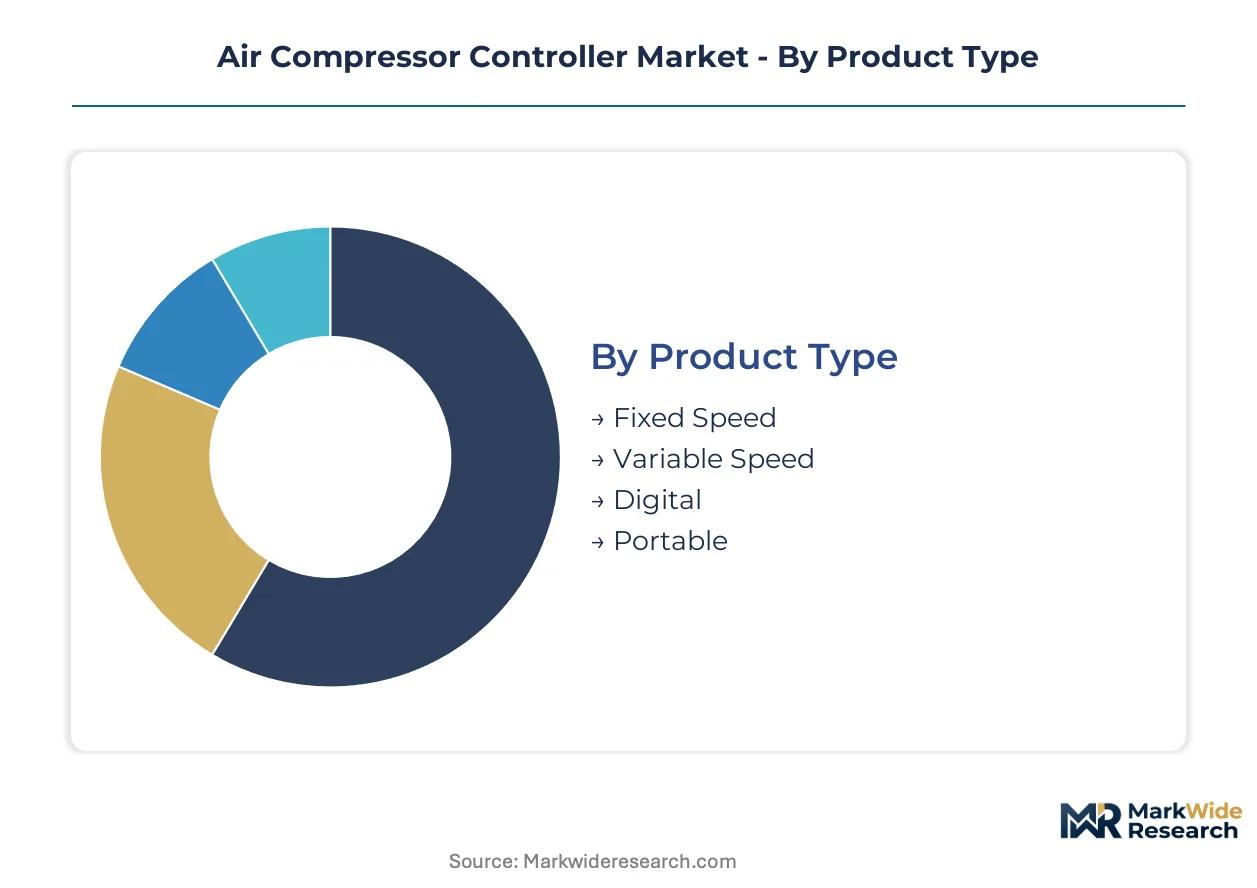
Controller segmentation reveals divergent margin pools across hardware architectures and connectivity tiers. Procurement patterns cluster around energy-efficiency mandates in process manufacturing while cost-sensitive segments retain legacy analog systems.
Product Type:
Cost tier differentiation separates capital-intensive variable-speed platforms from maintenance-driven fixed-speed replacements.
- Variable Speed:PID algorithms manage discharge pressure between 4 and 13 bar through continuous motor modulation. Chemical manufacturers in Germany deploy these units to satisfy EU Ecodesign real-time logging mandates while cutting energy waste in continuous-process environments.
- Digital:Embedded AI inference at the motor-drive interface collapses hardware boundaries while expanding software attach rates. Smart factory integration in Shanghai and Shenzhen industrial clusters drives procurement of cloud-connected analytics modules.
- Fixed Speed:Legacy relay-logic architectures dominate agriculture and construction where switching costs delay digital migration.
- Portable:Compact units serve mobile service fleets and temporary job sites with reduced feature sets.
Fixed Speed commands the established base. The steepest expansion runs through Digital.
Technology:
Application requirements dictate architecture selection between deterministic heavy-process systems and analytics-oriented connected platforms.
- IoT-Enabled:Cloud-connected controllers reshape service contracts through remote diagnostics and predictive maintenance bundling. Compressed-air-as-a-service procurement models in Michigan and Ohio automotive stamping operations embed these units as standard.
- PLC-Based:Deterministic cycle-time guarantees anchor heavy-process installations where safety interlocks and emergency shutdown logic demand hard-real-time performance. OSHA certification requirements extend validation timelines for US market entry.
- Microcontroller-Based:Mid-tier integrations balance cost and programmability for standalone compressor OEMs.
- Analog:Decades of installed base in cost-sensitive segments create persistent replacement demand.
PLC-Based retains process-industry dominance. IoT-Enabled climbs the fastest as subscription revenue models mature.
End User:
Volume concentration varies sharply across customer types with divergent uptime requirements and capital flexibility.
- Manufacturing:Multi-compressor synchronization demands dominate procurement specifications. Food processing and cold chain logistics facilities face steep F-Gas Regulation compliance curves that accelerate controller replacement ahead of mechanical end-of-life.
- Automotive:Tier-one suppliers favor uptime guarantees over capital budget flexibility, driving compressed-air-as-a-service adoption in paint shop and stamping operations.
- Construction:Price-sensitive procurement tolerates reduced functionality for mobile and temporary deployment scenarios.
- Agriculture:Legacy fixed-speed retention persists due to seasonal utilization patterns and limited maintenance infrastructure.
Manufacturing anchors revenue concentration. Automotive gains share fastest through service-contract expansion.
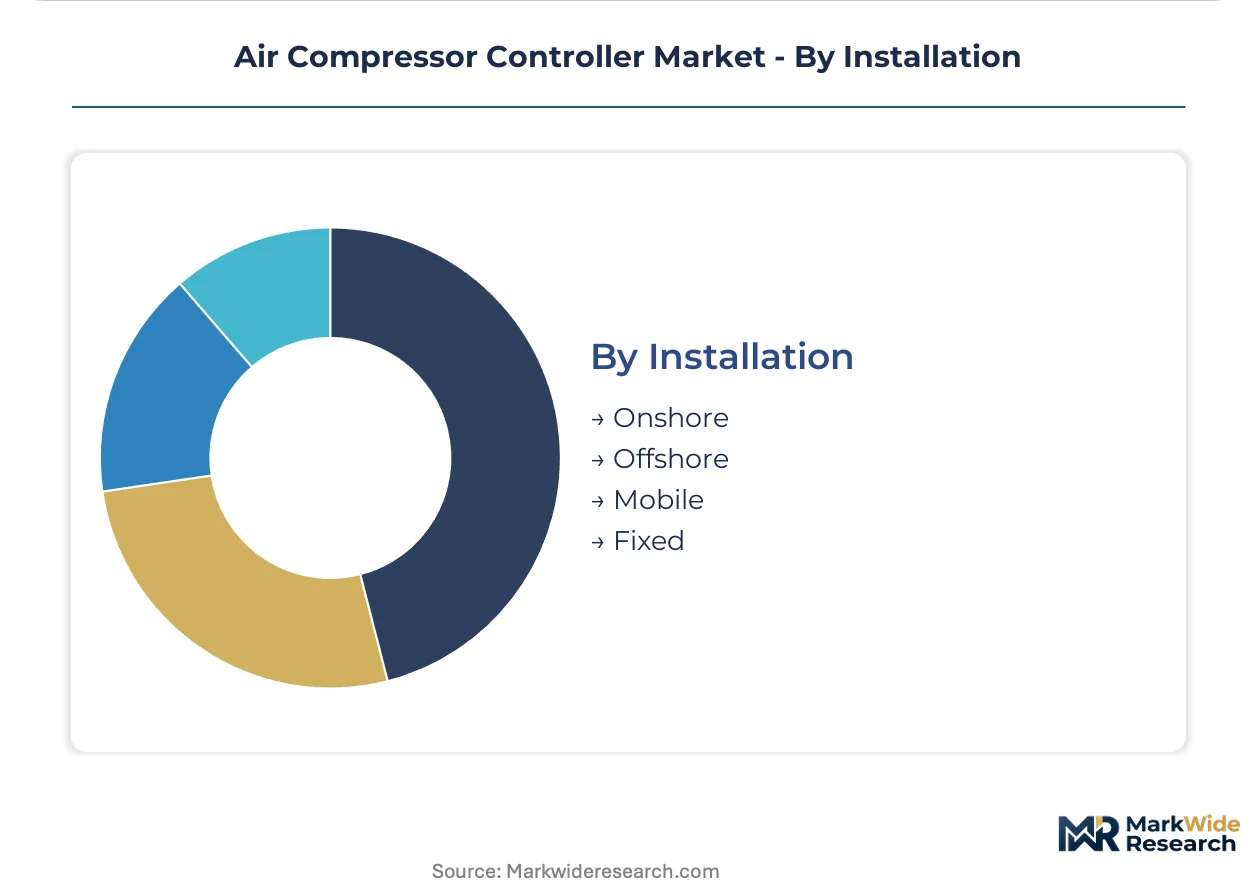
Installation:
Geography and mobility requirements segment hardware ruggedization and connectivity specifications.
- Fixed:Permanent industrial installations integrate with plant-wide SCADA and energy management systems. Bavaria and Baden-Württemberg automotive electronics manufacturers deploy edge-native architectures to meet EU Ecodesign mandates.
- Mobile:Vibration-hardened controllers serve construction and mining fleets with intermittent connectivity and harsh-environment tolerance.
- Onshore:Standard industrial specifications apply to grounded manufacturing and process facilities.
- Offshore:Corrosion-resistant enclosures and redundant safety systems address platform and marine deployment constraints.
Fixed installation commands the established base. Mobile climbs the fastest as fleet telematics integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export intelligent compressor management systems to industrial clusters across Italy and France, while Chinese producers supply IoT-enabled controllers to Southeast Asian smart factory projects.
United States
Automotive tier-one suppliers in Michigan and Ohio drive compressed-air-as-a-service procurement. OSHA safety protocols mandate extensive validation of emergency shutdown logic. Stamping and paint shop operations embed remote monitoring as standard uptime guarantees.
Germany
Bavaria and Baden-Württemberg automotive electronics manufacturers deploy edge-native architectures. EU Ecodesign Directive mandates real-time efficiency logging. Manufacturing facilities accelerate replacement cycles to comply with tightening energy intensity thresholds.
China
Industrial clusters around Shanghai and Shenzhen demand IoT-enabled controllers for smart factory integration. MIIT smart manufacturing mandates accelerate domestic substitution of legacy analog systems. Multi-compressor synchronization specifications dominate procurement.
India
Automotive supplier parks in Maharashtra and Tamil Nadu create procurement windows for connected compressor management. PLI scheme incentives and BIS motor efficiency standards reshape vendor selection criteria. Manufacturing corridors favor subscription-based service models over capital ownership.
Italy
Food processing facilities face steep F-Gas Regulation compliance curves. EU Ecodesign real-time logging requirements accelerate controller replacement ahead of mechanical end-of-life. Cold chain logistics operators in Lombardy and Emilia-Romagna prioritize energy-efficiency retrofits.
Air Compressor Controller Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers. Diversified industrial conglomerates anchor premium positioning through captive hardware-software bundling. Specialized compressor OEMs defend aftermarket revenue through controller lock-in. Pure-play automation vendors compete on protocol flexibility and edge-native architectures. Dominant competitive moves include vertical integration into motor-drive manufacturing and strategic partnerships with cloud analytics platforms.
Among diversified industrial groups, Siemens AG, Atlas Copco, and Ingersoll Rand exemplify contrasting archetypes. Siemens AG represents the automation-led path with embedded AI inference capabilities. Atlas Copco occupies a position defined by captive compressor-controller bundling that secures recurring service revenue. Ingersoll Rand sits within the IIoT platform expansion archetype, converging controller hardware with predictive maintenance software for distributed fleet operators.
| Leading Market Players |
|---|
| Siemens AG |
| Atlas Copco |
| Ingersoll Rand |
| Schneider Electric SE |
| Emerson Electric |
| Rockwell Automation |
| Compressor Controls Corporation |
| Kaeser Compressors |
| Gardner Denver |
| Others |
Supply Flow & Price Mechanics
MCU and power transistor manufacturing concentration in Taiwan and South Korea directly determines margin distribution across controller tiers, with embedded AI inference modules commanding premium positioning while analog fixed-speed units face cost compression from commoditized relay-logic components.
Pricing Analysis
Next-generation edge-native architectures with embedded AI inference carry 40-60% premiums over prior-generation PID-based digital controllers, while legacy analog fixed-speed units face sustained price erosion. Three-tier pricing structure across premium IoT-enabled, standard digital, and economy analog levels reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from semiconductor component volatility constraining production timelines for advanced modules. Construction and agriculture segments exhibit highest price sensitivity, while automotive tier-one suppliers prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for tier-one compressor OEMs sourcing from Taiwanese MCU suppliers and German power electronics manufacturers. Controller production draws from semiconductor fabrication in Taiwan and South Korea, power transistor assembly in Germany and China, and enclosure manufacturing in Mexico and Vietnam. Single-source vulnerability around automotive-grade AI inference chips creates supply chain risk. Distribution runs through captive OEM channels, industrial automation distributors, and direct-to-plant procurement for large manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among automotive tier-one suppliers and smart factory operators in China, compressing margins for standalone controller vendors while expanding software and service revenue pools.
For Market Incumbents: Build switching-cost moats through captive compressor-controller bundling and predictive maintenance module lock-in. Siemens AG and Atlas Copco exemplify this path by embedding remote diagnostics as standard to defend against pure-play automation entrants. Vertical integration into motor-drive manufacturing secures supply continuity amid semiconductor volatility. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized automotive supplier parks where BIS motor efficiency standards are reshaping vendor selection. Target agriculture and construction segments with cost-optimized digital controllers that bridge the legacy analog installed base. Partner with local system integrators for compressed-air-as-a-service deployment to bypass captive OEM channel control. For Investors and Strategic Acquirers: Capital is best deployed toward edge-native automation specialists with firmware capabilities in real-time control algorithms and multi-protocol integration. Long-term viability hinges on software attach rates and recurring service contract expansion rather than discrete hardware margins. Watch for MIIT smart manufacturing mandate acceleration in China as inflection signal for domestic substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded AI Inference Integration | Siemens AG collapses hardware boundaries while expanding software revenue pools at the motor-drive interface. |
| Predictive Maintenance Module Launch | Ingersoll Rand converges IIoT platforms with vibration analytics for distributed fleet operators. |
| Backward Integration into Power Electronics | Atlas Copco secures captive supply of variable-speed drive components amid semiconductor constraints. |
| Compressed-Air-as-a-Service Partnership | Automotive tier-one suppliers in Michigan embed remote monitoring as standard uptime guarantee. |
| EU Ecodesign Compliance Certification | German manufacturers accelerate replacement cycles to meet real-time efficiency logging mandates. |
Methodological Framework
Operator-level perspectives from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation from customs/trade data, SEC 10-K filings, and MIIT smart manufacturing disclosures. Bottom-up unit economics triangulated against top-down market sizing across controller architecture tiers.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user industry, and installation mobility. CAGRs derived from historical trajectory analysis adjusted for regulatory mandate timing and technology substitution curves. Forecast inputs incorporated EU Ecodesign Directive compliance deadlines and China MIIT smart manufacturing substitution rates.
Sensitivities concentrate around semiconductor supply continuity and regulatory enforcement variance. Forecasts reflect documented assumptions on technology adoption curves and buyer consolidation patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Asia-Pacific Peristaltic Pumps Market
Pumps and Control Devices
Europe Positive Displacement Pumps Market
Pumps and Control Devices
Hydrogen Circulation Pump Market
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
Southeast Asia Industrial Pumps Market
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
In Pipe Hydro Systems Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Global Variable Displacement Pumps Market
Pumps and Control Devices
Asia-Pacific Cryogenic Pump Market
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Mist Sprayer Pumps Market
Pumps and Control Devices
Axial and Mixed Flow Pumps Market