
 Digital Power Utility Market | 2026-2036
Digital Power Utility Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Power Utility Market Analysis
Utility procurement channels is reconfiguring as state-backed grid modernization programs consolidate vendor relationships around platform providers. General Electric Company leverages its turbine-to-grid software stack to anchor long-term service contracts with North American utilities. Siemens AG competes through its hardware-integrated digital twin architecture for substation automation. Schneider Electric SE dominates distribution management deployments across European municipal networks.
Digital power utility denotes the integration of information technology, operational technology, and advanced analytics into electricity generation, transmission, and distribution systems to enable real-time monitoring, predictive control, and automated response across grid assets. SCADA systems form the operational backbone by collecting telemetry from remote terminal units at millisecond intervals to maintain voltage stability and fault isolation. IoT Solutions within Advanced Metering Infrastructure command the fastest expansion as utilities replace electromechanical meters with two-way communicating endpoints that support time-of-use pricing and distributed energy resource coordination. Big Data Analytics applied to load forecasting extracts margin pools by reducing spinning reserve requirements and improving day-ahead market bidding accuracy.
FERC Order 2222 in the United States compels regional transmission organizations to accommodate aggregated distributed energy resources, directly expanding addressable demand for grid-edge software platforms. The EU Green Deal and GDPR together shape procurement by mandating carbon disclosure across supply chains while restricting cross-border data flows from smart metering systems. Stakeholders must weigh interoperability standards against cybersecurity certification timelines when selecting technology partners for multi-decade infrastructure commitments.
Market Dynamics
Grid-edge software platforms are consolidating procurement decisions as utilities abandon point solutions in favor of integrated operational technology stacks spanning generation control through distribution management.
Growth Catalysts
- FERC Order 2222:The United States mandate compels regional transmission organizations to integrate aggregated distributed energy resources, expanding addressable demand for distributed energy resource management systems across independent system operators.
- Advanced Metering Infrastructure:Municipal utilities in Germany are replacing electromechanical meters with two-way communicating endpoints that enable time-of-use pricing and real-time load balancing across low-voltage networks.
- EU F-Gas Regulation:The phasedown of sulfur hexafluoride in switchgear accelerates investment in digital monitoring systems for alternative insulation technologies across European transmission networks.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries control critical manufacturing capacity for power electronics and communications chipsets essential to remote terminal units, exposing grid automation timelines to geopolitical disruption.
- Cybersecurity certification friction:IEC 62443 compliance timelines extend vendor qualification periods to 18-24 months, delaying deployment of substation automation platforms.
- Copper and rare earth price volatility:Permanent magnet materials for transformer monitoring sensors and cabling infrastructure face input cost swings that compress equipment margins.
Strategic Opportunities
- Virtual power plant aggregation:Germany's regulatory framework for aggregated behind-the-meter assets creates white space for software platforms coordinating battery storage, EV chargers, and rooftop solar across distribution system operator territories.
- Digital twin convergence:Integration of physics-based simulation with real-time SCADA telemetry enables predictive maintenance for high-voltage transformers, reducing unplanned outage costs for transmission operators.
- China's dual carbon goals:Provincial grid companies face mandatory renewable integration targets that drive procurement of forecasting analytics and automated dispatch systems.
Industry Challenges
- OT-IT integration complexity:Utilities struggle to merge legacy SCADA protocols with cloud-native analytics platforms, requiring specialized systems integrators and extended commissioning periods.
- Cybersecurity workforce scarcity:Shortages of industrial control system security engineers delay implementation of zero-trust architectures for critical infrastructure protection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Power Utility Market |
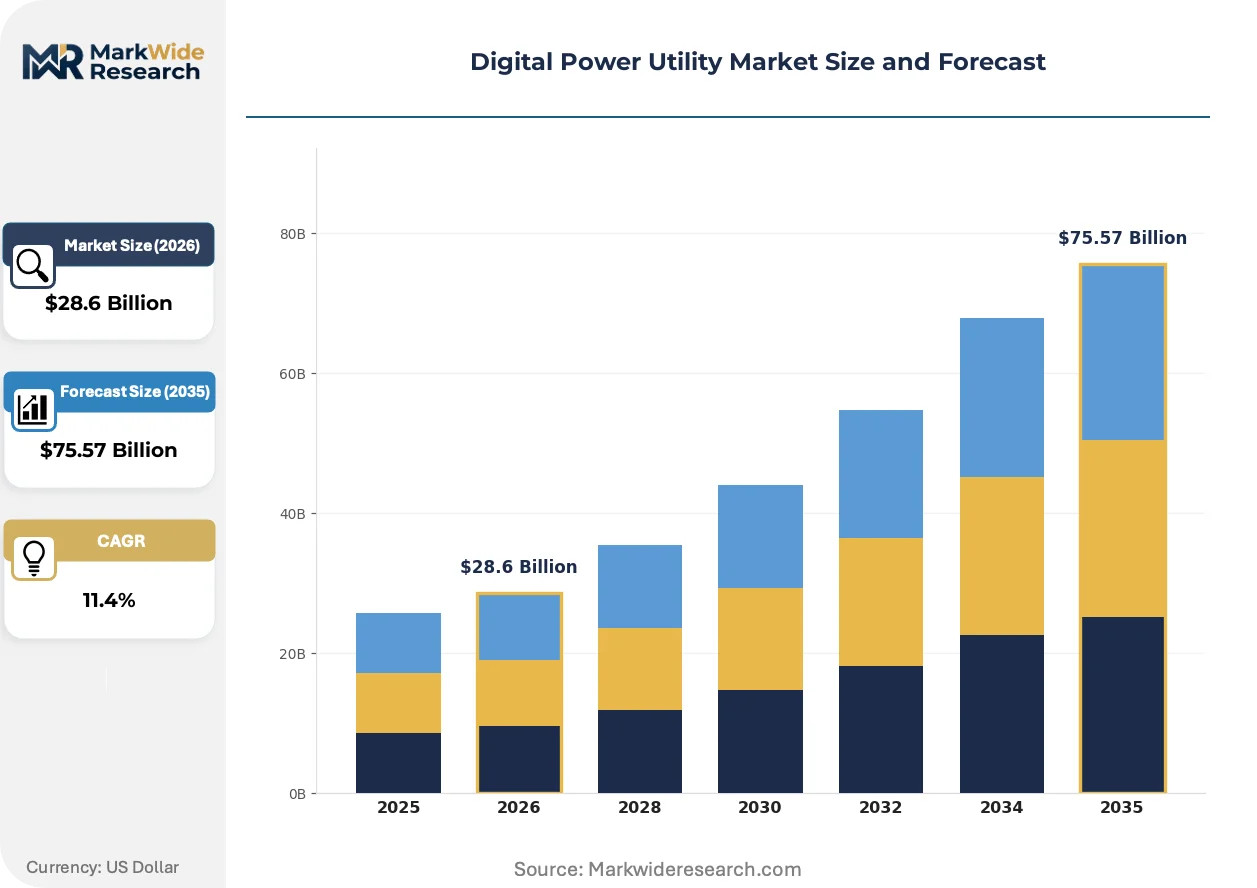
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Smart Grid, Distribution Management, Demand Response, Energy Management Technology: SCADA, IoT Solutions, Big Data Analytics, Advanced Metering Infrastructure Application: Renewable Energy Integration, Grid Automation, Load Forecasting, Outage Management End User: Utilities, Independent Power Producers, Large Enterprises, Residential Customers |
| Companies Covered | General Electric Company, Siemens AG, ABB Ltd, Accenture PLC, Capgemini SE, IBM Corporation, SAP SE, Microsoft Corporation, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Power Utility Market Emerging Trajectories
Software-defined architectures are displacing hardware-centric control systems across electricity networks, compressing upgrade cycles and shifting vendor value capture toward recurring service models.
Digital substation technology is virtualizing protection and control functions that previously required dedicated copper-wired relay cabinets. European transmission operators are deploying IEC 61850-compliant process bus architectures that reduce substation footprint by 40 percent. This virtualization is collapsing the boundary between primary equipment and software platforms, enabling remote firmware updates that extend asset lifecycles.
The EU Green Deal's carbon disclosure mandates are reshaping procurement criteria for grid infrastructure. Suppliers must now document embodied carbon across switchgear, transformers, and cable systems to qualify for municipal utility tenders. German network operators have responded by embedding lifecycle assessment tools directly into their enterprise resource planning systems, filtering vendor shortlists based on verified emissions data.
Utility buyers are consolidating vendor relationships around platform providers capable of spanning turbine control through distribution management. North American municipal utilities increasingly require single-source accountability for generation asset performance and grid-edge analytics, displacing the historical pattern of siloed procurement across transmission and distribution departments. This concentration is most visible in integrated resource planning processes across vertically organized utilities in the United States.
Digital Power Utility Market Segmentation
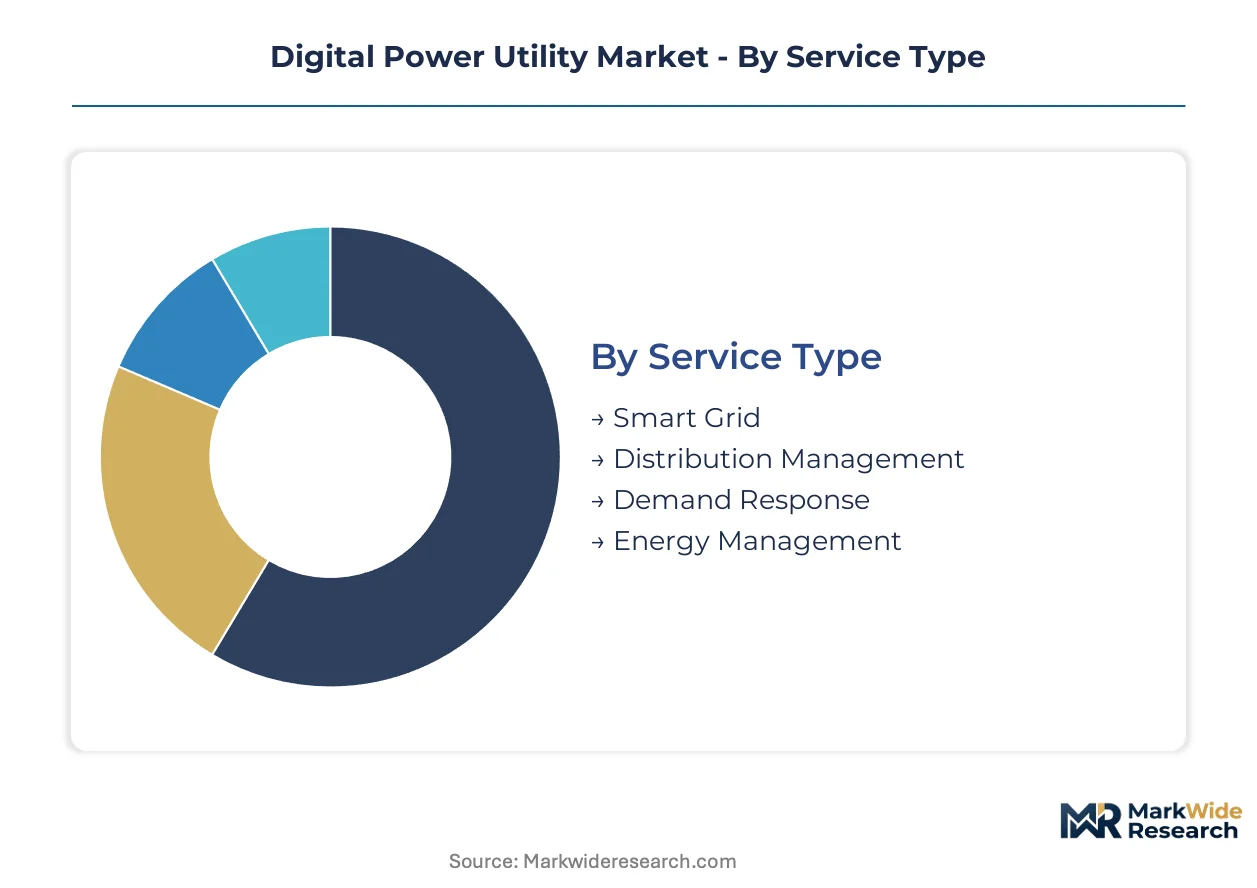
Segmentation in the digital power utility market reveals how procurement cycles, technology refresh rates, and regulatory pressures vary across service layers and customer types. Understanding these differences enables vendors to align R&D investment with replacement timelines and margin profiles.
Service Type:
Replacement cycles diverge sharply across service categories, with grid-edge platforms turning over every 3-5 years while backbone infrastructure persists for 15-20 years.
- Smart Grid:Encompasses two-way communication networks, automated switching, and real-time control systems that synchronize distributed generation with load patterns. German municipal utilities and California investor-owned utilities are consolidating procurement around integrated platforms that span transmission interconnection through distribution automation, driven by renewable integration mandates.
- Distribution Management:Deploys outage management, voltage optimization, and fault location algorithms across medium-voltage networks. Demand concentrates among European distribution system operators facing EU Green Deal carbon disclosure requirements, where lifecycle assessment tools now filter vendor selection.
- Demand Response:Aggregates controllable loads and behind-the-meter assets for grid balancing services.
- Energy Management:Optimizes consumption patterns through building-level analytics and industrial process control.
Distribution Management anchors the volume base while Smart Grid gains share at the steepest rate.
Technology:
Cost tiers separate legacy hardware-dependent systems from software-defined architectures that shift value capture toward recurring service models.
- SCADA:Forms the operational backbone through remote terminal units collecting telemetry at millisecond intervals for voltage stability and fault isolation. North American transmission operators maintain these systems on 20-year depreciation schedules, though cybersecurity retrofitting now accelerates partial upgrades.
- IoT Solutions:Deploys sensor networks and edge computing nodes across substations and distribution feeders. Advanced Metering Infrastructure deployments in Germany and China are replacing electromechanical meters with two-way communicating endpoints, expanding fastest among all technology categories.
- Big Data Analytics:Extracts predictive insights from operational data streams for load forecasting and asset health monitoring.
- Advanced Metering Infrastructure:Provides the physical endpoint layer enabling time-of-use pricing and distributed energy resource coordination.
SCADA retains the largest installed base while IoT Solutions climbs the fastest as utilities abandon point solutions for integrated operational technology stacks.
Application:
Application maturity correlates with regulatory pressure intensity, with renewable mandates forcing faster deployment than reliability-centered use cases.
- Renewable Energy Integration:Forecasts, dispatches, and stabilizes variable wind and solar output through automated control systems. China's provincial grid companies face mandatory renewable targets that drive procurement of forecasting analytics, creating concentrated demand across state-owned transmission operators.
- Grid Automation:Implements self-healing networks, automated sectionalizing, and remote-controlled switchgear. European transmission operators deploying IEC 61850-compliant process bus architectures are reducing substation footprint by 40 percent, accelerating virtualization of protection functions.
- Load Forecasting:Predicts demand patterns to optimize generation scheduling and reduce spinning reserve requirements.
- Outage Management:Triggers automated restoration sequences and crew dispatch upon fault detection.
Grid Automation anchors the volume base while Renewable Energy Integration expands most quickly under decarbonization policy pressure.
End User:
Customer type determines procurement sophistication, with regulated utilities favoring proven platforms while independent power producers prioritize speed-to-revenue.
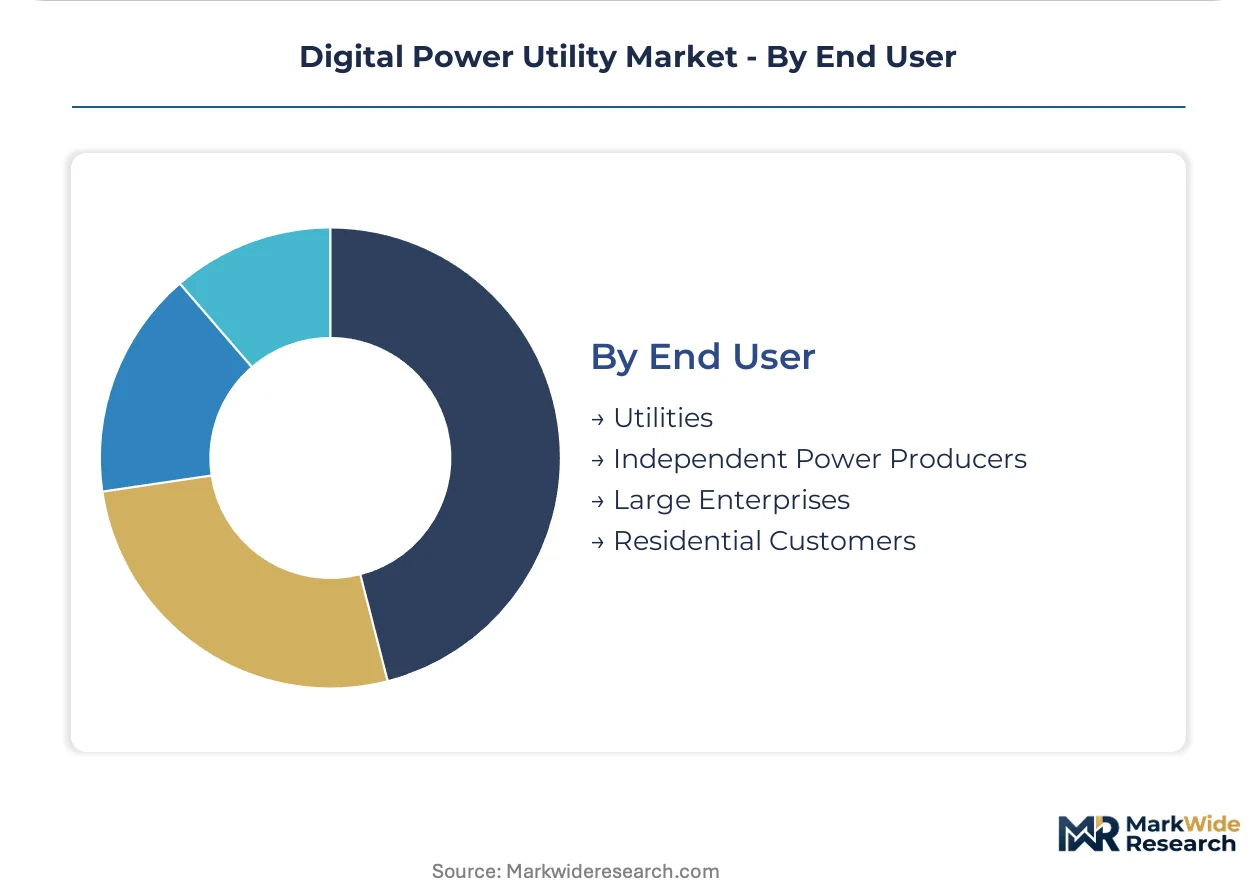
- Utilities:Vertically integrated and distribution-only operators with multi-decade infrastructure planning horizons. Municipal utilities in Germany and investor-owned utilities in the United States are consolidating vendor relationships around single-source accountability spanning generation through grid-edge analytics.
- Independent Power Producers:Own and operate generation assets selling into wholesale markets or under power purchase agreements. These entities prioritize forecasting accuracy and automated bidding systems to maximize capture prices in day-ahead markets.
- Large Enterprises:Industrial and commercial consumers managing on-site generation, storage, and demand flexibility.
- Residential Customers:Households equipped with smart meters, rooftop solar, and controllable loads participating in aggregated demand response programs.
Utilities anchor the volume base while Independent Power Producers gain share at the steepest rate as merchant generation and battery storage proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German municipal procurement while Chinese state-owned grid companies extract volume discounts through consolidated tendering. This asymmetry shapes vendor margin structures across the two largest demand centers.
United States
FERC Order 2222 compels regional transmission organizations to integrate aggregated distributed energy resources, expanding procurement of grid-edge software platforms. State-level renewable portfolio standards in California and Texas accelerate deployment of forecasting analytics. ERCOT's grid instability events drive investment in automated dispatch systems across Texas municipal utilities.
Germany
The EU F-Gas Regulation phases down sulfur hexafluoride in switchgear, accelerating digital monitoring adoption for alternative insulation technologies. Municipal utilities in Bavaria and North Rhine-Westphalia consolidate vendor relationships around single-source accountability. Berlin's distribution system operators embed lifecycle assessment tools into ERP systems, filtering suppliers by verified carbon data.
China
Provincial grid companies face mandatory renewable integration targets under dual carbon goals, driving procurement of automated dispatch systems. State Grid Corporation consolidates tenders for smart substation technology across Yangtze River Delta clusters. Shenzhen's municipal operators deploy IEC 61850-compliant process bus architectures to reduce urban substation footprints.
Japan
METI's grid modernization roadmap prioritizes digital twin deployment for aging transformer fleets. Tokyo Electric Power and Kansai Electric accelerate SCADA cybersecurity retrofits following IEC 62443 mandates. Osaka's industrial corridor concentrates demand response aggregation for manufacturing load flexibility.
Digital Power Utility Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, communications modules, and power electronics. The vendor base organizes around three archetypes: turbine-to-grid software stacks, hardware-integrated digital twin architectures, and distribution management platforms. Consolidation pressures favor integrated operational technology stacks over point solutions. Strategic moves concentrate on long-term service contract anchoring and substation automation virtualization.
Among diversified industrial conglomerates, General Electric Company and Siemens AG occupy positions spanning generation control through grid-edge analytics. Schneider Electric SE anchors the European distribution management tier. These three exemplify the platform consolidation pattern as municipal utilities abandon siloed procurement across transmission and distribution departments.
| Leading Market Players |
|---|
| General Electric Company |
| Siemens AG |
| ABB Ltd |
| Accenture PLC |
| Capgemini SE |
| IBM Corporation |
| SAP SE |
| Microsoft Corporation |
| Schneider Electric SE |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp freight corridors transmit semiconductor and rare earth cost volatility directly into substation automation equipment pricing, compressing margins for European vendors while amplifying price differentiation between configured-to-order digital twin platforms and standard SCADA hardware.
Pricing Analysis
The customization-premium spread separates IEC 61850-compliant digital substation platforms from legacy electromechanical relay systems. Project-based licensing with recurring service tiers dominates, with price differentiation driven by cybersecurity certification grade and geographic delivery complexity. Pricing pressure stems from municipal utility consolidation around single-source accountability contracts. Independent power producers exhibit highest price sensitivity; transmission operators with 20-year depreciation schedules show lowest.
Supply Chain Analysis
Tariff exposure between Taiwan and Germany dominates supply chain risk for power electronics and communications chipsets essential to remote terminal units. Manufacturing concentrates in Taiwan, China, and South Korea. Raw material dependencies include copper cabling, neodymium permanent magnets for transformer sensors, and silicon carbide substrates. Single-source vulnerability in foundry capacity threatens grid automation timelines. Distribution runs through systems integrators and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source grid-edge software stacks threaten incumbent platform providers with commoditization, forcing substitution defense through service contract anchoring and hardware-software integration depth.
For Market Incumbents: Pre-empt open-source displacement by embedding lifecycle assessment tools directly into ERP-integrated procurement workflows, tightening carbon disclosure compliance for municipal utilities. Secure long-term service contracts spanning turbine control through distribution management to lock out modular competitors. Deepen backward integration into sensor manufacturing to capture margin pools eroding at the component tier.
For New Entrants and Emerging Players: Build out virtual power plant aggregation software for Germany's distribution system operator territories, exploiting regulatory white space for behind-the-meter asset coordination. Target independent power producers in Texas ERCOT territory with forecasting analytics for merchant generation bidding. Pursue channel partnerships with European systems integrators burdened by OT-IT integration complexity.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core grid software units amid platform consolidation pressures. Five-to-ten year viability hinges on recurring revenue share exceeding project-based licensing. Monitor FERC Order 2222 implementation velocity across independent system operators as inflection signal for distributed energy resource management system demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates SCADA, IoT, and analytics into unified operational technology stacks for municipal utilities. |
| Acquisition of Specialist Firm | Captures cybersecurity certification capabilities compressed by IEC 62443 compliance timelines. |
| Long-term Service Agreement | Anchors recurring revenue through turbine-to-grid software maintenance contracts with North American utilities. |
| Geographic Expansion | Targets China's provincial grid companies facing mandatory renewable integration targets under dual carbon goals. |
| Strategic Partnership | Aligns with systems integrators to resolve OT-IT integration friction delaying substation deployments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FERC filings, EIA grid modernization databases, EU Green Deal regulatory texts, and IEC standard documentation. Utility planning officers, IPP project developers, EPC contractors, and grid operators provided operational perspectives. Bottom-up segment sizing triangulates against top-down market value reconstruction.
Forecast inputs span service type replacement cycles, technology refresh rates, and regulatory pressure intensity across the projection horizon. Segmentation dimensions include deployment architecture, utility type, and regional grid modernization policy cluster. CAGRs derive from installed base turnover analysis and procurement pipeline tracking. Load forecasting accuracy improvements and renewable integration mandates shape demand-side modeling.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud entrants would shift outcomes. Semiconductor supply disruption or accelerated F-Gas Regulation timelines could revise deployment trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Brazil Power Market
Power
Denmark Power Market
Power
Steam Turbine MRO Market
Power
Wireless Power Receiver Market
Power
Gas Freeing Fan Market
Power
Global UPS Market
Power
North America Microturbine Market
Power
Power Rental Market
Power
Asia-Pacific Power Market
Power
LNG Power Barge Market
Power
Italy Power Market
Power
Modular PSA Nitrogen Generator Market
Power
Argentina Power Market
Power
Controllable Shunt Reactor for UHV Market
Power
Nigeria Power Market
Power
Smart PV Inverters Market