
 Japan Power Market | 2026-2036
Japan Power Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Power Market Outlook
Industrial offtake from semiconductor fabs and battery gigafactories is collapsing the historical dominance of residential and commercial buyer segments in Japan's power procurement mix. Tokyo Electric Power Co Holdings, Inc. leverages its transmission network density to anchor premium industrial contracts across the Kanto corridor. Chubu Electric Power Company, Inc. sustains competitive positioning through nuclear restart licensing and LNG portfolio flexibility. Kyushu Electric Power Company, Inc. dominates geothermal-rich southern prefectures with specialized baseload supply contracts.
Japan power encompasses electricity generation, transmission, and distribution infrastructure operating across alternating current grids standardized at 50 Hz eastern and 60 Hz western frequencies, with voltage classes spanning 6.6 kV distribution to 500 kV ultra-high-voltage trunk lines serving industrial and urban load centers. Photovoltaic technology leads capacity additions as land constraints drive floating solar installations and agrivoltaic dual-use projects, while turbine-based thermal generation retains margin concentration in frequency regulation and peak shaving roles. Hybrid installation configurations are capturing the fastest growth trajectory by combining on-grid reliability with behind-the-meter resilience for critical manufacturing facilities.
METI's GX League framework and JIS standards for grid interconnection shape technology qualification timelines and capital recovery profiles for new generation assets. The country's national energy regulator enforces capacity market rules and carbon intensity benchmarks that filter market access for imported fuel sources and offshore wind developers. Stakeholders must monitor feed-in tariff phase-out schedules and regional grid stability constraints as distributed energy resource penetration reshapes dispatch economics.
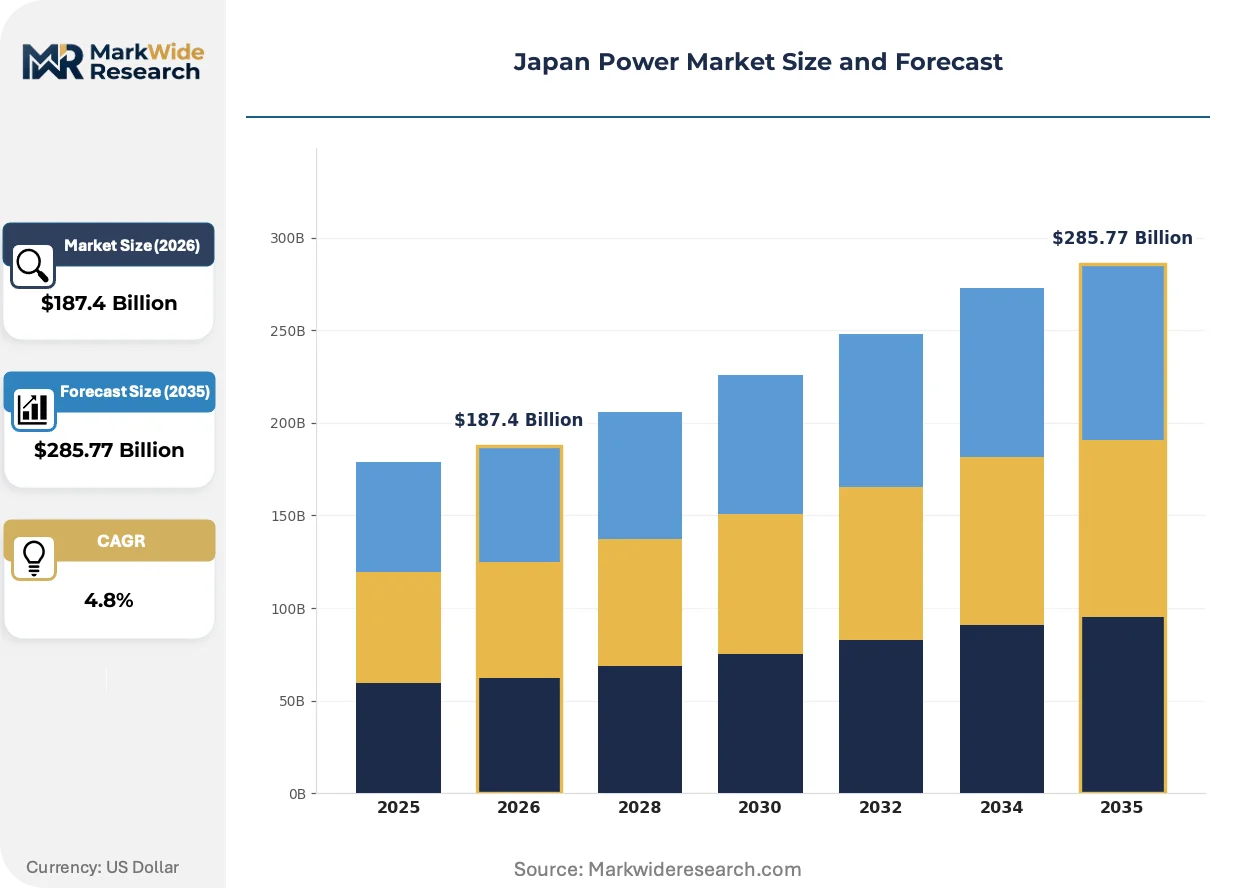
Market Dynamics
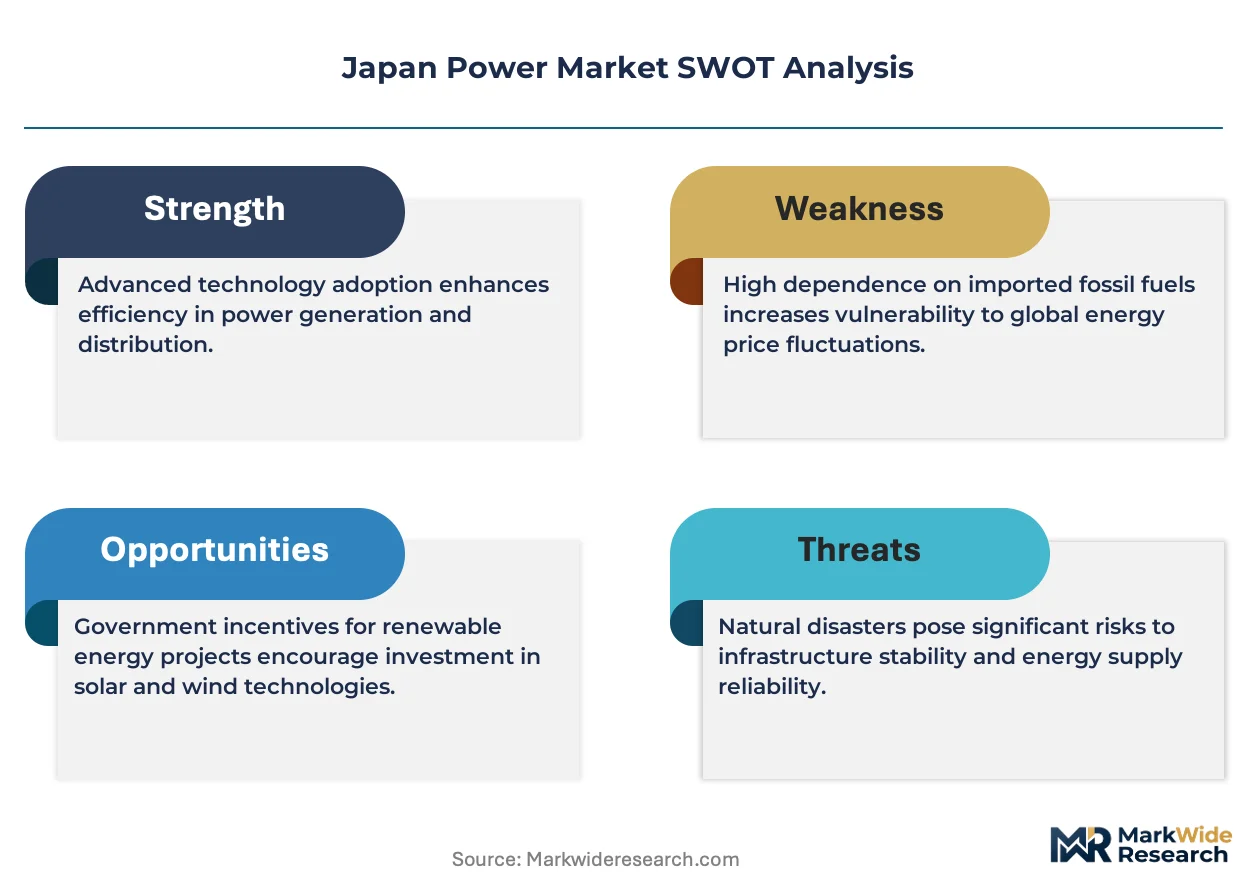
Japan's power sector is restructuring around industrial electrification mandates under METI's Green Transformation framework, with grid modernization timelines compressing investment horizons for conventional thermal assets.
Growth Catalysts
- GX League decarbonization targets:METI's corporate emissions disclosure requirements are forcing industrial facilities to secure renewable power purchase agreements, expanding offtake from utility-scale solar and wind installations.
- Semiconductor manufacturing reshoring:Domestic fabs in Kumamoto and Hokkaido are contracting for firm baseload supply, accelerating transmission upgrades across Kyushu and northern Honshu.
- Floating solar technology maturation:Reservoir-based photovoltaic systems are unlocking capacity additions where land scarcity previously blocked ground-mount development.
Market Restraints
- LNG import price volatility:Thermal generators face margin compression when Asian spot LNG benchmarks spike, undermining dispatch economics for combined-cycle plants.
- Grid frequency synchronization costs:The 50 Hz eastern and 60 Hz western interconnection bottleneck requires expensive frequency converter stations, limiting inter-regional power trading.
- Geothermal resource access restrictions:National park and onsen proximity rules block drilling in Japan's most productive volcanic zones, capping baseload renewable expansion.
Strategic Opportunities
- Agrivoltaic dual-use deployment:METI's agricultural land co-use permits are opening subsidy pathways for solar arrays above rice paddies in Niigata and Akita prefectures.
- Behind-the-meter battery aggregation:Industrial facilities with onsite storage can participate in emerging capacity markets, monetizing frequency regulation services.
- Offshore wind leasing rounds:The General Maritime Bureau's seabed permits for floating turbines in deep Pacific waters offer first-mover positioning for developers with floating foundation technology.
Industry Challenges
- Grid interconnection queue congestion:JIS certification timelines for inverter compliance are stretching project commissioning schedules, straining developer working capital.
- Utility workforce transition gaps:Regional power companies lack sufficient technicians trained in battery storage integration and smart grid operations.
- Legacy thermal asset stranding risk:Coal and LNG plant owners face accelerated depreciation schedules as carbon intensity benchmarks tighten under METI's GX roadmap.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Power Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Solar, Wind, Hydro, Biomass Technology: Photovoltaic, Thermal, Turbine, Geothermal End User: Residential, Commercial, Industrial, Public Sector Installation Type: On-grid, Off-grid, Hybrid, Net Metering |
| Companies Covered | Kyushu Electric Power Company, Inc., The Chugoku Electric Power Co., Inc., The Kansai Electric Power Company, Inc., Hokkaido Electric Power Company, Inc., Shikoku Electric Power Company, Inc., Tokyo Electric Power Co Holdings, Inc., Tohoku Electric Power Company, Inc., Hokuriku Electric Power Company, Chubu Electric Power Company, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Power Market Strategic Shifts
Technology convergence and procurement model experimentation are fragmenting Japan's historically centralized power architecture, with distributed resources capturing investment flows that previously concentrated in transmission-linked generation.
Solid-state battery storage is bifurcating the industrial resilience market. These systems provide four-hour discharge duration for semiconductor fabs requiring uninterrupted supply. Toyota and Panasonic manufacturing campuses are piloting installations ahead of broader commercialization. The technology is bifurcating procurement between premium on-site backup and grid-scale frequency regulation services.
METI's 2024 feed-in tariff phase-out schedule is compressing merchant solar economics. Developers must now negotiate bilateral contracts with industrial offtakers rather than relying on guaranteed purchase prices. Projects in Hokkaido and Tohoku with strong wind resources are securing corporate PPAs, while southern Kyushu solar assets face merchant price exposure.
Industrial buyers are consolidating electricity procurement through specialized trading houses rather than incumbent utilities. Battery gigafactories and data center operators in the Kanto corridor are engaging directly with renewable developers, bypassing traditional utility intermediaries. This disintermediation is most pronounced among semiconductor and cloud computing facilities with 24/7 clean energy commitments.
Japan Power Market Segmentation
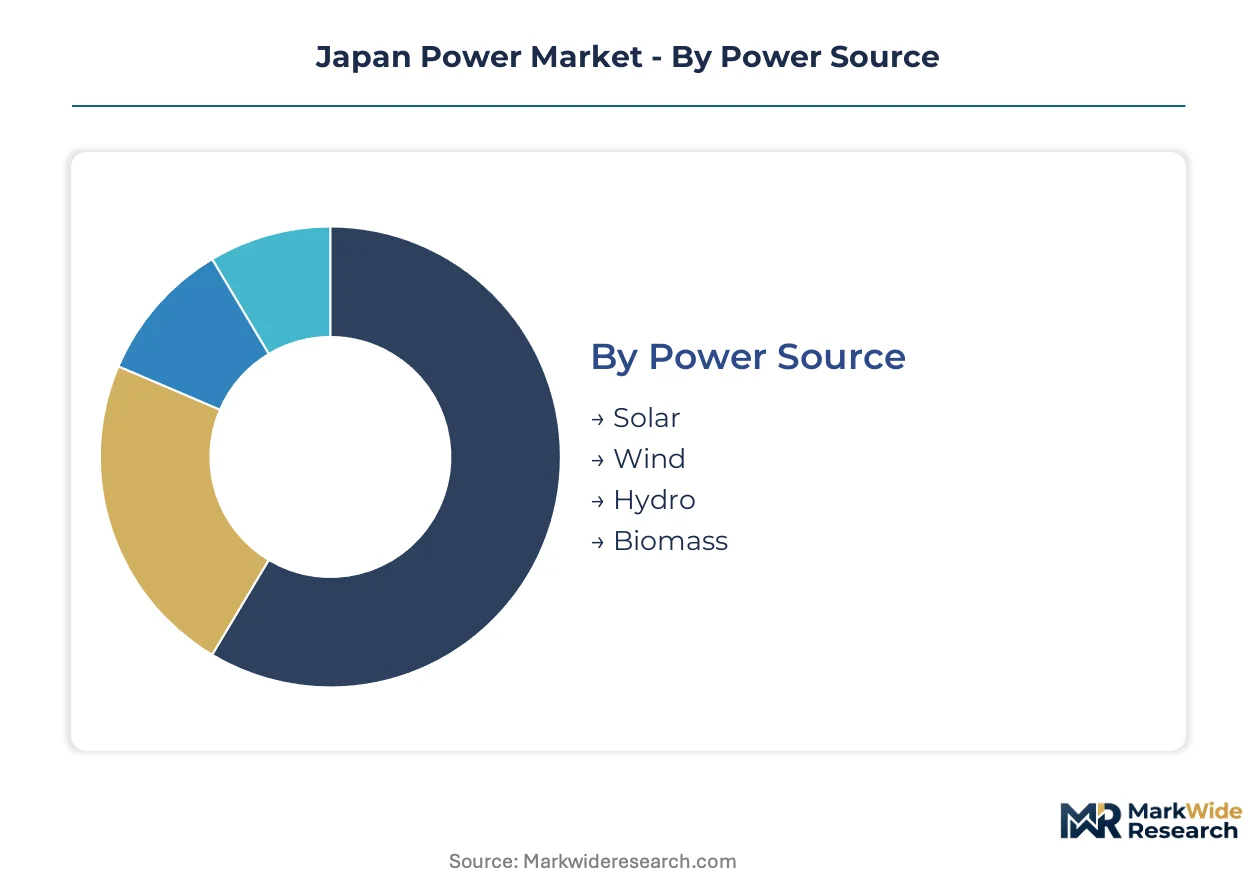
Segmentation reveals how METI's regulatory frameworks create divergent investment returns across generation technologies and buyer categories. Procurement patterns split sharply between industrial offtakers with 24/7 clean energy mandates and residential segments exposed to feed-in tariff phase-outs.
Power Source:
METI's feed-in tariff schedules and grid interconnection standards differentiate capital recovery timelines across renewable technologies, with solar and wind facing accelerated merchant exposure while geothermal and hydro retain baseload premiums.
- Solar:Photovoltaic arrays dominate capacity additions through floating installations on reservoirs and agrivoltaic dual-use deployments above rice paddies in Niigata prefecture. Semiconductor fabs in Kumamoto and Hokkaido are contracting directly with solar developers for firm supply under GX League disclosure requirements.
- Wind:Onshore turbine development concentrates in Hokkaido and Tohoku corridors with strong resource profiles; offshore floating platforms in deep Pacific waters await General Maritime Bureau seabed permits. Corporate PPAs from battery gigafactories are securing offtake ahead of grid connection.
- Hydro:Pumped-storage facilities provide frequency regulation services across the 50 Hz eastern and 60 Hz western interconnection boundary. Existing run-of-river assets face limited greenfield expansion due to watershed protection designations.
- Biomass:Wood pellet and agricultural residue combustion qualifies for renewable portfolio standards under JIS certification pathways. Industrial heat users in pulp and paper clusters anchor demand in northern Honshu.
Solar handles the majority of throughput; wind is the fastest mover on share.
Technology:
Cost tiers separate premium solid-state storage configurations from conventional inverter-based systems, with thermal and turbine assets occupying peak shaving and frequency regulation niches as renewable penetration rises.
- Photovoltaic:Silicon-based modules with PERC and TOPCon cell architectures dominate utility-scale deployments. Residential rooftop segments face margin compression as net metering compensation rates decline under METI's 2024 tariff revisions.
- Thermal:Combined-cycle gas turbines retain dispatch priority during renewable intermittency events. LNG price volatility at Asian spot benchmarks undermines plant economics when import costs spike.
- Turbine:Steam and gas turbine generators provide spinning reserves for grid stability. Aging coal units face accelerated depreciation schedules under carbon intensity benchmarks tightening through the GX roadmap.
- Geothermal:Binary and flash steam plants extract heat from volcanic zones in Kyushu and Tohoku. National park proximity restrictions and onsen protection rules block drilling in the most productive resource areas.
Photovoltaic technology commands the largest installed base; geothermal is climbing the fastest as baseload renewable demand intensifies.
End User:
Customer type determines contract structure, with industrial buyers negotiating bilateral PPAs while residential and commercial segments remain tethered to utility tariff schedules.
- Residential:Single-family and multi-unit dwellings consume distributed generation through rooftop solar and community energy schemes. Feed-in tariff phase-outs are shifting investment toward self-consumption with battery backup.
- Commercial:Office buildings and retail chains procure electricity through incumbent utilities with limited direct renewable access. Energy service companies are aggregating behind-the-meter storage for demand charge management.
- Industrial:Semiconductor fabs, battery gigafactories, and data centers contract for firm baseload and 24/7 clean energy. Manufacturing reshoring under Japan's Green Transformation policy is expanding procurement volumes fastest.
- Public Sector:Municipal buildings, hospitals, and military installations operate under government energy efficiency mandates. Prefecture-level procurement is consolidating through joint purchasing agreements.
Industrial offtake handles the majority of throughput; public sector procurement is gaining share fastest as government facilities electrify heating and transport fleets.
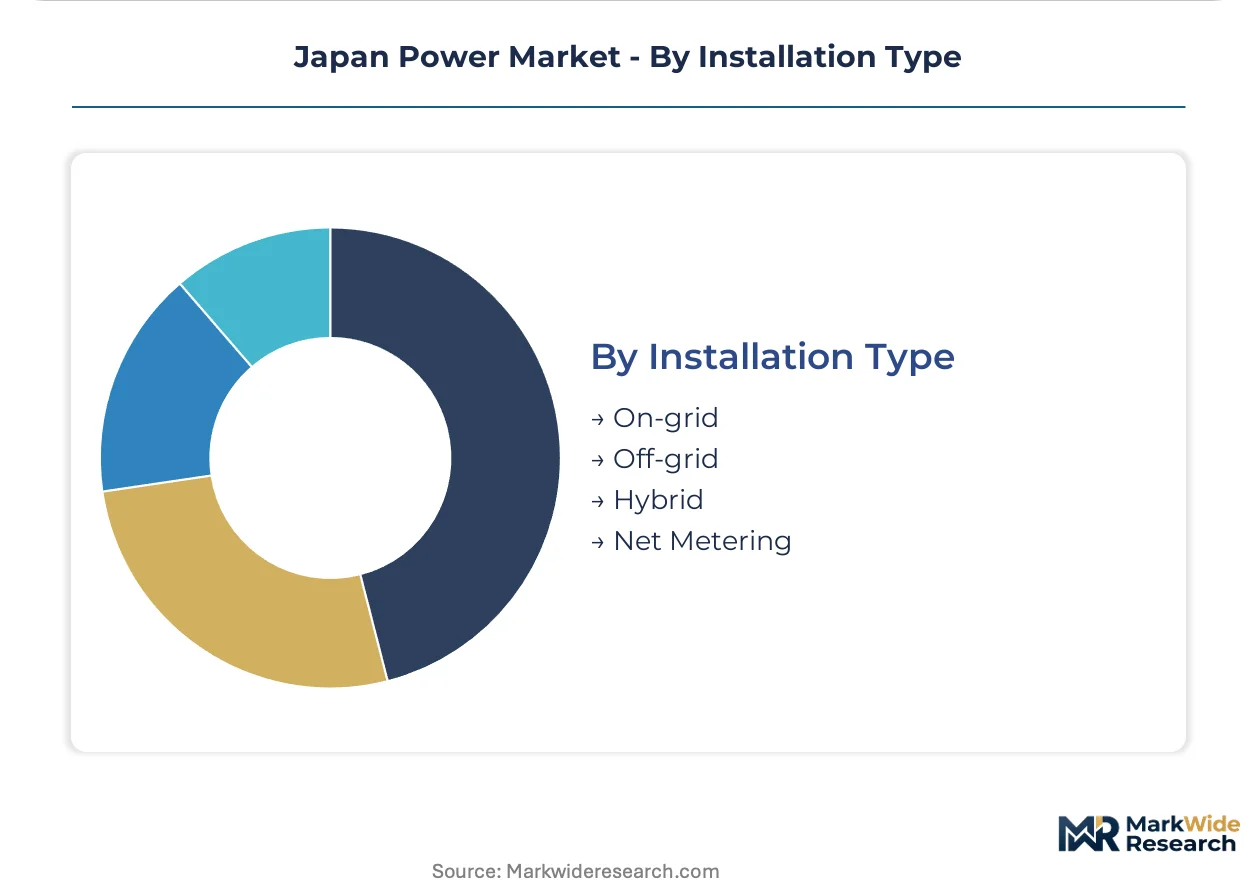
Installation Type:
Grid configuration determines revenue model stability, with hybrid systems capturing premium pricing for resilience while pure on-grid assets face merchant price exposure.
- On-grid:Utility-scale solar and wind connect to transmission networks at 66 kV and above. Grid interconnection queue congestion from JIS certification backlogs stretches commissioning timelines.
- Off-grid:Remote industrial sites and island communities deploy diesel-solar hybrid systems. Mining operations in Hokkaido and fisheries in southern archipelagos anchor niche demand.
- Hybrid:Solar-plus-battery configurations combine on-grid reliability with behind-the-meter resilience for critical manufacturing. Toyota and Panasonic campuses are piloting solid-state storage ahead of broader commercialization.
- Net Metering:Residential and small commercial generators export surplus to the grid at regulated rates. Compensation structures are compressing under METI's tariff reform schedules.
On-grid installations handle the majority of throughput; hybrid configurations are expanding most quickly as industrial buyers prioritize supply continuity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 500 kV trunk lines spanning Honshu anchor Japan's power distribution architecture, linking industrial load centers across frequency-divided eastern and western grids through converter stations at Sakuma and Higashi-Shimizu.
Kanto/Tokyo
Semiconductor fabs in Yokohama and data centers in Saitama Prefecture drive 24/7 clean energy procurement under METI's GX League disclosure rules. The Ministry of Economy, Trade and Industry enforces carbon intensity benchmarks that filter grid access for new generation assets. Tokyo Electric Power Co Holdings leverages transmission density to anchor premium industrial contracts across the corridor.
Kansai/Osaka
Manufacturing reshoring in Osaka and Kyoto prefectures expands electricity offtake from utility-scale solar installations. The Kansai Electric Power Company sustains competitive positioning through nuclear restart licensing at Takahama and Ohi stations. Battery gigafactories in the Hanshin industrial zone contract directly with renewable developers, bypassing traditional utility intermediaries.
Kyushu
Geothermal-rich volcanic zones in Oita and Kumamoto prefectures supply baseload renewable power to semiconductor fabs under firm supply contracts. Kyushu Electric Power Company dominates specialized baseload agreements in southern prefectures. TSMC's Kumamoto fab anchors industrial electrification demand, accelerating transmission upgrades across the island.
Hokkaido
Onshore wind corridors in the Oshima and Kamikawa subprefectures capture corporate PPAs from energy-intensive facilities. Hokkaido Electric Power Company manages grid stability constraints as distributed resource penetration reshapes dispatch economics. Mining operations and fisheries deploy off-grid diesel-solar hybrid systems in remote northern territories.
Chubu/Nagoya
Automotive electrification supply chains in Aichi Prefecture contract for behind-the-meter battery aggregation services. Chubu Electric Power Company sustains positioning through LNG portfolio flexibility and pumped-storage frequency regulation. Toyota manufacturing campuses pilot solid-state storage configurations ahead of broader commercialization.
Japan Power Market Competitive Environment
Concentration sits with the ten regional electric power companies that inherited generation, transmission, and distribution assets from the 1951 sector restructuring. These vertically integrated utilities retain grid control across geographically defined service territories. Three archetypes dominate: transmission-dense incumbents anchoring industrial corridors, nuclear-restart specialists capturing baseload premiums, and geothermal-rich southern operators. Competitive moves center on direct PPA negotiations with semiconductor fabs and strategic battery storage partnerships for frequency regulation services.
Among the established regional utilities, Tokyo Electric Power Co Holdings, Chubu Electric Power Company, and Kyushu Electric Power Company occupy differentiated positions within the competitive structure. Tokyo Electric exemplifies the transmission-density archetype through its Kanto corridor dominance. Chubu Electric represents the nuclear-restart specialist model with licensed capacity at Hamaoka. Kyushu Electric anchors the geothermal-baseload tier through volcanic zone resource access. Each sits within METI's regulatory framework governing capacity market participation and carbon intensity compliance.
| Leading Market Players |
|---|
| Kyushu Electric Power Company, Inc. |
| The Chugoku Electric Power Co., Inc. |
| The Kansai Electric Power Company, Inc. |
| Hokkaido Electric Power Company, Inc. |
| Shikoku Electric Power Company, Inc. |
| Tokyo Electric Power Co Holdings, Inc. |
| Tohoku Electric Power Company, Inc. |
| Hokuriku Electric Power Company |
| Chubu Electric Power Company, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between semiconductor fabs and renewable developers lock in both supply access and price visibility, insulating industrial buyers from merchant price exposure as METI's feed-in tariff phase-outs compress solar economics across southern prefectures.
Pricing Analysis
Volume-discount tiering separates industrial offtakers contracting for baseload firm supply from residential segments exposed to declining net metering rates. Premium pricing attaches to hybrid solar-plus-battery configurations with four-hour discharge duration, while standard on-grid assets face merchant price risk. Cost compression in utility-scale solar intensifies as bilateral PPA negotiations replace guaranteed tariffs. Semiconductor and data center operators demonstrate lowest price sensitivity due to 24/7 clean energy mandates, whereas residential rooftop segments face acute sensitivity to compensation rate reductions.
Supply Chain Analysis
Just-in-time inventory strategies dominate photovoltaic module procurement, with developers minimizing working capital exposure during extended JIS certification timelines. Manufacturing concentrates in China, South Korea, and domestic Japanese facilities for silicon wafers and inverter components. Solid-state battery cells draw from specialized production lines in Japan and South Korea. Single-source vulnerability runs through polysilicon refining capacity concentrated in specific geographies. Distribution feeds from EPC contractors directly to project sites, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where METI's grid interconnection standards and JIS certification requirements create structural barriers that protect incumbent utilities from rapid competitive displacement.
For Market Incumbents: Shield transmission network density through accelerated frequency converter investments at the 50 Hz and 60 Hz interconnection boundary, neutralizing the threat of industrial buyers bypassing utility intermediaries through direct PPA negotiations. Deepen backward integration into battery storage integration capabilities to capture emerging capacity market revenues from behind-the-meter aggregation services.
For New Entrants and Emerging Players: METI's agricultural land co-use certification fast-track offers entry into agrivoltaic deployments across Niigata and Akita prefectures, where incumbent utility presence remains underdeveloped. Target remote industrial sites in Hokkaido mining territories with off-grid diesel-solar hybrid configurations. Lead with specialized EPC expertise in floating solar reservoir installations to differentiate from conventional ground-mount developers.
For Investors and Strategic Acquirers: Geothermal-rich regional operators with established onsen-adjacent drilling rights present acquisition targets with durable baseload contract profiles. Long-term viability centers on renewable penetration rates and carbon intensity benchmark enforcement trajectories across the analysis window. Watch for LNG import price volatility spikes as inflection indicators that accelerate industrial buyer migration toward firm renewable supply contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Behind-the-Meter Battery Aggregation | Industrial facilities monetize frequency regulation services through METI's emerging capacity market mechanisms. |
| Floating Solar Platform Deployment | Reservoir-based installations unlock capacity additions where land scarcity previously blocked development. |
| Geothermal Resource Access Expansion | Binary and flash steam plants supply baseload renewable power to semiconductor fabs under firm contracts. |
| Direct PPA Negotiation Bypass | Battery gigafactories and data centers engage renewable developers without traditional utility intermediation. |
| Grid Interconnection Queue Management | Developers compress JIS certification timelines to reduce working capital strain during project commissioning. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators; and secondary validation against METI regulatory filings, IEA power sector reports, FERC-equivalent capacity market disclosures, and project development databases. Bottom-up installation capacity estimates triangulated with top-down electricity demand forecasts from industrial load projections.
Across the projection horizon, the analytical framework modeled segmentation by fuel source, generation capacity tier, project scale, and regional grid type. CAGRs derived from regression analysis of historical capacity additions against policy incentive trajectories and manufacturing reshoring timelines. Forecast inputs incorporated LNG import price volatility indices and semiconductor fab electrification schedules.
Underlying assumptions cover METI's GX League enforcement trajectory and feed-in tariff phase-out schedules, with deviation risk concentrated in nuclear restart licensing delays and geothermal drilling permit approvals. Revision becomes warranted when industrial offtake growth crosses thresholds that strain transmission upgrade timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Global Power Line Communication (PLC) Systems Market
Power
Norway Power Market
Power
Modified Sine Wave Home Inverters Market
Power
Solar Plants Controllers Market
Power
Middle-East and Africa Power Rental Market
Power
Europe Microturbine Market
Power
Global UPS Market
Power
Canada Power Market
Power
Global Ancillary Services Power Market
Power
Europe Submarine Power Cables Market
Power
Asia-Pacific Package Substation Market
Power
Global Diesel Power Engine Market
Power
Italy Power Market
Power
Denmark Power Market
Power
Equatorial Guinea Power Market
Power
United States Power Market