
 Substation Automation System Market | 2026-2036
Substation Automation System Market Size, Share, and Industry Trends Forecast 2026-2036
Substation Automation System Market Analytics
The substation automation supply base is consolidating around a widening capability gap between premium integrated platforms and commodity hardware. Siemens AG leverages its digital twin portfolio to anchor high-margin digital substation contracts across European utilities. ABB Limited competes through deep specialization in IEC 61850-compliant intelligent electronic devices that sustain renewal demand in mature grids. Schneider Electric SE differentiates by extending edge-computing architectures into remote terminal units, positioning its offerings for distributed renewable integration.
A substation automation system encompasses intelligent electronic devices, communication networks, and SCADA platforms that execute real-time monitoring, protection, and control functions within electrical substations, typically operating across IEC 61850 protocol stacks with sub-10-millisecond latency requirements for fault isolation. These systems serve the primary purpose of maintaining grid stability while enabling remote operability and reducing manual intervention in high-voltage environments. Intelligent electronic devices command the largest installed base within product type segments, though cybersecurity solutions within the technology dimension represent the fastest-expanding margin pool as NERC CIP enforcement tightens. SCADA systems remain structurally mature with replacement-driven demand concentrated in North American and European utilities, while integration platforms are gaining share where multi-vendor interoperability becomes a procurement priority.
FERC Order 2222 in the United States, the EU Cybersecurity Act through ENISA, and IEC 61850 Edition 2.1 collectively reshape product certification requirements and procurement specifications for substation automation vendors. These frameworks elevate barrier-to-entry for non-compliant suppliers while creating specification advantages for vendors with pre-certified cybersecurity architectures. Stakeholders must weigh capital allocation between proprietary platform development and ecosystem partnerships as regulatory fragmentation across jurisdictions intensifies compliance complexity.
Market Dynamics
Grid operators are replacing electromechanical protection relays with microprocessor-based intelligent electronic devices at accelerating velocity, compressing replacement cycles from fifteen years to seven as IEC 61850 interoperability mandates harden procurement specifications.
Growth Catalysts
- FERC Order 2222:United States transmission operators must enable distributed energy resource aggregation, forcing substation upgrades that accommodate bidirectional power flows and real-time telemetry.
- Offshore wind interconnection:Germany's North Sea and Baltic Sea grid expansion requires digital substations capable of managing variable renewable injection at 66 kV and above.
- IEC 61850 Edition 2.1:The revised standard mandates cybersecurity-by-design for intelligent electronic devices, triggering wholesale replacement of pre-2018 installed base across European utilities.
Market Restraints
- Semiconductor supply concentration:Power management integrated circuits for protective relays depend on TSMC and Samsung foundry capacity, exposing lead times to geopolitical friction in Taiwan Strait logistics.
- Copper and rare earth volatility:Permanent magnet materials for optical current transformers face price instability from Chinese export quota adjustments.
- Interoperability certification delays:UCAlug testing backlog for IEC 61850 compliance extends vendor time-to-revenue by eight to fourteen months.
Strategic Opportunities
- India's smart grid mission:Power Grid Corporation of India Limited targets 175 GW renewable integration by 2022 mandates, creating demand for substation automation in Rajasthan and Gujarat solar zones.
- Digital twin convergence:Integration of asset performance management software with physical protection relays enables predictive maintenance contracts that capture fifteen-year lifecycle value.
- Edge computing architectures:Remote terminal units with localized analytics reduce backhaul bandwidth requirements for Brazilian Amazon basin transmission lines.
Industry Challenges
- Cybersecurity workforce scarcity:NERC CIP compliance requires certified control system security professionals that utilities cannot recruit at scale, forcing reliance on third-party assessors.
- Multi-vendor integration complexity:Brownfield substations mixing ABB, Siemens, and Schneider Electric devices suffer protocol translation failures that delay commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Substation Automation System Market |
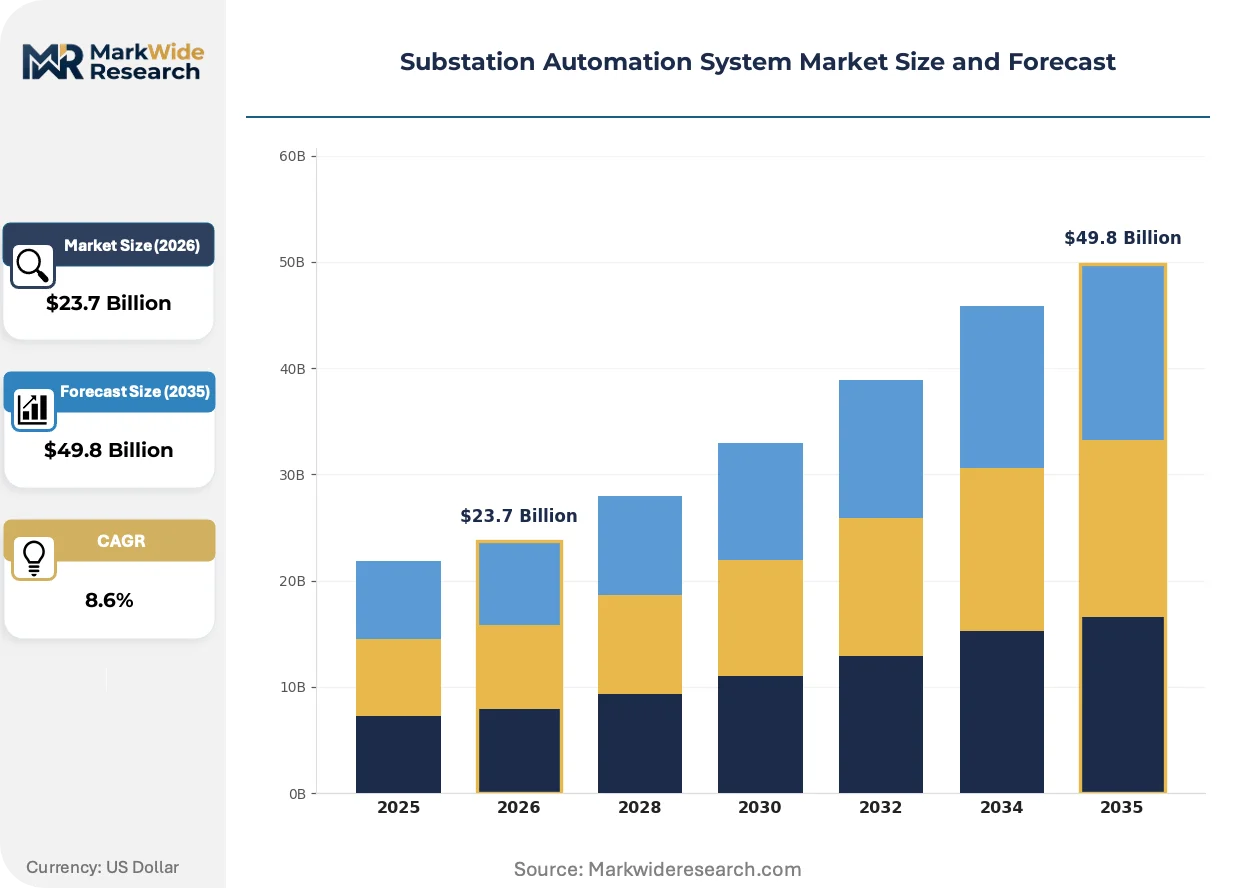
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Terminal Units, Intelligent Electronic Devices, Communication Networks, SCADA Systems Technology: Digital Substation, Remote Monitoring, Cybersecurity Solutions, Integration Platforms End User: Utilities, Power Generation, Industrial Sector, Renewable Energy Providers Application: Grid Management, Fault Detection, Energy Management, Automation Control |
| Companies Covered | ABB Limited, Siemens AG, Schneider Electric SE, General Electric Company, Hitachi Energy Ltd, Eaton Corporation, Cisco Systems Inc., Honeywell International Inc., Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Substation Automation System Market Evolving Landscape
Substation automation is pivoting from hardware-centric protection toward software-defined control planes that decouple physical asset management from real-time operational logic.
Optical current transformers with Rogowski coil sensing are rewriting fault detection economics by eliminating magnetic saturation and enabling wide-area measurement synchronization. German transmission system operators TenneT and 50Hertz are deploying these devices at 380 kV substations to support dynamic line rating. The technology is compressing protection relay form factors while extending measurement bandwidth into harmonic analysis.
EU Cybersecurity Act through ENISA mandates Common Criteria EAL4+ certification for critical energy infrastructure components, forcing European vendors to re-architect firmware supply chains. Industrial consequence includes mandatory secure boot and hardware root-of-trust in all new intelligent electronic device designs. Scandinavian utilities are responding by pre-qualifying only vendors with certified development facilities.
Asset-as-a-service contracting is displacing capital purchase models for SCADA platforms, with United States rural electric cooperatives leading adoption. Subscription pricing transfers obsolescence risk to vendors while locking buyers into fifteen-year maintenance relationships. This pattern is most visible across Midwestern agricultural load zones where cooperative governance favors operational expenditure smoothing.
Substation Automation System Market Segmentation
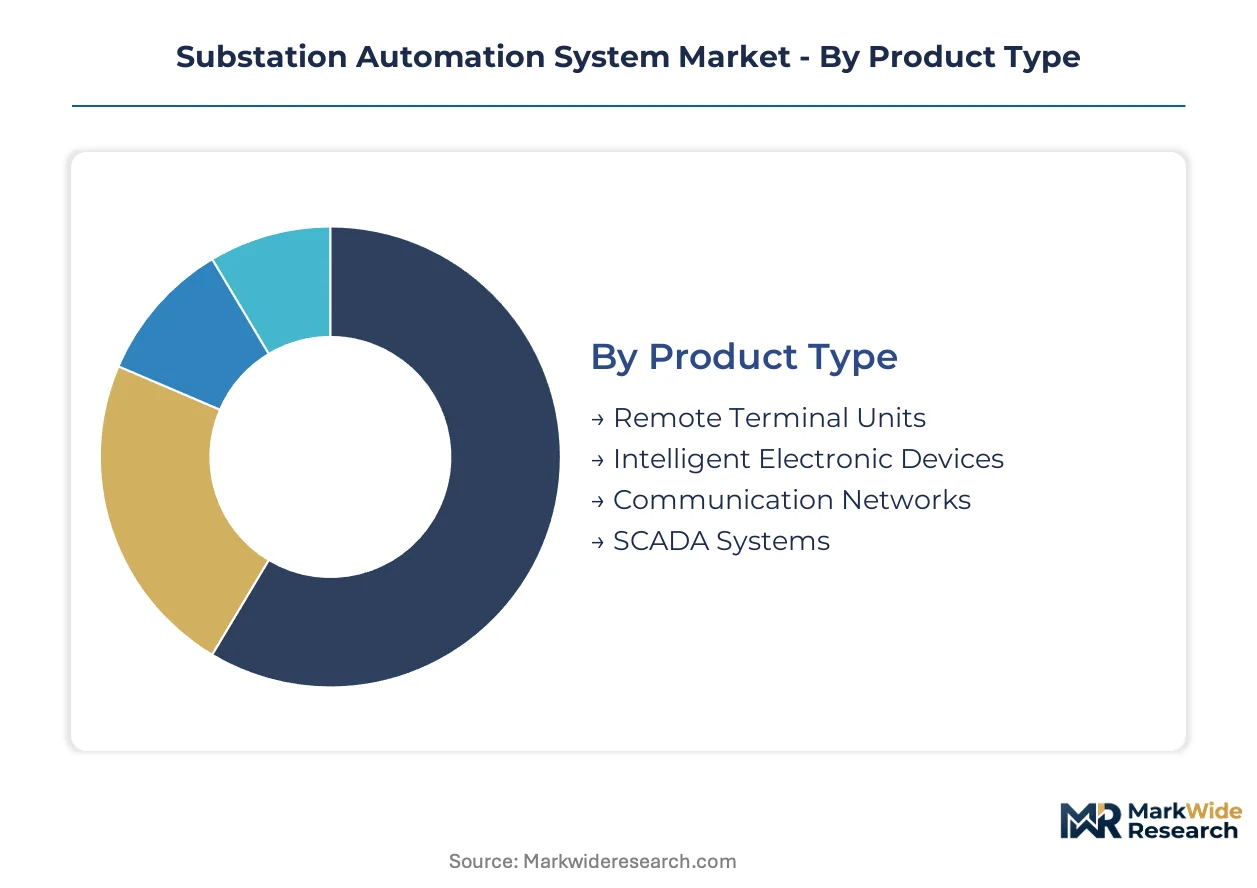
Segmentation in substation automation reveals how procurement specifications diverge between legacy grid upgrades and greenfield digital substation deployments. Understanding these divides helps vendors align R&D investment with replacement-cycle timing and regulatory compliance windows.
Product Type:
Replacement cycles now compress from fifteen years to seven as IEC 61850 interoperability mandates harden procurement specifications across transmission and distribution networks.
- Intelligent Electronic Devices:Microprocessor-based protection relays executing real-time fault isolation with sub-10-millisecond latency. Demand concentrates in German transmission system operators replacing pre-2018 installed base under Edition 2.1 cybersecurity mandates.
- Remote Terminal Units:Edge-computing architectures enabling localized analytics and reduced backhaul bandwidth for remote transmission lines. Brazilian Amazon basin deployments favor these units where fiber connectivity remains uneconomical.
- Communication Networks:IEC 61850 protocol stacks with redundant Ethernet switching for station bus and process bus architectures.
- SCADA Systems:Structurally mature platforms with replacement-driven demand concentrated in North American rural electric cooperatives.
Intelligent Electronic Devices sits at the top of the volume ranking, with Remote Terminal Units climbing the fastest.
Technology:
Cost tiers separate premium integrated platforms from commodity hardware as cybersecurity certification becomes a non-negotiable procurement filter.
- Cybersecurity Solutions:Firmware with secure boot, hardware root-of-trust, and Common Criteria EAL4+ certification under EU Cybersecurity Act. Scandinavian utilities pre-qualify only vendors with certified development facilities, creating specification advantages for compliant suppliers.
- Digital Substation:Software-defined control planes decoupling physical asset management from operational logic through optical current transformers and process bus architectures. Germany's North Sea grid expansion drives 66 kV and above deployments.
- Remote Monitoring:Cloud-connected telemetry reducing manual substation inspections and enabling condition-based maintenance.
- Integration Platforms:Multi-vendor interoperability layers resolving protocol translation failures in brownfield substations mixing equipment from different suppliers.
Digital Substation commands the premium pricing tier, while Cybersecurity Solutions expands most quickly as NERC CIP enforcement tightens.
End User:
Customer type determines contract structure, with utilities favoring capital purchases and renewable developers seeking operational expenditure models.
- Utilities:Transmission and distribution operators with fifteen-year asset lifecycles and regulatory-mandated reliability standards. United States municipal utilities drive SCADA replacement demand under FERC Order 2222 distributed energy resource aggregation requirements.
- Renewable Energy Providers:Wind and solar developers requiring bidirectional power flow telemetry and real-time variable injection management. India's Rajasthan solar zones create concentrated demand under 175 GW renewable integration targets.
- Power Generation:Conventional plant operators modernizing switchyard protection and synchronization systems.
- Industrial Sector:Heavy manufacturing facilities with captive substations prioritizing power quality and arc flash protection.
Utilities dominate current installed base, with Renewable Energy Providers gaining share fastest as offshore wind interconnection accelerates.
Application:
Functional priority varies by grid maturity, with developed markets emphasizing automation control and emerging markets prioritizing fault detection visibility.
- Fault Detection:Optical current transformers with Rogowski coil sensing eliminating magnetic saturation and enabling wide-area measurement synchronization. TenneT and 50Hertz deploy these at 380 kV substations for dynamic line rating.
- Automation Control:Software-defined protection logic reducing commissioning time and enabling remote configuration changes without site visits.
- Grid Management:Real-time topology processing and contingency analysis for transmission operators.
- Energy Management:Load forecasting integration and demand response coordination at distribution substations.
Fault Detection leads deployment priority in transmission upgrades, with Automation Control showing the steepest expansion trajectory in greenfield digital substations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Munich, Bangalore, and Houston anchor substation automation development across three continents. Utility procurement teams in these hubs drive specification standards that cascade to secondary markets. Regulatory divergence between FERC, EU Cybersecurity Act, and IEC frameworks fragments certification requirements.
United States
Rural electric cooperatives in the Midwest accelerate SCADA replacement cycles under FERC Order 2222 distributed energy resource mandates. NERC CIP enforcement tightens cybersecurity staffing requirements beyond utility recruitment capacity. Houston-Gulf Coast transmission operators deploy digital substations for hurricane-resilient grid segmentation.
Germany
TenneT and 50Hertz expand North Sea offshore wind interconnection requiring 380 kV digital substation architectures. EU Cybersecurity Act through ENISA mandates Common Criteria EAL4+ certification for all new intelligent electronic devices. Bavarian industrial automation specialists supply process bus components for Hamburg-anchored grid expansion.
China
State Grid Corporation procurement prioritizes domestic intelligent electronic device production for ultra-high voltage transmission corridors. MIIT cybersecurity standards for critical infrastructure harden firmware development requirements. Yangtze River Delta manufacturing clusters produce optical current transformers for 66 kV and above deployments.
India
Power Grid Corporation targets 175 GW renewable integration across Rajasthan and Gujarat solar zones. Central Electricity Authority mandates IEC 61850 compliance for all new transmission substations above 132 kV. Bangalore-based software engineering pools supply integration platforms for multi-vendor brownfield deployments.
Japan
Tokyo Electric Power accelerates earthquake-resilient substation automation following 2011 grid fragility assessments. METI efficiency standards drive replacement of electromechanical protection relays with microprocessor-based devices. Osaka-Kansai industrial electronics manufacturers specialize in compact intelligent electronic devices for space-constrained urban substations.
Substation Automation System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market consolidating around three capability tiers. Integrated platform vendors command premium pricing through proprietary digital twin and cybersecurity architectures. Component specialists sustain margins in intelligent electronic device niches where IEC 61850 certification creates specification stickiness. The dominant competitive moves are strategic partnerships for multi-vendor interoperability and geographic expansion into India's renewable integration zones.
Within the integrated platform tier, Siemens AG and ABB Limited exemplify European engineering heritage applied to utility-scale automation contracts. Schneider Electric SE occupies a position bridging hardware manufacturing with edge-computing software architectures. These three entities represent the premium tier where procurement specifications favor pre-certified cybersecurity portfolios and fifteen-year lifecycle service agreements.
| Leading Market Players |
|---|
| ABB Limited |
| Siemens AG |
| Schneider Electric SE |
| General Electric Company |
| Hitachi Energy Ltd |
| Eaton Corporation |
| Cisco Systems Inc. |
| Honeywell International Inc. |
| Mitsubishi Electric Corporation |
| Others |
Value Network & Pricing Analysis
London Metal Exchange copper futures volatility cascades through substation automation manufacturing, compressing margins on commodity-grade intelligent electronic devices while amplifying pricing power for vendors with captive transformer winding and rare earth magnet supply.
Pricing Analysis
The bundled-vs-unbundled service split separates capital-purchase hardware from subscription-based lifecycle contracts. Premium vendors anchor pricing through fifteen-year maintenance agreements that transfer obsolescence risk from United States rural electric cooperatives to suppliers. Certification tier creates the primary price differentiation driver, with Common Criteria EAL4+ compliant devices commanding substantial premiums over uncertified alternatives. Cost compression in standard-grade remote terminal units is intensifying because Indian solar zone procurement favors lowest-compliant-bid award criteria. Municipal utilities exhibit highest price sensitivity, while German transmission system operators demonstrate lowest sensitivity due to regulatory-mandated reliability standards.
Supply Chain Analysis
Control systems engineering talent scarcity in Munich, Houston, and Bangalore manufacturing clusters constrains production scaling for intelligent electronic device foundries. Taiwan and South Korea anchor semiconductor supply for power management integrated circuits, while China dominates rare earth processing for optical current transformer magnets. The supply chain draws from copper concentrate, silicon steel laminations, and gallium nitride substrates. Single-source vulnerability in TSMC foundry capacity for protective relay processors exposes lead times to geopolitical friction. Distribution runs through authorized systems integrators who perform IEC 61850 compliance testing before utility handover.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where IEC 61850 Edition 2.1 cybersecurity mandates trigger wholesale replacement cycles across European utilities.
For Market Incumbents: Extend digital twin platform penetration into predictive maintenance contracts that capture full lifecycle value. Consolidate position through exclusive partnerships with Scandinavian utilities pre-qualifying only EAL4+ certified vendors. Counter margin pressure from commodity hardware competitors by deepening firmware supply chain control. For New Entrants and Emerging Players: Capture white-space in Indian renewable integration zones where Power Grid Corporation procurement lacks incumbent lock-in. Penetrate Brazilian Amazon basin edge-computing deployments where fiber connectivity constraints favor localized analytics architectures. Lead with interoperability certification services that resolve brownfield protocol translation failures. For Investors and Strategic Acquirers: Asymmetric upside sits with cybersecurity-specialist component vendors holding ENISA pre-certification. Five-to-ten year viability favors suppliers with demonstrated NERC CIP compliance track records in United States transmission markets. Monitor UCAlug testing backlog duration as inflection indicator for vendor time-to-revenue compression.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61850 Edition 2.1 Certification Investment | ENISA EAL4+ pre-certification creates specification advantages in German and Scandinavian utility procurement. |
| Digital Twin Platform Integration | Siemens and ABB leverage asset performance management software to anchor fifteen-year service contracts. |
| Edge Computing Architecture Development | Schneider Electric extends remote terminal unit capabilities for Brazilian and Indian distributed renewable zones. |
| Multi-Vendor Interoperability Partnership | Integration platform vendors resolve protocol translation failures in brownfield substations mixing equipment suppliers. |
| Cybersecurity Workforce Development | Third-party assessor networks address NERC CIP staffing gaps beyond utility recruitment capacity. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with transmission planning officers, substation engineering directors, IEC certification auditors, and rural electric cooperative procurement managers combined with secondary validation from FERC filings, EIA grid modernization databases, ENISA critical infrastructure reports, and UCAlug interoperability testing records. Triangulation between demand-side replacement cycle analysis and supply-side production capacity verification ensures cross-dimensional consistency.
Historical trendline analysis of electromechanical-to-digital relay replacement patterns informs the projection framework across the analysis window. Segmentation dimensions include product type, technology tier, end-user archetype, and application function, with regional regulatory cluster as an additional modeling layer. CAGRs derive from weighted average of utility capital expenditure trajectories and vendor order backlog conversion rates. Forecast inputs incorporate offshore wind interconnection timelines and cybersecurity mandate enforcement intensity.
Copper price volatility, semiconductor foundry capacity constraints, and interoperability certification delays are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and utility procurement cycle timing. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
North America Micro CHP Market
Power
Green UPS Market
Power
Middle-East and Africa Power Rental Market
Power
Brazil Power Market
Power
Global Advanced Marine Power Supply Market
Power
Canada Thermal Power Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Global Diesel Power Engine Market
Power
Wind Turbine Drivetrain Market
Power
Recloser Control Market
Power
Italy Power EPC Market
Power
Global Ancillary Services Power Market
Power
Saudi Arabia Power Market
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
Global Power Line Communication (PLC) Systems Market
Power
Asia-Pacific Microturbine Market