
 Resonant Power Converters Market | 2026-2036
Resonant Power Converters Market Size, Share, and Industry Trends Forecast 2026-2036
Resonant Power Converters Market Analytics
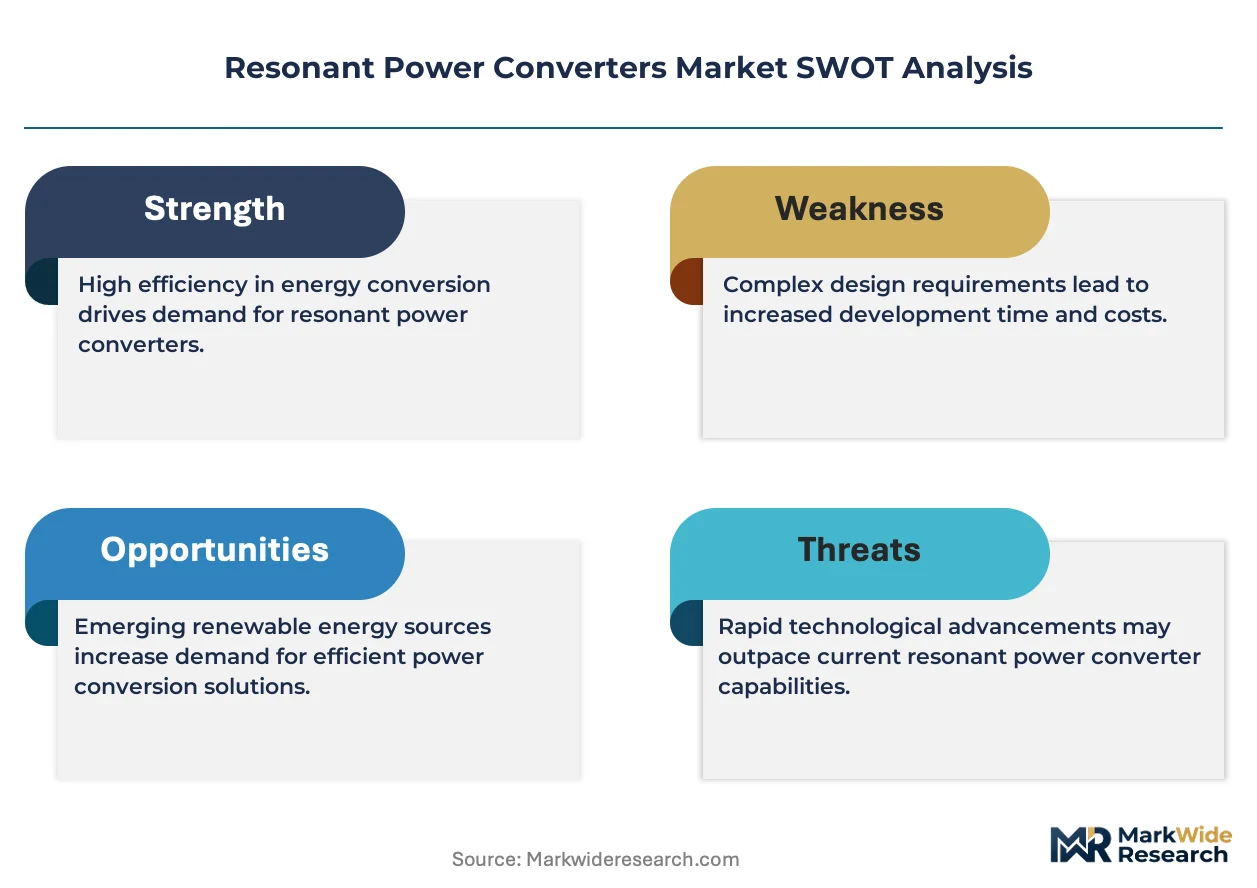
The EU Ecodesign Directive is realigning procurement criteria for external power supplies and industrial drives across European manufacturing. Infineon Technologies leverages its SiC and GaN portfolio to dominate high-frequency resonant designs for automotive traction inverters. Texas Instruments anchors its position through integrated controller ICs that reduce external component count in LLC and phase-shifted full-bridge architectures. STMicroelectronics specializes in silicon carbide MOSFETs paired with gate drivers optimized for soft-switching resonant operation.
Resonant power converters employ inductor-capacitor tank networks to achieve zero-voltage or zero-current switching, typically operating between 100 kHz and 1 MHz to minimize switching losses and magnetic component size. LLC converters occupy the largest share of consumer electronics adapters and LED driver applications due to their natural voltage regulation capability and integrated magnetics. Full-bridge phase-shifted resonant topologies lead in DC-DC converter applications for datacenter and telecommunications power supplies where isolation and high step-down ratios are mandatory. Component-level demand concentrates in transformers and capacitors engineered for high-frequency, high-dV/dt stress environments.
EPA ENERGY STAR specifications and EU Ecodesign regulations enforce minimum efficiency tiers that directly disqualify hard-switched alternatives below 75-100 W in many product categories. China's GB standards and NMPA-aligned quality certification for medical power supplies create parallel compliance pathways that shape export manufacturing requirements. The FCC's conducted and radiated emission limits constrain resonant frequency selection and filtering component choices in North American-bound equipment. Stakeholders must monitor evolving wide-bandgap semiconductor cost curves and corresponding shifts in optimal switching frequency ranges for each resonant topology family.
Market Dynamics
The transition from silicon to wide-bandgap semiconductors is compressing switching losses and enabling frequency scaling that redefines magnetic component sizing across resonant converter designs.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficiency mandates for external power supplies above 75W are disqualifying hard-switched topologies in European consumer electronics and industrial equipment procurement.
- Electric vehicle powertrain integration:Onboard chargers and high-voltage DC-DC stages in battery electric vehicles require isolated resonant topologies for thermal management and power density.
- Wide-bandgap semiconductor cost curves:Silicon carbide and gallium nitride device pricing trajectories are expanding economically viable operating frequencies from 100 kHz toward 500 kHz and above.
Market Restraints
- Magnetic component supply concentration:High-frequency transformer and inductor manufacturing concentrates in East Asian suppliers, creating vulnerability to regional logistics disruptions.
- EMI filtering cost inflation:FCC conducted emission limits and CISPR 32 radiated requirements force oversized common-mode chokes and shielding at frequencies above 300 kHz.
- Hard-switched alternative persistence:Quasi-resonant flyback designs retain cost advantages below 100W in price-sensitive adapter markets, limiting resonant topology penetration.
Strategic Opportunities
- India industrial electrification:BIS efficiency standards and CEA grid code compliance for variable frequency drives are opening demand for resonant front-end PFC stages in motor control applications.
- Data center 48V direct conversion:Phase-shifted full-bridge resonant architectures enable high-step-down ratios from 400V bus to point-of-load without intermediate conversion stages.
- GaN-Si hybrid integration:Monolithic integration of gallium nitride HEMTs with silicon control logic is collapsing gate driver complexity and board area in LLC controller implementations.
Industry Challenges
- Magnetic design talent scarcity:High-frequency transformer engineering for LLC tank networks requires specialized knowledge of core loss modeling and leakage inductance control that outpaces university curriculum refresh rates.
- Multi-physics simulation capacity:Thermal-electromagnetic co-simulation of resonant tanks at megahertz frequencies demands software licenses and computational infrastructure beyond mid-tier converter houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resonant Power Converters Market |
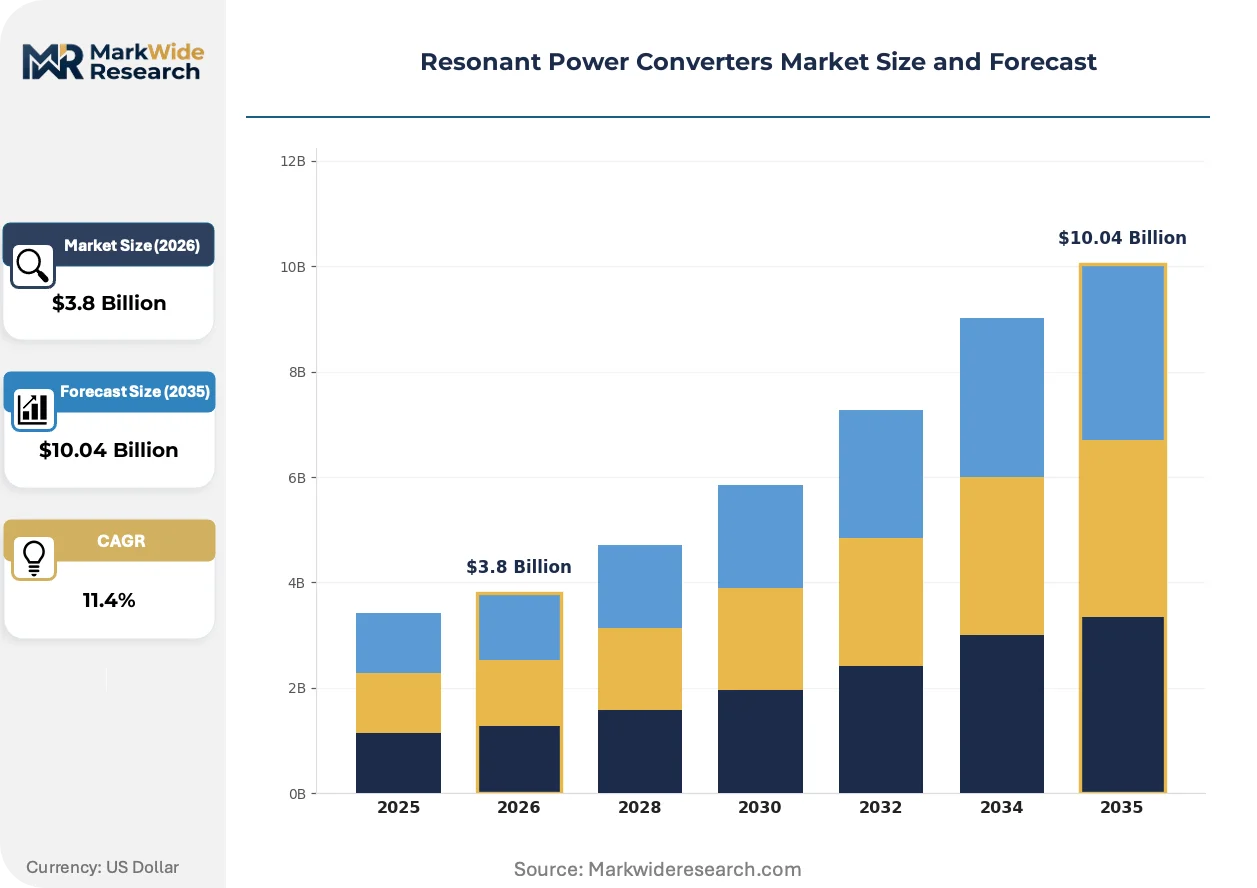
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quarter-Bridge, Half-Bridge, Full-Bridge, LLC Converter End User: Telecommunications, Consumer Electronics, Automotive, Renewable Energy Application: Power Supplies, DC-DC Converters, Inverters, UPS Systems Component: Transformers, Capacitors, Inductors, Switches |
| Companies Covered | Power Integrations, Infineon Technologies, Texas Instruments, STMicroelectronics, ON Semiconductor, ROHM, Delta Electronics, Vicor Corporation, Wolfspeed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resonant Power Converters Market Evolving Landscape
Resonant converter development is converging on three vectors: semiconductor material transitions, regulatory efficiency ratchets, and buyer consolidation forcing standardization. These forces are compressing design differentiation and amplifying scale advantages.
GaN-on-Si lateral devices are consolidating the mid-power resonant converter segment through integrated half-bridge packages that collapse driver-loop inductance. Server power supply manufacturers in Taiwan and China are adopting these devices for 3 kW+ telecom rectifier designs. The technology is consolidating competitive positioning around semiconductor supplier relationships rather than discrete magnetic engineering capabilities.
EPA ENERGY STAR Version 8.0 specifications for external power supplies are tightening no-load power consumption limits below 0.075W, forcing burst-mode control refinements in LLC controllers. This regulatory compression is eliminating marginal designs from North American retail channels. Medical power supply vendors targeting FDA 510(k) pathways are pre-certifying resonant platforms to these efficiency tiers to streamline dual-use product development.
Hyperscale data center operators are unbundling power supply procurement from server OEM contracts, creating direct purchasing relationships with specialized resonant converter manufacturers. This channel disintermediation is collapsing the traditional tier-one server power supply vendor margin structure. The shift is most visible in Virginia and Singapore colocation markets where facility operators specify converter efficiency guarantees independent of server hardware selection.
Resonant Power Converters Market Segmentation
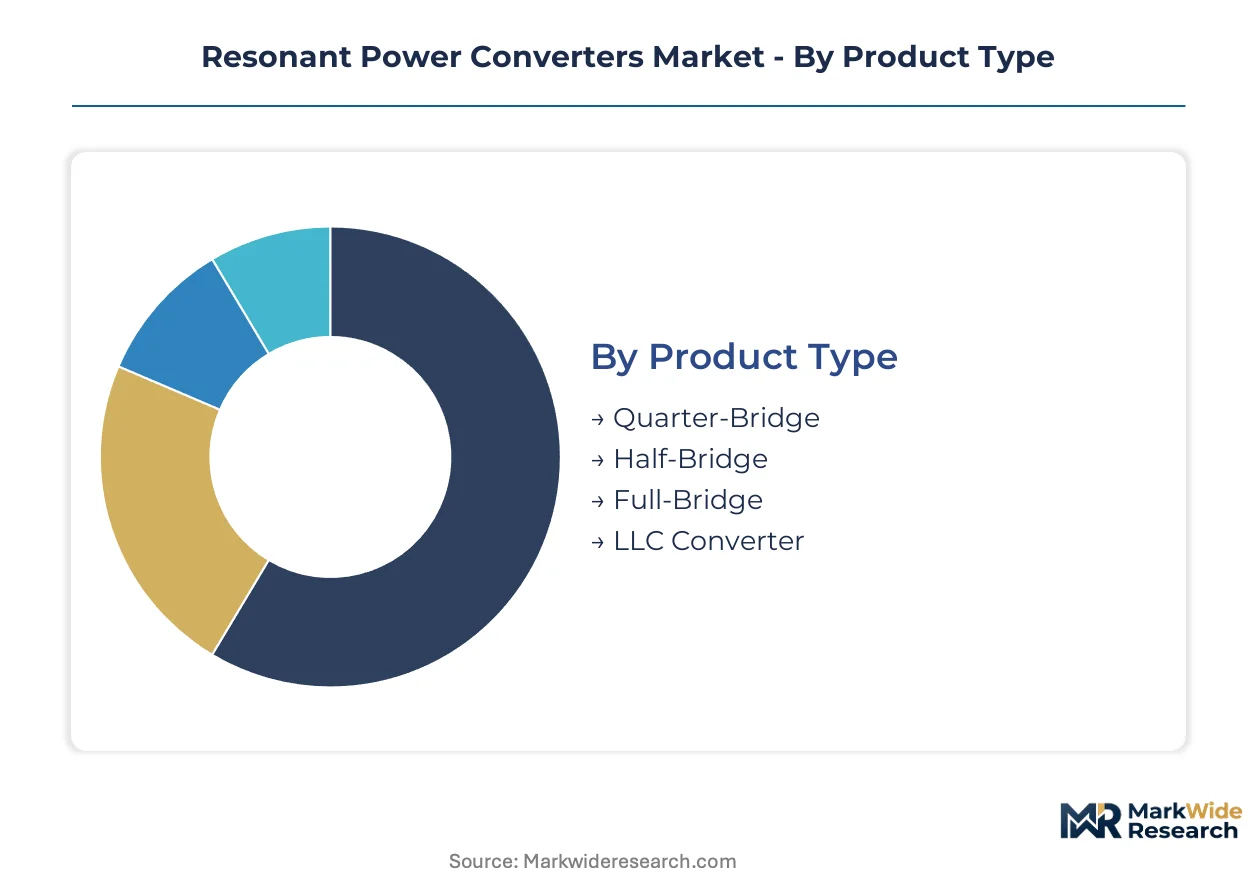
Resonant power converter architectures fragment across multiple technical and commercial dimensions, each imposing distinct magnetic design requirements and semiconductor selection criteria. Topology choice dictates tank network complexity, while end-use application determines isolation ratings and thermal constraints.
Product Type:
Full-bridge and LLC configurations demand substantially higher upfront engineering investment in transformer design and control loop optimization than simpler quarter-bridge alternatives.
- Full-Bridge:Four-switch phase-shifted architectures achieve zero-voltage switching across wide load ranges through resonant tank manipulation. Datacenter and telecommunications rectifier procurement in Northern Virginia and Singapore clusters favors this topology for 3 kW+ isolated DC-DC stages.
- LLC Converter:Integrated magnetics and natural voltage regulation through variable frequency control reduce external component count. Consumer electronics adapter manufacturers in Guangdong and LED driver suppliers in Taiwan concentrate procurement here for 75-300 W applications.
- Half-Bridge:Two-switch resonant tanks balance component cost with soft-switching capability in mid-power industrial equipment.
- Quarter-Bridge:Single-switch quasi-resonant designs retain cost advantages below 100 W in price-sensitive adapter markets where EU Ecodesign efficiency mandates have not yet displaced hard-switched alternatives.
LLC converters absorb the bulk of installed capacity; full-bridge topologies are expanding most quickly in high-power datacenter applications.
End User:
Automotive and renewable energy segments impose the most stringent qualification cycles and longest design-in timelines, stretching working capital requirements for converter suppliers.
- Automotive:Onboard chargers and high-voltage DC-DC stages in battery electric vehicles require isolated resonant topologies rated for AEC-Q100 thermal cycling and ISO 26262 functional safety. NHTSA documentation requirements and EPA fuel economy credits accelerate OEM adoption of wide-bandgap-enabled designs.
- Telecommunications:Central office rectifiers and 5G base station power supplies mandate NEBS compliance for seismic and thermal stress tolerance. Carrier procurement specifications in Germany, Japan, and South Korea enforce 98%+ efficiency thresholds that disqualify hard-switched alternatives.
- Consumer Electronics:External power supplies for laptops, tablets, and gaming consoles face EPA ENERGY STAR Version 8.0 no-load consumption limits below 0.075 W.
- Renewable Energy:Solar microinverters and energy storage power conditioning systems require galvanic isolation and wide input voltage range operation.
Telecommunications maintains the largest cumulative installed base; automotive applications are climbing the fastest as EV production scales.
Application:
Power supply applications concentrate procurement volume, while inverter and UPS segments command premium pricing through specialized magnetic component requirements.
- Power Supplies:AC-DC adapters, open-frame industrial supplies, and enclosed LED drivers constitute the foundational demand layer. EU Ecodesign Directive minimum efficiency tiers for external supplies above 75 W have restructured European procurement toward resonant architectures since 2019.
- DC-DC Converters:Isolated bus converters and intermediate bus architectures in servers and network equipment require high step-down ratios from 400 V or 48 V distribution buses. Hyperscale operators in Ashburn, Frankfurt, and Singapore now specify converter efficiency guarantees independent of server OEM selection.
- Inverters:DC-AC power conversion for motor drives and renewable energy integration employs resonant soft-switching to reduce IGBT or SiC MOSFET switching losses.
- UPS Systems:Uninterruptible power supplies for healthcare and critical infrastructure deploy resonant battery charger stages and inverter topologies for sinusoidal output.
Power supplies dominate cumulative shipment volume; DC-DC converters are gaining share fastest in datacenter direct conversion architectures.
Component:
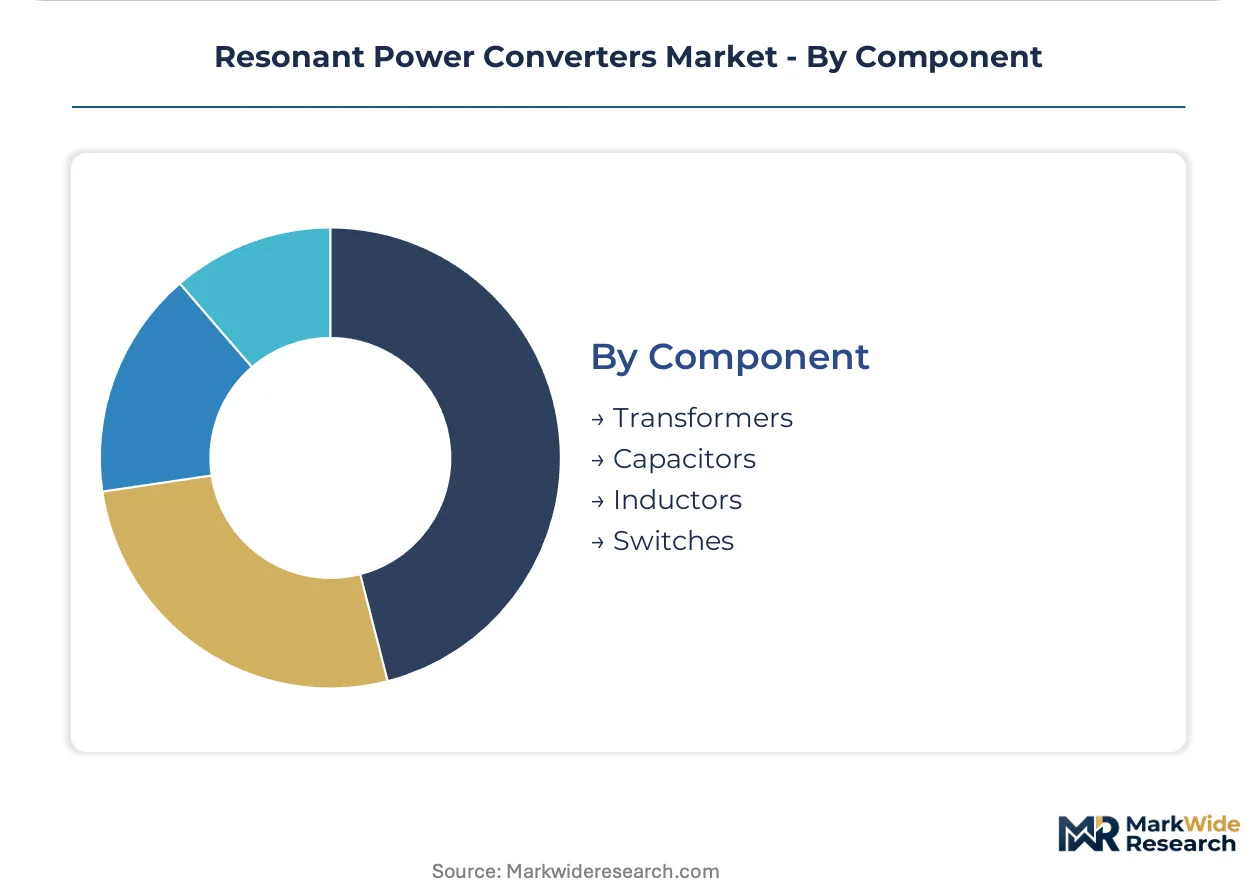
Transformers and capacitors represent the highest-value bill-of-materials items, with specialized high-frequency magnetic components commanding substantial gross margins.
- Transformers:High-frequency power transformers for LLC and phase-shifted full-bridge tanks require engineered leakage inductance and distributed gap core geometries. Manufacturing concentrates in East Asian suppliers, creating vulnerability to regional logistics disruptions.
- Switches:Silicon carbide MOSFETs and gallium nitride HEMTs enable frequency scaling from 100 kHz toward 500 kHz and above, collapsing magnetic component size. Infineon, STMicroelectronics, and Texas Instruments anchor supply through integrated half-bridge packages and optimized gate drivers.
- Capacitors:Film and ceramic capacitors for resonant tanks must withstand high dV/dt stress and elevated ripple current at megahertz frequencies.
- Inductors:Resonant inductors and output filter chokes require core loss modeling at operating frequencies where traditional Steinmetz equations lose accuracy.
Transformers represent the largest component expenditure; wide-bandgap switches are expanding most quickly as GaN-Si hybrid integration reduces driver complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and the Pearl River Delta anchor the largest concentration of resonant converter manufacturing capacity, with Guangdong province housing the dominant share of high-frequency transformer and adapter production for consumer electronics and EV powertrains.
China
Domestic EV manufacturers and wide-bandgap semiconductor foundries are scaling resonant topology deployment across onboard chargers and DC-DC stages. MIIT efficiency mandates and GB standards for external power supplies above 75W are tightening compliance thresholds. Manufacturing clusters in Shenzhen, Dongguan, and Suzhou are vertically integrating from GaN wafer fabrication through finished adapter assembly.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are disaggregating power supply procurement from server OEM contracts. EPA ENERGY STAR Version 8.0 specifications and FCC emission limits are reshaping resonant frequency selection and filtering requirements. Design engineering concentrates in Silicon Valley and Austin, with manufacturing partnerships extending to Mexico for cost-sensitive adapter production.
Germany
Industrial drive manufacturers and automotive Tier-1 suppliers are adopting resonant front-end PFC stages for motor control and traction inverter applications. EU Ecodesign Directive minimum efficiency tiers are disqualifying hard-switched alternatives in procurement specifications. The Baden-Württemberg and Bavaria industrial corridors host concentrated R&D activity for SiC-enabled resonant designs.
Japan
Telecommunications equipment vendors and precision power supply manufacturers are specifying 98%+ efficiency thresholds for central office rectifiers and 5G base station infrastructure. METI technology roadmaps and JIS standards are accelerating wide-bandgap semiconductor qualification cycles. Manufacturing and design engineering clusters in Nagoya and Osaka are specializing in high-reliability resonant converters for NEBS-compliant telecommunications equipment.
India
Variable frequency drive adoption and industrial electrification are opening demand for resonant front-end stages in motor control applications. BIS efficiency standards and CEA grid code compliance requirements are restructuring procurement toward soft-switching architectures. Manufacturing investment is concentrating in Gujarat and Tamil Nadu, with design partnerships emerging in Bangalore for controller IC development.
Resonant Power Converters Market Competitive Landscape
The competitive structure tilts toward integrated semiconductor suppliers with captive wide-bandgap device portfolios and specialized magnetic component manufacturers with high-frequency transformer engineering capabilities. Market positioning fragments across three archetypes: diversified power semiconductor conglomerates, pure-play resonant controller IC vendors, and vertically integrated power supply manufacturers. Dominant competitive moves include strategic partnerships between semiconductor suppliers and magnetic component specialists, and geographic expansion of high-frequency transformer manufacturing into India and Vietnam.
Among diversified semiconductor suppliers, Infineon Technologies, Texas Instruments, and STMicroelectronics exemplify distinct positioning archetypes within the resonant converter ecosystem. Infineon anchors the wide-bandgap device tier through its SiC and GaN portfolio integration. Texas Instruments occupies the controller IC specialization vector with integrated solutions reducing external component count. STMicroelectronics represents the European semiconductor conglomerate model with silicon carbide MOSFETs paired with optimized gate driver architectures.
| Leading Market Players |
|---|
| Power Integrations |
| Infineon Technologies |
| Texas Instruments |
| STMicroelectronics |
| ON Semiconductor |
| ROHM |
| Delta Electronics |
| Vicor Corporation |
| Wolfspeed |
| Others |
Value Network & Pricing Analysis
EU Ecodesign Directive efficiency mandates for external power supplies above 75W gate qualified supply access and premium-tier pricing power for resonant converter manufacturers serving European consumer electronics and industrial equipment procurement channels.
Pricing Analysis
Efficiency-guarantee contracts tied to datacenter uptime metrics anchor value-based pricing for high-power DC-DC converters in Northern Virginia and Singapore colocation markets. Pricing stratifies across automotive-grade AEC-Q100 certified tiers, industrial standard tiers, and consumer economy tiers with 2-3 year warranty differentiation. Cost compression in consumer adapter segments runs through GaN device price erosion and magnetic component standardization. Automotive OEMs exhibit lowest price sensitivity due to thermal cycling qualification requirements, while consumer electronics brands enforce aggressive target costing.
Supply Chain Analysis
High-frequency ferrite core supply rests on Japanese and Chinese specialty ceramic producers with limited alternative sourcing for Mn-Zn and Ni-Zn formulations optimized for 500 kHz+ operation. Raw material dependencies include rare-earth elements for transformer cores, copper magnet wire, and wide-bandgap semiconductor wafers from Taiwan and the United States. Single-source vulnerability concentrates in East Asian transformer winding capacity for LLC tank networks. Distribution runs through direct OEM contracts for automotive and datacenter segments, with electronics manufacturing service intermediaries handling consumer adapter volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive and comparable efficiency mandates in China and the United States have erected compliance barriers that protect incumbent converter suppliers with certified design platforms while raising capital requirements for new entrants.
For Market Incumbents: To counter GaN-Si hybrid integration from semiconductor suppliers collapsing gate driver value-add, deepen magnetic component engineering capabilities through acquisition of specialized transformer design houses in East Asia and expand captive SiC MOSFET sourcing partnerships with foundries in Germany and the United States.
For New Entrants and Emerging Players: Enter via India's industrial motor drive electrification wave where BIS efficiency standards and CEA grid code compliance are restructuring procurement toward soft-switching front-end PFC stages with limited established supplier relationships.
For Investors and Strategic Acquirers: Hyperscale data center operators disaggregating power supply procurement from server OEM contracts is the leading indicator that specialized resonant converter manufacturers with direct facility operator relationships will command premium multiples; target acquisition archetypes combine wide-bandgate device access with high-frequency magnetic engineering talent.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN-Si Hybrid Controller Integration | Monolithic integration collapses board area and gate driver complexity in LLC implementations. |
| High-Frequency Transformer Manufacturing Expansion | Capacity addition in India and Vietnam reduces logistics vulnerability to East Asian concentration. |
| Direct Hyperscale Data Center Contracts | Bypassing server OEM intermediaries captures margin previously absorbed by tier-one power supply vendors. |
| AEC-Q100 Platform Pre-Certification | Automotive thermal cycling qualification streamlines design-in timelines for EV onboard charger procurement. |
| Wide-Bandgap Semiconductor Foundry Partnership | Captive SiC and GaN supply secures frequency scaling roadmap and insulates against device allocation constraints. |
Research Methodology
Document review covered SEC filings from power semiconductor suppliers, EPA ENERGY STAR certification databases, and EU Ecodesign Directive implementation guidance, complemented by interviews with power electronics design engineers at automotive Tier-1 suppliers, procurement managers at hyperscale data center operators, magnetic component engineering directors, and resonant controller IC product managers. Secondary validation drew from MIIT efficiency standard publications, FCC emission limit enforcement records, and customs trade data for high-frequency transformer imports. Bottom-up shipment estimates triangulated against top-down semiconductor device revenue attribution.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. The analytical framework modeled segmentation across topology type, end-use application, power rating tier, and regional regulatory cluster. CAGRs were derived from installed base turnover dynamics and efficiency mandate phase-in schedules. Industry-specific forecast inputs included EV production ramp rates and datacenter power density roadmaps.
Forecast precision tightens around the base case; tail outcomes carry wider variance under wide-bandgap semiconductor supply disruption or magnetic component logistics interruption scenarios. Forecasts reflect documented assumptions regarding regulatory phase-in timing and technology cost curves. A small set of named triggers—including EPA ENERGY STAR specification revisions, MIIT efficiency tier adjustments, and hyperscale operator procurement policy shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Uzbekistan Power Market
Power
Rotating Phase Converter Market
Power
Europe Frequency Converter Market
Power
Global Advanced Marine Power Supply Market
Power
Static Synchronous Compensator (STATCOM) Market
Power
Asia-Pacific Power Market
Power
Brazil Power Market
Power
Critical Power Market
Power
Electric Power Sports Market
Power
Solar UPS Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
Residential Portable Inverter Generator Market
Power
Power Sled Market
Power
Distributed Buoyancy Modules Market
Power
China Power Market