
 Sudan Power Market | 2026-2036
Sudan Power Market Size, Share, and Industry Trends Forecast 2026-2036
Sudan Power Market Analytics
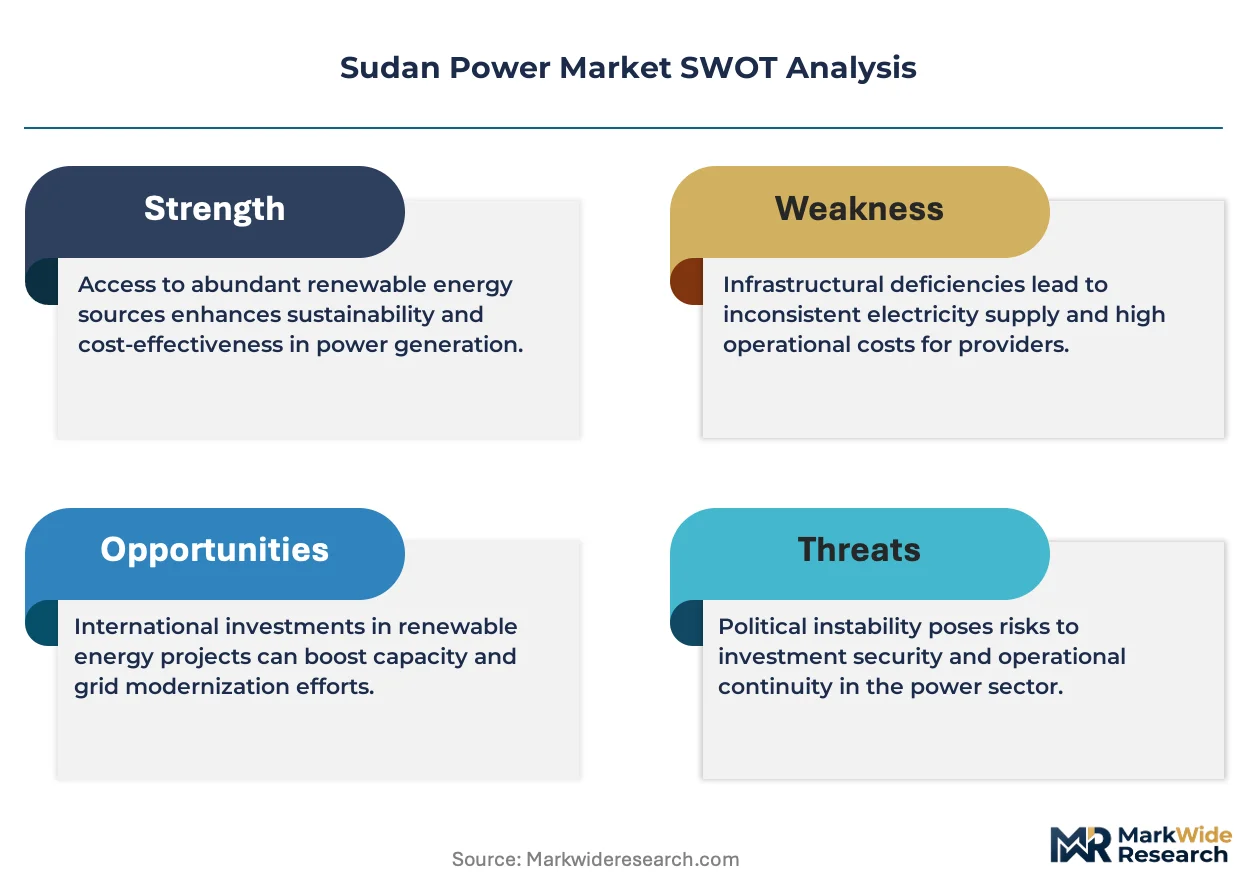
Sudan's renewable energy tariff reform is realigning capital allocation toward independent power producers. Siemens Energy AG leverages its turbine servicing infrastructure to sustain long-term maintenance contracts across the national grid. Sinohydro Corporation anchors its position through dam rehabilitation and hydroelectric expansion on the Nile system. Dal Group competes in distributed generation by controlling diesel backup supply chains for commercial offtakers.
Sudan power encompasses electricity generation, transmission, and distribution infrastructure spanning thermal plants, hydroelectric dams, and emerging photovoltaic arrays, typically operating at 220-400 kV transmission voltage with frequency stabilized at 50 Hz to serve industrial machinery and residential loads. Thermal power still dominates installed capacity, though solar power represents the fastest-growing product type as panel costs fall and desert irradiation levels attract IPP developers. Grid-tied systems lead technology deployment in urban centers, while off-grid solutions penetrate rural localities where transmission extension remains uneconomical.
The Sudanese Electricity Regulatory Authority and the country's national standards body shape licensing timelines and equipment import rules, with the central bank's foreign exchange controls directly constraining project finance availability. Stakeholders must monitor currency convertibility rulings and sovereign payment guarantees before committing capital to long-dated generation assets.
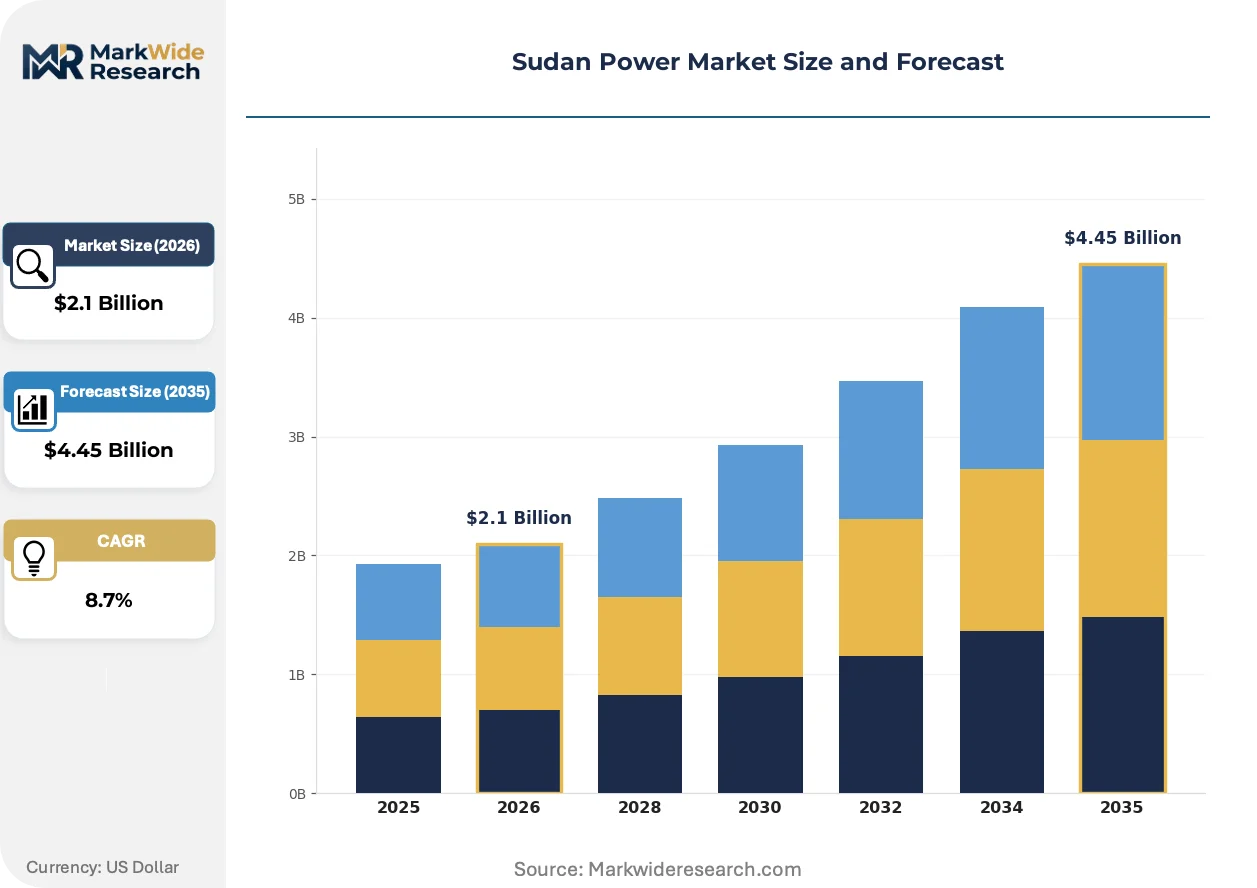
Market Dynamics
Sudan's power sector is being restructured by feed-in tariff reforms that redirect capital toward renewable independent power producers, while foreign exchange controls at the central bank constrain project finance timelines for thermal and hydroelectric developers.
Growth Catalysts
- Renewable IPP Incentives:The Sudanese Electricity Regulatory Authority's adjusted feed-in tariffs create favorable returns for solar and wind developers targeting the Blue Nile corridor.
- Industrial Load Recovery:Manufacturing facilities in Khartoum State are expanding electricity offtake as production lines restart, tightening grid utilization and justifying capacity additions.
- Hydro Rehabilitation:Dam modernization on the Nile system unlocks stranded capacity without requiring greenfield transmission corridors.
Market Restraints
- Foreign Exchange Illiquidity:The central bank's convertibility restrictions block equipment imports and debt service for generation assets denominated in hard currency.
- Diesel Supply Chain Concentration:Backup power dependence concentrates risk with a limited importer base serving commercial offtakers during grid instability.
- Transmission Voltage Limitations:The 220-400 kV ceiling constrains long-distance wheeling from remote hydro and solar sites to demand centers.
Strategic Opportunities
- Rural Off-Grid Deployment:Distributed photovoltaic systems bypass uneconomical transmission extension into western and southern localities.
- Desert Solar Irradiation:Northern Sudan's high insolation levels attract international developers seeking utility-scale sites with minimal land competition.
- Frequency Stabilization Services:Grid-forming inverters and battery storage can capture ancillary revenue streams as renewable penetration rises.
Industry Challenges
- Turbine Servicing Expertise Gap:Maintenance of thermal and hydro rotating equipment depends on expatriate technicians, creating downtime risk during travel restrictions.
- Equipment Import Certification Delays:The national standards body's licensing timelines extend project commissioning schedules.
- Legacy Diesel Integration:Commercial offtakers' existing backup generator fleets complicate grid-tied solar adoption and load management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sudan Power Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Power, Wind Energy, Hydro Power, Thermal Power Technology: Grid-Tied Systems, Off-Grid Solutions, Smart Grids, Battery Storage End User: Residential Users, Commercial Establishments, Industrial Sectors, Government Entities Service Type: Installation Services, Maintenance Contracts, Consultancy Services, Financing Options |
| Companies Covered | Sudanese Thermal Power Generating Company, Sudanese Electricity Distribution Company, Siemens Energy AG, Ram Energy, Dal Group, Sinohydro Corporation, China National Nuclear Corporation, PowerChina, Bharat Heavy Electricals Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sudan Power Market Evolving Landscape
Photovoltaic cost declines and regulatory preference shifts are compressing development timelines for grid-tied generation while fragmenting procurement patterns across state-backed and private offtakers.
Containerized solar-plus-storage systems are rewriting deployment economics for industrial microgrids. Food processing and textile manufacturers near Khartoum are adopting these units to hedge grid unreliability. The technology is rewriting capital allocation by displacing diesel gensets from baseload backup to peak shaving only.
The Sudanese Electricity Regulatory Authority's feed-in tariff framework mandates priority dispatch for renewable IPPs. Industrial offtakers now face structured curtailment rules that favor clean supply during daylight hours. Large manufacturing clusters are responding by rescheduling energy-intensive processes to match solar generation profiles.
Commercial buyers are unbundling maintenance contracts from equipment supply, forcing turbine and panel vendors to compete on lifecycle service pricing. Diesel backup providers in Khartoum State are losing long-term service lock-in as offtakers seek multi-technology maintenance aggregators. This pattern is most visible among warehousing and cold chain operators with 24-hour load requirements.
Sudan Power Market Segmentation
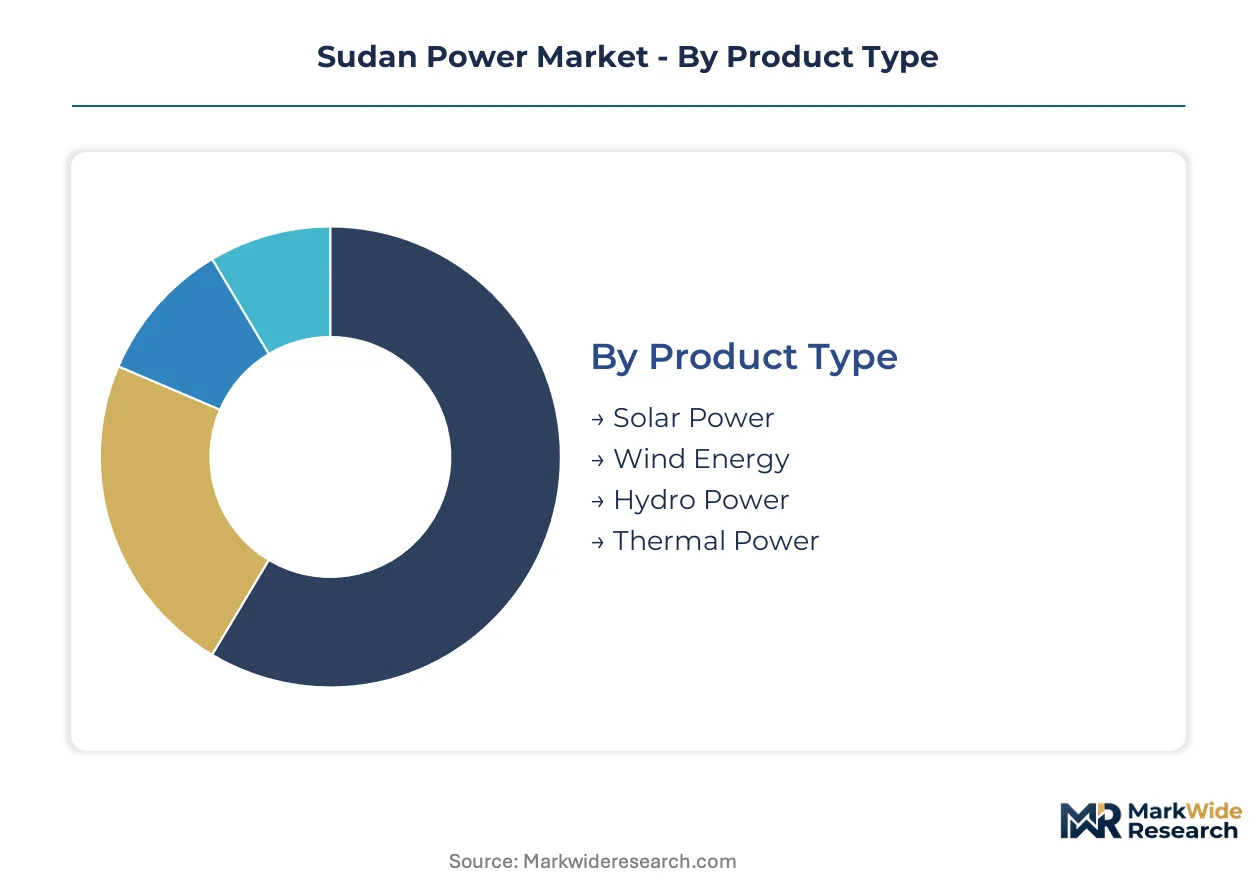
Sudan's power market fragments across generation technologies, delivery modes, and customer economics. Each segment carries distinct capital intensity, regulatory exposure, and currency risk profiles that shape investor entry strategies.
Product Type:
Standardized thermal and hydro assets dominate baseload procurement, while solar and wind installations require site-specific engineering to match irradiation patterns and grid connection points.
- Solar Power:Photovoltaic arrays leverage northern Sudan's desert insolation levels exceeding 2,200 kWh/m² annually. IPP developers target the Blue Nile corridor where the Sudanese Electricity Regulatory Authority's priority dispatch rules guarantee offtake during daylight hours.
- Thermal Power:Natural gas and heavy fuel oil plants provide frequency-stabilized baseload at 50 Hz for industrial machinery. Khartoum State manufacturing clusters depend on these assets when hydro output fluctuates with Nile flow variability.
- Wind Energy:Onshore turbines concentrate in Red Sea coastal zones with consistent trade wind patterns. Project finance remains constrained by foreign exchange illiquidity affecting turbine import timelines.
- Hydro Power:Dam infrastructure on the Nile system generates at 220-400 kV transmission voltage. Rehabilitation of existing assets avoids greenfield permitting delays.
Most installed capacity flows through Thermal Power. Expansion is steepest in Solar Power.
Technology:
Volume concentration favors established grid-tied architectures, though margin profiles improve for distributed solutions that bypass transmission bottlenecks.
- Grid-Tied Systems:Centralized generation connects to the national 220-400 kV network serving Khartoum State industrial parks. The Sudanese Electricity Regulatory Authority mandates frequency synchronization standards that complicate renewable integration.
- Off-Grid Solutions:Standalone photovoltaic and diesel hybrid systems penetrate western and southern localities where transmission extension costs exceed generation economics. Rural health clinics and agricultural processing cooperatives drive procurement.
- Smart Grids:Advanced metering infrastructure enables demand response programs for commercial offtakers. Deployment concentrates in Khartoum's central business district.
- Battery Storage:Lithium-ion and flow battery systems capture ancillary revenue through grid-forming inverter services. Frequency stabilization contracts attract developers as renewable penetration rises.
Grid-Tied Systems carry the largest cumulative deployment. Battery Storage is gaining share fastest among new capital commitments.
End User:
Customer type determines payment reliability, with sovereign-backed entities offering hard currency guarantees unavailable to private offtakers.
- Industrial Sectors:Textile, food processing, and cement manufacturers in Khartoum State require 24-hour baseload with voltage stability for motor drives. These offtakers negotiate bilateral power purchase agreements bypassing retail tariffs.
- Residential Users:Household demand concentrates in Greater Khartoum and the Blue Nile corridor. Subsidized tariff tiers strain distribution utility finances while driving peak load growth.
- Commercial Establishments:Warehousing and cold chain operators adopt containerized solar-plus-storage to hedge grid unreliability. Diesel backup providers lose service lock-in as these buyers seek multi-technology maintenance aggregators.
- Government Entities:Public buildings and military installations procure through sovereign-guaranteed tenders. Payment security attracts international EPC contractors despite broader currency convertibility restrictions.
Industrial Sectors absorb the largest share of firm capacity. Commercial Establishments show the steepest adoption curve for distributed generation.
Service Type:
Margin structure inverts between upfront installation and long-term maintenance, with lifecycle contracts capturing recurring revenue streams.
- Maintenance Contracts:Turbine servicing and panel cleaning agreements extend 10-15 years for thermal and hydro assets. Expatriate technician dependence creates downtime risk during travel restrictions.
- Installation Services:EPC contractors execute civil works, equipment mounting, and grid synchronization. Project timelines extend due to national standards body certification delays for imported components.
- Consultancy Services:Feasibility studies and grid integration planning support IPP developer entry. Regulatory navigation expertise commands premium pricing given licensing complexity.
- Financing Options:Local currency lending and Islamic finance structures address hard currency shortages. Central bank convertibility rulings directly constrain debt availability for generation assets.
Installation Services represent the largest revenue pool by transaction value. Maintenance Contracts offer the most predictable long-term cash flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Khartoum anchor Sudan's power sector workforce, with specialized technicians clustering around dam rehabilitation sites and transmission maintenance depots along the Nile corridor.
Khartoum State
Industrial load recovery in textile and cement manufacturing drives electricity demand growth. The Sudanese Electricity Regulatory Authority's feed-in tariff adjustments create procurement pathways for renewable independent power producers. Manufacturing parks in Khartoum North and Jabal Awlia expand bilateral power purchase agreements to secure voltage-stable baseload for motor drives.
Blue Nile Corridor
Agricultural processing cooperatives and rural health clinics generate distributed generation demand. Priority dispatch rules for solar and wind installations attract independent power producer development. Sennar and Damazin municipalities anchor containerized solar-plus-storage deployment for commercial offtakers hedging grid instability.
Northern Sudan
Desert irradiation levels exceeding 2,200 kWh/m² annually draw utility-scale photovoltaic developers. Dongola and Wadi Halfa municipalities concentrate land allocation negotiations for international independent power producers. Transmission voltage limitations at 400 kV constrain wheeling capacity to distant demand centers.
Red Sea Coastal Zone
Port Sudan's warehousing and cold chain operators adopt multi-technology maintenance contracts. Consistent trade wind patterns support onshore turbine feasibility studies. Foreign exchange illiquidity at the central bank delays turbine import timelines for project finance closure.
Sudan Power Market Competitive Landscape
The competitive structure tilts toward state-owned generation assets with selective international equipment and engineering participation. Thermal and hydroelectric baseload capacity remains concentrated under national utility control, while renewable development attracts independent power producer entry. Two strategic archetypes dominate: integrated state generators managing transmission voltage stabilization, and international engineering contractors executing dam rehabilitation and turbine servicing. Competitive moves center on long-term maintenance contract unbundling and containerized solar-plus-storage system deployment for industrial microgrids.
Among international engineering specialists, Siemens Energy AG and Sinohydro Corporation occupy positions reflecting distinct geographic origins and service archetypes. Siemens Energy AG exemplifies the turbine servicing infrastructure model, sustaining maintenance relationships across rotating equipment fleets. Sinohydro Corporation anchors the dam rehabilitation and hydroelectric expansion segment, leveraging civil works execution capabilities on Nile system infrastructure. Dal Group represents the distributed generation supply chain archetype, controlling diesel backup logistics for commercial offtakers in Khartoum State. These three entities illustrate the market's segmentation between equipment lifecycle services, capital-intensive civil engineering, and fuel supply chain management.
| Leading Market Players |
|---|
| Sudanese Thermal Power Generating Company |
| Sudanese Electricity Distribution Company |
| Siemens Energy AG |
| Ram Energy |
| Dal Group |
| Sinohydro Corporation |
| China National Nuclear Corporation |
| PowerChina |
| Bharat Heavy Electricals Limited |
| Others |
Value Network & Pricing Analysis
The Sudanese Electricity Regulatory Authority's priority dispatch mandate for renewable IPPs gates both qualified equipment supply and premium-tier pricing access for developers serving Khartoum State industrial parks. Foreign exchange illiquidity at the central bank compresses margins across imported component tiers while favoring locally sourced installation services.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across Sudan's power sector. Project-based EPC contracting dominates grid-tied thermal and hydro installations, while containerized solar-plus-storage systems command premium pricing through unbundled maintenance subscriptions. Price differentiation rests on certification grade from the national standards body and after-sales service bundling for turbine assets. Cost compression in thermal generation equipment is intensifying because Chinese manufacturers are displacing European suppliers in dam rehabilitation tenders. Commercial offtakers in warehousing and cold chain operations show highest price sensitivity, whereas government entities with sovereign guarantees accept elevated capital costs for delivery certainty.
Supply Chain Analysis
Warehouse-distribution layer concentration in Port Sudan anchors equipment import logistics for the national grid. Supply concentrates in China for photovoltaic panels and inverters, Germany for turbine rotating equipment, and the UAE for diesel generator sets. Raw material dependencies include polysilicon for solar arrays, copper for transmission cabling, and heavy fuel oil for thermal baseload. Single-source vulnerability runs through the central bank's foreign exchange allocation system, which blocks debt service for hard-currency-denominated generation assets. Distribution runs through state-controlled procurement channels for utility-scale projects and through Dal Group's logistics network for commercial backup power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sudan's power sector offers margin-expansion pathways as photovoltaic cost declines enable premium-tier positioning for integrated solar-plus-storage providers. The feed-in tariff framework accelerates returns for developers who qualify under the Sudanese Electricity Regulatory Authority's priority dispatch rules.
For Market Incumbents: Extend lifecycle service contracts for existing turbine fleets to lock out independent maintenance aggregators. Siemens Energy AG's servicing infrastructure provides a template for multi-decade revenue capture. Capacity addition in northern Sudan's desert solar zones defends position against emerging IPP entrants. Certification investment with the national standards body preserves import channel control. For New Entrants and Emerging Players: The price-point gap between premium containerized solar-plus-storage and economy diesel backup creates entry space for hybrid system providers. Western and southern localities with uneconomical transmission extension represent the most penetrable geography. Agricultural processing cooperatives offer a go-to-market angle through equipment leasing structures that bypass sovereign payment risk. For Investors and Strategic Acquirers: Roll-up economics work for maintenance contract aggregators because turbine servicing expertise concentrates with expatriate technician networks. The 5-10 year viability window favors platforms consolidating distributed generation supply chains. Acquisition targets should show captive diesel logistics or solar EPC execution capabilities. The signal to watch is central bank convertibility rulings that would unlock project finance for utility-scale renewable developers.| Strategic Initiative | Industry Significance |
|---|---|
| Feed-in Tariff Qualification | Priority dispatch rights from the Sudanese Electricity Regulatory Authority secure offtake certainty for solar IPPs. |
| Dam Rehabilitation Partnership | Sinohydro Corporation's Nile system execution capabilities unlock stranded hydro capacity without greenfield permitting. |
| Containerized Solar-Plus-Storage Deployment | Khartoum State manufacturers hedge grid unreliability while displacing diesel from baseload to peak shaving. |
| Multi-Technology Maintenance Aggregation | Unbundling service contracts from equipment supply captures recurring revenue from 24-hour load operators. |
| Desert Solar Land Allocation | Dongola and Wadi Halfa municipalities attract international IPPs through minimal land competition and high insolation. |
Research Methodology
Bottom-up industrial offtake modeling reconciled against top-down generation capacity tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators informed demand segmentation and regulatory interpretation. Secondary validation drew from Sudanese Electricity Regulatory Authority filings, central bank foreign exchange rulings, national standards body certification records, and regional energy development databases. Triangulation between supply-side project pipelines and demand-side manufacturing load curves calibrated volume estimates.
Input-output matrix framing connects macroeconomic drivers to segment-specific capacity additions across the projection horizon. The analytical framework models generation technology, delivery mode, customer type, and service category as core segmentation dimensions. CAGRs were derived from installed capacity buildout trajectories and industrial electricity demand elasticity. Forecast inputs include Nile flow variability for hydro output and central bank convertibility rulings for project finance availability.
Caveats apply where sovereign payment guarantees, currency convertibility shifts, or equipment import certification delays could materially shift the outlook. Forecasts reflect documented assumptions about regulatory stability and foreign exchange access. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Colombia Power Market
Power
Water Turbine Market
Power
Distributed Buoyancy Modules Market
Power
Germany Solar Inverter Market
Power
Portugal Power Market
Power
Residential Portable Inverter Generator Market
Power
Doubly Fed Induction Generator (DFIG) Market
Power
Direct Current Power System Market
Power
Iran Power Market
Power
Electric Arc Furnaces Market
Power
Russian Federation Power Market
Power
Brazil Power Market
Power
Japan Power Market
Power
Existent Gum Steam Generator Market
Power
Power Shelf Market
Power
Steam Turbine MRO Market