
 Asia-Pacific Alternating Current (AC) Drive Market | 2026-2036
Asia-Pacific Alternating Current (AC) Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Alternating Current (AC) Drive Market Outlook
CE marking under the EU's F-Gas Regulation is collapsing as a de facto gatekeeper for multinational suppliers serving Southeast Asian export-manufacturing clients. ABB Ltd leverages its integrated drive-motor-service portfolio to anchor premium positioning across Australian mining automation. Siemens AG competes through digital twin-enabled predictive maintenance software bundled with hardware contracts. Yaskawa Electric Corporation dominates servo drive applications for precision manufacturing in South Korea and Taiwan.
An alternating current (AC) drive, also termed a variable frequency drive, modulates motor speed and torque by converting fixed-frequency AC input into variable-frequency output, typically spanning 0.1 Hz to 400 Hz depending on load requirements; this enables precise process control and substantial energy recovery in centrifugal applications. Variable Frequency Drive technology leads installed base volumes across the region, though Vector Control Drive adoption accelerates in high-inertia material handling. Servo Drive systems command margin pools in electronics assembly, while Soft Starter deployments persist in cost-sensitive Water & Wastewater pump stations. Manufacturing end users represent the broadest application footprint, with HVAC Systems and Pumps together absorbing the majority of new hardware shipments.
China's MIIT enforces GB 18613 efficiency tiers that phase out IE2-class motors, directly stimulating AC drive retrofits in Shanghai and Jiangsu province industrial clusters. India's BIS certification for power electronics and Australia's MEPS standards create parallel compliance architectures that filter supplier participation. Japan's METI Top Runner program extends these efficiency mandates to imported industrial equipment. Stakeholders must monitor divergent national implementation timelines and pre-certify hardware portfolios against each jurisdiction's evolving technical specifications.
Market Dynamics
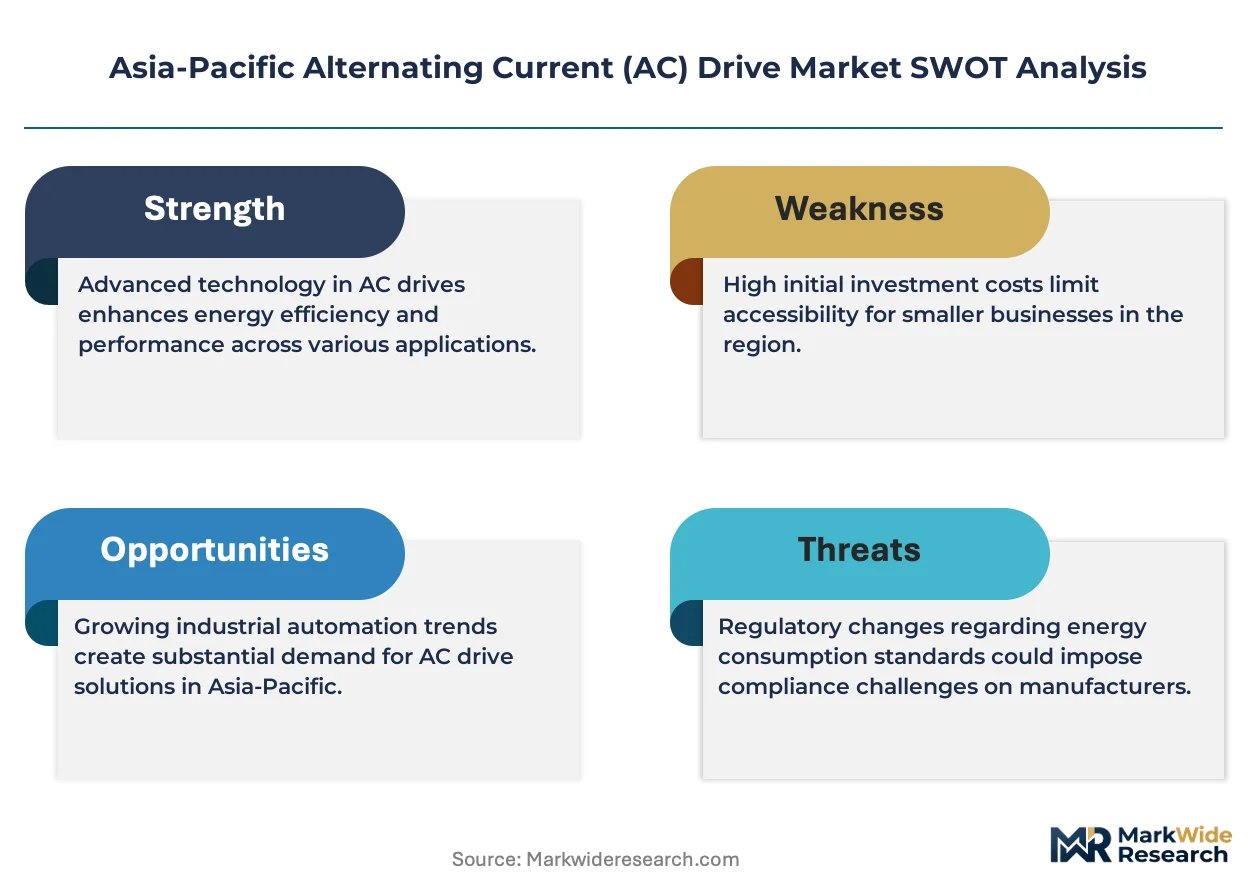
China's MIIT enforcement of GB 18613 motor efficiency tiers is compressing replacement cycles across industrial clusters in Jiangsu and Shanghai provinces, forcing synchronous AC drive upgrades as legacy IE2-class equipment phases out.
Growth Catalysts
- Water & Wastewater infrastructure:Southeast Asian utilities are deploying AC drives for energy-efficient pumping systems as urban water demand intensifies across Indonesia, Vietnam, and Thailand.
- GB standards compliance:China's MIIT efficiency mandates for motor systems are triggering hardware refresh cycles in manufacturing facilities throughout the Yangtze River Delta.
- Precision manufacturing:Servo drive adoption is accelerating in South Korean and Taiwanese electronics assembly lines for high-accuracy motion control applications.
Market Restraints
- Silicon carbide component costs:Wide-bandgap semiconductor shortages are inflating bill-of-materials for high-performance drives targeting Australian mining automation.
- Supplier concentration:Premium drive-motor integrated systems rely heavily on Japanese and German component sources, creating exposure to yen-euro volatility.
- Legacy integration friction:Vector Control Drive retrofits face compatibility barriers with existing motor winding specifications in Indian textile mills.
Strategic Opportunities
- Western India industrial corridor:Gujarat and Maharashtra states present underpenetrated demand for HVAC-integrated drive systems in pharmaceutical and chemical processing plants.
- Digital twin convergence:Predictive maintenance software bundled with hardware contracts is opening recurring revenue streams beyond equipment sales.
- Australia MEPS alignment:Stricter minimum energy performance standards are mandating drive retrofits in Queensland and Western Australia mining operations.
Industry Challenges
- Power electronics certification:India's BIS approval timelines for imported drives extend project commissioning schedules by four to six months.
- Field commissioning expertise:Shortages of certified drive technicians in Vietnam and Indonesia delay startup and optimization of water utility installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Alternating Current (AC) Drive Market |
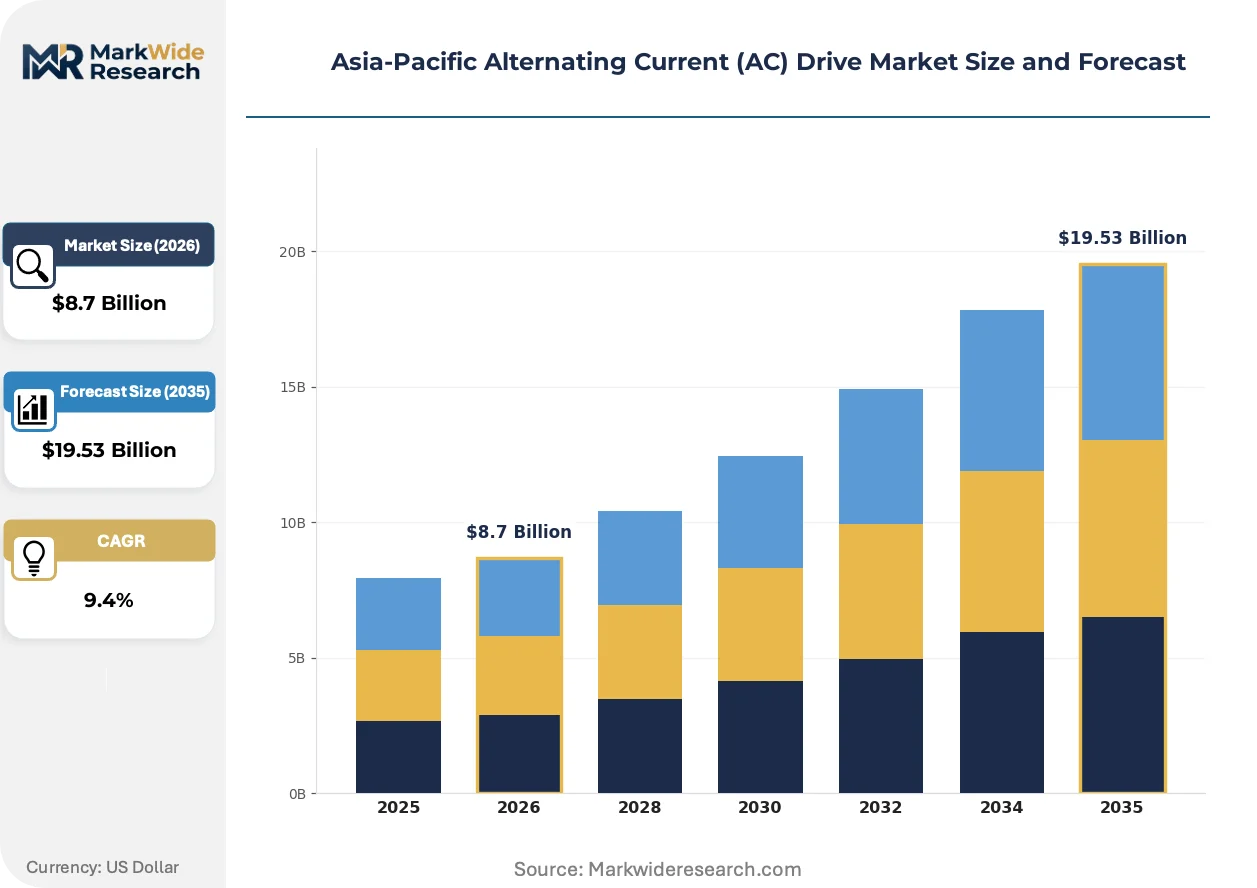
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Variable Frequency Drive, Servo Drive, Soft Starter, Vector Control Drive End User: Manufacturing, Oil & Gas, Water & Wastewater, Mining Application: Conveyor Systems, HVAC Systems, Pumps, Fans Solution: Hardware, Software, Integrated Systems, Maintenance |
| Companies Covered | ABB Ltd, Siemens AG, Danfoss Group, Schneider Electric SE, Mitsubishi Electric Corporation, Fuji Electric Co. Ltd., Yaskawa Electric Corporation, Inovance Technology, Hiconics eco-energy Technology Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Alternating Current (AC) Drive Market Strategic Shifts
Digitalization of motor control architectures is converging with efficiency mandates to reshape how industrial buyers evaluate total cost of ownership across the hardware-service boundary.
Vector Control Drive technology is supplanting scalar V/F control in high-inertia material handling applications across Chinese steel and cement plants. Mining operators in Western Australia are specifying vector drives for conveyor systems requiring precise torque control during load fluctuations. This migration is compressing margins for basic Variable Frequency Drive suppliers while elevating system integrators with motion control expertise.
Japan's METI Top Runner program is extending efficiency mandates to imported industrial equipment, compelling drive suppliers to pre-certify hardware against JIS specifications before market entry. Australian distributors are building compliance documentation libraries to accelerate customs clearance. The policy is most affecting medium-voltage drive shipments destined for Queensland coal handling facilities.
Service unbundling is disrupting traditional hardware-plus-maintenance contracts in South Korean automotive manufacturing. Tier-one suppliers are separating predictive analytics subscriptions from capital equipment purchases, forcing drive manufacturers to build software recurring revenue capabilities. This pattern is most visible in Hyundai and Kia supplier parks around Ulsan and Asan.
Asia-Pacific Alternating Current (AC) Drive Market Segmentation
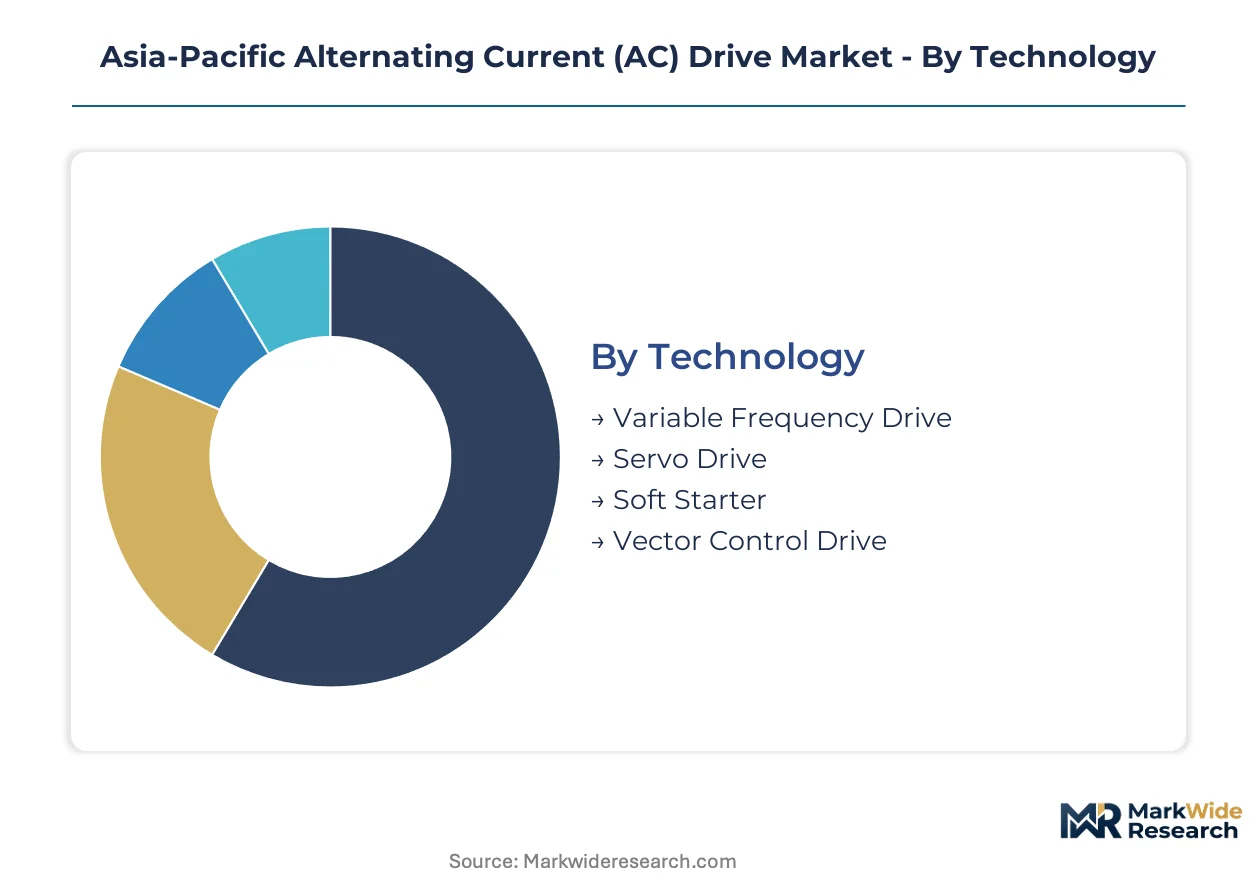
Segmentation in the Asia-Pacific AC drive market exposes how regulatory pressure, application complexity, and service economics fragment procurement patterns across industrial buyers. Understanding these fault lines reveals where hardware margins compress and where software attach rates expand.
Technology:
MIIT's GB 18613 efficiency tiers and Japan's METI Top Runner program create divergent certification burdens that reshape technology selection across Chinese and Japanese industrial clusters.
- Variable Frequency Drive:Scalar V/F control dominates installed base volumes across Southeast Asian water utilities and Indian textile mills. China's Jiangsu province manufacturing clusters absorb the majority of new VFD shipments as IE2 motor phase-outs accelerate hardware refresh cycles.
- Servo Drive:Closed-loop position control with encoder feedback enables sub-micron accuracy in South Korean electronics assembly and Taiwanese semiconductor fabrication. South Korea's Ulsan automotive supplier parks drive premium servo adoption as motion control requirements tighten.
- Soft Starter:Reduced-voltage motor starting for centrifugal pumps in Indonesian and Vietnamese water treatment facilities.
- Vector Control Drive:Field-oriented control algorithms for high-inertia conveyors in Australian iron ore operations and Chinese steel plants.
Established volume favors Variable Frequency Drive; emerging adoption favors Servo Drive.
End User:
Cost-to-serve economics concentrate supplier attention on asset-intensive sectors where downtime penalties justify premium drive-motor-service bundles.
- Manufacturing:Discrete automation across automotive, electronics, and food processing commands the broadest application footprint. India's western industrial corridor spanning Gujarat and Maharashtra states presents concentrated demand for HVAC-integrated drive systems in pharmaceutical and chemical processing.
- Mining:Australian iron ore and coal operations specify ruggedized drives for conveyor systems requiring torque control during load fluctuations. Western Australia's Pilbara region drives premium vector drive specifications as automation investments deepen.
- Oil & Gas:Downstream refining and offshore platforms in Thailand and Malaysia.
- Water & Wastewater:Municipal pumping infrastructure across Indonesia, Vietnam, and Thailand.
Manufacturing captures the widest segment breadth; Mining delivers the highest contract value per installation.
Application:
Load profile characteristics determine whether scalar control suffices or vector algorithms become mandatory.
- Pumps:Centrifugal and positive displacement configurations in water utilities and chemical processing dominate energy-efficient retrofit demand. Southeast Asian urban water intensification drives AC drive deployment for variable-speed pumping that cuts energy consumption against fixed-speed throttling.
- HVAC Systems:Fan and compressor modulation in commercial buildings and industrial climate control. India's pharmaceutical manufacturing clusters around Hyderabad and Pune mandate precise environmental control that favors drive-based fan speed regulation.
- Conveyor Systems:Bulk material handling in mining and port logistics.
- Fans:Ventilation and combustion air supply in power generation and metals processing.
Pumps lead in policy-driven replacement volume; HVAC Systems gain share fastest in green building codes.
Solution:
Procurement patterns are shifting from capital equipment purchases toward outcome-based service contracts that bundle hardware with performance guarantees.
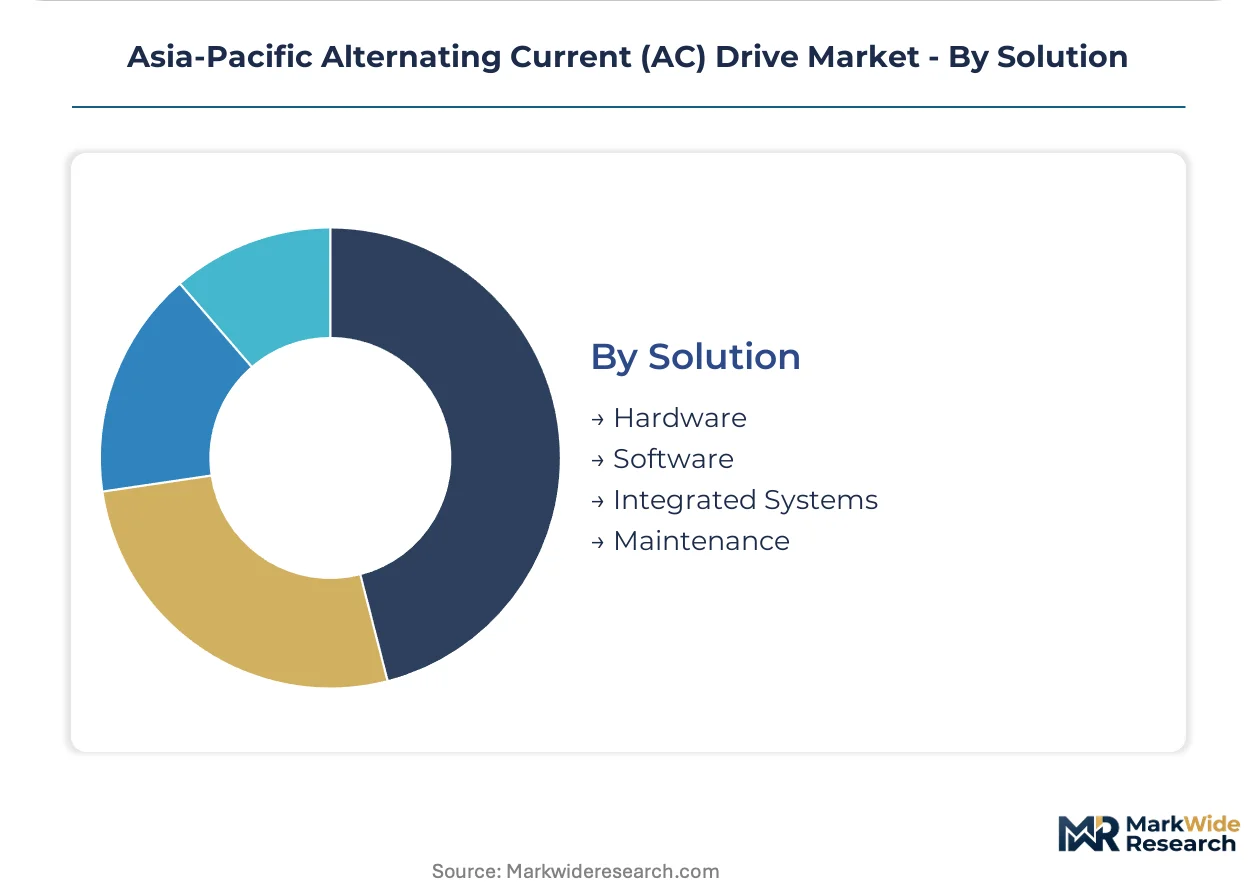
- Hardware:Standalone drive units and drive-motor combinations constitute the baseline procurement mode. Australian mining automation and Chinese steel plants specify premium hardware with extended temperature and vibration tolerances.
- Software:Digital twin-enabled predictive maintenance platforms create recurring revenue streams beyond equipment sales. South Korean automotive manufacturers around Asan unbundle analytics subscriptions from capital purchases, forcing drive suppliers to build software capabilities.
- Integrated Systems:Pre-engineered drive-motor-control packages for specific applications.
- Maintenance:Field service contracts and spare parts logistics.
Hardware retains the largest revenue share; Software expands most quickly in automotive and electronics verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT efficiency mandates and Japan's METI Top Runner program are compressing equipment replacement cycles across East Asian industrial clusters. Australia's MEPS standards and India's BIS certification create parallel compliance architectures that reshape supplier participation patterns.
China
Jiangsu and Shanghai province manufacturing clusters absorb the majority of new AC drive shipments as GB 18613 motor efficiency tiers phase out IE2-class equipment. MIIT enforcement synchronizes drive retrofits with legacy motor replacements across Yangtze River Delta textile and steel plants. Suzhou and Wuxi industrial zones drive premium vector control specifications for high-inertia material handling.
Japan
METI's Top Runner program extends efficiency mandates to imported industrial equipment, compelling pre-certification against JIS specifications. Nagoya automotive supplier parks and Osaka electronics assembly lines anchor servo drive demand for sub-micron precision motion control. Yokohama port logistics facilities specify ruggedized drives for crane and conveyor automation.
India
Gujarat and Maharashtra states present concentrated demand for HVAC-integrated drive systems in pharmaceutical and chemical processing plants. BIS certification timelines for power electronics extend project commissioning schedules by four to six months across western industrial corridors. Pune and Hyderabad manufacturing clusters mandate precise environmental control favoring drive-based fan speed regulation.
Australia
Queensland and Western Australia mining operations face MEPS-mandated drive retrofits for conveyor and pumping infrastructure. Pilbara iron ore producers specify premium vector drives requiring precise torque control during load fluctuations. Perth-based distributors build compliance documentation libraries to accelerate customs clearance for medium-voltage shipments.
South Korea
Ulsan and Asan automotive supplier parks drive unbundling of predictive analytics subscriptions from capital equipment purchases. Seoul electronics assembly lines accelerate servo drive adoption for high-accuracy motion control in semiconductor fabrication. Busan port authorities deploy energy-efficient drives for container handling crane modernization.
Asia-Pacific Alternating Current (AC) Drive Market Competitive Environment
Listed leaders compete with private specialists across integrated system bundling and software attach rates. The vendor base spans Swiss-German industrial conglomerates, Japanese precision automation houses, and emerging Chinese power electronics firms. Three archetypes dominate: full-stack drive-motor-service integrators, digital twin-enabled predictive maintenance platforms, and cost-optimized hardware specialists. Competitive moves center on strategic partnerships for silicon carbide sourcing and backward integration into power semiconductor fabrication.
Within the integrated systems tier, ABB Ltd and Siemens AG exemplify full-stack positioning through bundled hardware-service portfolios. Yaskawa Electric Corporation anchors precision motion control specialization across East Asian electronics verticals. Among China-based power electronics fabricators, Inovance Technology and Hiconics eco-energy Technology Co., Ltd. occupy positions serving domestic efficiency retrofit demand under MIIT compliance timelines.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Danfoss Group |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Fuji Electric Co. Ltd. |
| Yaskawa Electric Corporation |
| Inovance Technology |
| Hiconics eco-energy Technology Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for silicon carbide power modules concentrate pricing power with Japanese and German component suppliers serving Australian mining automation projects. This inventory compression forces drive manufacturers to absorb cost volatility or pass through to end users in premium vector control segments.
Pricing Analysis
Certification level under GB 18613 and MEPS standards creates the primary spread between premium and standard drive tiers. Three-tier pricing structure across premium, standard, and economy levels reflects compliance burden, after-sales bundling, and geographic delivery cost. Cost compression in economy-grade Variable Frequency Drives is intensifying because Chinese domestic suppliers are scaling IE3-compliant production. Water utilities in Southeast Asia exhibit highest price sensitivity; Australian iron ore operators show least sensitivity due to downtime penalty structures.
Supply Chain Analysis
Strategic stockpiling of wide-bandgap semiconductors is displacing just-in-time preferences among tier-one drive manufacturers facing Australian mining project deadlines. Component sourcing draws from Japan, Germany, and China for power modules, control boards, and enclosure materials. Single-source vulnerability concentrates in silicon carbide substrate supply from Japanese wafer fabricators. Distribution runs through authorized distributor networks with certified technician attachment for commissioning support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance software subscriptions are expanding faster than hardware sales across South Korean automotive supplier parks, repositioning AC drive procurement as a service-attach opportunity rather than capital expenditure.
For Market Incumbents: Consolidate drive-motor-service bundling to defend against unbundling pressure from digital-native entrants. Deepen backward integration into power semiconductor sourcing to mitigate yen-euro volatility exposure. Anchor premium positioning through pre-certified compliance documentation libraries for MEPS and BIS timelines. For New Entrants and Emerging Players: Differentiate on field commissioning expertise to capture delayed water utility projects in Vietnam and Indonesia. Target Gujarat and Maharashtra pharmaceutical clusters with HVAC-integrated drive packages. Lead with outcome-based energy savings contracts rather than hardware-centric proposals. For Investors and Strategic Acquirers: Long-term, this sits as a efficiency-mandate play because MIIT, METI, and MEPS regulations are structurally compressing replacement cycles. Acquisition candidates include motion control specialists with servo drive IP and established JIS certification. Watch for BIS approval timeline compression as inflection indicator for Indian market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductors | Captive silicon carbide supply secures margin control against Japanese wafer shortages. |
| Predictive Maintenance Platform Launch | Software recurring revenue offsets hardware commoditization in South Korean automotive. |
| GB 18613 Pre-Certification Investment | Early IE3 compliance lock-in captures Jiangsu province replacement wave. |
| Field Technician Certification Program | Commissioning capability shortage in Vietnam creates first-mover service advantage. |
| Digital Twin Integration Partnership | Analytics bundling mirrors Siemens and ABB positioning in Australian mining. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at industrial facilities in China, India, Australia, and Southeast Asia. Secondary validation incorporated customs trade data, MIIT efficiency standard filings, SEC 10-K disclosures from listed automation suppliers, and BIS certification registry records. Bottom-up shipment estimates triangulated against top-down industrial motor stock assessments.
Across the analysis window, value and volume outputs reflect segment-level modeling across technology type, end-user industry, application load profile, and solution bundling configuration. CAGRs derived from regression against industrial production indices, efficiency mandate implementation schedules, and energy price trajectories. Forecast inputs included MIIT enforcement intensity projections and mining automation capital commitment patterns.
Material uncertainties — silicon carbide supply disruption, BIS approval timeline volatility, and currency fluctuation in yen-euro crosses — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement continuity and industrial energy cost structures. Revision becomes warranted when wide-bandgap semiconductor capacity expansion crosses thresholds that eliminate current supply constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Malaysia Power EPC Market
Power
Residential Portable Inverter Generator Market
Power
Global Advanced Marine Power Supply Market
Power
Recloser Control Market
Power
Global Ancillary Services Power Market
Power
LNG Power Barge Market
Power
Solar UPS Market
Power
Critical Power Market
Power
Norway Power Market
Power
Mexico Power Market
Power
Modified Sine Wave Home Inverters Market
Power
Wind Alarm Controller Market
Power
Doubly Fed Induction Generator (DFIG) Market
Power
Global Marine Power Systems Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Brunei Power Market