
 Smart PV Inverters Market | 2026-2036
Smart PV Inverters Market Size, Share, and Industry Trends Forecast 2026-2036
Smart PV Inverters Market Insights
Market Context with Strategic Players
Silicon carbide (SiC) and gallium nitride (GaN) power electronics is fragmenting inverter architectures away from traditional silicon-based designs toward higher-efficiency topologies. Huawei Technologies leverages its digital power platform to dominate utility-scale string inverter deployments across Asia and the Middle East. SMA Solar Technology anchors European market presence through its specialized focus on grid-forming inverters for weak-grid environments. Enphase Energy competes in the residential micro inverter segment with integrated power electronics and module-level monitoring.
Technical Definition and Structural Segments
Smart PV inverters are power conversion systems that transform direct current (DC) from photovoltaic modules into grid-compliant alternating current (AC) while embedding bidirectional communication, grid support functions, and maximum power point tracking algorithms with efficiency ratings typically exceeding 98%. Their primary commercial purpose is to optimize energy harvest from solar arrays while enabling grid stability services such as reactive power compensation and frequency response. String inverters occupy the dominant position in commercial and utility installations due to lower balance-of-system costs and scalable redundancy. Micro inverters represent the fastest-expanding product category in residential rooftop segments where shading tolerance and module-level monitoring justify premium pricing. Hybrid connection types are capturing growing margin pools as battery storage co-deployment becomes standard in new solar installations across Europe and Australia.
Regulatory Frame and Forward-Looking Close
IEEE 1547 interconnection standards in the United States and EU grid codes under the F-Gas Regulation are mandating ride-through capabilities and harmonic distortion limits that force inverter redesign cycles. China's GB standards and NMPA certification requirements enforce efficiency tiers that disqualify lower-performing units from domestic procurement tenders. India's CEA technical standards for grid-connected solar specify fault response protocols that favor smart inverter architectures with embedded grid management functions. Stakeholders must monitor how evolving grid code harmonization between jurisdictions shapes certification burdens and product platform strategies.
Market Dynamics
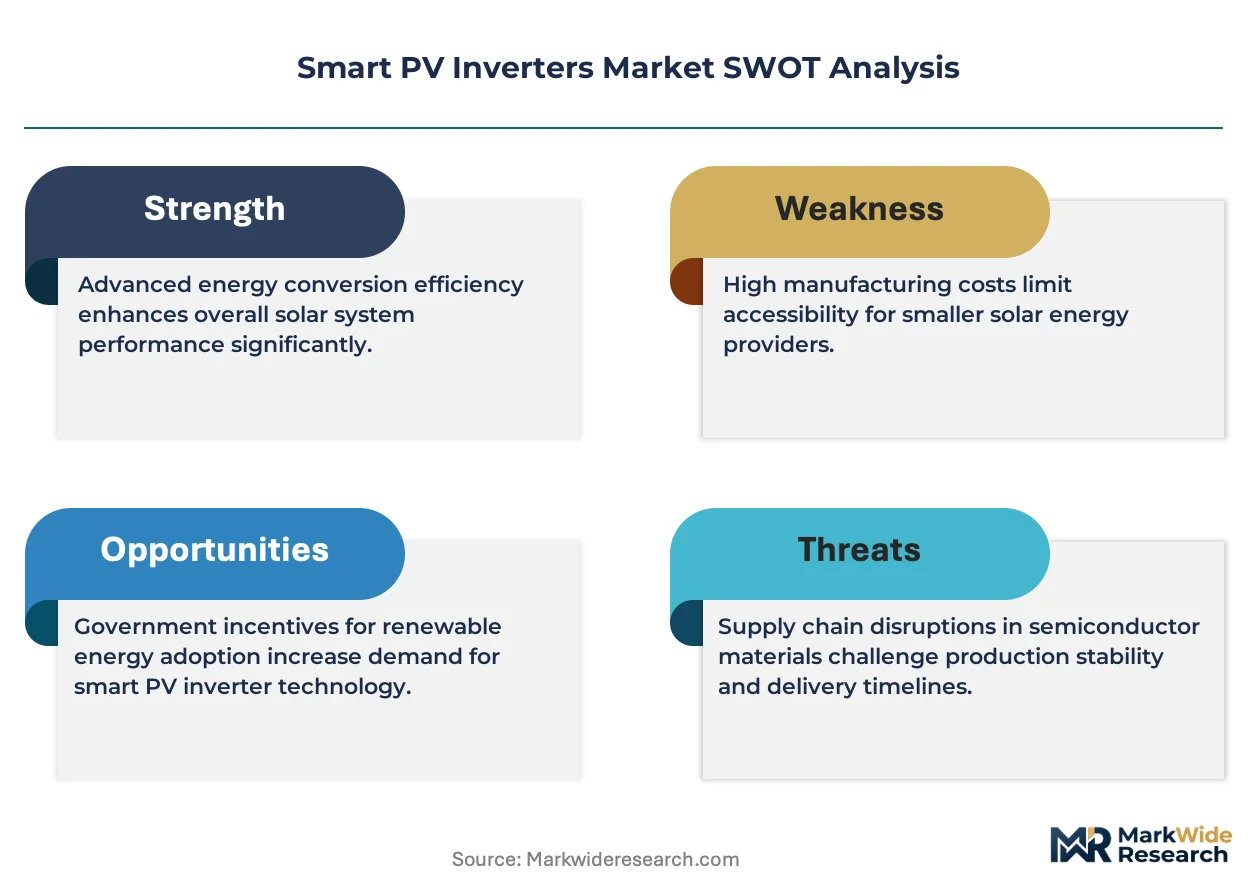
Silicon carbide power semiconductors are compressing inverter conversion losses below 1%, forcing incumbent manufacturers to retool production lines or cede margin to vertically integrated semiconductor suppliers. This materials transition rewrites cost structures across string, central, and micro inverter architectures simultaneously.
Growth Catalysts
- EU F-Gas Regulation phase-down:Fluorinated gas restrictions on switchgear insulation accelerate adoption of dry-air or vacuum-insulated inverters with embedded grid-forming capability.
- India's CEA grid codes:Mandatory fault ride-through and reactive power support specifications favor smart inverter architectures with embedded power electronics control.
- Hybrid storage co-deployment:Battery-ready inverters capture expanding installation volumes in Germany's industrial retrofit segment and Australia's residential solar-plus-storage market.
Market Restraints
- SiC substrate supply concentration:Wolfspeed, Coherent, and II-VI control over 80% of substrate capacity, creating input cost volatility and allocation risk for inverter OEMs.
- Grid code fragmentation:Divergent IEEE 1547-2018, EU 2016/631, and China's GB/T 37408-2019 certification requirements multiply testing burdens and platform complexity.
- Electrolytic capacitor lifespans:Thermal degradation in harsh climates limits warranty terms and increases service liability for utility-scale deployments in desert regions.
Strategic Opportunities
- Vietnam's PDP8 renewable targets:Utility-scale solar auctions mandate grid-interactive inverters with SCADA integration, creating first-mover advantages for certified suppliers.
- Vehicle-to-grid convergence:Bidirectional residential inverters enabling EV battery dispatch open new revenue streams in California's SGIP incentive territory and Japan's V2G demonstration zones.
- Module-level power electronics integration:Power optimizers paired with string inverters capture shading-tolerant applications in urban rooftop segments without full micro inverter cost premiums.
Industry Challenges
- Power electronics engineering scarcity:SiC and GaN device characterization expertise concentrates in semiconductor firms, forcing inverter OEMs to compete for analog design talent or outsource gate driver development.
- Multi-jurisdiction certification pipelines:Parallel UL 1741, IEC 62109, and NMPA approval tracks extend product launch timelines by 8-14 months for global platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart PV Inverters Market |
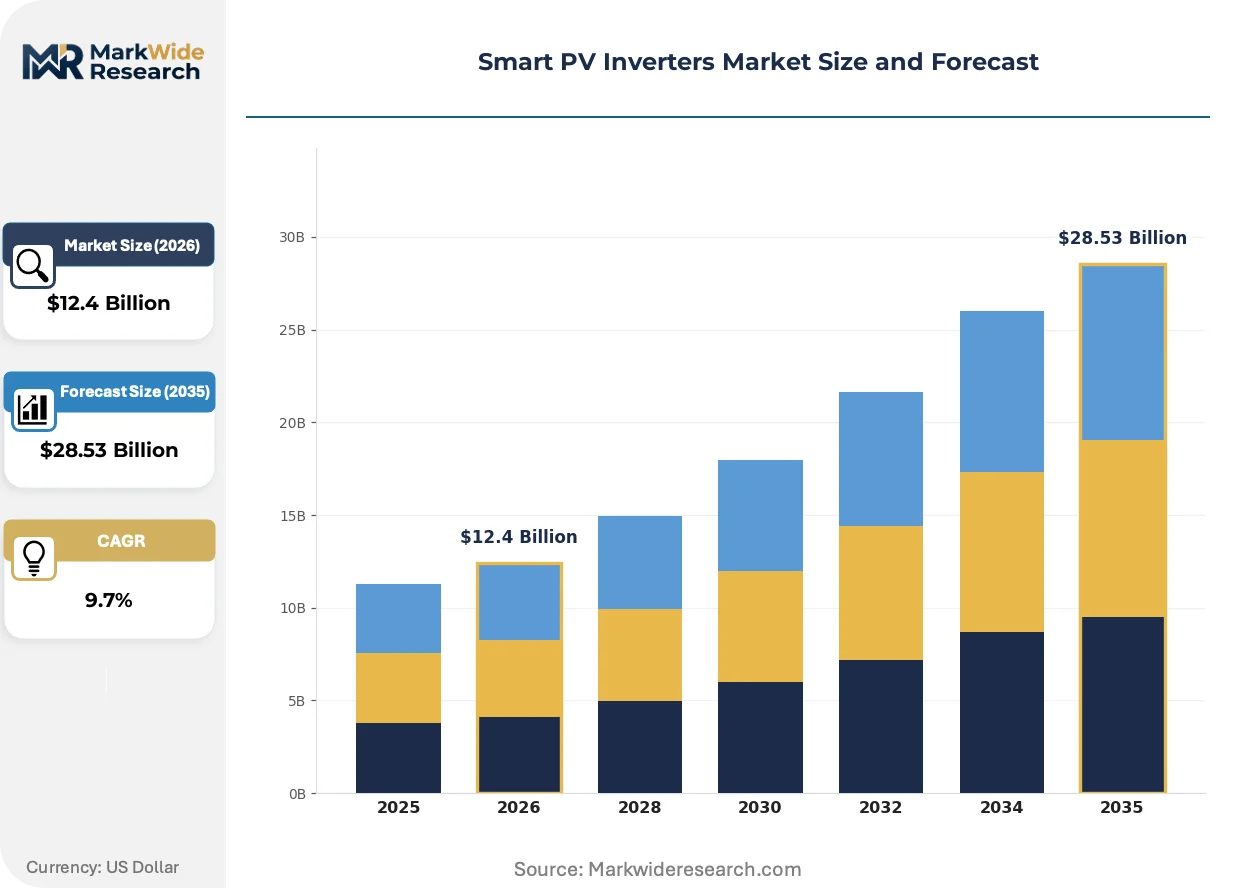
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.53 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Micro Inverters, Central Inverters, Power Optimizers Connection Type: Grid-Tied, Off-Grid, Hybrid, Standalone Control Technology: Digital Control, Analog Control, Adaptive Control, Smart Control End User: Residential, Commercial, Industrial, Utilities |
| Companies Covered | Huawei Technologies, Sungrow Power Supply, Ginlong Technologies, SMA Solar Technology, SolarEdge Technologies, Growatt New Energy Technology, GoodWe, Delta Electronics, Enphase Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart PV Inverters Market Trends and Innovations
Digital twin architectures and edge-computing capabilities are embedding intelligence directly into inverter firmware, transforming hardware-only vendors into software-defined energy platform providers. This shift compresses service margins while opening recurring revenue streams.
Wide-bandgap semiconductors are digitizing inverter thermal management and switching performance. SiC MOSFETs from Wolfspeed and Infineon enable 50kHz+ switching frequencies that shrink magnetics volume by 40%. Utility-scale developers in Texas and Saudi Arabia specify these topologies for containerized skid reductions. The technology is digitizing balance-of-system cost structures while forcing legacy IGBT supply chains into obsolescence.
China's NMPA efficiency tier mandates and dual carbon enforcement mechanisms tighten conversion-loss thresholds for domestic procurement eligibility. Manufacturers must redesign platforms to meet 99% peak efficiency benchmarks or exit state-backed tender participation. String inverter suppliers with existing SiC roadmaps capture preferential listing status in State Grid and Southern Power Grid frameworks.
Industrial buyers in Germany's Baden-Württemberg and North Rhine-Westphalia corridors now specify 15-year performance warranties with guaranteed availability clauses. EPC contractors respond by unbundling inverter supply from installation, creating direct OEM-buyer relationships that displace traditional distributor channels. This procurement evolution concentrates volume with manufacturers possessing in-house service networks.
Smart PV Inverters Market Segmentation
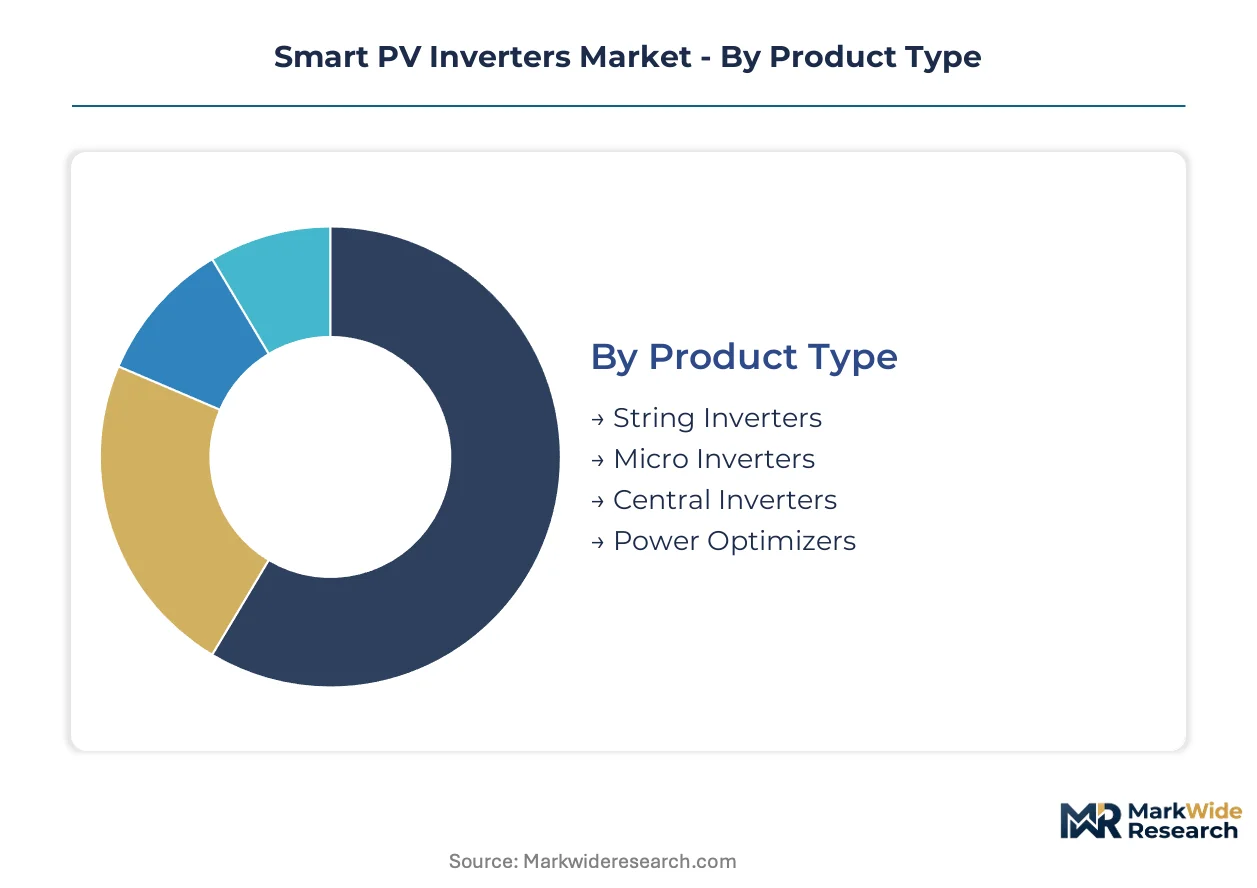
Segmentation in smart PV inverters determines warranty structures, service network density, and spare parts inventory strategies. Product architecture directly correlates with failure modes and field replacement complexity. Each segment demands distinct technical support capabilities and margin profiles.
Product Type:
After-sales-service intensity varies dramatically by product architecture, with field-replaceable units requiring different technician skill levels and response time commitments.
- String Inverters:Modular power conversion systems handling 3-150kW per unit with distributed MPPT zones and IP65 outdoor enclosures. Demand concentrates in India's utility-scale solar parks where CEA grid codes mandate remote monitoring capabilities and rapid fault response protocols.
- Micro Inverters:Module-level power electronics converting DC to AC at individual panel level with per-panel MPPT and rapid shutdown compliance. Residential installers in California's SGIP territory and Australia's solar-plus-storage retrofit segment specify these for shading tolerance and granular production visibility.
- Central Inverters:High-capacity conversion platforms exceeding 1MW per skid with integrated medium-voltage transformers and liquid cooling systems.
- Power Optimizers:DC-DC converters attached at module level performing maximum power point tracking and voltage management before string inverter aggregation.
By volume, String Inverters leads. By growth pace, Micro Inverters is ahead.
Connection Type:
Cost tier stratification follows connection complexity, with hybrid architectures commanding premium pricing for integrated battery management and bidirectional power flow.
- Grid-Tied:Single-purpose inverters synchronizing with utility frequency without energy storage capability, optimized for maximum energy export and minimal component count.
- Off-Grid:Standalone power conversion with battery charging logic and load prioritization algorithms for sites without utility interconnection.
- Hybrid:Dual-mode inverters managing solar generation, battery cycling, and grid interaction through unified power electronics and software control layers. Germany's industrial corridor retrofits and Australia's residential storage mandates are driving specification volume for battery-ready hybrid platforms.
- Standalone:Diesel-generator-synchronized or pure-renewable systems with no grid interconnection capability and specialized voltage regulation.
By installed base, Grid-Tied dominates. By margin expansion, Hybrid is climbing the fastest.
Control Technology:
Application context determines control architecture selection, with grid-forming functions and predictive maintenance algorithms driving specification shifts.
- Digital Control:DSP and FPGA-based control loops with firmware-upgradable algorithms and real-time grid parameter adjustment. Utility-scale developers in Texas and Saudi Arabia specify these for 50kHz+ SiC switching and containerized footprint reduction.
- Analog Control:Hardwired feedback circuits with fixed compensation networks and limited configurability, surviving in cost-sensitive distributed installations.
- Adaptive Control:Self-tuning algorithms modifying switching patterns and MPPT sweep rates based on irradiance variability and temperature profiles.
- Smart Control:Edge-computing platforms with digital twin integration, predictive failure detection, and autonomous grid support function activation.
By shipment volume, Digital Control leads. By technology transition velocity, Smart Control is gaining share fastest.
End User:
Customer type dictates procurement channel, warranty duration, and performance guarantee structures, with industrial buyers unbundling supply from installation.
- Residential:Single-phase or small three-phase systems under 20kW with plug-and-play installation requirements and mobile app monitoring interfaces.
- Commercial:Three-phase rooftop and carport installations from 20kW to 1MW with revenue-grade metering and demand charge management.
- Industrial:Large rooftop and ground-mount systems exceeding 1MW with power factor correction, harmonic filtering, and direct OEM service contracts. Manufacturers in Germany's Baden-Württemberg and North Rhine-Westphalia corridors now specify 15-year warranties with guaranteed availability clauses.
- Utilities:Central and string inverter deployments at solar farms with SCADA integration, fault ride-through certification, and multi-decade service agreements.
By absolute unit volume, Residential leads. By project scale and contract value, Utilities shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China-based manufacturers dominate export flows to utility-scale solar developers across India, the Middle East, and Southeast Asia. German industrial buyers source premium grid-forming inverters for weak-grid retrofit projects. Australian residential installers drive micro-inverter demand through solar-plus-storage mandates.
China
State Grid and Southern Power Grid procurement frameworks prioritize 99% peak efficiency string inverters with SiC power electronics. The National Medical Products Administration (NMPA) enforces GB/T 37408-2019 certification tiers that disqualify lower-performing units from domestic tenders. Yangtze River Delta manufacturers in Jiangsu and Zhejiang provinces scale automated production lines for utility-scale string inverter exports to India and Vietnam.
India
Central Electricity Authority (CEA) technical standards mandate fault ride-through and reactive power support for all grid-connected solar installations. Gujarat and Rajasthan host the largest concentration of utility-scale solar parks specifying remote monitoring capabilities and rapid fault response protocols. Domestic developers source string inverters with SCADA integration for 2-5GW auction blocks under the National Solar Mission.
Germany
Industrial manufacturers in Baden-Württemberg and North Rhine-Westphalia corridors specify 15-year performance warranties with guaranteed availability clauses for captive solar retrofits. The EU F-Gas Regulation phase-down accelerates adoption of dry-air insulated inverters with embedded grid-forming capability. EPC contractors unbundle inverter supply from installation, creating direct OEM-buyer relationships that displace traditional distributor channels.
United States
California's Self-Generation Incentive Program (SGIP) territory drives residential micro-inverter specifications for shading-tolerant rooftop installations. IEEE 1547-2018 interconnection standards mandate ride-through capabilities and harmonic distortion limits that force inverter redesign cycles. Texas utility-scale developers specify 50kHz+ SiC switching topologies for containerized skid reductions in merchant solar projects.
Australia
State-level solar-plus-storage mandates in New South Wales and Victoria accelerate hybrid inverter deployment for residential retrofit segments. The Clean Energy Council certification program enforces AS/NZS 4777 grid connection standards with voltage ride-through requirements. Sydney and Melbourne installers specify module-level power electronics for urban rooftop applications with complex shading profiles.
Smart PV Inverters Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent certification and service network requirements. The market structures around three tiers: vertically integrated semiconductor-inverter combinations, pure-play power electronics specialists, and diversified industrial conglomerates with renewable energy divisions. Consolidation pressures concentrate volume with manufacturers possessing in-house SiC device sourcing and multi-jurisdiction certification pipelines. Competitive moves center on backward integration into substrate supply and geographic expansion through local assembly partnerships.
Within the utility-scale string inverter tier, Huawei Technologies and Sungrow Power Supply exemplify scale-driven platform strategies. SMA Solar Technology anchors European market presence through specialized grid-forming architectures. Enphase Energy occupies the residential micro-inverter position with integrated module-level monitoring capabilities.
| Leading Market Players |
|---|
| Huawei Technologies |
| Sungrow Power Supply |
| Ginlong Technologies |
| SMA Solar Technology |
| SolarEdge Technologies |
| Growatt New Energy Technology |
| GoodWe |
| Delta Electronics |
| Enphase Energy |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Yangtze River Delta inverter manufacturing clusters is compressing supplier margins and forcing OEMs into aggressive pricing postures to maintain utilization rates, while simultaneously accelerating the shift toward SiC-based platforms that command modest premiums.
Pricing Analysis
Silicon IGBT-based string inverters trade at substantial discounts to SiC-enabled next-generation units, with the technology-generation pricing gap widening as NMPA efficiency mandates in China disqualify legacy architectures from state tender participation. Three-tier pricing structure across premium grid-forming, standard grid-tied, and economy-grade residential units separates buyers by certification tier and warranty duration. Pricing pressure stems from Wolfspeed and Coherent substrate allocation constraints that inflate input costs for SiC adopters. Residential installers in Australia's solar-plus-storage retrofit segment exhibit highest price sensitivity, while German industrial buyers in Baden-Württemberg prioritize 15-year availability guarantees over upfront cost.
Supply Chain Analysis
Export control regimes targeting wide-bandgap semiconductor manufacturing equipment are restricting technology flows to Chinese SiC substrate expansion projects, tightening global supply concentration. Production gravity centers on China, Germany, and the United States for final assembly, while raw material dependencies include high-purity silicon carbide substrates, electrolytic capacitors, and rare-earth magnetics for cooling systems. Single-source vulnerability concentrates in Wolfspeed's substrate dominance, creating allocation risk during demand surges. Distribution runs through direct OEM-buyer relationships displacing traditional distributor channels in Germany's industrial corridor, with EPC contractors unbundling supply from installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart PV inverter incumbents face substitution pressure from integrated semiconductor-inverter combinations that capture margin pools through captive SiC device supply, requiring defensive repositioning around service network density and certification breadth.
For Market Incumbents: Pre-empt SiC supply concentration risk by securing long-term substrate offtake agreements with Wolfspeed, Coherent, or II-VI before allocation windows tighten further. Anchor defensive positioning through backward integration into gate driver firmware development rather than outsourcing to semiconductor firms, preserving analog design expertise in-house against engineering talent scarcity.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's PDP8 utility-scale solar auction pipeline where grid-interactive inverter mandates with SCADA integration create certification barriers that favor nimble specialists over legacy central inverter suppliers. Target module-level power electronics paired with string inverters for urban rooftop segments in Sydney and Melbourne, leveraging shading-tolerant applications without bearing full micro inverter cost structures.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among inverter OEMs with embedded digital twin platforms and predictive maintenance contracts extending beyond hardware warranties. Long-term viability over the next decade hinges on software-defined energy platform positioning rather than pure hardware shipment volume. Monitor NMPA efficiency tier enforcement in China as the critical inflection signal—accelerated disqualification of sub-99% peak efficiency units would force consolidation among second-tier domestic suppliers unable to fund SiC platform redesigns.
| Strategic Initiative | Industry Significance |
|---|---|
| SiC Platform Redesign | NMPA efficiency mandates in China disqualify silicon IGBT architectures from state-backed tenders. |
| Grid-Forming Certification | IEEE 1547-2018 and EU 2016/631 ride-through requirements force firmware upgrades for weak-grid revenue. |
| Digital Twin Integration | Edge-computing capabilities transform hardware vendors into software-defined energy platform providers. |
| Direct OEM-Buyer Relationships | EPC channel unbundling in Germany concentrates volume with manufacturers possessing in-house service networks. |
| Substrate Supply Security | Wolfspeed and Coherent allocation risk necessitates long-term offtake agreements for SiC MOSFET access. |
Research Methodology
The analysis maps string inverter, micro inverter, central inverter, and power optimizer architectures, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators across primary interviews combined with EIA data, IEA renewable deployment reports, FERC interconnection filings, and project development databases. Secondary validation draws from SEC filings of listed power electronics firms, CEA technical standard publications, and NMPA certification registries. Bottom-up unit shipment estimates triangulate against top-down capacity installation figures from national renewable energy agencies.
Assumptions held fixed include existing IEEE 1547-2018, EU 2016/631, and GB/T 37408-2019 certification requirements throughout the projection horizon, while SiC substrate pricing trajectories and grid code harmonization timelines were varied across sensitivity scenarios. Segmentation dimensions modeled span product architecture, connection type, control technology, and end-user category with regional regulatory framework overlays. CAGRs derive from logistic diffusion curves fitted to historical deployment data with adjustment for technology substitution effects. Forecast inputs incorporate CEA fault ride-through mandate enforcement intensity and EU F-Gas Regulation phase-down pace for dry-air insulated switchgear.
Sensitivities concentrate around NMPA efficiency tier acceleration, Wolfspeed substrate allocation disruptions, and grid code harmonization between IEEE and EU frameworks that would compress multi-jurisdiction certification timelines. Forecasts reflect documented assumptions on SiC adoption curves and hybrid storage co-deployment rates. Material shifts in China's dual carbon enforcement mechanisms or India's CEA technical standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Middle-East and Africa Power Rental Market
Power
Oxy-Hydrogen Generators Market
Power
India Power Market
Power
India Uninterruptible Power Supply (UPS) Market
Power
Compact Substation Market
Power
Marine Thermal Fluid Heaters Market
Power
Iran Power Market
Power
LNG Power Barge Market
Power
Electric Power Sports Market
Power
Residential Micro Inverter Market
Power
Residential Portable Inverter Generator Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Spain Power Market
Power
Uzbekistan Power Market
Power
Australia Power Market
Power
Global Ancillary Services Power Market