
 Modular PSA Nitrogen Generator Market | 2026-2036
Modular PSA Nitrogen Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Modular PSA Nitrogen Generator Market Insights
Aftermarket service revenue is reshaping margin distribution in the modular PSA nitrogen generator space. Atlas Copco leverages its compressor service infrastructure to capture recurring maintenance contracts. Parker Hannifin anchors its position through integrated filtration and gas generation bundling. Linde competes by extending cryogenic expertise into on-site PSA retrofit advisory.
A modular PSA nitrogen generator employs carbon molecular sieve beds that selectively adsorb oxygen under elevated pressure, yielding nitrogen purities from 95% to 99.999% for industrial inerting and blanketing applications. Containerized systems dominate deployment in remote oilfield and mining camps where rapid relocation outweighs permanent installation economics. Skid-mounted systems lead pharmaceutical and electronics end-use segments due to cleanroom-compatible footprints and validated qualification protocols. Membrane separation technology occupies the portable generator niche where lower purity tolerance trades off against minimal moving parts and silent operation.
The EPA mandates leak detection and repair protocols for compressed gas systems, while OSHA enforces confined-space entry standards around nitrogen-enriched environments, elevating certified generator specification requirements. ISO 8573 purity classes shape procurement criteria for food and beverage and pharmaceutical buyers. Stakeholders must monitor evolving carbon footprint disclosure rules for on-site versus delivered nitrogen supply models.
Market Dynamics
Containerized PSA systems are compressing deployment timelines for remote oilfield operators while EPA leak-detection mandates force specification upgrades across the installed base.
Growth Catalysts
- Food packaging nitrogen flushing:Beverage bottlers in Germany's chemical corridor are eliminating chemical preservatives through inerting systems that extend shelf life without additive labeling requirements.
- OSHA confined-space standards:Tighter enforcement around nitrogen-enriched environments is mandating certified generator specifications that lock out uncertified equipment from industrial tenders.
- Carbon molecular sieve advances:Improved adsorption kinetics are pushing purity thresholds toward 99.999% for electronics-grade blanketing without cryogenic backup.
Market Restraints
- Specialized maintenance labor scarcity:Carbon molecular sieve bed replacement requires technicians certified in pressure-vessel handling, creating service bottlenecks in remote deployment zones.
- Membrane substitution in portable segments:Lower-purity membrane generators are capturing mobile applications where 95% nitrogen tolerance eliminates PSA complexity.
- Skid-mounted system capex concentration:Pharmaceutical cleanroom installations demand stainless-steel construction and IQ/OQ/PQ validation, concentrating upfront costs with single-source suppliers.
Strategic Opportunities
- Electronics manufacturing migration:Semiconductor fabrication expansion in Vietnam and Malaysia is creating demand for containerized high-purity systems where delivered nitrogen supply chains remain undeveloped.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases are accelerating refrigerant recovery system nitrogen demand for leak testing and system purging.
- Remote mining camp electrification:Off-grid solar-hybrid PSA installations are displacing liquid nitrogen trucking in Australian and Chilean extraction sites where grid extension is uneconomical.
Industry Challenges
- ISO 8573 certification timeline compression:Third-party validation for pharmaceutical and food-grade purity classes is extending procurement cycles by 4-6 months, delaying revenue recognition for system integrators.
- Legacy compressed air integration:Retrofitting PSA nitrogen generators into existing plant air systems requires pressure-drop recalculation and dryer reconfiguration, complicating brownfield deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular PSA Nitrogen Generator Market |
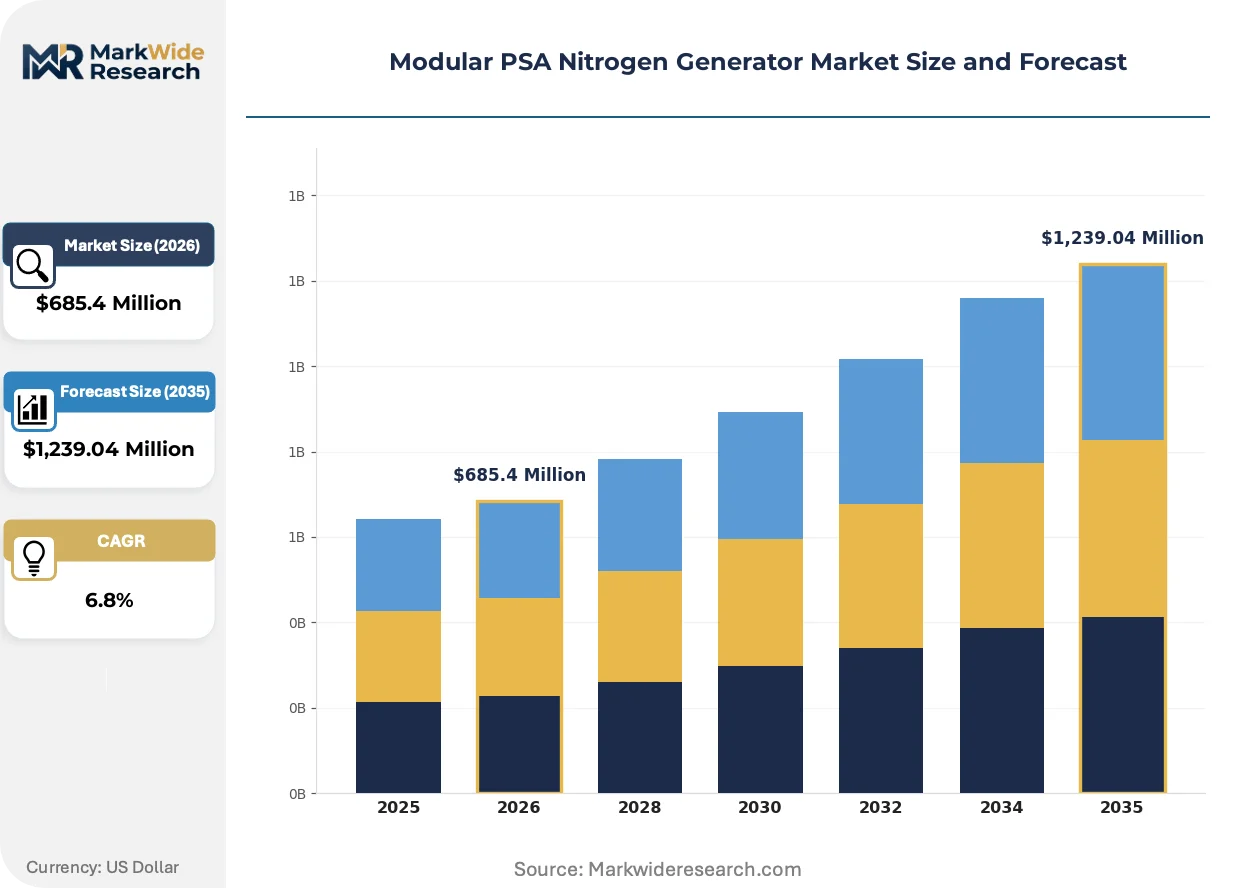
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containerized Systems, Skid-Mounted Systems, Industrial Units, Portable Generators End User: Food & Beverage, Pharmaceuticals, Electronics, Metal Fabrication Technology: Pressure Swing Adsorption, Membrane Separation, Cryogenic Distillation, Vacuum Swing Adsorption Application: Aerospace, Water Treatment, Chemical Processing, Laboratory Use |
| Companies Covered | Air Products and Chemicals, Atlas Copco, Parker Hannifin, Linde, Ingersoll Rand, Air Liquide, NOVAIR, INMATEC, Generon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular PSA Nitrogen Generator Market Trends and Innovations
Intelligent pressure-swing algorithms and predictive maintenance analytics are transforming PSA nitrogen generation from commodity equipment into digitally integrated process assets.
Advanced carbon molecular sieve formulations with engineered pore distributions are rendering obsolete the traditional purity-versus-flow trade-off that forced buyers to oversize systems. Electronics manufacturers in South Korea and Taiwan are adopting these materials to achieve 99.999% purity at 40% reduced footprint. The technology is compressing equipment room requirements for semiconductor fabs where floor space carries premium lease rates.
REACH restrictions on adsorbent material imports are forcing European PSA manufacturers to document full carbon molecular sieve supply chain provenance. The regulation is elevating compliance costs for systems serving food contact and pharmaceutical applications. German chemical processors are responding by consolidating procurement with suppliers holding ECHA-registered material certifications.
Service contract unbundling is fragmenting the traditional bundled sale model that tied generator supply to captive maintenance agreements. Oilfield operators in the Permian Basin are negotiating separate technical service agreements with independent pressure-vessel specialists, eroding OEM aftermarket margins. The practice is spreading to mining camps in Western Australia where equipment mobility favors multi-vendor service relationships.
Modular PSA Nitrogen Generator Market Segmentation
Modular PSA nitrogen generator procurement patterns diverge sharply between permanent industrial installations and mobile deployment scenarios. Buyers prioritize purity thresholds, relocation frequency, and integration complexity when matching product configurations to operational requirements.
Product Type:
Containerized systems address remote extraction sites where mobility outweighs capital efficiency, while skid-mounted configurations dominate validated manufacturing environments.
- Containerized Systems:Fully enclosed units built to ISO shipping dimensions enable rapid relocation between oilfield pads and mining camps. Australian iron ore operators deploy these systems to avoid liquid nitrogen trucking across unsealed haul roads.
- Skid-Mounted Systems:Frame-integrated assemblies with pre-piped utilities reduce cleanroom installation downtime. Pharmaceutical manufacturers in Germany's chemical corridor specify stainless-steel skids with IQ/OQ/PQ documentation packages.
- Industrial Units:Fixed-base installations serving continuous-process chemical plants with 99.9%+ purity requirements.
- Portable Generators:Compact membrane-based or miniaturized PSA units for field maintenance crews requiring 95% nitrogen at point-of-use.
Established volume favors skid-mounted systems; emerging adoption favors containerized systems.
End User:
Regulatory stringency separates food-grade inerting demand from electronics-grade blanketing requirements across customer verticals.
- Food & Beverage:Nitrogen flushing replaces chemical preservatives in packaged goods. German bottlers eliminate additive labeling through inerting systems that extend shelf life without E-number declarations.
- Electronics:Semiconductor fabs demand 99.999% purity for wafer handling and chamber purging. South Korean memory manufacturers specify containerized high-purity systems where delivered nitrogen infrastructure remains undeveloped.
- Pharmaceuticals:API manufacturing and packaging operations requiring ISO 8573 Class 1.2.1 compressed air quality with full batch documentation.
- Metal Fabrication:Laser cutting and heat treatment operations using 95-99.5% nitrogen for oxidation prevention.
Electronics and pharmaceuticals command premium pricing; food and beverage delivers scaled unit volume.
Technology:
Adsorption kinetics and membrane selectivity define the purity-versus-flow trade-offs that shape technology selection.
- Pressure Swing Adsorption:Carbon molecular sieve beds achieve 95-99.999% purity through cyclic pressure variation. Electronics manufacturers in Taiwan adopt advanced CMS formulations that compress equipment footprints by 40%.
- Membrane Separation:Hollow-fiber polymer modules deliver 95-99% purity with minimal moving parts. Mobile maintenance crews favor these systems for silent operation and field reliability.
- Cryogenic Distillation:Liquid nitrogen production for ultra-high-purity requirements exceeding PSA technical limits.
- Vacuum Swing Adsorption:Lower-pressure regeneration cycles reducing energy consumption for large-scale air separation.
PSA retains dominance in high-purity stationary applications; membrane separation gains share in portable and lower-purity segments.
Application:
Operational environment dictates certification requirements from laboratory validation to aerospace material compatibility.
- Chemical Processing:Reactor inerting and catalyst protection in Germany's Ruhr industrial cluster. EPA leak-detection mandates force specification upgrades for existing compressed gas systems.
- Aerospace:Fuel tank inerting and composite manufacturing requiring material compatibility certification. OEM specifications from Airbus and Boeing suppliers drive qualification protocols.
- Water Treatment:Membrane bioreactor aeration control and ozone generator feed gas preparation.
- Laboratory Use:Analytical instrument support and sample preservation with documented purity traceability.
Chemical processing anchors current installation base; aerospace qualification requirements create the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's chemical corridor exhibit the lowest price elasticity, accepting premium skid-mounted systems with full validation documentation, while Australian mining operators drive the hardest bargains on containerized units where liquid nitrogen trucking costs anchor willingness-to-pay.
United States
Permian Basin oilfield operators compress deployment timelines through rapid-relocation containerized systems. EPA leak-detection and repair protocols for compressed gas systems force specification upgrades across existing installations. Houston's energy corridor concentrates demand for nitrogen-enriched environment safety equipment tied to OSHA confined-space enforcement.
Germany
Beverage bottlers in the Ruhr industrial cluster eliminate chemical preservatives through nitrogen flushing systems that sidestep additive labeling requirements. REACH restrictions on carbon molecular sieve imports pressure manufacturers to document full supply chain provenance. Bavarian pharmaceutical cleanrooms specify stainless-steel skid-mounted systems with IQ/OQ/PQ validation packages.
China
Semiconductor fabrication expansion in the Yangtze River Delta generates demand for high-purity containerized systems where delivered nitrogen infrastructure remains undeveloped. MIIT industrial gas handling standards tighten certification requirements for electronics-grade applications. Shenzhen electronics manufacturers adopt advanced carbon molecular sieve formulations to compress equipment footprints.
Australia
Iron ore operators in Western Australia deploy containerized PSA systems to avoid liquid nitrogen trucking across unsealed haul roads. Off-grid solar-hybrid installations displace delivered supply in remote extraction sites where grid extension proves uneconomical. Perth-based mining camps favor multi-vendor service relationships that erode traditional OEM aftermarket margins.
Modular PSA Nitrogen Generator Market Competitive Landscape
Capability concentration sits with specialized gas technology developers; scale advantage sits with diversified industrial equipment conglomerates. The market structures around three tiers: cryogenic heritage players extending into on-site generation, compressor OEMs leveraging service infrastructure for recurring revenue capture, and independent PSA specialists competing on purity customization. Dominant competitive moves include strategic partnerships for regional distribution access and technology licensing agreements for carbon molecular sieve formulation advances.
Within the diversified industrial tier, Atlas Copco and Ingersoll Rand exemplify scale-driven positioning through compressor service network extension into generator maintenance contracts. Among European gas technology specialists, Linde occupies a position bridging cryogenic heritage with PSA retrofit advisory, while Air Liquide represents the industrial gas incumbent archetype. Parker Hannifin anchors the integrated systems vector through filtration and gas generation bundling.
| Leading Market Players |
|---|
| Air Products and Chemicals |
| Atlas Copco |
| Parker Hannifin |
| Linde |
| Ingersoll Rand |
| Air Liquide |
| NOVAIR |
| INMATEC |
| Generon |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in German carbon molecular sieve manufacturing is compressing lead times for pharmaceutical-grade systems and hardening supplier pricing power against cost-sensitive mining buyers in remote deployment zones.
Pricing Analysis
Long-term offtake contracts dominate procurement for continuous-process chemical plants, while project-based pricing prevails in containerized deployments for oilfield and mining mobility requirements. Price differentiation hinges on ISO 8573 certification tier and stainless-steel construction grade, with pharmaceutical cleanroom specifications commanding substantial premiums over standard industrial units. Pricing pressure stems from membrane substitution in portable segments where 95% purity tolerance eliminates PSA complexity. Australian mining operators exhibit the highest price sensitivity, benchmarking against liquid nitrogen trucking costs, while German chemical processors accept premium positioning for validated skid-mounted systems.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for carbon molecular sieve procurement, forcing manufacturers to qualify secondary sourcing corridors. Manufacturing concentrates in Germany, China, and the United States, with specialized pressure-vessel fabrication anchored in the Ruhr industrial cluster and advanced CMS formulation centered on Chinese chemical parks. Raw material dependencies span activated carbon feedstocks, specialty steel alloys for pressure vessels, and precision valve assemblies. Distribution runs through OEM-direct channels for large industrial installations and specialized gas equipment distributors for mid-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue layers are expanding faster than hardware sales as oilfield operators unbundle maintenance contracts and mining camps favor multi-vendor technical service agreements.
For Market Incumbents: Insulate recurring revenue streams by capturing carbon molecular sieve bed replacement contracts before independent pressure-vessel specialists penetrate remote deployment zones. Deepen backward integration into CMS formulation to offset REACH documentation burdens and lock out emerging competitors lacking ECHA-registered material certifications. Prioritize certification investment in ISO 8573 Class 1.2.1 validation capabilities to defend pharmaceutical segment positioning against cryogenic heritage players extending into PSA retrofit advisory. For New Entrants and Emerging Players: Vietnamese semiconductor fabrication corridors represent the most penetrable white-space target, where delivered nitrogen infrastructure remains undeveloped and containerized high-purity demand outpaces local supply capability. Target off-grid solar-hybrid PSA installations in Chilean mining extraction sites, where grid extension economics favor modular generation over liquid nitrogen trucking. Lead with project-based go-to-market positioning that emphasizes rapid deployment timelines and independent service relationships rather than bundled OEM captive maintenance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across containerized system manufacturing as standardized ISO-dimension enclosures displace custom engineering. Long-term viability favors acquisition targets with established aftermarket service density in remote extraction geographies rather than pure hardware manufacturers lacking maintenance contract portfolios. Watch for inflection signals in carbon molecular sieve import restriction enforcement across European jurisdictions, which would accelerate consolidation toward suppliers with documented supply chain provenance.| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Unbundling | Independent pressure-vessel specialists are eroding OEM captive maintenance margins in Permian Basin oilfields. |
| Carbon Molecular Sieve Backward Integration | In-house CMS formulation control defends against REACH supply chain documentation requirements in European pharmaceutical markets. |
| Containerized System Standardization | ISO-dimension enclosure platforms compress manufacturing costs and accelerate relocation timelines for remote mining operators. |
| Solar-Hybrid Electrification Partnerships | Off-grid renewable integration opens Australian and Chilean extraction sites previously uneconomical for PSA deployment. |
| ISO 8573 Certification Acceleration | Third-party validation capabilities shorten procurement cycles for pharmaceutical buyers facing 4-6 month documentation delays. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, aftermarket service heads, and OEM procurement teams anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation drawn from EPA enforcement records, OSHA confined-space incident reports, ECHA REACH registration databases, and industrial gas trade association filings. Bottom-up unit economics modeling triangulated against top-down market sizing across product configuration, end-use vertical, purity tier, and geographic deployment clusters.
Scenario-bracketing framed the analytical approach, with growth trajectories tested against regulatory acceleration, membrane substitution thresholds, and remote electrification adoption curves. Segmentation dimensions spanned product mobility class, end-use regulatory stringency, purity specification tier, and regional infrastructure maturity. CAGRs derived from installed base expansion rates, replacement cycle compression, and purity threshold escalation patterns in electronics manufacturing. Forecast inputs incorporated carbon molecular sieve adsorption kinetics advances and solar-hybrid system cost curves for off-grid deployments.
Practitioners should monitor EPA leak-detection enforcement intensity, REACH adsorbent import restriction expansion, and semiconductor fabrication geographic migration for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Recloser Control Market
Power
Sudan Power EPC Market
Power
Europe Frequency Converter Market
Power
Brunei Power Market
Power
Rotating Phase Converter Market
Power
North America Microturbine Market
Power
Harmonic Filter Market
Power
LNG Power Barge Market
Power
India Uninterruptible Power Supply (UPS) Market
Power
Nigeria Power Market
Power
Existent Gum Steam Generator Market
Power
Critical Power Market
Power
Italy Power Market
Power
Europe Solar Inverter Market
Power
Resonant Power Converters Market
Power
Smart PV Inverters Market