
 Uzbekistan Power Market | 2026-2036
Uzbekistan Power Market Size, Share, and Industry Trends Forecast 2026-2036
Uzbekistan Power Market Analytics
Decentralized solar photovoltaic integration is tilting Uzbekistan's generation mix away from centralized thermal plants. ACWA Power anchors the utility-scale solar pipeline through independent power producer agreements with the national grid operator. Masdar Clean Energy Company leverages its engineering expertise to deliver photovoltaic projects under the government's competitive tender program. RusHydro PAO sustains its position in the small-hydro segment through equipment supply and technical cooperation.
Uzbekistan power encompasses electricity generation, transmission, distribution, and retail services across a network operating at 110-500 kV for backbone transmission and 0.4-10 kV for last-mile distribution, serving industrial, residential, and agricultural loads. Generation by technology shows thermal plants still dominate installed capacity, yet solar is expanding fastest under auction-driven procurement. Distribution by end user reveals industrial consumers concentrate the highest load densities around Tashkent, Navoi, and the Fergana Valley, creating margin pools for grid modernization investments.
The Ministry of Energy and the State Inspectorate for Energy Supervision enforce grid connection codes and technical standards that determine project bankability and market access for new entrants. Uzbekistan's adoption of renewable energy auction regulations and net metering provisions shapes how distributed solar developers structure power purchase agreements. Stakeholders must monitor how fuel price liberalization and carbon accounting requirements from multilateral lenders reshape project finance terms for new capacity additions.
Market Dynamics
Auction-driven renewable procurement is compressing development timelines and forcing incumbent thermal operators to restructure fuel supply contracts. The Ministry of Energy's competitive tender framework has shifted project economics toward levelized cost optimization rather than capacity payments.
Growth Catalysts
- Renewable Energy Auction Regulations:Uzbekistan's competitive tender framework awards long-term power purchase agreements to lowest-cost solar bidders. Industrial offtakers in Navoi and Tashkent regions secure fixed-price electricity through these indexed contracts.
- Fergana Valley Load Growth:Agricultural processing and textile manufacturing clusters are expanding electricity demand. Distribution utilities are reinforcing 110 kV substations to serve these load centers.
- Grid Modernization Mandates:The State Inspectorate for Energy Supervision enforces updated grid codes requiring automated metering infrastructure and reactive power compensation at new interconnection points.
Market Restraints
- Gas Price Volatility:Thermal generation still supplies the majority of Uzbekistan's electricity. Domestic gas allocation policies create fuel cost uncertainty for combined-cycle operators.
- Transmission Bottlenecks:Aging 220-500 kV corridors constrain renewable energy evacuation from western solar zones to eastern demand centers. Reinforcement requires multi-year capital programs.
- Limited Local EPC Capacity:Engineering and construction capabilities for utility-scale photovoltaic plants concentrate with international developers. Domestic contractors lack experience in high-voltage direct current substation integration.
Strategic Opportunities
- Karakalpakstan Solar Zones:The autonomous republic offers high irradiance and available land for gigawatt-scale photovoltaic development. Transmission extensions from these sites could supply export markets.
- Net Metering Expansion:Regulatory provisions for distributed solar behind-the-meter installations remain underutilized. Commercial and industrial facilities in Samarkand and Bukhara could deploy rooftop systems.
- Green Hydrogen Pilots:Surplus renewable electricity from auction-priced solar projects could feed electrolyzer demonstrations. The Ministry of Energy has signaled interest in hydrogen export corridor studies.
Industry Challenges
- Grid Code Compliance Timelines:New solar projects must complete frequency response and fault ride-through testing before commercial operation. Certification delays at the State Inspectorate for Energy Supervision extend commissioning schedules.
- Legacy SCADA Integration:Uzbekenergo's existing control systems require protocol upgrades to manage variable renewable inflows. Retrofit costs fall on developers through connection agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uzbekistan Power Market |
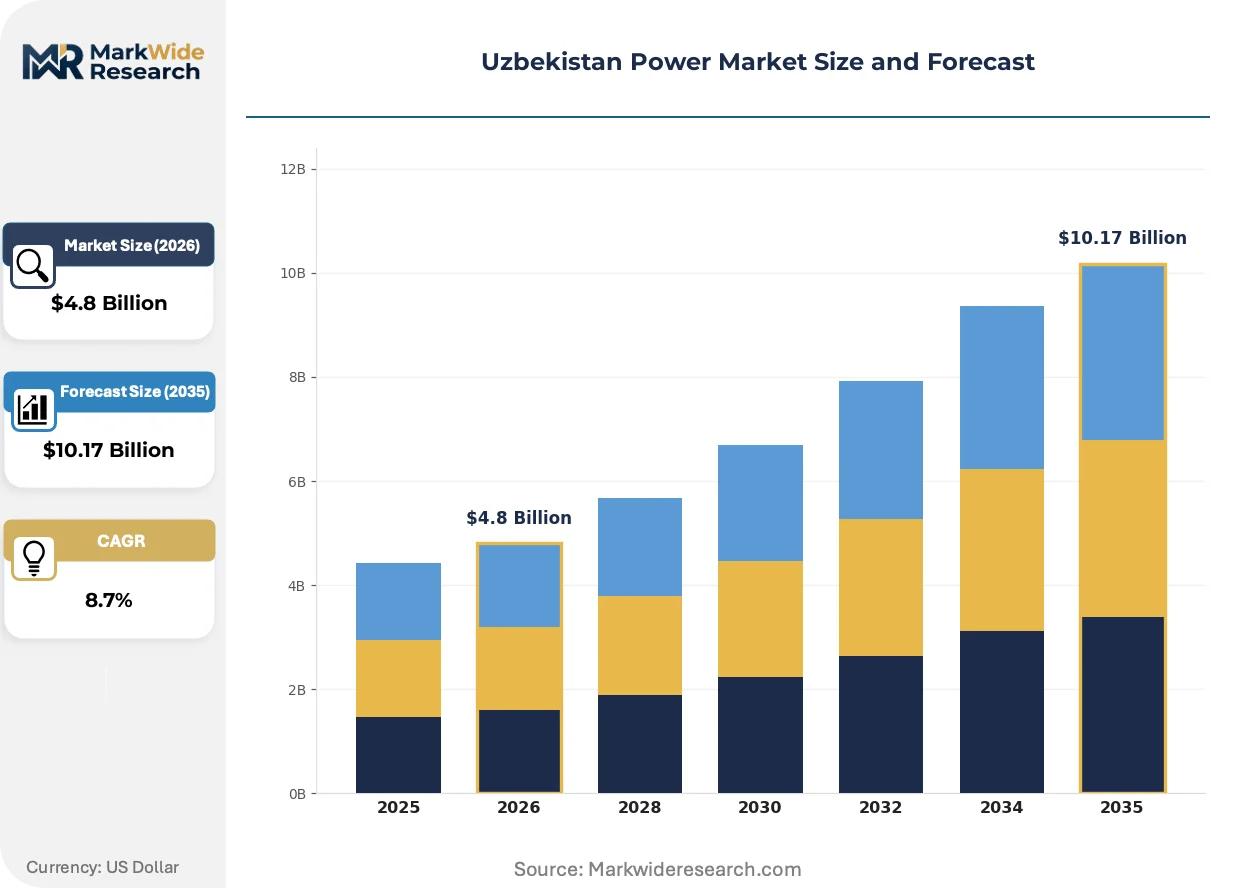
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Generation, Transmission, Distribution, Retail Technology: Hydroelectric, Solar, Wind, Thermal End User: Residential, Industrial, Commercial, Agricultural Fuel Type: Natural Gas, Coal, Renewables, Oil |
| Companies Covered | Total Eren, SkyPower Global, Masdar Clean Energy Company, RusHydro PAO, Rosatom State Corporation, Mitsubishi Heavy Industries Ltd, Helios Energy Ltd, National Electric Grid of Uzbekistan JSC, ACWA Power, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uzbekistan Power Market Evolving Landscape
Digital substation architectures and predictive maintenance platforms are reconfiguring how Uzbekistan's grid operator manages asset performance. These technologies compress outage durations and enable higher renewable penetration without synchronous spinning reserve.
Virtualized protection and control systems are replacing electromechanical relay panels in new 220 kV substations. ACWA Power and Masdar Clean Energy Company specify IEC 61850-compliant architectures in their engineering requirements. This technology is virtualizing hardware redundancy, reducing substation footprints by sixty percent and cutting civil works costs for greenfield solar interconnection points.
The Ministry of Energy's renewable energy auction regulations now incorporate domestic content requirements for module assembly and civil works. Developers must document local subcontractor participation to qualify for tariff escalation protections. Project sponsors are responding by partnering with Uzbek construction firms for mounting structure fabrication and site preparation, transferring technical knowledge through joint venture structures.
Industrial offtakers in the Tashkent region are negotiating behind-the-meter solar installations under net metering provisions rather than relying solely on grid supply. Food processing and chemical manufacturers are prioritizing power purchase agreements with fixed escalation rates over volatile gas-indexed tariffs. This behavioral shift is most visible among export-oriented firms seeking carbon disclosure compliance for European supply chain contracts.
Uzbekistan Power Market Segmentation
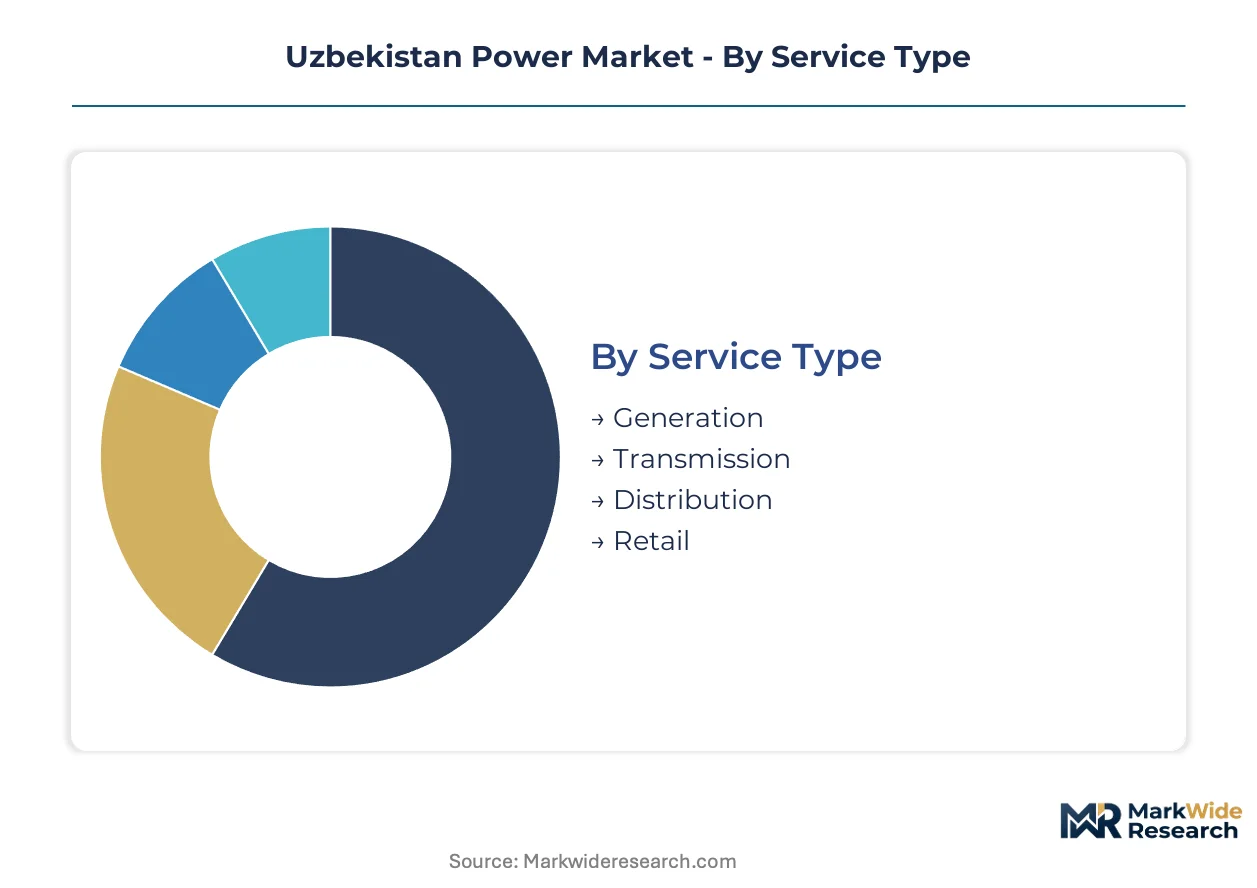
Segmentation reveals how Uzbekistan's power infrastructure serves divergent load profiles across generation technologies and consumer classes. Each dimension exposes distinct investment requirements and regulatory exposure for market participants.
Service Type:
Generation through retail delivery spans radically different capital intensities and margin structures across the value chain.
- Generation:Centralized power plants convert fuel or renewable resources into electricity at 110-500 kV transmission voltages. Solar auction winners ACWA Power and Masdar anchor new capacity additions in Karakalpakstan and Navoi regions, displacing aging gas-fired units.
- Transmission:High-voltage backbone networks at 220-500 kV evacuate bulk power from generation zones to load centers. The State Inspectorate for Energy Supervision mandates automated metering and reactive power compensation at new interconnection points, raising capital requirements for developers.
- Distribution:Medium and low-voltage networks at 0.4-110 kV deliver electricity to final consumers across urban and rural territories. Reinforcement of 110 kV substations in the Fergana Valley addresses agricultural processing load growth.
- Retail:Customer-facing sales and billing operations serve residential, industrial, and commercial accounts. Industrial offtakers in Tashkent negotiate behind-the-meter solar under net metering provisions to hedge against volatile gas-indexed tariffs.
Established volume favors Generation; emerging adoption favors Retail.
Technology:
Technology mix determines exposure to fuel price volatility and carbon accounting requirements from multilateral lenders.
- Thermal:Natural gas-fired combined-cycle and steam turbine plants dominate installed capacity. Domestic gas allocation policies create fuel cost uncertainty for operators, compressing margins when global LNG prices spike.
- Solar:Photovoltaic arrays convert high irradiance in western regions into electricity for auction-backed power purchase agreements. Competitive tenders have shifted project economics toward levelized cost optimization rather than capacity payments.
- Hydroelectric:Run-of-river and small-hydro installations provide dispatchable renewable generation. RusHydro PAO sustains equipment supply and technical cooperation in this segment.
- Wind:Onshore turbines capture wind resources in elevated terrain. Limited development to date reflects lower resource quality compared to solar zones.
Thermal retains dominant share; solar climbs the fastest under auction-driven procurement.
End User:
Demand concentration varies sharply by geography and load density across consumer categories.
- Industrial:Heavy manufacturing, mining, and chemical processing clusters concentrate around Tashkent, Navoi, and the Fergana Valley. Export-oriented firms seek fixed-price electricity and carbon disclosure compliance for European supply chain contracts.
- Residential:Urban households in Tashkent and regional capitals drive consumption growth through appliance penetration. Tariff subsidies for low-income consumers strain distribution utility finances.
- Commercial:Retail, hospitality, and office buildings in Samarkand and Bukhara present rooftop solar deployment opportunities under net metering provisions.
- Agricultural:Irrigation pumping and processing facilities in the Fergana Valley expand electricity demand as cotton and fruit exports grow.
Industrial load centers command highest margins; commercial distributed generation gains share fastest.
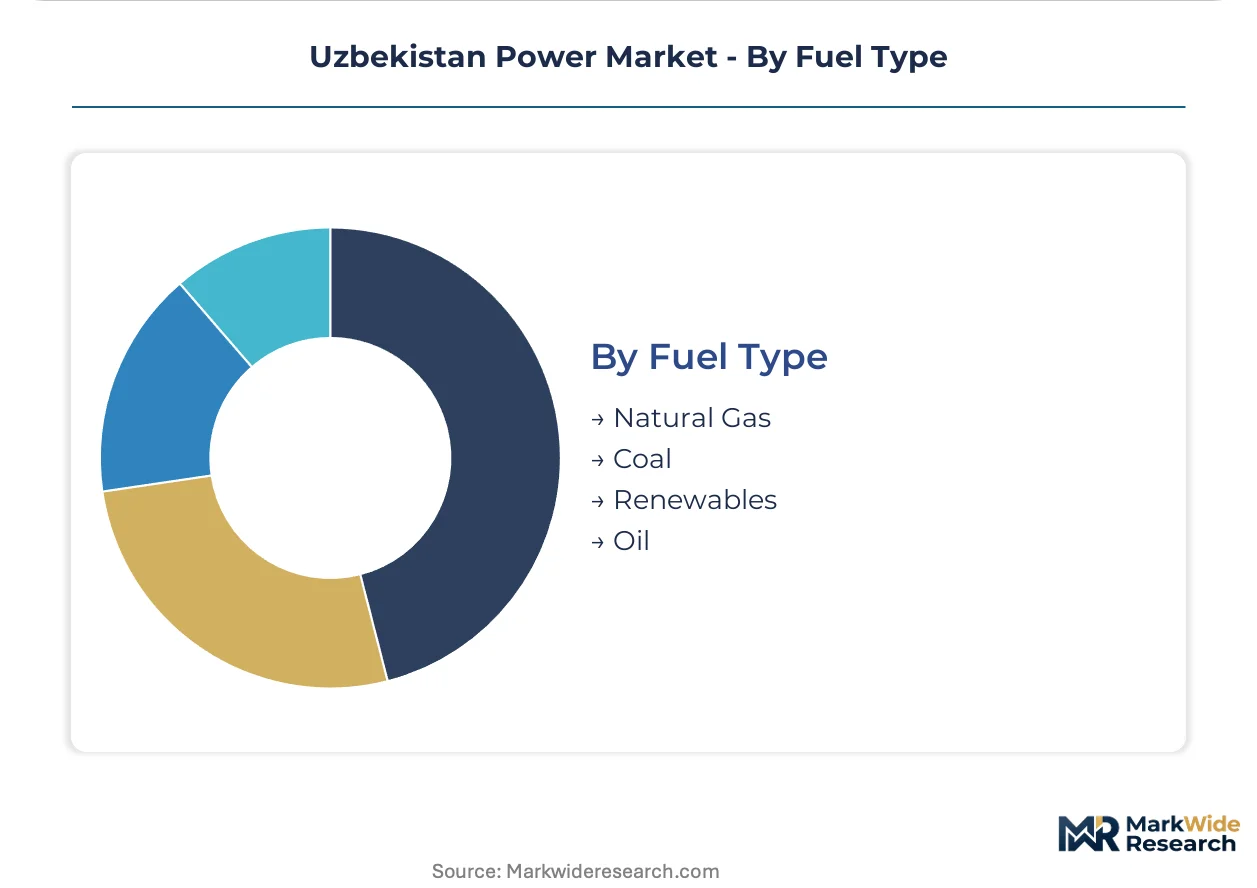
Fuel Type:
Fuel sourcing shapes project finance terms and exposure to price liberalization policies.
- Natural Gas:Domestic production feeds the majority of thermal generation capacity. Price volatility and allocation uncertainty constrain long-term planning for combined-cycle operators.
- Renewables:Solar and hydro resources carry zero fuel cost and attract concessional financing from multilateral development banks. Auction regulations incorporate domestic content requirements for module assembly.
- Coal:Limited lignite deposits support small-scale thermal units in regional industrial zones. Carbon accounting requirements from international lenders restrict new project finance.
- Oil:Diesel and heavy fuel oil serve remote generation and backup power applications. High delivered costs limit economic viability for grid-connected capacity.
Natural gas dominates dispatch; renewables attract capital inflows fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Uzbekistan exports electricity to neighboring Central Asian republics through synchronized grid interconnections with Kazakhstan, Kyrgyzstan, and Tajikistan. The country imports surplus hydropower from Kyrgyzstan during summer irrigation releases. Cross-border transmission corridors at 220-500 kV enable seasonal power swaps that balance regional supply-demand imbalances.
Tashkent Region
Industrial manufacturing and data center investments are expanding electricity demand in Uzbekistan's capital region. The Ministry of Energy enforces grid connection codes requiring reactive power compensation at new interconnection points. Chirchiq and Angren industrial zones host chemical and metallurgical facilities negotiating behind-the-meter solar installations.
Navoi Region
Mining operations and gold processing facilities consume high-density loads requiring reliable baseload supply. The State Inspectorate for Energy Supervision mandates automated metering infrastructure for large industrial consumers. Zarafshan and Uchkuduk mining clusters are securing fixed-price renewable power purchase agreements to hedge volatile gas-indexed tariffs.
Karakalpakstan
High solar irradiance and available desert land attract gigawatt-scale photovoltaic development. Renewable energy auction regulations award long-term contracts to lowest-cost bidders for projects in this autonomous republic. Nukus and Kungrad districts host solar zones where ACWA Power and Masdar anchor utility-scale capacity additions.
Fergana Valley
Agricultural processing and textile manufacturing clusters drive electricity demand growth across Namangan, Fergana, and Andijan provinces. Distribution utilities are reinforcing 110 kV substations to serve expanding load centers. Margilan and Kokand industrial zones concentrate cotton ginning and fruit processing facilities with rising power requirements.
Bukhara Region
Historical tourism infrastructure and emerging commercial real estate create distributed generation opportunities. Net metering provisions for rooftop solar remain underutilized in commercial buildings. Bukhara city and Kagan district present deployment potential for behind-the-meter photovoltaic systems serving hospitality and retail loads.
Uzbekistan Power Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Uzbekistan's power sector. State-backed utilities dominate transmission and distribution infrastructure through National Electric Grid of Uzbekistan JSC. International independent power producers capture generation capacity through auction-backed power purchase agreements. Three archetypes define competitive positioning: integrated state utilities, foreign renewable developers, and equipment-technology providers. Dominant competitive moves include strategic partnerships for local content compliance and technology licensing for grid modernization.
Among Saudi Arabia-based independent power producers, ACWA Power anchors the utility-scale solar pipeline through competitive auction wins. Masdar Clean Energy Company, originating from Abu Dhabi's sovereign wealth structures, occupies a position exemplifying engineering-led project delivery under government tender programs. RusHydro PAO represents the small-hydro equipment and technical cooperation archetype. These three entities sit within distinct strategic tiers: ACWA Power at the scale-driven auction tier, Masdar at the technology-execution tier, and RusHydro at the specialized equipment tier.
| Leading Market Players |
|---|
| Total Eren |
| SkyPower Global |
| Masdar Clean Energy Company |
| RusHydro PAO |
| Rosatom State Corporation |
| Mitsubishi Heavy Industries Ltd |
| Helios Energy Ltd |
| National Electric Grid of Uzbekistan JSC |
| ACWA Power |
| Others |
Value Network & Pricing Analysis
Gas price volatility creates fuel cost uncertainty that compresses margins for thermal operators while simultaneously widening the auction-driven pricing spread between renewable and fossil-based generation tiers. This risk vector determines how ACWA Power and Masdar structure indexed power purchase agreements and how domestic EPC contractors price civil works for solar interconnection points.
Pricing Analysis
The thermal-to-solar pricing gap separates legacy gas-indexed tariffs from auction-backed renewable contracts. Uzbekistan's power sector runs on a contract-based long-term offtake model where the Ministry of Energy awards fixed-price agreements to lowest-cost solar bidders. Price differentiation rests on technology vintage and grid connection tier, with automated metering infrastructure and reactive power compensation requirements adding capital premiums. Pricing pressure stems from competitive tender compression as international developers underbid domestic thermal operators. Industrial offtakers in Navoi and Tashkent exhibit lowest price sensitivity due to carbon disclosure compliance requirements, while agricultural processors in the Fergana Valley face highest sensitivity to tariff escalation.
Supply Chain Analysis
Extended payment terms from multilateral development banks enable Chinese and South Korean module manufacturers to anchor photovoltaic supply contracts. Uzbekistan's solar buildout draws from polysilicon feedstock concentrated in China, inverter electronics from Germany and China, and mounting structures fabricated through domestic joint ventures. Single-source vulnerability concentrates in high-voltage direct current substation equipment where European and Japanese suppliers dominate. Distribution runs through National Electric Grid of Uzbekistan JSC's transmission backbone, with ACWA Power and Masdar managing downstream interconnection through engineering-procurement-construction contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Uzbekistan's power market sits at an inflection where renewable auction regulations are displacing gas-dependent generation economics, creating asymmetric returns for early movers in solar development.
For Market Incumbents: Entrench transmission and distribution control through accelerated grid code compliance investments at the State Inspectorate for Energy Supervision. National Electric Grid of Uzbekistan JSC should prioritize reactive power compensation upgrades at 220 kV substations to maintain interconnection gatekeeper status against independent power producer vertical integration threats. For New Entrants and Emerging Players: Establish a beachhead in Karakalpakstan's gigawatt-scale solar zones where land availability and irradiance metrics exceed competing Central Asian markets. Target commercial and industrial behind-the-meter installations in Samarkand and Bukhara under net metering provisions, deploying a direct sales model to export-oriented textile and food processing firms seeking fixed-price electricity. For Investors and Strategic Acquirers: The market sits at a buildout phase that favors engineering-led independent power producers with demonstrated auction execution capability. Long-term viability over the next decade hinges on securing offtake agreements before grid interconnection bottlenecks intensify. Watch for Ministry of Energy signals on green hydrogen pilot funding as an inflection indicator for next-generation renewable offtake demand.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Auction Participation | ACWA Power and Masdar anchor utility-scale solar capacity through competitive tender wins under Ministry of Energy regulations. |
| Grid Modernization Investment | Automated metering infrastructure deployment at 110 kV substations addresses Fergana Valley load growth and regulatory mandates. |
| Domestic Content Partnership | Joint ventures with Uzbek construction firms satisfy auction requirements for local subcontractor participation in mounting structure fabrication. |
| Behind-the-Meter Solar Deployment | Net metering provisions enable commercial and industrial facilities in Tashkent to hedge volatile gas-indexed grid tariffs. |
| Green Hydrogen Pilot Development | Surplus auction-priced solar electricity could feed electrolyzer demonstrations signaled by Ministry of Energy export corridor studies. |
Research Methodology
A standing panel of utility planning officers, independent power producer project developers, EPC contractors, and grid operators provided ongoing calibration across primary fieldwork. Secondary validation drew from International Energy Agency power market reports, EIA country analysis briefs, project development databases tracking Central Asian renewable auctions, and regulatory filings at the State Inspectorate for Energy Supervision. Bottom-up capacity addition modeling triangulated against top-down macroeconomic demand projections.
Scenario-bracketing framed low, base, and high cases across the projection horizon without specifying discrete years. The analytical framework segmented by fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived through iterative convergence of demand elasticity estimates and supply cost curves. Forecast inputs incorporated solar irradiance mapping data and domestic gas allocation policy scenarios.
Stress conditions across auction participation rates, transmission reinforcement timelines, and fuel price liberalization trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory continuity and technology cost decline curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Sudan Power Market
Power
North America CHP Market
Power
Denmark Power Market
Power
Distribution Feeder Protection System Market
Power
Kuwait Power Market
Power
Resonant Power Converters Market
Power
LNG Power Barge Market
Power
Power Sled Market
Power
Power Rental Market
Power
Flue Gas Desulfurization Unit Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
Global Diesel Power Engine Market
Power
Existent Gum Steam Generator Market
Power
High Voltage DC Power System Market
Power
Power Purchase Agreement Market
Power
North America Microturbine Market