
 Europe Solar Inverter Market | 2026-2036
Europe Solar Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Solar Inverter Market Foresight
The gap between premium module-level electronics and commodity string units is repositioning procurement strategies across European installer networks. SMA Solar Technology AG leverages its German manufacturing base to sustain dominance in utility-scale central and three-phase string architectures. Fronius International GmbH anchors its position in residential and commercial segments through Austrian-engineered galvanic isolation and welding-grade power electronics heritage.
A solar inverter converts direct current generated by photovoltaic modules into alternating current synchronized to grid frequency and voltage parameters, with efficiency ratings typically spanning 95% to 99% and maximum power point tracking across variable irradiance conditions. String inverters occupy the mature volume tier in ground-mounted and large rooftop applications where cost-per-watt optimization governs procurement, while microinverters and power optimizers capture expanding share in residential and commercial segments where shading mitigation and module-level monitoring justify premium positioning. Hybrid inverters integrating battery storage interfaces represent the fastest-growing product configuration as retrofit demand accelerates across German and Italian markets.
The EU Green Deal and REPowerEU framework mandate accelerated renewable deployment targets while CE marking and the F-Gas Regulation constrain cooling system design choices for power-dense inverter architectures. Germany's KBA and grid operators enforce VDE-AR-N 4105 and VDE-AR-N 4110 standards that shape inverter reactive power capability and fault ride-through requirements. Stakeholders must monitor evolving network codes in Spain and Italy alongside battery storage coupling mandates that will determine next-generation hybrid inverter specifications.
Market Dynamics
Grid-code harmonization under the EU Green Deal is compressing inverter design cycles while REPowerEU deployment targets force simultaneous scaling across utility and distributed segments. German VDE-AR-N 4110 fault ride-through requirements and Spanish grid stability mandates are creating divergent certification burdens that fragment product roadmaps.
Growth Catalysts
- REPowerEU Framework:Binding renewable deployment targets across member states are mandating procurement quotas for hybrid inverters with battery storage interfaces in Germany and Italy.
- Net-Metering Reforms:Spanish and Italian regulatory updates are redirecting residential installer preferences toward module-level power electronics with granular monitoring capabilities.
- Utility-Scale Expansion:Ground-mounted solar parks in Spain and Germany are driving procurement of three-phase string and central inverter architectures above 100 kW.
Market Restraints
- IGBT and SiC Module Concentration:Power semiconductor supply concentrates among East Asian foundries, exposing European inverter OEMs to input cost volatility and allocation constraints.
- F-Gas Regulation Cooling Constraints:The EU F-Gas Regulation limits refrigerant choices for liquid-cooled power-dense architectures above 250 kW, forcing design trade-offs in utility-scale units.
- Grid-Code Fragmentation:Divergent VDE-AR-N 4105, VDE-AR-N 4110, and evolving Spanish network codes create certification duplication that extends product launch timelines.
Strategic Opportunities
- Polish and Romanian Distributed Markets:Underpenetrated residential solar segments in Eastern Europe present first-mover positioning for hybrid inverter portfolios before grid-code harmonization completes.
- Battery Retrofit Interfaces:DC-coupled storage retrofit demand in German existing installations is creating white space for next-generation hybrid inverters with backward-compatible firmware architectures.
- Agricultural PV Coupling:Italian agrivoltaic mandates are opening specialized inverter specifications for dual-use land applications with elevated environmental protection ratings.
Industry Challenges
- Power Electronics Talent Scarcity:Recruitment bottlenecks for magnetics design and grid-synchronization firmware engineers are extending R&D timelines for OEMs in Germany and Austria.
- CE Marking Documentation Burden:Expanding scope of electromagnetic compatibility and safety standards under the Machinery Directive is consuming compliance resources ahead of product launches.
- Legacy Fleet Firmware Integration:Retrofit compatibility requirements with installed string inverter bases are complicating software architecture decisions for hybrid product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Solar Inverter Market |
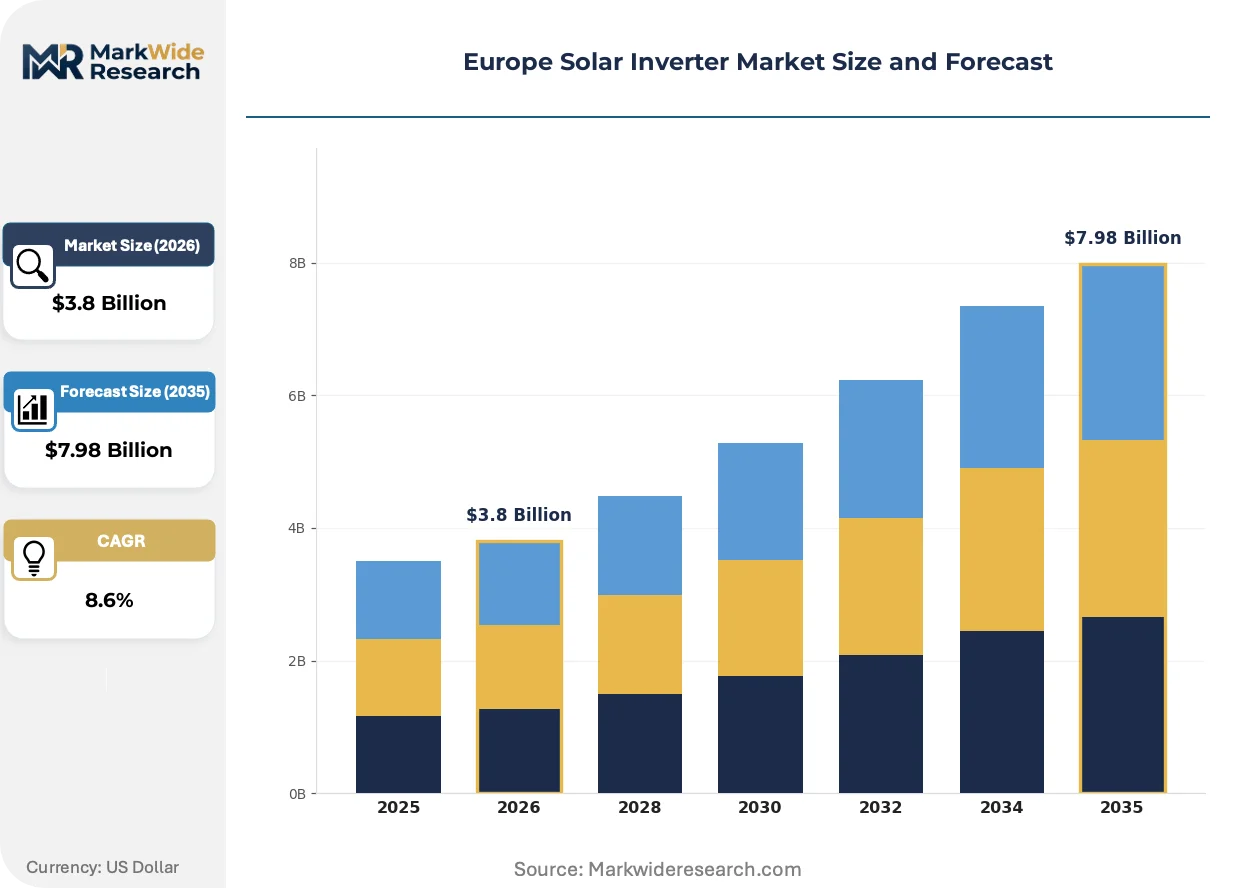
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Microinverters, Power Optimizers, Hybrid Inverters Technology: Grid-Tied, Off-Grid, Battery Storage, Smart Inverters End User: Residential, Commercial, Industrial, Utility Installation Type: Roof-Top, Ground-Mounted, Building Integrated, Others |
| Companies Covered | SolarEdge Technologies, Fronius International GmbH, SMA Solar Technology AG, GoodWe, Enphase Energy, Huawei Technologies, FIMER SpA, ABB Ltd, Sungrow Power Supply, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Solar Inverter Market Shifts & Advancements
Silicon carbide power semiconductors and AI-driven maximum power point tracking algorithms are compressing efficiency gaps between string and central architectures. Regulatory pressure on grid stability is forcing simultaneous advances in reactive power control and predictive maintenance capabilities.
SiC MOSFET-based inverter topologies are electrifying conversion efficiency benchmarks above 99% in three-phase string units above 50 kW. German utility-scale developers are specifying these architectures for new ground-mounted installations to minimize levelized cost of energy. The technology is electrifying procurement criteria away from pure cost-per-watt toward lifetime yield optimization and grid-service revenue stacking.
The EU F-Gas Regulation is constraining liquid cooling system designs for power-dense central inverters above 1 MW. OEMs are responding with air-cooled architectures and dielectric fluid alternatives that trade thermal performance for regulatory compliance. Utility-scale projects in Spain and Italy are most affected, with developers accepting derated continuous output ratings to secure permitting approval.
Installer procurement consolidation across German and Austrian residential networks is compressing distributor margins and forcing direct OEM engagement models. Regional buying cooperatives are displacing traditional electrical wholesalers for volumes above 500 kW annually. Southern Germany and northern Italy exhibit the most visible channel restructuring, with Fronius and SMA deploying dedicated account teams for top-twenty installer groups.
Europe Solar Inverter Market Segmentation
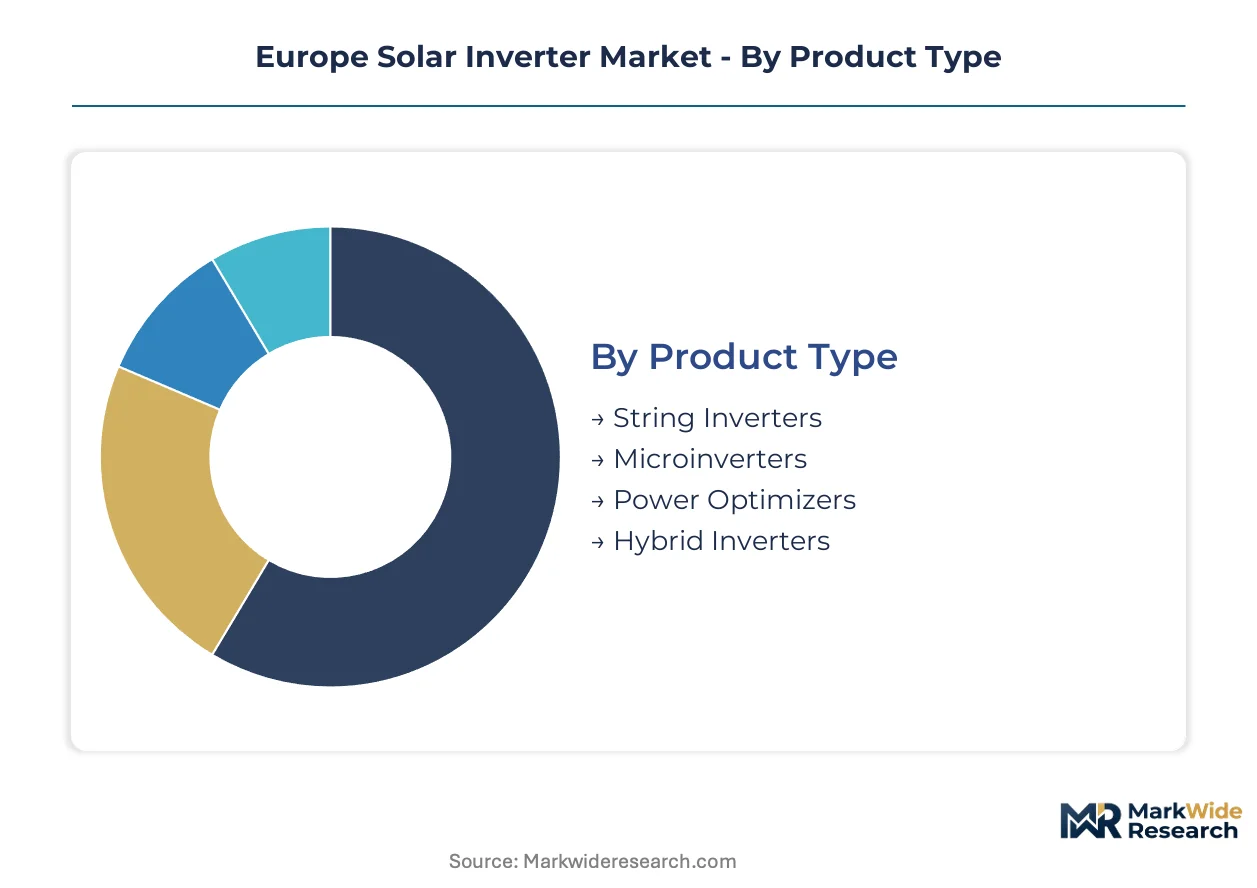
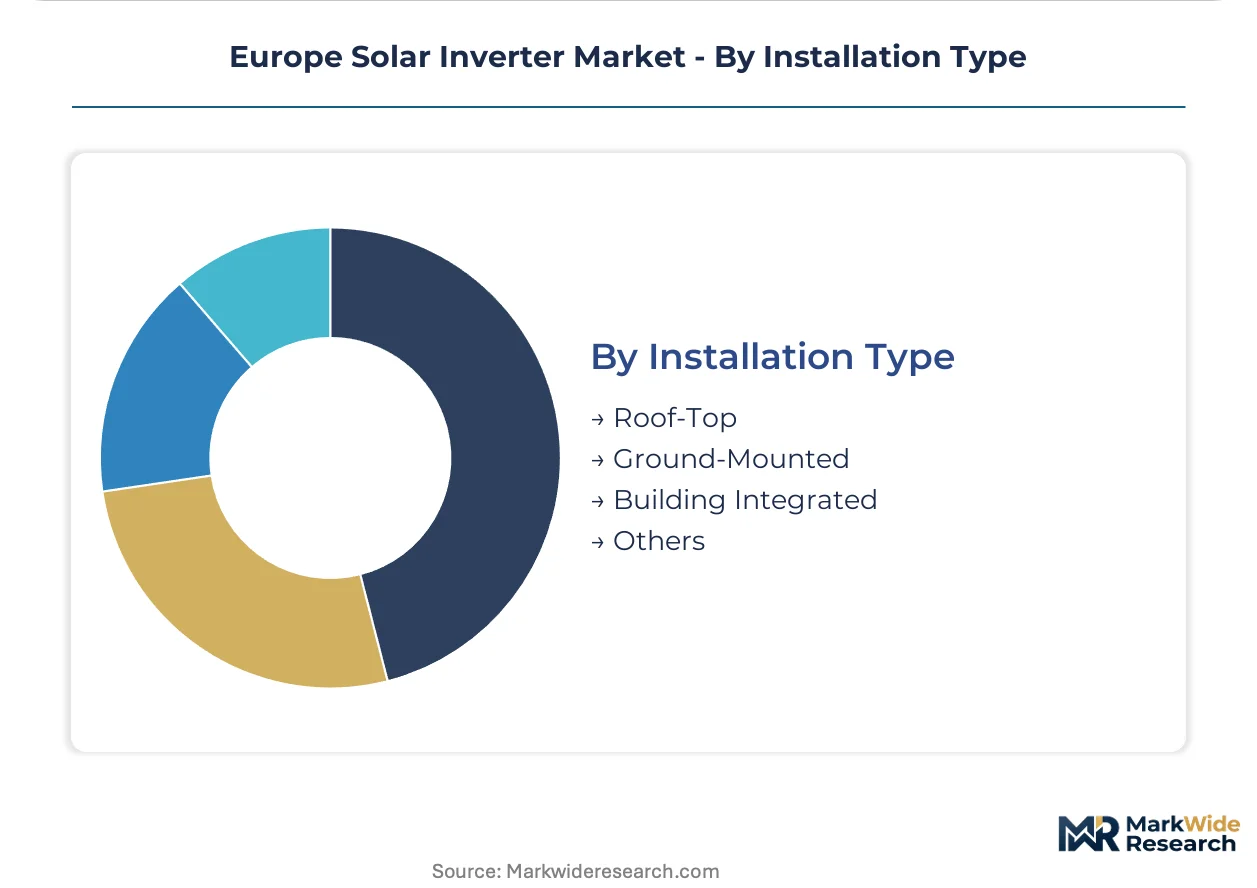
Inverter procurement across Europe fragments across four structural dimensions that determine certification pathways, margin profiles, and channel access. Product architecture dictates CE marking complexity under the Machinery Directive, while end-use concentration shapes grid-code compliance burdens under national network codes.
Product Type:
CE marking and F-Gas Regulation compliance divide sharply across architectures, with liquid-cooled central units above 250 kW facing the most constrained refrigerant choices.
- String Inverters:Modular AC-conversion units process 8-22 panel strings through single MPPT channels, dominating German and Spanish ground-mounted procurement where cost-per-watt optimization governs utility-scale tenders. VDE-AR-N 4110 fault ride-through certification consumes 14-18 month validation cycles for three-phase units above 100 kW.
- Hybrid Inverters:DC-coupled battery interfaces with bidirectional power flow capability are capturing installer preference in Italian and German residential retrofit markets where storage coupling mandates reshape replacement cycles. REPowerEU procurement quotas accelerate specification for new distributed generation connections.
- Microinverters:Module-level AC conversion with per-panel MPPT addresses shading mitigation in complex rooftop geometries across Mediterranean residential markets.
- Power Optimizers:DC-to-DC conditioning units paired with string inverters enable granular monitoring and rapid shutdown compliance for commercial installations in France and Benelux.
String inverters sit at the top of the volume ranking, with hybrid inverters climbing the fastest.
Technology:
Grid-interconnection standards fragment procurement across network service capabilities and islanding protection requirements.
- Grid-Tied:Synchronous inverters without battery buffering represent the mature volume base across Spanish and Italian utility-scale installations where pure feed-in economics dominate. Spanish grid stability mandates enforce stricter reactive power capability specifications than German VDE frameworks.
- Battery Storage:DC-coupled or AC-coupled energy storage interfaces with time-shift optimization algorithms are gaining specification share in German residential markets where EEG reform erodes feed-in tariffs. Firmware architectures must maintain backward compatibility with 2015-2020 installed string inverter fleets.
- Smart Inverters:Grid-forming capability with autonomous voltage regulation and synthetic inertia response addresses evolving Austrian and Swiss network code requirements for distributed generation penetration above 50% local load.
- Off-Grid:Standalone inverters with battery prioritization serve Alpine and Mediterranean island applications where grid extension costs exceed solar-plus-storage capital expenditure.
Grid-tied architectures retain volume leadership, though battery storage interfaces are expanding most quickly.
End User:
Customer scale determines procurement channel structure and service bundling expectations across European installer networks.
- Utility:Central and three-phase string architectures above 1 MW dominate procurement for Spanish and German ground-mounted solar parks where EPC contractors bundle inverter supply with 20-year service agreements. Liquid cooling trade-offs under F-Gas Regulation constrain power density for units above 2.5 MW.
- Residential:Single-phase string and hybrid inverters below 20 kW flow through consolidated buying cooperatives in southern Germany and northern Italy that displace traditional electrical wholesalers for volumes above 500 kW annually.
- Commercial:Three-phase string configurations between 30-150 kW serve rooftop and carport installations across French and Polish distributed generation markets where net-metering reforms redirect preference toward module-level monitoring.
- Industrial:Behind-the-meter installations with peak shaving optimization leverage hybrid inverters in Italian manufacturing regions where power purchase agreement structures favor self-consumption maximization.
Utility-scale procurement commands the highest absolute volumes, with residential segments showing the steepest expansion trajectory.
Installation Type:
Mounting configuration determines environmental protection ratings and thermal management specifications for inverter enclosure design.
- Ground-Mounted:Large-scale solar parks in Spain and Germany specify IP65-rated string and central inverters with active cooling for continuous operation at 50°C ambient, with F-Gas Regulation forcing air-cooled alternatives for power-dense architectures above 250 kW.
- Roof-Top:Residential and commercial rooftop installations across Italian and Austrian markets favor string and microinverter architectures where weight constraints and fire safety regulations govern rapid shutdown and arc fault detection integration.
- Building Integrated:Façade-integrated PV systems in German and Dutch urban markets require specialized inverter form factors with elevated electromagnetic compatibility shielding for proximity to occupied spaces.
- Others:Floating solar and agricultural PV applications in France and Italy demand corrosion-resistant enclosures with enhanced sealing against humidity and chemical exposure.
Ground-mounted deployments anchor volume rankings, with building-integrated configurations gaining share fastest in urban densification zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power electronics engineering talent concentrates in German and Austrian industrial clusters, anchoring inverter design capability across the continent. Spanish and Italian installer networks drive distributed generation deployment. Eastern European markets present expansion corridors before grid-code harmonization completes.
Germany
Utility-scale solar parks in Brandenburg and Saxony-Anhalt are expanding procurement of three-phase string and central inverters above 100 kW. The KBA enforces VDE-AR-N 4110 fault ride-through standards that shape reactive power capability specifications. SMA Solar Technology AG maintains manufacturing operations in Niestetal, sustaining domestic supply chain integration for utility-scale architectures.
Spain
Ground-mounted installations in Extremadura and Andalusia are driving demand for power-dense central inverters with grid-stability mandates. Spanish network codes enforce stricter reactive power specifications than German VDE frameworks. The Seville-Málaga corridor hosts concentrated EPC contractor activity bundling inverter supply with long-term service agreements.
Italy
Agrivoltaic mandates in Emilia-Romagna and Lombardy are opening specialized inverter specifications for dual-use land applications. Net-metering reforms redirect residential installer preferences toward module-level power electronics with granular monitoring. The Po Valley industrial zone anchors manufacturing demand for behind-the-meter hybrid inverters with peak shaving optimization.
Poland
Underpenetrated residential solar segments in Masovia and Silesia present first-mover positioning for hybrid inverter portfolios. CE marking requirements under the Machinery Directive govern electromagnetic compatibility certification pathways. The Warsaw-Katowice corridor exhibits fastest-growing installer network consolidation ahead of EU Green Deal deployment targets.
Netherlands
Building-integrated PV systems in Randstad urban markets require specialized inverter form factors with elevated electromagnetic compatibility shielding. The EU F-Gas Regulation constrains cooling system designs for power-dense architectures in port-side industrial installations. Eindhoven-region technical universities feed power electronics talent into Dutch-German cross-border supply chains.
Europe Solar Inverter Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across inverter architectures, with manufacturing concentration in Germany and Austria against Asian module sourcing. The vendor base separates into three strategic archetypes: vertically integrated European OEMs with captive magnetics production, Asia-Pacific scale players leveraging semiconductor cost advantages, and module-level electronics specialists targeting residential retrofit niches. Dominant competitive moves include backward integration into power semiconductor sourcing and geographic expansion through installer network direct engagement.
Among German-incumbent manufacturers, SMA Solar Technology AG and Fronius International GmbH occupy positions anchoring premium-tier procurement for utility and residential segments respectively. Huawei Technologies represents the Asia-Pacific scale archetype, while SolarEdge Technologies exemplifies module-level electronics specialization. These three anchors illustrate the competitive tension between regional engineering heritage and cost-optimized global manufacturing.
| Leading Market Players |
|---|
| SolarEdge Technologies |
| Fronius International GmbH |
| SMA Solar Technology AG |
| GoodWe |
| Enphase Energy |
| Huawei Technologies |
| FIMER SpA |
| ABB Ltd |
| Sungrow Power Supply |
| Others |
Supply & Pricing Matrix
CE certification tier divergence between utility-scale central inverters and residential string units manifests in both procurement premiums and magnetics sourcing geography, with German and Austrian OEMs commanding price advantages from captive ferrite core production while Asian competitors undercut through foundry-sourced silicon carbide modules.
Pricing Analysis
Bundled long-term service agreements versus unbundled hardware-only procurement splits the European solar inverter market into divergent margin structures. Three-tier pricing structure across premium, standard, and economy levels tracks VDE-AR-N 4110 certification status and reactive power capability ratings. Pricing pressure stems from installer buying cooperative consolidation in southern Germany and northern Italy. Residential retrofit buyers exhibit highest price sensitivity, while utility-scale EPC contractors prioritize lifetime yield optimization over upfront capital cost.
Supply Chain Analysis
IGBT and silicon carbide MOSFET supply rests on Taiwanese and South Korean foundry capacity, with German magnetics producers anchoring ferrite core and inductor winding for premium-tier OEMs. Power semiconductor wafers, aluminum enclosures, and cooling system components constitute the critical input stack. Single-source vulnerability concentrates in 650V and 1200V SiC module allocation from East Asian suppliers. Distribution runs through direct OEM engagement with consolidated installer networks and specialized solar distributors serving fragmented residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe solar inverter market reads as a late-cycle quality story, with procurement criteria shifting from pure cost-per-watt toward grid-service revenue stacking and lifetime yield optimization.
For Market Incumbents: Hedge against Asian semiconductor cost advantages by deepening backward integration into magnetics and firmware development. Prioritize captive ferrite core production in German industrial clusters to defend margin position against foundry-sourced competitors. Accelerate VDE-AR-N 4110 certification pipelines to maintain premium positioning as Spanish and Italian grid codes tighten.
For New Entrants and Emerging Players: Polish buying cooperatives represent the most penetrable channel entry point, with underpenetrated residential solar segments in Masovia and Silesia offering first-mover positioning before grid-code harmonization completes. Target hybrid inverter portfolios with backward-compatible firmware architectures for German battery retrofit demand. Lead with direct installer engagement models that bypass traditional electrical wholesalers.
For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid inverter specialists possessing DC-coupled storage interfaces and proven grid-forming capability. Long-term viability favors vendors with demonstrated compliance pathways across divergent German, Spanish, and Italian network codes. Watch for inflection signals in Polish and Romanian procurement quota announcements under REPowerEU deployment targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetics | Captive ferrite core production insulates German OEMs from East Asian semiconductor allocation volatility. |
| Grid-Forming Firmware Development | Autonomous voltage regulation capability addresses Austrian and Swiss network code requirements above 50% distributed penetration. |
| Battery Retrofit Interface Launch | DC-coupled hybrid architectures capture German residential replacement cycles as EEG reform erodes feed-in economics. |
| Eastern European Channel Expansion | Direct engagement with Polish buying cooperatives establishes positioning before grid-code harmonization completes. |
| SiC MOSFET Topology Migration | Conversion efficiency above 99% in three-phase string units electrifies procurement criteria toward lifetime yield optimization. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with EPC contractors, utility planning officers, inverter OEM product managers, and German installer cooperative procurement leads with secondary validation from IEA deployment databases, EU Green Deal policy filings, VDE certification registries, and national grid operator network code submissions. Bottom-up project pipeline aggregation and top-down regulatory target reconciliation provided cross-check triangulation.
Historical reference periods spanning installed capacity additions and inverter shipment volumes anchored the projection horizon across product architecture, end-user scale, and national regulatory cluster segmentation. CAGRs derived from regression against REPowerEU binding targets and national deployment trajectories incorporated silicon carbide adoption curves, grid-code compliance timeline assumptions, and battery storage coupling mandate schedules as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to East Asian semiconductor allocation constraints and evolving Spanish network code specifications. Forecasts reflect documented assumptions about grid-code harmonization progress and F-Gas Regulation cooling system compliance pathways. A small set of triggers—including Polish procurement quota acceleration and Italian agrivoltaic mandate expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Statcom Market
Power
North America Power Market
Power
Canada Power Market
Power
Substation Automation System Market
Power
Sudan Power EPC Market
Power
Equatorial Guinea Power Market
Power
Angola Power EPC Market
Power
Smart PV Inverters Market
Power
Brunei Power Market
Power
Single-Phase Microinverter Market
Power
High Voltage DC Power System Market
Power
Global Advanced Marine Power Supply Market
Power
Qatar Power Market
Power
Direct Current Power System Market
Power
Europe Power Market
Power
North America CHP Market