
 Regenerative Blowers Market | 2026-2036
Regenerative Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
Regenerative Blowers Market Analysis
A shortage of certified vacuum-system technicians is redrawing competitive boundaries in the regenerative blowers sector. Gardner Denver leverages its extensive service network to sustain aftermarket revenue streams across North American industrial corridors. Becker Pump Corporation anchors its position through specialized oil-free blower architectures that dominate food-grade applications. Busch Vacuum Solutions differentiates via backward integration into precision impeller casting, controlling critical tolerances that determine energy efficiency.
Regenerative blowers are dynamic compression devices employing non-contacting impellers that recirculate air through a toroidal channel, achieving pressure differentials typically spanning 5 to 200 mbar with oil-free discharge. These machines serve primarily as aeration and vacuum sources where pulsation-free airflow and minimal maintenance define operational value. Single-stage configurations occupy the dominant volume position due to their cost efficiency in standard aeration duties, while twin-stage designs capture margin pools in higher-pressure conveying applications. Electric technology leads the installed base, though pneumatic variants retain niche traction in explosive atmospheres where spark containment governs specification.
The EPA enforces blower efficiency benchmarks through Clean Water Act compliance pathways that directly shape municipal procurement specifications across the United States. ISO 8573-1 Class 0 certification requirements for oil-free compressed air are tightening product standards in food processing and pharmaceutical adjacent sectors. Ecodesign regulations in Europe mandate minimum efficiency indices that filter market access for non-compliant equipment. Stakeholders must weigh regional certification divergence against platform standardization economics when configuring global product portfolios.
Market Dynamics
The regenerative blowers sector is restructuring around energy efficiency mandates that penalize legacy aeration equipment. Municipal utilities now face dissolved oxygen compliance thresholds that obsolete single-stage blowers in favor of precision-controlled twin-stage architectures.
Growth Catalysts
- EPA Clean Water Act enforcement:Stricter dissolved oxygen standards in the United States are forcing wastewater treatment plants to replace aging aeration equipment with higher-efficiency blower systems.
- China's industrial zone expansion:Municipal and manufacturing aeration needs in Chinese industrial corridors are scaling rapidly, creating concentrated demand pockets for oil-free blower technologies.
- ISO 8573-1 Class 0 certification:Food processing and pharmaceutical sectors are mandating oil-free compressed air standards that favor regenerative blower architectures over lubricated alternatives.
Market Restraints
- Copper and aluminum price volatility:Electric motor windings and impeller castings face raw material cost swings that compress margins for standardized single-stage units.
- Certified technician scarcity:A shortage of vacuum-system specialists constrains aftermarket service capacity across North American industrial corridors.
- Positive displacement blower substitution:Lobe and screw compressor technologies capture higher-pressure conveying applications above 200 mbar differential limits.
Strategic Opportunities
- India's wastewater infrastructure buildout:The country's national pollution control mandates are accelerating municipal aeration investments in tier-2 and tier-3 cities.
- IoT-enabled predictive maintenance:Sensor-integrated blower systems allow utilities to shift from scheduled maintenance to condition-based service models.
- EU Ecodesign regulation compliance:Minimum efficiency index thresholds are filtering market access and creating premium positioning for compliant equipment manufacturers.
Industry Challenges
- ISO 8573-1 Class 0 certification timelines:Oil-free validation protocols extend product development cycles by 8-14 months for food-grade applications.
- Legacy SCADA integration complexity:Municipal utilities require blower systems to interface with decades-old control architectures without full automation overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regenerative Blowers Market |
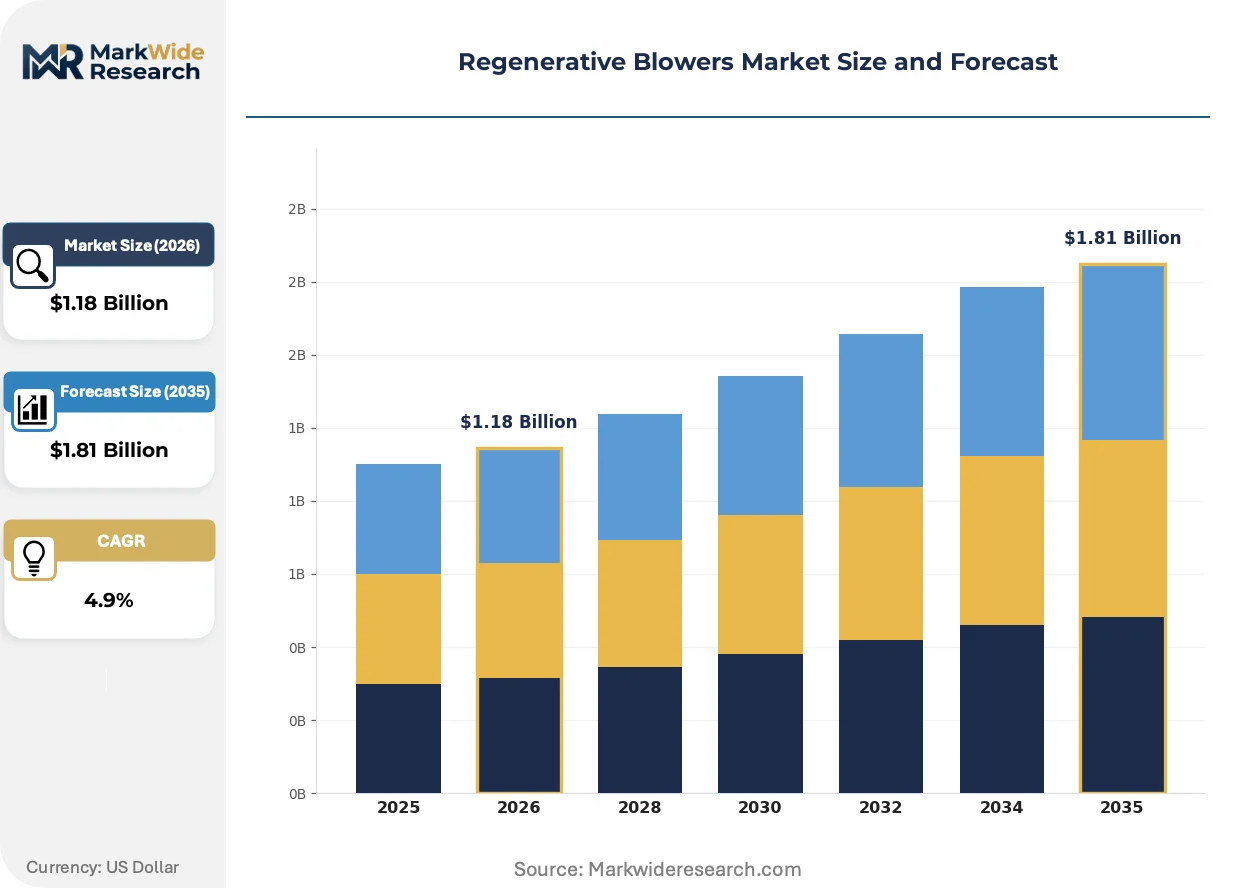
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.81 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-stage, Twin-stage, Multi-stage, Compact Technology: Electric, Pneumatic, Hydraulic, Mechanical End User: Agriculture, Water Treatment, Food Processing, Textile Application: Vacuum Handling, Aeration, Cooling, Conveying |
| Companies Covered | Busch Vacuum Solutions, Gardner Denver, Becker Pump Corporation, Air Control Industries, Ametek, The Spencer Turbine Company, Atlantic Blowers, FPZ SpA, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regenerative Blowers Market Emerging Trajectories
Digitalization and material science are converging to redefine blower performance benchmarks. Equipment specifications now prioritize real-time efficiency monitoring and oil-free operation as baseline requirements rather than premium features.
Magnetic bearing technology is fragmenting traditional mechanical seal architectures in high-duty-cycle applications. Pharmaceutical manufacturers in Germany and Switzerland are adopting oil-free magnetic levitation blowers for continuous fermentation processes. This shift is fragmenting the competitive landscape between established impeller specialists and magnetic bearing entrants from adjacent turbomachinery sectors.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants and tightening leakage monitoring requirements across industrial cooling systems. Blower manufacturers must now certify equipment compatibility with low-global-warming-potential working fluids. Food cold chain operators in France and the Netherlands are retrofitting facilities with compliant blower systems ahead of 2030 phase-down deadlines.
Lifecycle contracting is displacing capital procurement in municipal wastewater sectors. German utilities now specify total cost of ownership over 15-year horizons, bundling energy consumption guarantees with equipment supply. This model compresses vendor margins while locking in long-term service revenues across Ruhr Valley treatment networks.
Regenerative Blowers Market Segmentation
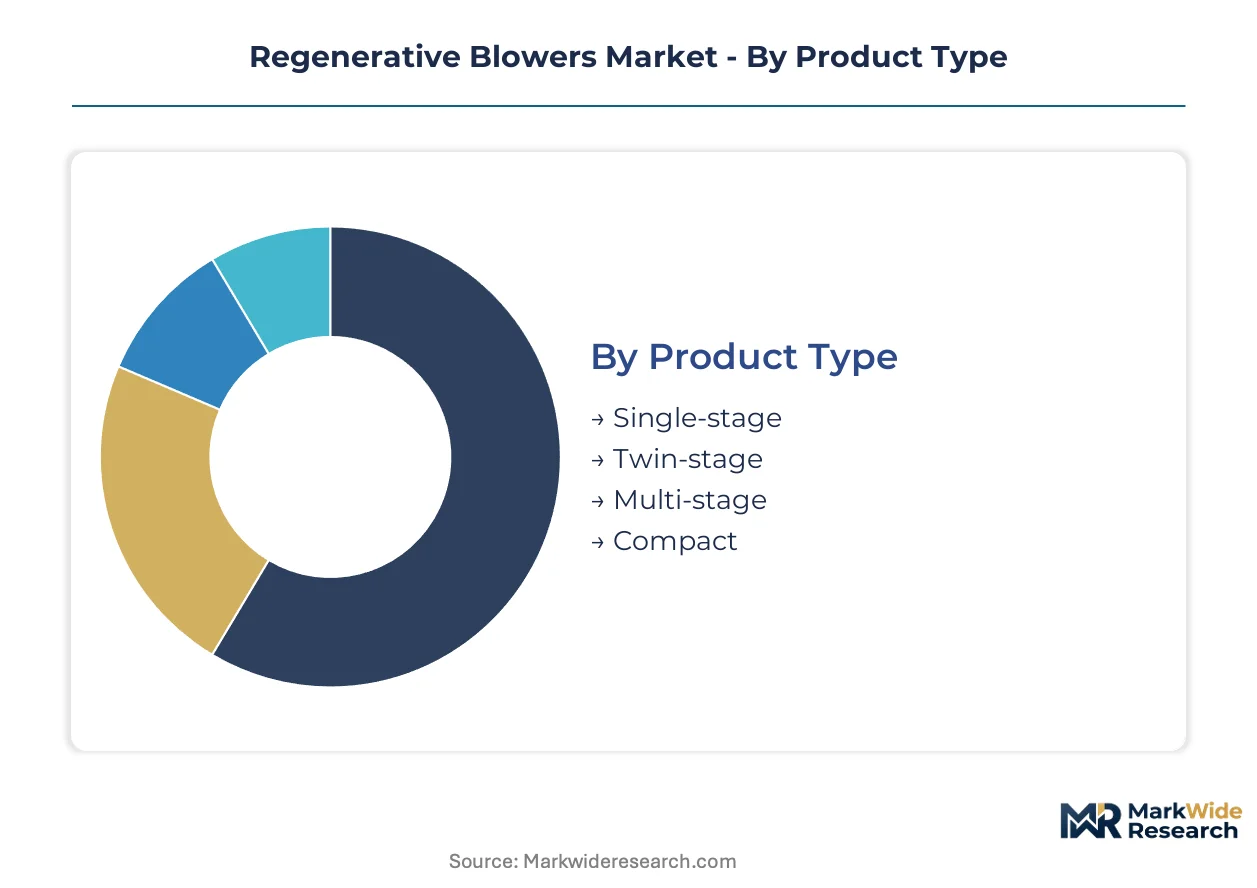
Regenerative blower procurement patterns diverge sharply across pressure requirements and contamination sensitivity. Specification committees weigh first-cost against lifecycle energy consumption when mapping segments to facility upgrade timelines.
Product Type:
Single-stage configurations face intensifying substitution pressure from twin-stage architectures as dissolved oxygen standards tighten across wastewater treatment specifications.
- Single-stage:Non-contacting impellers recirculate air through toroidal channels achieving 5-100 mbar differentials with minimal maintenance. German municipal utilities along the Ruhr Valley specify these for standard aeration basins where capital constraints override efficiency premiums.
- Twin-stage:Cascaded compression chambers deliver 100-200 mbar pressure ranges with precision airflow control. China's industrial zones in Jiangsu and Guangdong provinces are scaling deployments for high-density aquaculture systems requiring exact oxygen transfer rates.
- Multi-stage:Three or more compression stages serve specialized vacuum conveying above 200 mbar where positive displacement alternatives typically dominate.
- Compact:Reduced footprint designs integrate directly into OEM equipment for decentralized water treatment skids in India's tier-2 cities.
Single-stage anchors the volume base while twin-stage gains share at the steepest rate.
Technology:
Cost tier stratification separates premium electric drives from pneumatic alternatives in hazardous environment specifications.
- Electric:AC induction and permanent magnet motors dominate installed capacity with variable frequency drive compatibility. United States wastewater plants under EPA Clean Water Act enforcement are retrofitting electric blowers with IoT-enabled efficiency monitoring across Ohio and Pennsylvania treatment networks.
- Pneumatic:Compressed air-driven impellers eliminate ignition risks in explosive atmospheres. Oil and gas processing facilities along the US Gulf Coast specify these for tank vapor recovery systems.
- Hydraulic:Fluid power transmission serves mobile aeration equipment in agricultural drainage applications.
- Mechanical:Direct shaft drives persist in isolated installations lacking electrical infrastructure.
Electric systems command the revenue majority while pneumatic variants defend niche positions in safety-critical specifications.
End User:
Application maturity varies dramatically across contamination tolerance thresholds and regulatory exposure.
- Water Treatment:Municipal and industrial aeration basins represent the core demand concentration. Stricter dissolved oxygen mandates from the EPA and China's MEE are accelerating replacement cycles across aging infrastructure.
- Food Processing:ISO 8573-1 Class 0 oil-free requirements dominate specification sheets. Swiss dairy processors and Dutch cold chain operators mandate certified architectures for product contact applications.
- Agriculture:Aquaculture oxygenation and grain conveying drive volume in lower-margin equipment categories.
- Textile:Yarn conveying and loom suction applications favor compact single-stage units with minimal footprint requirements.
Water treatment anchors the volume base while food processing commands the steepest margin expansion trajectory.
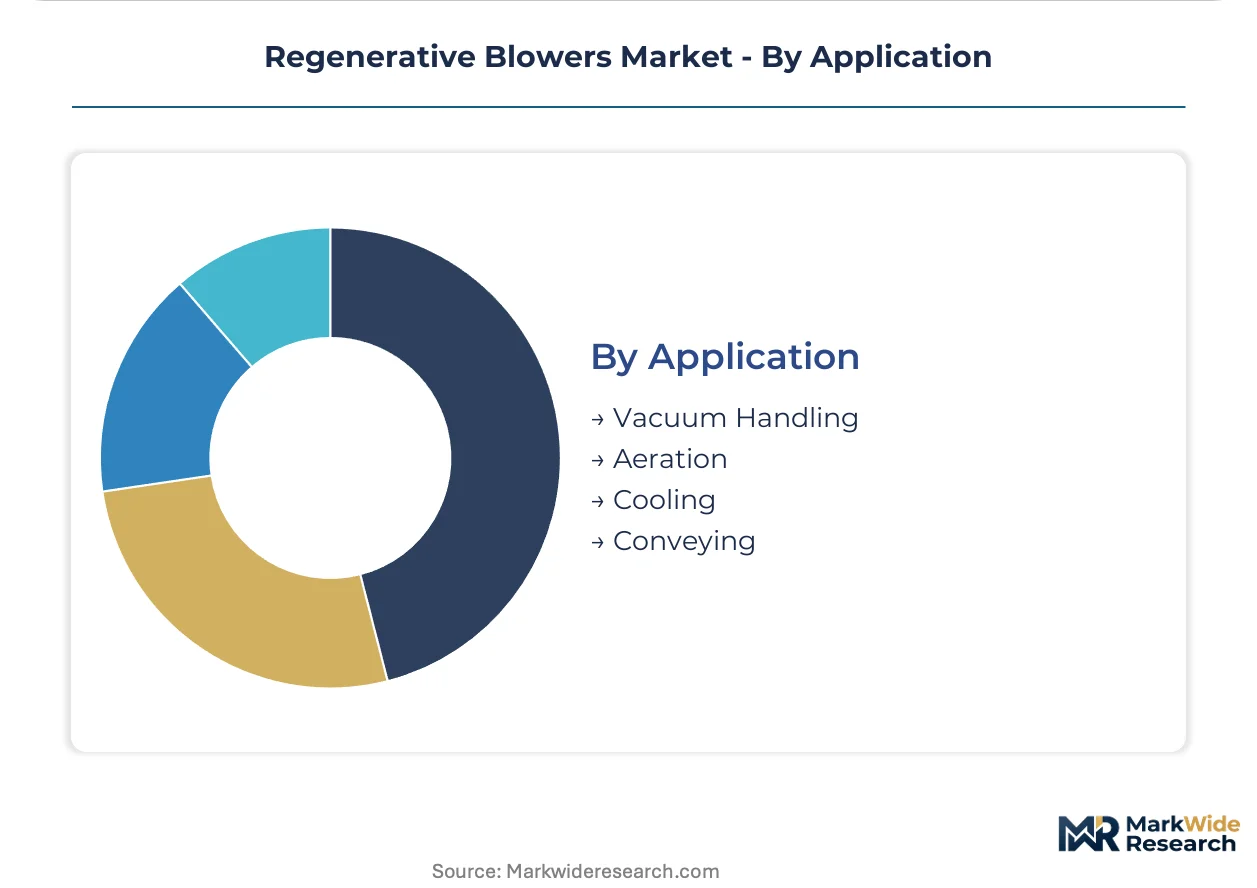
Application:
Customer type fragmentation separates specification-driven municipal procurement from price-sensitive industrial maintenance budgets.
- Aeration:Oxygen transfer for biological treatment processes defines the dominant use case. German utilities now contract on 15-year total cost of ownership metrics bundling energy guarantees with equipment supply.
- Vacuum Handling:Pulsation-free suction for automated manufacturing lines requires precise pressure stability. Automotive component manufacturers in Stuttgart and Wolfsburg specify oil-free systems for cleanroom material transport.
- Conveying:Pneumatic material transport spans food powders to plastic pellets. Bulk handling facilities in France's agricultural processing corridors favor twin-stage configurations for dense-phase conveying.
- Cooling:Air circulation for industrial processes and electronics thermal management occupies a commoditized specification tier.
Aeration anchors the volume base while vacuum handling climbs fastest on automation penetration in precision manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of dissolved oxygen standards is reshaping municipal procurement across the United States, while China's MEE accelerates industrial aeration mandates. Germany's Ecodesign regulations filter market access for non-compliant equipment. These regulatory anchors create divergent compliance pathways across three major demand centers.
United States
Wastewater treatment plants in Ohio and Pennsylvania are retrofitting aging aeration basins under EPA Clean Water Act deadlines. The agency's stricter dissolved oxygen thresholds obsolete single-stage blowers in favor of precision-controlled twin-stage architectures. Municipal utilities across the Rust Belt now contract on 15-year total cost of ownership metrics.
Germany
Ruhr Valley treatment networks bundle energy consumption guarantees with equipment supply through lifecycle contracting models. EU Ecodesign regulations mandate minimum efficiency indices that exclude non-compliant blowers from public procurement. Bavarian pharmaceutical manufacturers specify oil-free magnetic levitation systems for continuous fermentation processes.
China
Jiangsu and Guangdong industrial zones scale twin-stage deployments for high-density aquaculture requiring exact oxygen transfer rates. The MEE's national pollution control mandates accelerate municipal aeration investments in tier-2 and tier-3 cities. Manufacturing corridors around Shanghai prioritize oil-free architectures for food-grade export processing.
India
Tier-2 cities drive compact blower demand for decentralized water treatment skids under national pollution control mandates. The Central Pollution Control Board's dissolved oxygen standards force municipal upgrades across Maharashtra and Gujarat. Industrial clusters in Pune and Ahmedabad specify cost-efficient single-stage units for standard aeration duties.
Switzerland
Swissmedic-regulated pharmaceutical manufacturers mandate ISO 8573-1 Class 0 certified oil-free compressed air for product contact applications. Basel's life sciences corridor leads adoption of magnetic bearing blowers for cleanroom material transport. Swiss dairy processors enforce certified architectures across supply chain cold chain operations.
Regenerative Blowers Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in regenerative blower supply. The upper tier controls critical component manufacturing and service networks spanning multiple industrial corridors. Mid-scale specialists concentrate on oil-free architectures or regional aftermarket density. Competitive moves center on backward integration into precision casting and IoT-enabled predictive maintenance platforms.
Within the integrated tier, Busch Vacuum Solutions and Gardner Denver occupy positions defined by upstream control over manufacturing inputs and extensive service footprints. Becker Pump Corporation exemplifies the specialization vector through dedicated oil-free blower architectures. These three anchors represent distinct competitive positions: casting-integrated efficiency control, network-dense aftermarket capture, and certified contamination-free architectures.
| Leading Market Players |
|---|
| Busch Vacuum Solutions |
| Gardner Denver |
| Becker Pump Corporation |
| Air Control Industries |
| Ametek |
| The Spencer Turbine Company |
| Atlantic Blowers |
| FPZ SpA |
| Hitachi |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day impeller casting lead times in European supply chains concentrate pricing power with foundries serving ISO 8573-1 Class 0 certified manufacturers, while Chinese motor winding suppliers compress margins for standardized single-stage units through volume-driven cost structures.
Pricing Analysis
German Ruhr Valley utilities pay fifteen to twenty percent premiums over Indian tier-2 municipal buyers for identical twin-stage specifications due to bundled fifteen-year energy performance guarantees. Three-tier pricing structure across premium magnetic bearing, standard twin-stage electric, and economy single-stage pneumatic configurations stratifies the market. Cost compression in single-stage segments is intensifying because Chinese industrial zone procurement favors lowest-first-cost bids over lifecycle metrics. Municipal wastewater treatment plants exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers demonstrate lowest sensitivity due to contamination liability exposure.
Supply Chain Analysis
Impeller inventory cycles stretching ninety days in German precision casting facilities contrast with thirty-day motor winding availability in Chinese manufacturing corridors, exposing OEMs to mismatch risk. Supply concentrates in Germany for high-tolerance castings, China for electric motor components, and Italy for compact pneumatic assemblies. Raw material dependencies span copper for motor windings, aluminum for impeller housings, and rare-earth magnets for permanent magnet drives. Single-source vulnerability in precision casting tolerances above ISO Class 0 thresholds threatens food-grade certification continuity. Distribution runs through authorized service networks for aftermarket capture and direct OEM supply for new equipment integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive boundaries as IoT-enabled predictive maintenance architectures create interoperability standards that lock in service revenue streams across multi-vendor installed bases.
For Market Incumbents: Consolidate aftermarket service density through certified technician training programs in North American industrial corridors where vacuum-system specialist scarcity constrains competitor expansion. Deepen backward integration into precision impeller casting to defend margin position against magnetic bearing entrants from adjacent turbomachinery sectors. Lock in municipal lifecycle contracts bundling energy guarantees with fifteen-year service horizons before Ecodesign compliance filters non-compliant equipment from European procurement. For New Entrants and Emerging Players: Differentiate on oil-free magnetic levitation architectures targeting Swiss and German pharmaceutical corridors where ISO 8573-1 Class 0 certification barriers protect premium positioning. Target India's tier-2 and tier-3 cities for compact blower skids where national pollution control mandates accelerate municipal infrastructure buildout with limited incumbent service presence. Pursue OEM integration partnerships with decentralized water treatment system manufacturers rather than direct municipal sales channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across IoT-enabled blower platforms requiring sensor integration, cloud infrastructure, and predictive analytics capabilities beyond traditional mechanical manufacturing. Focus acquisition screening on mid-scale specialists with established oil-free certifications and captive foundry relationships serving food-grade and pharmaceutical adjacent sectors. Watch for inflection signals in municipal procurement language shifting from capital expenditure specifications to total cost of ownership contracting with embedded energy performance guarantees.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captures critical tolerances determining energy efficiency in twin-stage architectures serving EPA-enforced wastewater treatment upgrades. |
| IoT-Enabled Predictive Maintenance Platform | Locks in recurring service revenues through condition-based monitoring contracts with German utilities adopting lifecycle procurement models. |
| ISO 8573-1 Class 0 Certification Investment | Secures pharmaceutical and food processing specification access where Swissmedic and FDA-adjacent contamination standards govern procurement. |
| Certified Technician Training Network Expansion | Addresses North American aftermarket capacity constraints that limit competitor service reach across Rust Belt industrial corridors. |
| Compact Blower Skid OEM Partnership Program | Captures India's tier-2 municipal buildout through decentralized water treatment system integrators under Central Pollution Control Board mandates. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across wastewater treatment and food processing facilities, combined with secondary validation through EPA enforcement records, EU Ecodesign compliance databases, customs trade data for copper and aluminum flows, and SEC filings from listed industrial equipment manufacturers. Bottom-up unit deployment estimates triangulated against top-down market sizing derived from municipal capital expenditure disclosures and industrial aeration project announcements.
Across the analysis window, the forecasting framework modeled pressure differential requirements, technology architecture preferences, end-use contamination sensitivity thresholds, and regional regulatory enforcement intensity as primary segmentation dimensions. CAGRs were synthesized from equipment replacement cycle analysis, dissolved oxygen standard tightening trajectories, and industrial zone expansion patterns in Chinese manufacturing corridors. Forecast inputs incorporated raw material cost trajectory assumptions for motor winding metals and foundry energy costs.
Forecasts assume regulatory continuity in EPA Clean Water Act enforcement, EU Ecodesign minimum efficiency indices, and China's MEE national pollution control mandates; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Oil Free Compressor Market
Compressors
Europe Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
Oil-Free Air Compressor Market
Compressors
CNG Compressor Market
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Centrifugal Compressors Market
Compressors
Air and Gas Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Rotary Air Compressor Market
Compressors
Rental Air Compressors Market
Compressors
Reciprocating Air Compressor Market
Compressors
Chlorine Compressors Market
Compressors
North America Air Compressor Market
Compressors
Booster Compressor Market
Compressors
Liquid Ring Compressors Market