
 Italy Power EPC Market | 2026-2036
Italy Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Power EPC Market Foresight
Steel-reinforced concrete foundation designs for turbine towers is hardening as offshore wind projects move into deeper Adriatic waters. Saipem SpA leverages its marine construction heritage to anchor floating platform capabilities. Webuild S.p.A. sustains a dominant position in civil infrastructure for thermal plant retrofits. Maire Tecnimont SpA specializes in hydrogen-ready combined cycle technology, differentiating its EPC offering from conventional fossil fuel contractors.
Italy Power EPC encompasses the full-scope engineering, procurement, and construction of electricity generation facilities, spanning turbine installation, grid interconnection at 132-380 kV, and civil works with seismic Zone 2 compliance. Solar project type leads current contractor backlogs as auction mechanisms favor photovoltaic deployments. Specialty contractor type captures premium margins in offshore wind foundation work where marine engineering expertise remains scarce. Design-build service type is expanding fastest as developers seek single-point accountability for utility-scale renewable assets.
ARERA sets revenue benchmarks for transmission investments while the EU Green Deal mandates emission reductions that reshape power plant permitting timelines. Italy's CNEL coordinates regional energy planning that channels EPC contracts toward southern provinces with superior renewable resource profiles. Stakeholders must monitor auction calendar density and grid connection queue lengths to calibrate bid capacity and labor allocation.
Market Dynamics
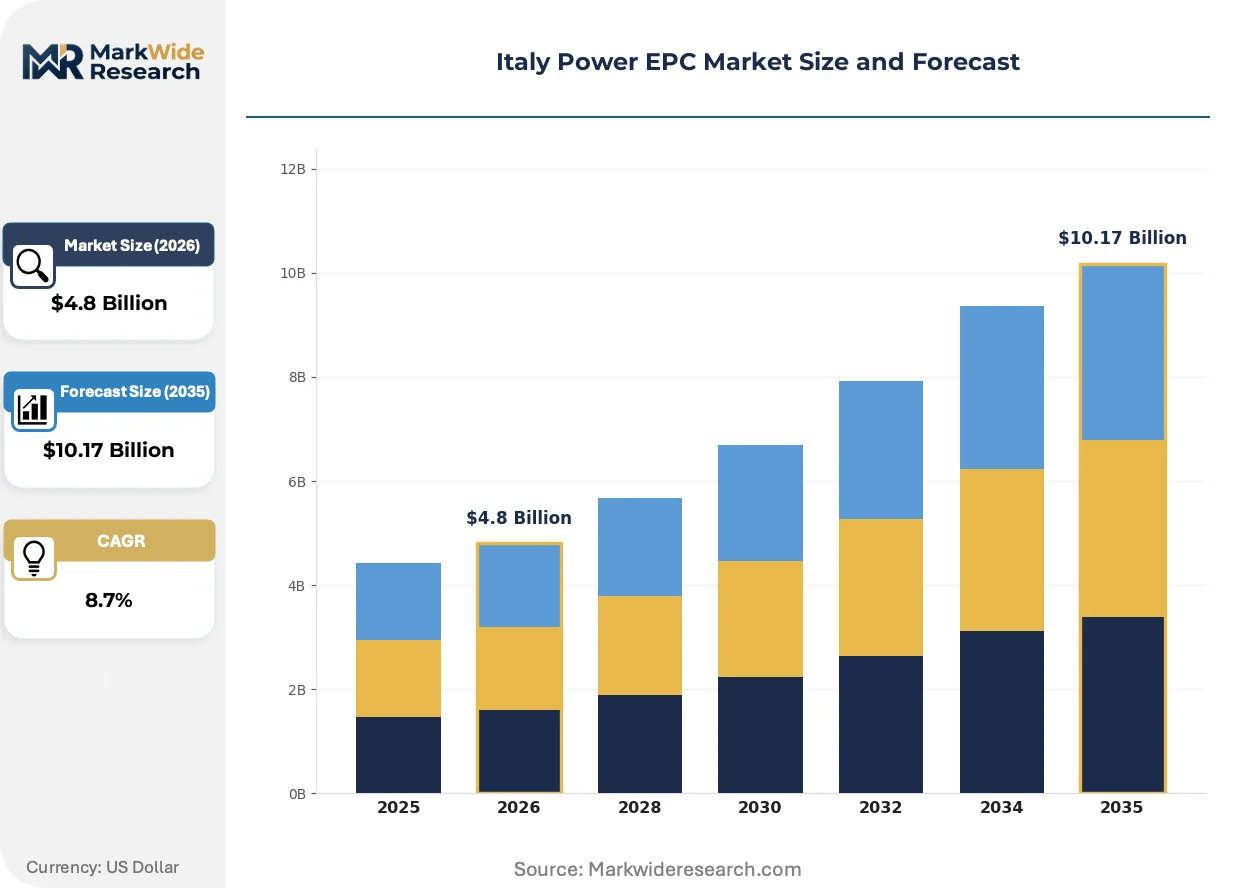
The Italy Power EPC sector is being fundamentally restructured by the convergence of floating offshore wind engineering demands with Terna SPA's transmission modernization timeline, compressing contractor qualification windows while expanding project complexity thresholds.
Growth Catalysts
- EU Green Deal emission mandates:Binding carbon reduction targets accelerate renewable energy auctions and force early retirement of thermal assets, creating replacement demand for clean generation infrastructure.
- Southern solar irradiation concentration:Sicily and Puglia host superior photovoltaic resource profiles that attract utility-scale developer interest and channel EPC contract flows toward specialized civil contractors.
- Hydrogen-ready combined cycle technology:Blending equipment for future fuel compatibility extends asset lifecycles and differentiates thermal retrofit offerings from stranded fossil plant alternatives.
Market Restraints
- Steel and copper input volatility:Foundation reinforcement materials and electrical cabling constitute major cost buckets with price exposure to commodity exchange fluctuations.
- Marine engineering talent scarcity:Floating platform design capabilities concentrate among legacy offshore oil service firms, limiting competitive entry for pure-play renewable contractors.
- Grid connection queue congestion:Terna SPA interconnection approval timelines extend developer holding costs and compress EPC margin buffers for projects awaiting energization.
Strategic Opportunities
- Seismic Zone 2 civil specialization:Central Italian geologies require earthquake-resistant foundation engineering that commands premium pricing from qualified structural contractors.
- Design-build single-point accountability:Developer preference for consolidated risk allocation is displacing traditional multi-contractor project structures in utility-scale solar deployments.
- EU Recovery Fund facility financing:Italy's National Recovery and Resilience Plan allocates capital grants that de-risk early-stage development and accelerate contractor backlog conversion.
Industry Challenges
- Offshore welding certification bottlenecks:Floating wind platform fabrication requires specialized maritime qualifications that extend workforce mobilization timelines.
- Legacy thermal asset remediation liability:Decommissioning obligations for retired fossil plants impose unexpected site preparation costs on adjacent greenfield renewable projects.
- 132-380 kV substation integration complexity:Grid interconnection engineering must reconcile variable renewable output profiles with Terna SPA transmission stability protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Power EPC Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Solar, Wind, Hydropower, Thermal Contractor Type: General Contractor, Specialty Contractor, Subcontractor, Independent Engineer Service Type: Design-Build, Engineering, Procurement, Construction End User: Utilities, Industrial Facilities, Commercial Users, Government Entities |
| Companies Covered | Carlo Gavazzi Impianti, Saipem SpA, Wärtsilä Oyj Abp, Alectris, Webuild S.p.A., STC Power Srl, Demont Srl, Juwi AG, Maire Tecnimont SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Power EPC Market Shifts & Advancements
Digital twin modeling and modular construction methods are compressing project delivery schedules while ARERA's evolving rate-case frameworks reshape capital recovery timelines for transmission-linked generation assets.
Floating foundation platforms for Adriatic offshore wind is unifying marine construction expertise from oil service heritage with renewable-specific load calculations. TSOs and large independent developers are specifying these systems for 50+ meter water depths where fixed-bottom economics fail. The technology is unifying previously separate supply chains for steel fabrication, dynamic cable installation, and mooring engineering into integrated EPC packages.
Italy's CNEL regional coordination mandates are channeling project approvals toward provinces with pre-certified environmental assessments, compressing permitting timelines for compliant developers. ARERA's transmission tariff benchmarks now incorporate grid stability service valuations that favor flexible generation technologies. Southern regions with established solar clusters are capturing disproportionate administrative resource allocation under this framework.
Developers are consolidating procurement authority under single design-build contractors to eliminate interface risk between civil, electrical, and marine work packages. This concentration is displacing fragmented subcontractor management models that dominated early utility-scale solar deployment. Sicily and Puglia project pipelines exhibit the strongest contractor consolidation as auction density rewards execution speed over lowest-bid procurement.
Italy Power EPC Market Segmentation
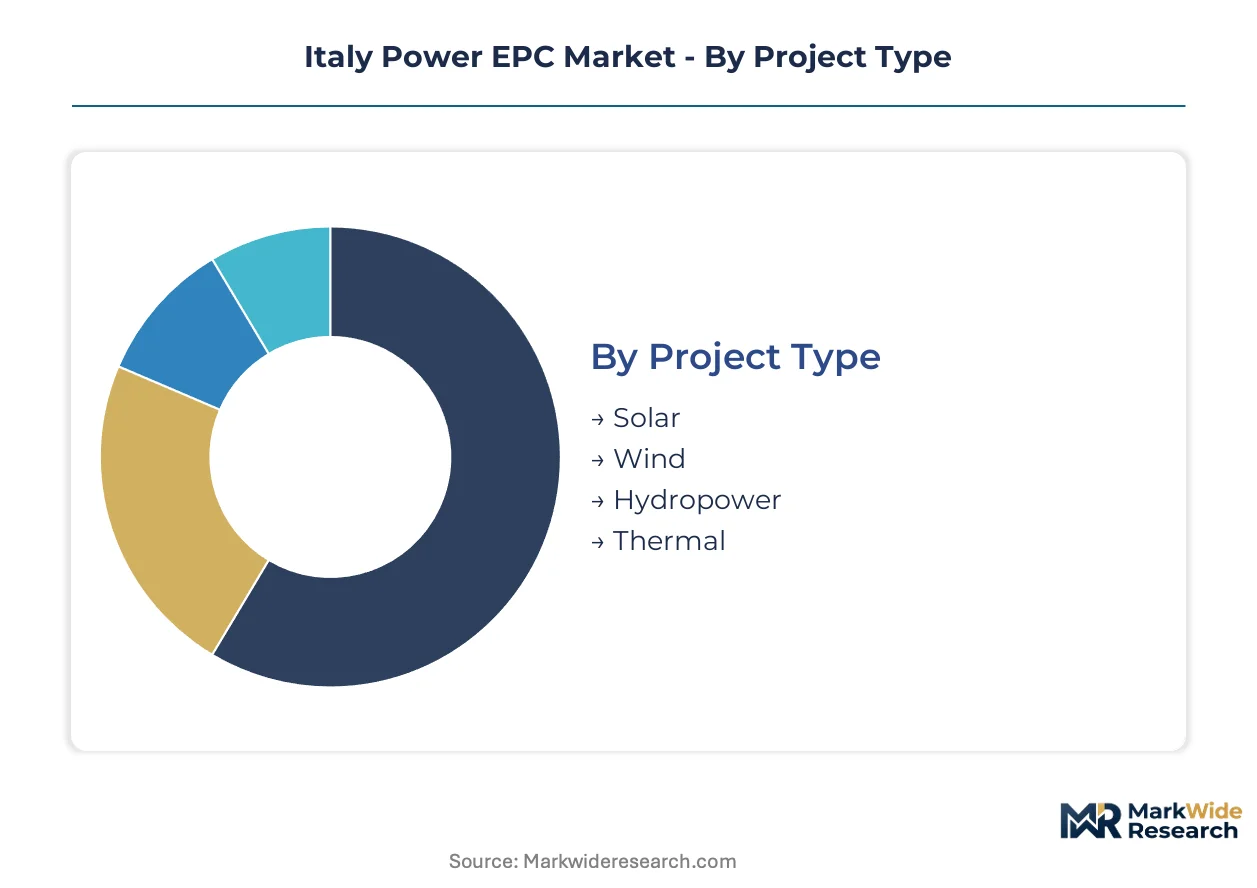
Segmentation in Italy's Power EPC market reveals how auction mechanisms and grid connection requirements reshape contractor specialization. Developer procurement patterns concentrate demand across distinct project types and service configurations that align with Terna SPA's transmission modernization timeline.
Project Type:
Buyers select project types based on resource availability profiles and ARERA tariff benchmarks that favor specific generation technologies in southern regions.
- Solar:Photovoltaic installations dominate contractor backlogs as Sicily and Puglia's irradiation levels support utility-scale deployments. Auction density in these provinces compresses development timelines and rewards execution speed.
- Wind:Offshore floating platforms in Adriatic waters above 50-meter depths require marine engineering heritage from legacy oil service firms. Foundation fabrication and dynamic cable installation constitute the critical path for project delivery.
- Hydropower:Small-scale run-of-river retrofits and pumped storage integration serve grid stability mandates under EU Green Deal protocols.
- Thermal:Hydrogen-ready combined cycle retrofits extend asset lifecycles for plants seeking fuel flexibility compliance with emission reduction targets.
Solar leads on scale; Wind leads on momentum.
Contractor Type:
Contractor selection hinges on risk allocation preferences and the technical complexity thresholds of marine versus terrestrial construction.
- General Contractor:Full-scope accountability for utility-scale solar and thermal retrofits spans civil works, electrical installation, and grid interconnection. Design-build consolidation favors these entities for single-point responsibility.
- Specialty Contractor:Premium margins attach to offshore wind foundation work where steel-reinforced concrete designs for floating platforms concentrate among firms with seismic Zone 2 and marine welding certifications.
- Subcontractor:Fragmented labor pools supply electrical cabling, turbine erection, and site preparation under prime contractor direction.
- Independent Engineer:Technical due diligence and lender advisory services support project finance structures for EU Recovery Fund-backed developments.
General Contractor captures volume concentration; Specialty Contractor captures margin expansion.
Service Type:
Service procurement patterns reflect developer preferences for consolidated risk transfer versus retained control over specific work packages.
- Design-Build:Single-point accountability accelerates utility-scale renewable deployments by eliminating interface risk between civil, electrical, and marine disciplines. Sicily and Puglia pipelines exhibit strongest consolidation under this model.
- Engineering:Seismic-resistant foundation design and 132-380 kV substation integration command specialized technical input for central Italian geologies.
- Procurement:Equipment sourcing for turbines, inverters, and dynamic cables operates under long-lead schedules vulnerable to steel and copper price volatility.
- Construction:Field execution encompasses turbine installation, grid interconnection, and civil works with Zone 2 seismic compliance.
Design-Build climbs the fastest; Engineering holds defensive value.
End User:
End-user segmentation tracks capital deployment capacity and regulatory access that determine project origination velocity.
- Utilities:Terna SPA transmission investments and distribution modernization anchor the largest contract values. Grid stability service valuations under ARERA tariff frameworks favor flexible generation procurement.
- Industrial Facilities:Cogeneration and captive renewable installations serve emission compliance mandates while hedging against wholesale price volatility.
- Commercial Users:On-site solar and power purchase agreements support corporate sustainability targets with shorter development cycles than utility-scale alternatives.
- Government Entities:National Recovery and Resilience Plan allocations de-risk public-sector renewable procurement through capital grant mechanisms.
Utilities lead on contract scale; Industrial Facilities lead on procurement velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lombardy's engineering concentration anchors Italy's Power EPC contractor ecosystem. Terna SPA's transmission investments channel procurement toward southern irradiation zones while northern industrial clusters supply specialized equipment. Regional specialization patterns concentrate solar development in Sicily and Puglia against offshore wind engineering emerging from Adriatic port infrastructure.
Sicily
Utility-scale photovoltaic deployments dominate contractor backlogs as auction density compresses development timelines. ARERA tariff benchmarks favor rapid execution in provinces with pre-certified environmental assessments. The Syracuse-Agrigento corridor captures disproportionate administrative resource allocation under CNEL regional coordination mandates.
Puglia
Superior solar irradiation profiles attract developer interest with foundation work requiring seismic Zone 2 civil specialization. EU Recovery Fund facility financing de-risks early-stage development through capital grant mechanisms. The Brindisi-Taranto industrial zone hosts grid interconnection engineering for 132-380 kV substation integration.
Campania
Offshore wind fabrication capabilities concentrate around legacy maritime engineering heritage from oil service supply chains. Floating platform designs for 50+ meter Adriatic depths demand marine welding certifications that extend workforce mobilization timelines. The Naples port cluster anchors steel-reinforced concrete foundation assembly for deep-water turbine installations.
Lazio
Thermal plant retrofit demand concentrates around hydrogen-ready combined cycle technology extending asset lifecycles. ARERA revenue benchmarks for transmission investments reshape capital recovery timelines for grid-linked generation assets. The Rome metropolitan coordination zone channels CNEL regional planning toward central Italian geologies.
Emilia-Romagna
Industrial cogeneration installations serve emission compliance mandates for manufacturing facilities hedging wholesale price volatility. Design-build procurement consolidation eliminates interface risk between civil, electrical, and mechanical work packages. The Bologna-Modena engineering corridor supplies seismic-resistant foundation design expertise for central Italian deployments.
Italy Power EPC Market Competitive Landscape
Global majors compete with regional champions across marine engineering heritage and civil infrastructure specialization. The vendor base stratifies between full-scope general contractors capturing utility-scale solar volume and specialty operators commanding premium margins in offshore wind foundation work. Three archetypes dominate: integrated design-build entities, marine construction heritage firms, and hydrogen-ready thermal retrofit specialists. Competitive positioning depends on M&A activity consolidating procurement authority and strategic partnerships securing floating platform fabrication capacity.
Among Italy-based contractors, Saipem SpA and Webuild S.p.A. exemplify the marine-civil dual capability archetype, while Maire Tecnimont SpA occupies a position within hydrogen-ready combined cycle specialization. These entities represent the convergence of legacy infrastructure engineering with renewable-specific technical thresholds.
| Leading Market Players |
|---|
| Carlo Gavazzi Impianti |
| Saipem SpA |
| Wärtsilä Oyj Abp |
| Alectris |
| Webuild S.p.A. |
| STC Power Srl |
| Demont Srl |
| Juwi AG |
| Maire Tecnimont SpA |
| Others |
Supply & Pricing Matrix
Utility-scale solar developers concentrated in Sicily and Puglia operate under project-based pricing models where EPC contractors compete on total installed cost per megawatt. ARERA auction mechanisms compress margin buffers by rewarding lowest compliant bids, forcing contractors to optimize steel and copper procurement exposure through long-term supply agreements.
Pricing Analysis
Input-cost pass-through dominates contractor pricing structures, with steel-reinforced concrete and dynamic cabling constituting the largest variable cost buckets. Price differentiation hinges on marine welding certification tiers and seismic Zone 2 engineering capabilities that command premium positioning for Adriatic offshore work. Pricing pressure intensifies as grid connection queue congestion extends developer holding costs and compresses EPC bid margins. Industrial cogeneration buyers exhibit highest price sensitivity due to wholesale price hedging objectives, while floating wind developers accept premium pricing for scarce marine engineering heritage.
Supply Chain Analysis
Single-source vulnerability sits with Chinese steel fabrication for turbine tower components and South Korean dynamic cable manufacturing for offshore interconnection. The supply chain draws from German electrical switchgear, Italian civil engineering labor pools, and Spanish foundation steel. Commodity price volatility in copper and steel reinforcement materials poses structural risk to project cost forecasting. Distribution runs through Terna SPA's transmission interconnection queue, where substation integration timelines determine project energization sequencing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy Power EPC market functions as a stable compounder anchored by EU Green Deal emission mandates that guarantee replacement demand for thermal assets through predictable regulatory timelines.
For Market Incumbents: Lock in floating platform fabrication capacity through exclusive partnerships with Adriatic port infrastructure operators before marine welding certification bottlenecks worsen. Secure backward integration into steel-reinforced concrete supply through captive relationships with seismic Zone 2 specialized contractors, insulating margin buffers from commodity volatility that threatens bid competitiveness in ARERA auctions.
For New Entrants and Emerging Players: Capture design-build consolidation opportunities in Sicily and Puglia utility-scale solar pipelines where execution speed rewards outweigh lowest-bid procurement. Target industrial cogeneration retrofits in Emilia-Romagna manufacturing corridors as the most penetrable segment, leveraging equipment supplier financing partnerships to overcome capital barriers that constrain pure-play renewable entrants.
For Investors and Strategic Acquirers: Marine construction heritage firms from legacy oil service supply chains are the most active acquirer in this space, consolidating floating wind engineering capabilities ahead of Adriatic lease round acceleration. The five-to-ten year viability window favors contractors with hydrogen-ready combined cycle retrofit expertise as thermal asset lifecycles extend through fuel flexibility investments. Monitor Terna SPA transmission tariff benchmark revisions as the critical inflection signal for grid stability service valuation shifts that favor flexible generation procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Floating Platform Fabrication Partnership | Saipem SpA leverages marine construction heritage to anchor Adriatic deep-water turbine installation capabilities. |
| Design-Build Procurement Consolidation | Webuild S.p.A. eliminates interface risk between civil, electrical, and marine disciplines for utility-scale solar developers. |
| Hydrogen-Ready Combined Cycle Retrofit | Maire Tecnimont SpA extends thermal asset lifecycles through fuel flexibility compliance with EU Green Deal mandates. |
| Seismic Zone 2 Civil Specialization | Qualified structural contractors command premium pricing for earthquake-resistant foundation engineering in central Italian geologies. |
| EU Recovery Fund Facility Financing | Capital grant mechanisms de-risk early-stage development and accelerate contractor backlog conversion in southern regions. |
Research Methodology
Coverage spans Italy's southern solar irradiation zones, central industrial corridors, and Adriatic offshore wind development areas, with primary inputs from each. The analysis combines structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation from ARERA regulatory filings, Terna SPA transmission investment disclosures, EU Recovery Fund allocation databases, and CNEL regional coordination mandates. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling were triangulated to establish market sizing.
Granularity-level modeling captured project type, contractor type, service type, and end user segmentation across the projection horizon. CAGRs were derived through regression analysis of auction calendar density, grid connection queue length trajectories, and capital grant disbursement velocity. Industry-specific forecast inputs incorporated floating platform fabrication capacity constraints and seismic Zone 2 engineering labor pool availability.
Commodity price volatility, regulatory auction schedule shifts, and marine welding certification throughput delays are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about ARERA tariff benchmark stability and EU Green Deal implementation continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Critical Power Market
Power
Denmark Power Market
Power
North America CHP Market
Power
Telecom Power Rental Market
Power
Resonant Power Converters Market
Power
Europe Solar Inverter Market
Power
Asia-Pacific Package Substation Market
Power
Recloser Control Market
Power
Kuwait Power Market
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
Europe Submarine Power Cables Market
Power
Electric Arc Furnaces Market
Power
Russian Federation Power Market
Power
Distributed Buoyancy Modules Market
Power
Solar Plants Controllers Market
Power
Modified Sine Wave Home Inverters Market