
 Oil and Gas Fabrication Market | 2026-2036
Oil and Gas Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Fabrication Market Analysis
Offshore platform demand is hardening as deepwater exploration budgets recover across the Atlantic margin. TechnipFMC plc leverages its integrated subsea-to-surface capabilities to anchor long-term contracts in harsh-environment basins. McDermott sustains fabrication dominance through modular construction scale at its Middle East and Southeast Asia yards. Bechtel Corporation differentiates via EPC execution discipline on mega-LNG export projects.
Oil and gas fabrication encompasses the engineered construction of pressure-boundary equipment, structural modules, and process skids using ASME-certified welding procedures, sour-service metallurgy, and dimensional tolerances measured in millimeters for subsea mating operations. Its primary purpose is converting raw steel and alloy into field-installable assets that contain hydrocarbons under extreme pressure, temperature, and corrosive conditions. Pipeline fabrication commands the largest value pool due to trunkline replacement cycles, while subsea engineering represents the fastest-growing technology segment as tieback architectures replace fixed platforms. Storage tanks remain a mature product category with margin compression from standardized designs and regional oversupply.
The American Petroleum Institute governs welding and material standards that dictate contractor qualification and project bid eligibility across North American waters. Brazil's national petroleum regulator enforces local content requirements that force fabrication partners to maintain domestic yard capacity. The EU F-Gas Regulation and REACH framework constrain insulation and coating chemistries used on North Sea assets. Stakeholders must monitor how carbon-border adjustment mechanisms and methane-emission thresholds reshape supplier qualification criteria without warning.
Market Dynamics
Deepwater tieback architectures are displacing fixed-platform fabrication across Atlantic margin basins, compressing project timelines from 48 months to 18 months and rewiring supplier qualification criteria around subsea integration capabilities rather than topside construction scale.
Growth Catalysts
- Pre-salt basin development:Brazil's national petroleum regulator mandates local content thresholds that sustain domestic yard utilization and force international fabricators to establish permanent Brazilian facilities.
- API welding standard updates:The American Petroleum Institute's revised sour-service protocols expand addressable market for contractors holding current certifications, particularly in US Gulf of Mexico high-pressure reservoirs.
- Modular construction adoption:LNG export terminal developers specify skid-mounted process trains that reduce field construction labor and accelerate commissioning schedules.
Market Restraints
- Alloy price volatility:Nickel and molybdenum input costs swing unpredictably, eroding fabrication margin on fixed-price EPC contracts signed 12-18 months before steel procurement.
- Specialized yard concentration:Heavy-lift capacity for integrated topsides concentrates in Singapore, South Korea, and the UAE, creating single-source vulnerability for mega-project schedules.
- Subsea welding technical ceiling:Hyperbaric dry welding at depths exceeding 3,000 meters remains commercially unproven, limiting tieback architectures in ultra-deepwater frontiers.
Strategic Opportunities
- Guyana-Suriname basin emergence:ExxonMobil's string of discoveries creates first-mover advantage for fabricators establishing modular assembly presence in Trinidad or northern Brazil.
- EU F-Gas Regulation compliance:REACH-constrained coating and insulation chemistries favor European fabricators with certified low-GWP material supply chains for North Sea decommissioning replacement projects.
- Digital twin integration:Convergence of laser scanning and physics-based simulation enables fabricators to sell predictive maintenance subscriptions alongside physical assets.
Industry Challenges
- Subsea welding technician scarcity:Hyperbaric dry welding certification programs produce fewer than 200 qualified welders annually against project pipeline demand.
- ASME Section IX recertification timelines:Procedure qualification record updates require 90-120 days, creating bid eligibility gaps when standards revise mid-tender cycle.
- Legacy platform integration complexity:Brownfield tieback designs must interface with 30-year-old topsides lacking as-built documentation, driving field verification costs upward.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Fabrication Market |
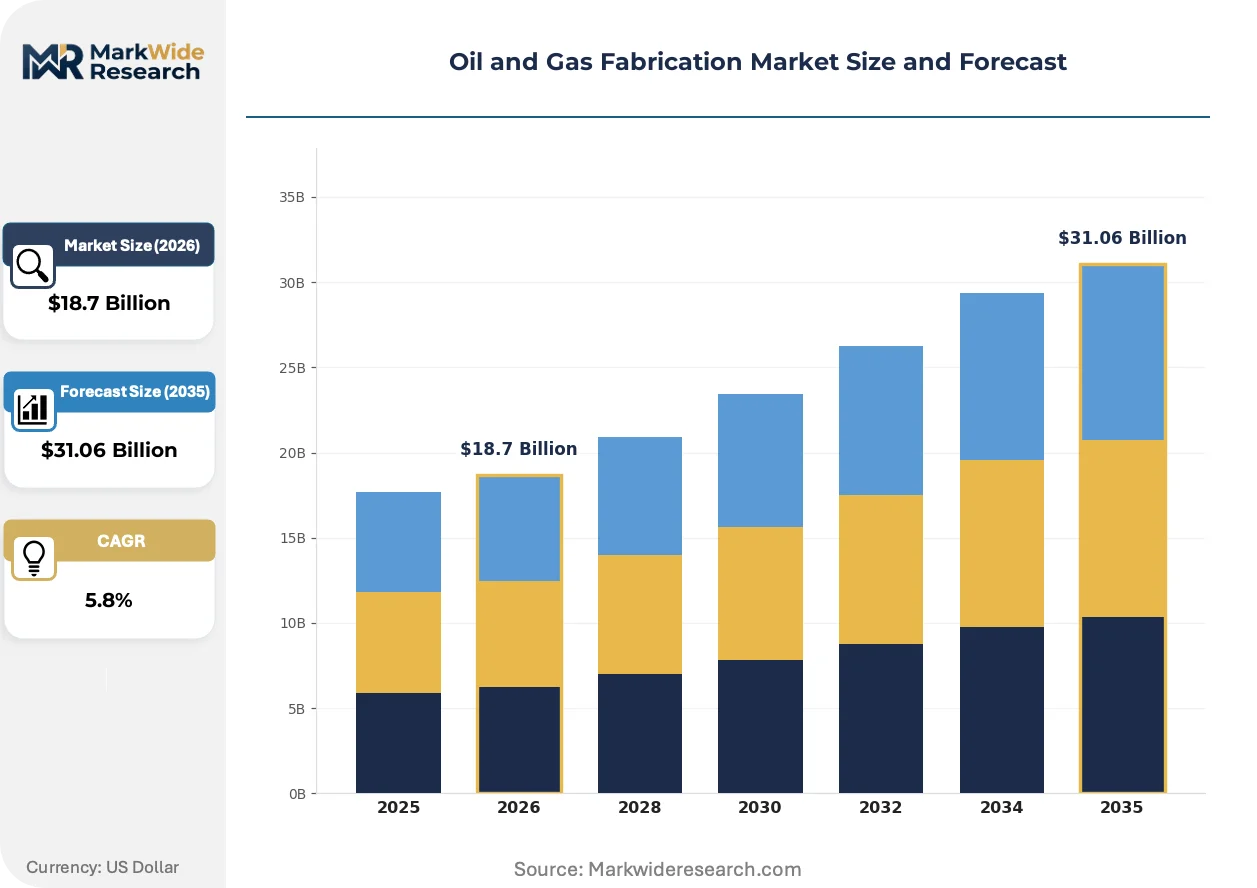
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Rigs, Pipelines, Offshore Platforms, Storage Tanks Technology: Subsea Engineering, Advanced Materials, CAD/CAM Technology, Automation Systems Application: Exploration, Production, Transportation, Refining End User: Oil Companies, Gas Operators, EPC Contractors, Service Providers |
| Companies Covered | National Petroleum Construction Company, Gulf Piping Company, Bechtel Corporation, Fluor Corporation, KBR Inc., McDermott, Petrofac Limited, SAIPEM SpA, TechnipFMC plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Fabrication Market Emerging Trajectories
Digital fabrication workflows and advanced joining technologies are compressing dimensional tolerances while expanding the addressable water depth for economically viable developments.
Additive manufacturing of Inconel 625 components is decentralizing spare parts logistics for subsea manifolds and wellhead connectors. Operators in the US Gulf of Mexico now print critical path items at shore bases rather than maintaining 90-day inventory buffers at Singapore consolidation hubs. This shift collapses lead times from 16 weeks to 72 hours and reduces working capital intensity for marginal field tiebacks.
The EU F-Gas Regulation and REACH framework are forcing coating reformulation across North Sea fabrication yards. Solvent-based epoxy systems face phase-out timelines that compress supplier qualification windows to 18 months. Contractors with in-house polymer chemistry capabilities secure preferential bidding status on Norwegian and UK decommissioning replacement projects.
Buyer consolidation among supermajors is concentrating procurement authority into centralized technical centers in Houston, London, and Singapore. This eliminates regional fabrication yard relationships and replaces them with global framework agreements spanning 3-5 year horizons. Marginal fabricators without Tier 1 operator accreditation face volume starvation as procurement teams reduce approved vendor lists from 40 to 12 suppliers.
Oil and Gas Fabrication Market Segmentation
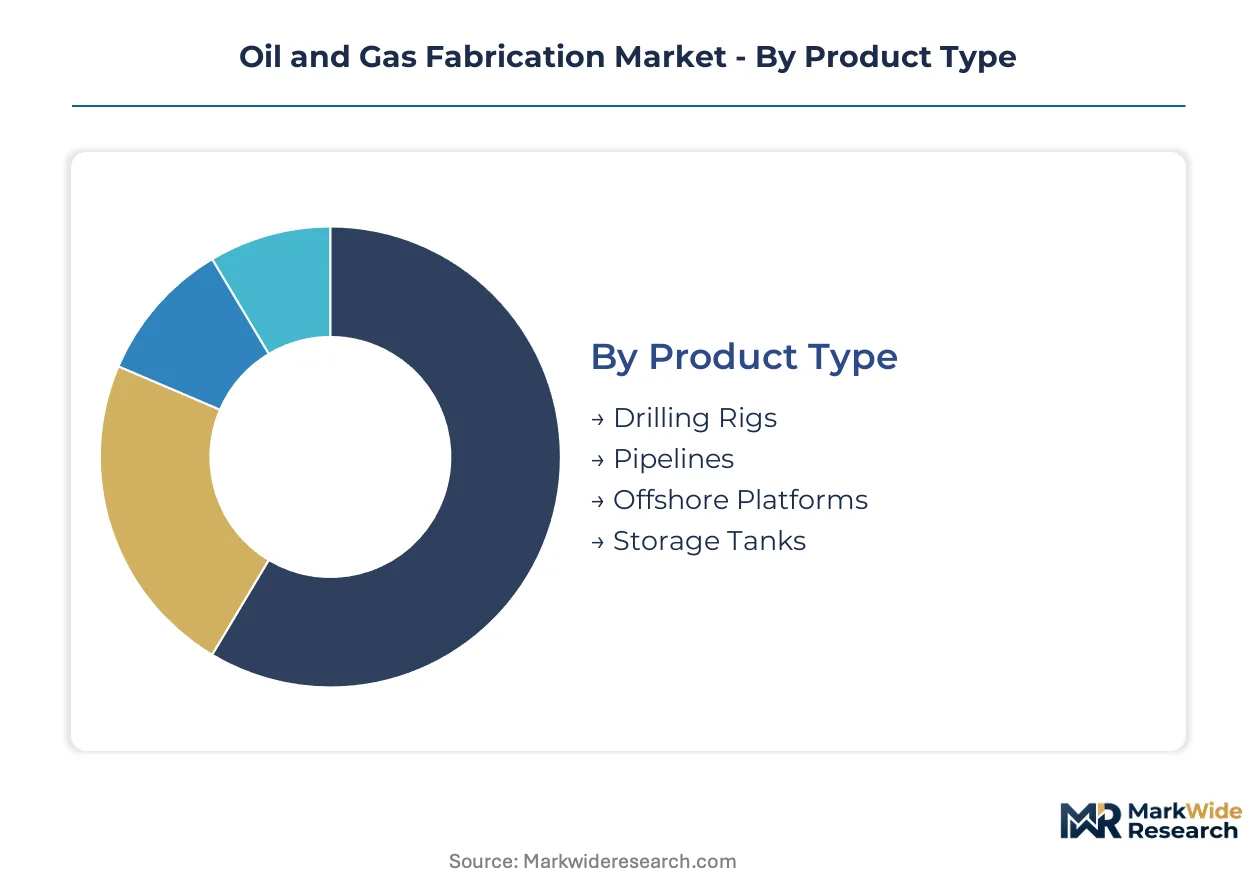
Segmentation in oil and gas fabrication reveals how procurement authority, technical complexity, and project economics fragment across distinct buyer types and application contexts. Understanding these divides exposes where margin pools concentrate and which capability investments yield competitive access.
Product Type:
Buyers differentiate by field development architecture—deepwater tiebacks versus onshore shale versus brownfield expansion—each dictating distinct metallurgical, dimensional, and logistics requirements.
- Pipelines:Trunkline replacement cycles across mature basins sustain steady fabrication demand for high-strength steel with sour-service corrosion resistance. US Gulf of Mexico operators and Brazil's pre-salt developers drive specification intensity around ultra-deepwater flowline welding protocols.
- Offshore Platforms:Fixed-leg jackets and floating production facilities demand integrated topside-module construction at heavy-lift yards in Singapore, South Korea, and the UAE. Atlantic margin deepwater budgets are hardening, compressing project timelines and rewarding fabricators with subsea-to-surface integration capabilities.
- Drilling Rigs:Jackup and semisubmersible hull construction concentrates in specialized shipyards with leg-fabrication and jacking-system integration expertise.
- Storage Tanks:Atmospheric and pressurized tank farms for terminals and refineries face margin compression from standardized API 650/620 designs and regional yard oversupply.
Volume sits with pipelines; growth tilts toward offshore platforms.
Technology:
Technology selection tracks water depth, reservoir pressure, and regulatory chemistry constraints—factors that stratify supplier qualification tiers.
- Subsea Engineering:Manifold, jumper, and riser fabrication for tieback architectures requires hyperbaric welding and pressure-testing capabilities. The technical ceiling at 3,000 meters remains commercially unproven, limiting ultra-deepwater frontier access.
- Advanced Materials:Inconel 625 cladding and duplex stainless steel address high-pressure, high-temperature, and corrosive reservoir conditions. REACH and EU F-Gas Regulation compliance is forcing coating reformulation across North Sea fabrication yards.
- CAD/CAM Technology:Digital twin integration through laser scanning and physics-based simulation enables predictive maintenance subscription models alongside physical asset delivery.
- Automation Systems:Robotic welding and modular assembly lines reduce field construction labor and accelerate commissioning schedules at LNG export terminals.
Revenue concentrates in subsea engineering; capability gaps are widening fastest in advanced materials.
Application:
Application segmentation maps to hydrocarbon value chain position—upstream exploration through downstream refining—each with distinct contracting rhythms and technical risk profiles.
- Production:Field development fabrication spans subsea trees, processing platforms, and artificial lift systems. Brazil's national petroleum regulator mandates local content thresholds that force international fabricators to establish permanent domestic facilities.
- Exploration:Wildcat drilling support structures and temporary production facilities face cyclical demand tied to lease sale timing and frontier basin licensing rounds.
- Transportation:Compressor stations, pump stations, and marine loading terminals require repetitive, specification-driven fabrication with lower margin but higher volume predictability.
- Refining:Process vessel and reactor fabrication for downstream upgrades competes with petrochemical and power sector contractors for ASME-certified shop capacity.
Procurement volume favors production; exploration exhibits the steepest demand volatility.
End User:
End user type determines contracting structure—direct owner purchase versus EPC wrap—and shapes risk allocation, payment terms, and technical specification authority.
- EPC Contractors:Engineering-procurement-construction integrators aggregate fabrication demand across mega-projects, concentrating procurement authority in Houston, London, and Singapore technical centers. Framework agreements spanning 3-5 years are reducing approved vendor lists from 40 to 12 suppliers.
- Oil Companies:Supermajor direct procurement of critical subsea equipment bypasses EPC markups but demands dedicated supplier technical support and inventory positioning.
- Gas Operators:LNG-focused developers specify skid-mounted process trains and modular cryogenic equipment with accelerated delivery schedules.
- Service Providers:Rental and maintenance contractors drive aftermarket fabrication demand for replacement components and upgrade modules.
Contract flow concentrates through EPC contractors; direct oil company procurement is expanding fastest in subsea categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones in Singapore, the UAE, and South Korea concentrate heavy-lift fabrication capacity for integrated topsides. Tax incentives and customs-free import regimes for alloy steel attract EPC contractors seeking modular construction scale. These zones anchor the geographic distribution of oil and gas fabrication demand.
United States
Deepwater exploration budgets in the Gulf of Mexico are hardening, with operators specifying sour-service welding protocols for high-pressure reservoirs. The American Petroleum Institute governs contractor qualification through updated Section IX standards that expand addressable market for certified fabricators. Houston hosts centralized procurement technical centers where supermajors consolidate framework agreements.
Brazil
Pre-salt basin development sustains domestic yard utilization through local content mandates enforced by the national petroleum regulator. International fabricators must establish permanent Brazilian facilities to bid on Petrobras-led projects. The Porto do Açu complex in Rio de Janeiro state anchors modular assembly operations for floating production facilities.
Singapore
Jurong Island's tax-advantaged status and deep-water quayside infrastructure support integrated topside-module construction for Atlantic margin developments. The Maritime and Port Authority coordinates heavy-lift vessel scheduling for mega-project execution. Jurong Shipyard and Sembcorp Marine facilities concentrate hyperbaric welding capability for subsea manifolds.
United Arab Emirates
Jebel Ali Free Zone incentives attract EPC contractors seeking fabrication scale for Middle East and African upstream projects. The zone's customs-free alloy steel import regime reduces working capital intensity for fixed-price contracts. Dubai Maritime City and Kizad industrial zone host modular construction yards serving LNG export terminal developers.
Norway
North Sea decommissioning replacement projects drive specification intensity around low-GWP coating chemistries constrained by the EU F-Gas Regulation. The Norwegian Petroleum Directorate enforces REACH-compliant material standards for subsea infrastructure. Stavanger and Bergen clusters anchor engineering-procurement centers for harsh-environment tieback architectures.
Oil and Gas Fabrication Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated EPC contractors dominating mega-project procurement while niche fabricators capture subsea equipment categories. The vendor base concentrates into three tiers: global framework agreement holders with 3-5 year operator accreditations, regional yard operators serving single-basin developments, and specialized subsea engineering houses. Market structure favors scale-driven consolidation through strategic partnerships and capacity expansion at tax-advantaged zones.
Among integrated EPC contractors, Bechtel Corporation, Fluor Corporation, and McDermott exemplify the tier-one archetype that anchors procurement authority in Houston, London, and Singapore technical centers. These firms occupy positions defined by modular construction scale and ASME-certified welding procedure libraries rather than geographic specialization. TechnipFMC plc and SAIPEM SpA represent the subsea-to-surface integration specialists competing on tieback architecture capabilities. National Petroleum Construction Company and Gulf Piping Company anchor the Middle East regional tier, where proximity to Saudi and UAE upstream budgets confers bidding advantages on fixed-platform and pipeline categories.
| Leading Market Players |
|---|
| National Petroleum Construction Company |
| Gulf Piping Company |
| Bechtel Corporation |
| Fluor Corporation |
| KBR Inc. |
| McDermott |
| Petrofac Limited |
| SAIPEM SpA |
| TechnipFMC plc |
| Others |
Supply Flow & Price Mechanics
Hyperbaric welding technician scarcity in Singapore and South Korea drives labor-cost differentials that widen pricing-tier spreads between certified subsea specialists and standard fabrication yards. This workforce concentration forces buyers to pay premiums for ASME Section IX-qualified contractors while spot-market yards compete on alloy procurement efficiency alone.
Pricing Analysis
Short-lead-time premiums for hyperbaric dry welding capacity separate expedited subsea contracts from standard-schedule pipeline fabrication. Three-tier pricing structure across premium certified, standard qualified, and economy spot tiers reflects ASME Section IX recertification status and sour-service protocol compliance. Price differentiation hinges on certification currency and geographic delivery cost to Atlantic margin basins. Pricing pressure stems from nickel and molybdenum alloy volatility eroding fixed-price EPC margins. EPC contractors show highest price sensitivity due to lump-sum contract exposure, while supermajor direct procurement tolerates premium pricing for subsea integration capabilities.
Supply Chain Analysis
API and ASME certification gating restricts qualified supplier pools to fabricators maintaining current procedure qualification records and sour-service welding libraries. Heavy-lift capacity concentrates in Singapore, South Korea, and the UAE, anchoring integrated topside construction for Atlantic margin developments. Raw material dependencies rest on nickel, molybdenum, and high-strength steel alloy feedstocks from specialized metallurgical suppliers. Single-source vulnerability at Jurong Island and Jebel Ali Free Zone heavy-lift yards threatens mega-project schedules. Distribution runs through centralized EPC technical centers in Houston, London, and Singapore that aggregate procurement across operator framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oil and gas fabrication is consolidating into a winner-take-most structure where buyer consolidation into 12-supplier approved vendor lists forces marginal yards into volume starvation. Framework agreement concentration rewards scale and certification depth while punishing regional single-basin operators.
For Market Incumbents: Deploy backward integration into alloy steel supply through captive metallurgical partnerships or long-term offtake agreements with nickel and molybdenum producers. Expand hyperbaric welding training pipelines through joint programs with Singapore's Maritime and Port Authority to address technician scarcity before competitor yards capture certification capacity. Lock in 3-5 year framework renewals with supermajor technical centers in Houston and Singapore to defend against emerging modular construction specialists. For New Entrants and Emerging Players: Additive manufacturing of Inconel 625 components offers a technology-first wedge into subsea spare parts logistics, collapsing 16-week lead times to 72-hour shore-base delivery. Target Guyana-Suriname basin developments through Trinidad or northern Brazil modular assembly presence before incumbent fabricators establish local content-compliant facilities. Lead with digital twin integration capabilities that bundle predictive maintenance subscriptions with physical asset delivery to bypass capital-intensive yard infrastructure requirements. For Investors and Strategic Acquirers: Re-rating potential sits with subsea-to-surface integration specialists given deepwater tieback architecture displacement of fixed platforms across Atlantic margin basins. Long-term viability favors fabricators with proven hyperbaric welding depth capability and established operator framework accreditation. Acquisition target archetype: mid-cap yards with ASME-certified procedure libraries but lacking EPC wrap capability to bolt onto integrated contractor platforms. Watch API Section IX standard revision timing as inflection indicator for recertification-driven vendor list shakeouts.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperbaric Welding Capacity Expansion | Addresses technician scarcity constraining subsea project pipelines across Brazil's pre-salt and US Gulf of Mexico. |
| Modular Construction Scale-Up | Reduces field labor costs and accelerates LNG export terminal commissioning schedules for Middle East developers. |
| Digital Twin Platform Integration | Enables predictive maintenance subscription revenue alongside physical asset sales to Atlantic margin operators. |
| Alloy Supply Backward Integration | Hedges nickel and molybdenum price volatility eroding fixed-price EPC contract margins. |
| Brazil Local Content Compliance | Secures bidding eligibility on Petrobras-led pre-salt developments through permanent domestic yard presence. |
Methodological Framework
Independent corroboration across fabrication yard operators, EPC procurement executives, and subsea engineering specialists underwrites the qualitative findings in this study. Primary interviews with hyperbaric welding technicians, ASME certification auditors, and supermajor technical center managers combined with secondary validation from API standard documentation, ANP local content filings, and EU REACH compliance databases. Bottom-up project pipeline tracking across Brazil, US Gulf of Mexico, and North Sea developments triangulates against top-down EPC contract award analysis.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. The forecast framework models fabrication demand by product type (pipelines, offshore platforms, subsea equipment, storage tanks), technology tier (subsea engineering, advanced materials, automation systems), and end-user contracting structure (EPC wrap versus direct operator procurement). CAGRs derive from project sanctioning timelines, replacement cycle analysis for trunkline infrastructure, and tieback architecture adoption curves. Industry-specific inputs include deepwater exploration budget trajectories and local content threshold enforcement patterns.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to API welding standards, abrupt alloy price shocks beyond historical volatility bands, and breakthrough advances in hyperbaric dry welding beyond 3,000 meters. Forecasts reflect assumptions about operator framework agreement renewal rates and EPC vendor list consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil and Gas Accumulators Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Mexico Oil and Gas Downstream Market
Oil & Gas
Mexico Oil and Gas Market
Oil & Gas
North America Natural Gas Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Subsea Well Access System Market
Oil & Gas
Copper Mining Market