
 North America Power Market | 2026-2036
North America Power Market Size, Share, and Industry Trends Forecast 2026-2036
North America Power Market Analytics
The US Inflation Reduction Act is pivoting utility investment toward tax-credit-eligible clean energy combinations. NextEra Energy leverages its Florida and Texas renewable development pipeline to capture production tax credit value at scale. Duke Energy anchors its Carolinas regulated footprint with nuclear relicensing and grid hardening programs. Vistra competes in Texas through its integrated retail and generation platform, balancing renewable output with dispatchable natural gas capacity.
North America power encompasses the generation, transmission, and distribution of electrical energy across voltage classes from 120V residential service to 765kV interstate transmission, with system reliability maintained through synchronized alternating current at 60Hz. The primary purpose is to deliver economically dispatchable energy to end users while maintaining grid stability through real-time frequency regulation and reactive power management. Renewable Energy and Natural Gas dominate new capacity additions, with photovoltaic plus battery storage configurations capturing the fastest expansion as lithium-ion costs decline and interconnection standards tighten. Grid Supply applications retain the largest revenue pool, though Distributed Generation and Microgrid segments are deepening as commercial and industrial buyers seek resilience against extreme weather events.
FERC Order 2023 reforms to generator interconnection queues, EPA greenhouse gas performance standards for existing power plants, and NERC reliability standards collectively reshape market access timelines and technology choices. These frameworks force developers to front-load grid impact studies and accelerate carbon capture or hydrogen co-firing demonstrations for fossil assets. Stakeholders must monitor how state-level renewable portfolio standards diverge from federal tax credit phase-down schedules to avoid stranded investment in transitional technologies.
Market Dynamics
The US Inflation Reduction Act production tax credits are redirecting capital toward utility-scale photovoltaic and battery storage combinations, compressing development timelines and reshaping interconnection queue priorities across ISO territories.
Growth Catalysts
- Production Tax Credits:The US IRA's 10-year credit certainty for standalone storage and solar-plus-battery hybrids is accelerating project financing commitments in ERCOT and PJM territories.
- Data Center Load Growth:Northern Virginia and Texas hyperscale facilities are expanding contracted capacity faster than traditional industrial buyers, creating dedicated offtake agreements for renewable developers.
- FERC Order 2023:The interconnection queue reform mandates cluster studies and readiness deposits, reducing speculative queue positions and accelerating viable project timelines.
Market Restraints
- Transformer Supply Bottleneck:Domestic manufacturing capacity for high-voltage power transformers remains concentrated among three North American suppliers, extending lead times beyond 24 months.
- Lithium Price Volatility:Battery storage project returns remain exposed to lithium carbonate and lithium iron phosphate cathode material cost swings from Chinese processing dominance.
- NERC CIP-014 Physical Security:Mandatory physical security assessments for critical transmission substations impose capital burdens on aging infrastructure operators without rate recovery mechanisms in restructured markets.
Strategic Opportunities
- Behind-the-Meter Microgrids:Texas commercial and industrial facilities are deploying island-capable systems combining solar, storage, and dispatchable generation to hedge against ERCOT price volatility.
- Hydrogen Co-Firing Retrofits:EPA greenhouse gas performance standards for existing power plants create regulatory pressure for natural gas turbine operators to demonstrate hydrogen blending capability.
- Canadian Hydro Export Expansion:Quebec and Manitoba hydroelectric surplus capacity offers baseload firming services for US Northeast renewable portfolios seeking capacity value.
Industry Challenges
- Interconnection Engineering Talent:Queue reform deadlines and cluster study complexity have outpaced the supply of transmission planners familiar with FERC Order 2023 compliance.
- Legacy SCADA Integration:Distribution utilities face cybersecurity and protocol compatibility barriers when retrofitting inverter-based resources onto aging supervisory control infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Power Market |
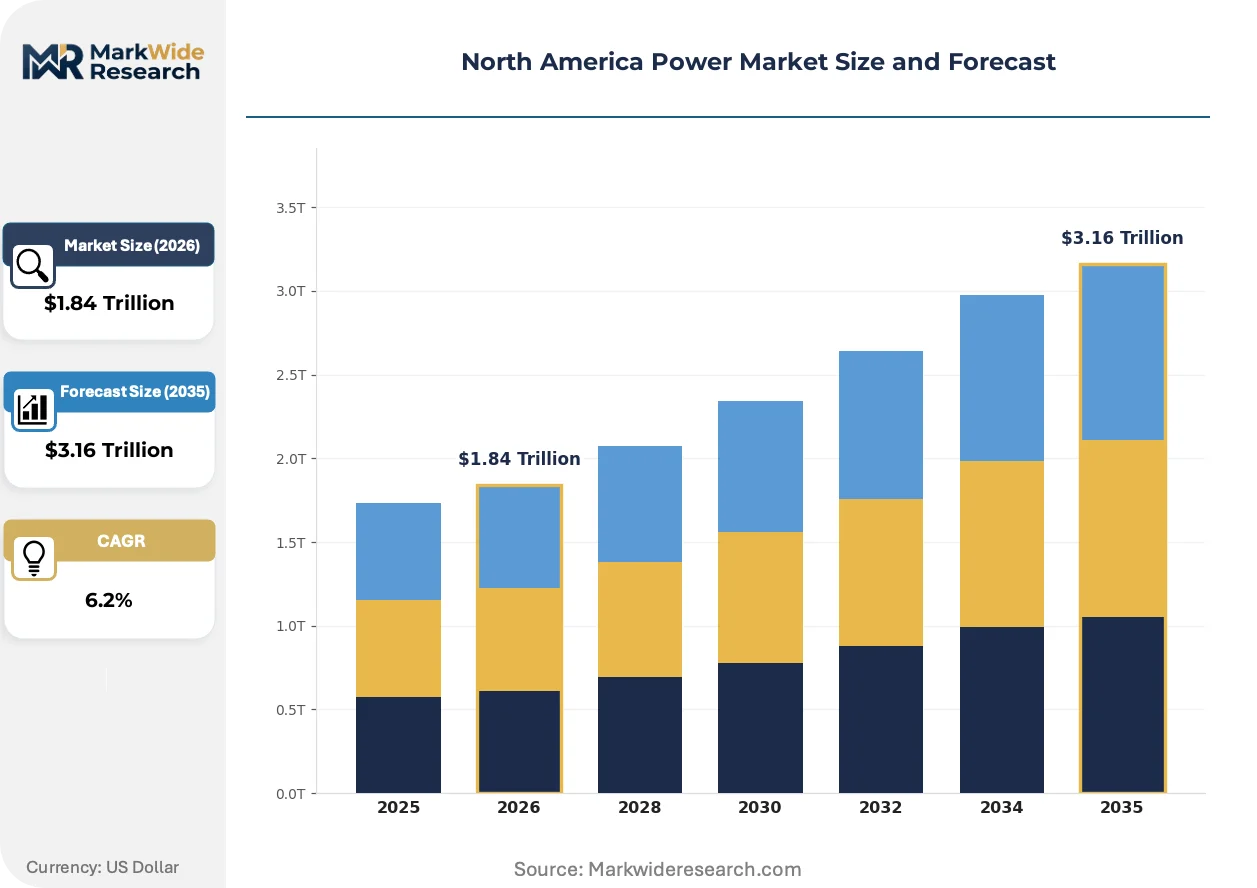
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $3.16 Trillion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable Energy, Natural Gas, Coal, Nuclear Application: Grid Supply, Distributed Generation, Backup Power, Microgrid End User: Residential, Commercial, Industrial, Utilities Technology: Photovoltaic, Wind Turbine, Hydroelectric, Energy Storage |
| Companies Covered | Duke Energy, PG&E, NextEra Energy, Exelon, Sempra Energy, Constellation Energy, American Electric Power, Vistra, Southern Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Power Market Evolving Landscape
Digital control systems and synthetic inertia technologies are actively reshaping how grid operators maintain stability amid rising inverter-based resource penetration, compressing traditional frequency response timelines.
Grid-forming inverters are automating voltage and frequency regulation functions previously requiring synchronous generation, enabling solar-plus-storage plants to provide black-start capability and primary frequency response. ERCOT and California ISO are revising interconnection requirements to mandate grid-forming behavior for new utility-scale battery installations. This technology shift is compressing the ancillary services revenue pool previously captured by natural gas peakers.
The EPA greenhouse gas performance standards for existing power plants mandate emission rate limits or co-firing demonstrations for fossil assets above 300MW. Coal and natural gas operators must front-load carbon capture retrofits or hydrogen blending infrastructure to maintain compliance timelines. Texas and Gulf Coast generators with pipeline access to hydrogen hubs face lower adaptation costs than inland coal-dependent systems.
Corporate offtake agreements are displacing traditional utility procurement as the dominant channel for renewable capacity contracting. Data center operators and Fortune 500 sustainability programs now negotiate direct virtual power purchase agreements with developers, bypassing incumbent utility green tariff programs. This channel shift concentrates most visibly in PJM and ERCOT territories where retail choice enables direct commercial relationships.
North America Power Market Segmentation
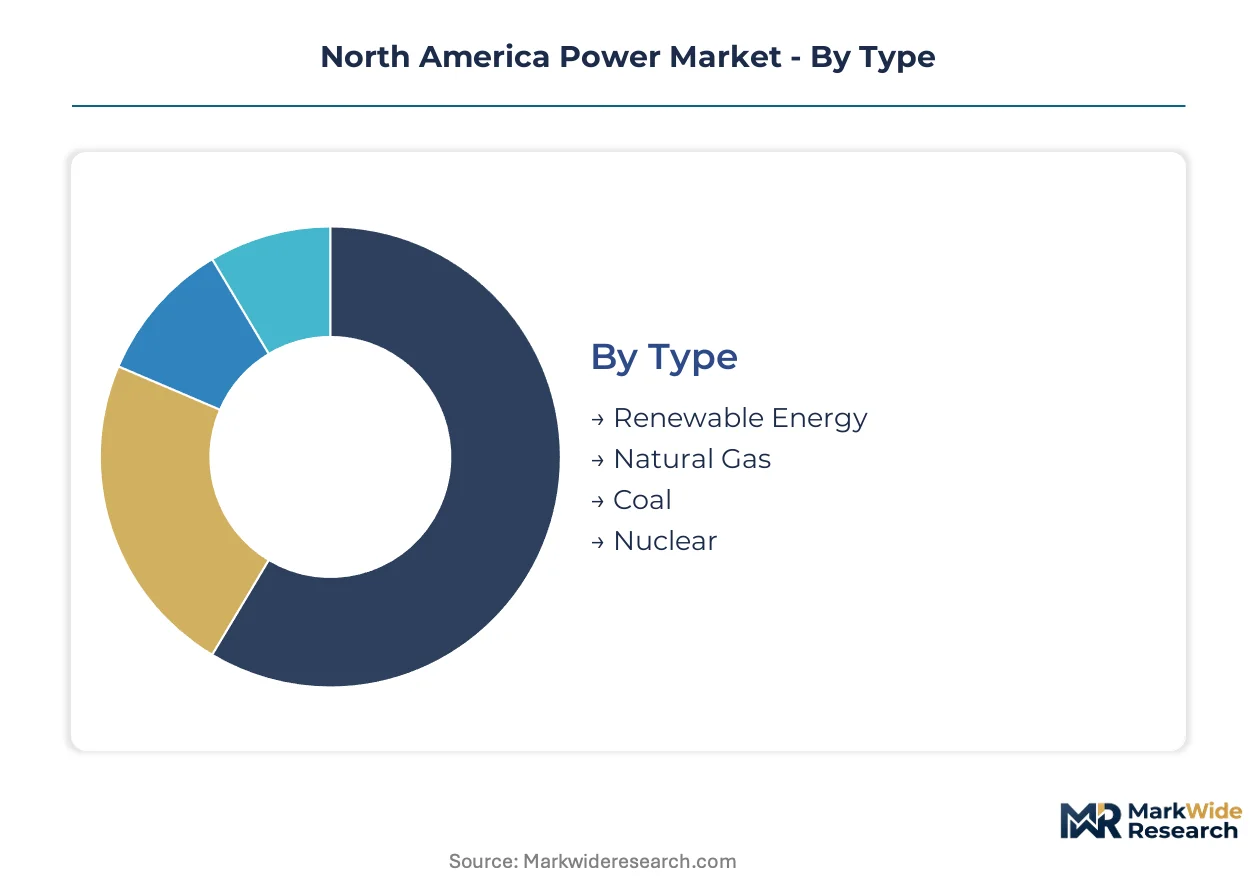
Power market segmentation reveals how capital deployment and policy incentives concentrate across generation technologies, delivery architectures, and customer classes. Understanding these divisions exposes where interconnection bottlenecks, regulatory arbitrage, and margin compression operate most intensely.
Type:
Capital intensity varies dramatically across generation technologies, with nuclear and renewable assets requiring the longest development timelines and largest upfront commitments.
- Renewable Energy:Photovoltaic and wind installations dominate interconnection queue positions across ERCOT and PJM territories. Northern Virginia data center load growth is absorbing contracted solar-plus-storage output faster than traditional utility procurement cycles.
- Natural Gas:Combined-cycle turbines provide dispatchable capacity essential for grid reliability amid rising renewable penetration. Texas generators leverage existing pipeline infrastructure to balance intermittency while hydrogen co-firing retrofits address EPA emission standards.
- Coal:Baseload plants face accelerated retirement pressure from carbon regulations and fuel cost disadvantages relative to gas and renewables.
- Nuclear:Relicensing programs at existing facilities anchor carbon-free baseload capacity with minimal marginal fuel costs.
Most installed capacity flows through Natural Gas. Expansion is steepest in Renewable Energy.
Application:
Delivery architecture determines revenue stability, with behind-the-meter configurations capturing premium pricing during grid stress events.
- Grid Supply:Utility-scale generation feeding high-voltage transmission networks constitutes the dominant revenue pool. FERC Order 2023 cluster study reforms are compressing development timelines for viable queue positions.
- Microgrid:Island-capable systems combining solar, storage, and dispatchable generation hedge against ERCOT price volatility. Texas commercial and industrial facilities are deploying these configurations fastest.
- Distributed Generation:Commercial rooftop solar and small-scale storage reduce transmission dependency for large electricity consumers.
- Backup Power:Standalone diesel and natural gas systems provide resilience for critical infrastructure during extreme weather events.
Grid Supply retains the largest revenue base. Microgrid deployments are gaining share fastest as resilience premiums justify higher capital outlays.
End User:
Customer class segmentation tracks how procurement authority and risk tolerance shape contracting structures and technology preferences.
- Industrial:Large-load facilities negotiate direct virtual power purchase agreements with developers, bypassing utility green tariffs. Data center operators in Northern Virginia and Texas are expanding contracted capacity faster than traditional manufacturing buyers.
- Utilities:Regulated and competitive retail providers balance resource adequacy mandates with shareholder return requirements. Duke Energy anchors its Carolinas footprint with nuclear relicensing while NextEra scales renewable development.
- Commercial:Corporate sustainability programs drive renewable procurement through aggregated deals and green tariff subscriptions.
- Residential:Distributed solar adoption concentrates in states with net metering policies and high retail electricity rates.
Utilities control the largest share of procured capacity. Industrial direct contracting is climbing the fastest as load growth concentrates in hyperscale facilities.
Technology:
Equipment category segmentation isolates where manufacturing scale, supply chain constraints, and performance improvements intersect.
- Photovoltaic:Module efficiency gains and domestic manufacturing incentives from the US Inflation Reduction Act are reshaping project economics. Utility-scale deployments pair with battery storage to capture production tax credit value.
- Energy Storage:Lithium-ion battery installations provide frequency regulation, capacity firming, and black-start capability. ERCOT and California ISO are mandating grid-forming inverter behavior for new utility-scale entries.
- Wind Turbine:Onshore installations in Texas and the Great Plains deliver low marginal cost generation with transmission expansion lagging behind resource development.
- Hydroelectric:Canadian surplus capacity from Quebec and Manitoba offers baseload firming services for US Northeast renewable portfolios.
Photovoltaic capacity additions dominate installation volumes. Energy Storage is expanding most quickly as interconnection standards tighten and ancillary service markets deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American power industry traces its modern scale to the Tennessee Valley Authority and Rural Electrification Act programs of the 1930s, which established the continent's integrated transmission architecture and public-private utility model.
United States
Texas and Virginia data center load growth is absorbing renewable capacity faster than traditional industrial procurement cycles. FERC Order 2023 interconnection reforms are compressing development timelines for viable queue positions across ISO territories. Northern Virginia's Loudoun County hosts the world's densest data center cluster, with contracted power demand exceeding 2,000 megawatts annually.
Canada
Quebec and Manitoba hydroelectric surplus capacity offers baseload firming services for US Northeast renewable portfolios seeking capacity value. The country's national energy regulator oversees cross-border transmission approvals under the North American Electric Reliability Corporation framework. Ontario's Bruce Power nuclear facility anchors carbon-free generation with ongoing refurbishment programs.
Mexico
Industrial manufacturing growth in Nuevo León and Baja California is driving transmission expansion from US border interconnections. The national energy regulator manages private generation permits under 2013 constitutional reforms. Monterrey's manufacturing corridor negotiates direct power purchase agreements with renewable developers to bypass traditional utility tariffs.
North America Power Market Competitive Landscape
Capital-heavy integrated utilities compete with asset-light renewable developers and retail energy providers across restructured and regulated jurisdictions. The market structure concentrates around vertically integrated holding companies in the Southeast and Midwest, while competitive retail markets in Texas and the Northeast fragment generation ownership. Three archetypes dominate: regulated utilities with rate-base growth strategies, independent power producers with renewable development pipelines, and retail-load aggregators balancing supply portfolios. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with developers securing offtake agreements ahead of interconnection approvals.
Within the integrated utility tier, Duke Energy and NextEra Energy exemplify scale-driven rate-base expansion through regulated renewable additions and nuclear relicensing. Vistra occupies a distinctive position as a Texas-anchored retail and generation platform, balancing intermittent renewable output with dispatchable natural gas capacity across ERCOT's volatile pricing environment.
| Leading Market Players |
|---|
| Duke Energy |
| PG&E |
| NextEra Energy |
| Exelon |
| Sempra Energy |
| Constellation Energy |
| American Electric Power |
| Vistra |
| Southern Company |
| Others |
Value Network & Pricing Analysis
Data center load growth in Northern Virginia and Texas is forcing developers to front-load interconnection deposits and accelerate procurement timelines, compressing margins for EPC contractors and concentrating pricing power among transformer suppliers with captive manufacturing capacity.
Pricing Analysis
Long-term offtake contracting dominates developer revenue structures, with virtual power purchase agreements separating baseload firming premiums from energy-only price exposure. Price differentiation hinges on renewable energy certificate bundling and grid services co-location, with data center buyers absorbing premium tiers while municipal utilities negotiate standard-economy splits. Cost compression in battery storage EPC runs through lithium carbonate volatility and domestic content bonus capture. Industrial direct buyers exhibit lowest price sensitivity due to sustainability procurement mandates, while smaller commercial offtakers face margin pressure from interconnection upgrade cost allocation.
Supply Chain Analysis
High-voltage transformer supply rests on three North American manufacturers with order backlogs extending beyond twenty-four months. Lithium iron phosphate cathode materials draw from Chinese processing facilities, while polysilicon feeds from domestic IRA-compliant facilities are scaling against Southeast Asian incumbent supply. Single-source vulnerability concentrates in grid-scale inverter manufacturing, where semiconductor component shortages persist. Distribution runs through utility procurement departments and independent power producer direct channels, with EPC contractors anchoring project delivery coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market stems from production tax credit capture at scale and the shift toward premium-tier grid services contracting that rewards operational flexibility.
For Market Incumbents: Extend rate-base growth through regulated renewable additions in Carolinas and Florida territories, while securing nuclear relicensing extensions to anchor carbon-free capacity. Counter emerging merchant renewable developers by controlling interconnection queue positions through FERC Order 2023 readiness deposits. Vertical integration into battery storage EPC capabilities defends margin capture against independent engineering-procurement firms. For New Entrants and Emerging Players: Launch via behind-the-meter microgrid deployments in Texas commercial and industrial segments, where ERCOT price volatility creates willingness-to-pay for island-capable systems. Target data center sustainability procurement officers with direct virtual power purchase agreement structures that bypass incumbent utility green tariffs. Prioritize grid-forming inverter certification to capture ancillary services revenue pools previously reserved for natural gas peakers. For Investors and Strategic Acquirers: Asymmetric upside sits with independent power producers holding secured interconnection positions in PJM and ERCOT queue clusters. Long-term viability favors developers with offtake diversification across data center, corporate, and utility buyers rather than single-counterparty concentration. Monitor FERC Order 2023 cluster study completion rates as the inflection signal for project timeline compression and capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Securement | Locks revenue certainty for developers ahead of interconnection approvals in ERCOT queue positions. |
| Grid-Forming Inverter Certification | Enables battery storage assets to capture primary frequency response markets from natural gas peakers. |
| Backward Integration into Storage Manufacturing | Captures IRA domestic content bonuses while hedging lithium carbonate price volatility exposure. |
| Hydrogen Co-Firing Demonstration | Satisfies EPA greenhouse gas performance standards for existing natural gas turbines above 300MW. |
| Canadian Hydro Import Contracting | Secures baseload firming services for US Northeast renewable portfolios seeking capacity value. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national grid operator territory. Utility planning officers, independent power producer project developers, EPC contractors, and grid operators provided demand-side and supply-side perspectives through structured interviews. Secondary validation drew from EIA generation statistics, FERC interconnection queue filings, IEA power market reports, and project development database tracking. Bottom-up capacity addition modeling and top-down regulatory scenario analysis were triangulated against stakeholder input.
Segmentation granularity modeled fuel source, generation capacity tier, project scale, and regional grid type across the projection horizon. CAGRs were derived from capacity-weighted average deployment trajectories incorporating interconnection queue conversion rates and production tax credit phase-down schedules. Forecast inputs included data center load growth projections, renewable energy certificate market depth, and natural gas price curve assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under interconnection reform implementation delays or lithium supply disruption scenarios. Forecasts reflect documented assumptions regarding IRA credit permanence and state renewable portfolio standard convergence. A small set of named triggers—FERC Order 2023 cluster study completion rates, transformer manufacturing capacity expansion, and data center offtake contract renegotiation cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Power Shelf Market
Power
India Uninterruptible Power Supply (UPS) Market
Power
Spain Power Market
Power
Asia-Pacific Power Market
Power
Saudi Arabia Power Market
Power
Global Power Line Communication (PLC) Systems Market
Power
Distribution Feeder Protection System Market
Power
Direct Current Power System Market
Power
Iran Power Market
Power
Compact Substation Market
Power
Gabon Power Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Flue Gas Desulfurization Unit Market
Power
North America Microturbine Market
Power
Global Advanced Marine Power Supply Market
Power
Global Diesel Power Engine Market