
 Distributed Solar Power Generation System Market | 2026-2036
Distributed Solar Power Generation System Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Solar Power Generation System Market Analytics
Modular system bundling that combines photovoltaic panels, inverters, and batteries into single procurement packages is pivoting buyer choice toward integrated solutions rather than component-by-component sourcing. NextEra Energy Inc. leverages its utility-scale development expertise to anchor large distributed portfolios across regulated markets. JinkoSolar Holding Co. Ltd. dominates module supply chains with vertically integrated cell-to-module manufacturing. Tesla Inc. differentiates through proprietary battery-inverter software stacks that optimize residential and commercial dispatch.
A distributed solar power generation system comprises decentralized photovoltaic arrays typically rated from kilowatts to tens of megawatts, connected at distribution voltage levels rather than centralized transmission infrastructure, with power electronics managing bidirectional flow to the local grid. These systems serve commercial, industrial, and residential loads by offsetting retail electricity rates while providing ancillary services such as voltage support and peak shaving. Photovoltaic panels and inverters together capture the dominant share of hardware value, though batteries represent the fastest-expanding margin pool as storage attachment rates climb across utility and commercial applications. Residential and commercial applications now drive volume growth, while industrial and government segments concentrate in larger project sizes with longer development cycles.
FERC Order 2222 in the United States enables distributed energy resource aggregation in wholesale markets, while the EU Green Deal and national building performance standards across Germany, France, and Italy mandate solar-ready structures for new construction. India's Ministry of New and Renewable Energy enforces domestic content requirements through the Approved List of Models and Manufacturers, restricting module sourcing for government-linked projects. Stakeholders must monitor evolving interconnection standards and tariff structures as distribution system operators redesign rate frameworks to accommodate two-way power flows at scale.
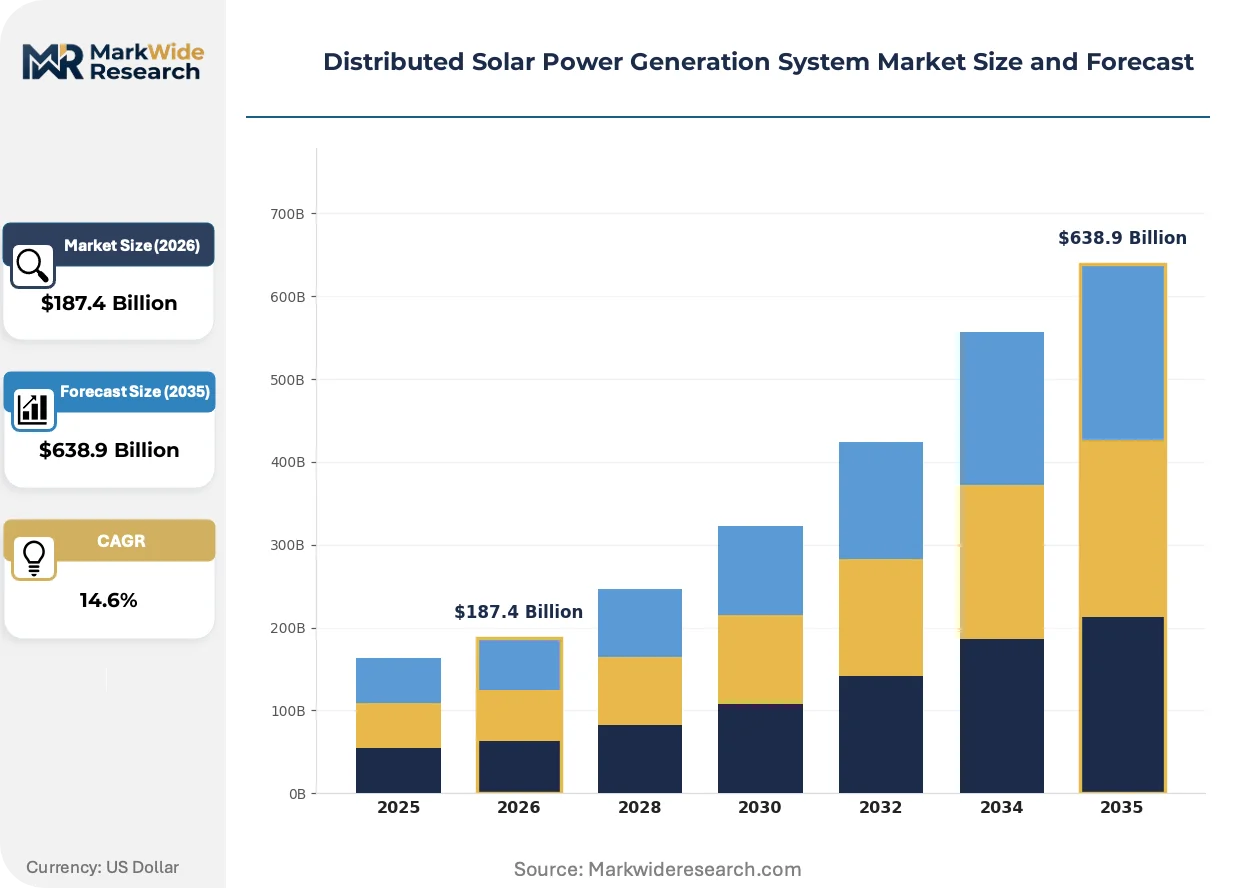
Market Dynamics
Modular bundling of photovoltaic panels, inverters, and batteries into single procurement packages is compressing component sourcing decisions and reshaping buyer-supplier relationships across residential and commercial segments.
Growth Catalysts
- FERC Order 2222:The United States regulation enables distributed energy resource aggregation in wholesale markets, unlocking new revenue streams for behind-the-meter solar-plus-storage systems.
- EU Green Deal building mandates:National performance standards across Germany, France, and Italy require solar-ready structures for new construction, embedding photovoltaic capacity into building codes.
- Grid parity acceleration:Utility-scale distributed arrays in India, China, and Germany now match or undercut retail electricity rates without subsidies, driving procurement volumes at the distribution voltage level.
Market Restraints
- Polysilicon supply concentration:Xinjiang-based producers control the majority of metallurgical-grade silicon refining, exposing module manufacturers to input cost volatility and forced labor compliance risks.
- Interconnection queue backlogs:Distribution system operators in California, Texas, and New York face 12-18 month delays for distributed solar interconnection studies, freezing project commissioning timelines.
- Net metering tariff redesign:State-level regulators in Hawaii, Nevada, and Arizona have shifted from full retail rate credits to time-of-use export valuations, degrading project economics for residential adopters.
Strategic Opportunities
- Commercial rooftop underpenetration:Warehouse and retail portfolios across the United States retain 60-70% untapped roof area suitable for megawatt-scale distributed installations with 15-20 year power purchase agreements.
- Battery-inverter software convergence:Virtual power plant platforms that aggregate residential storage dispatch are creating new ancillary service revenue pools in wholesale markets.
- India's ALMM domestic content requirements:The Approved List of Models and Manufacturers policy restricts module sourcing for government-linked projects, creating captive demand for local cell-to-module manufacturers.
Industry Challenges
- Electrical engineering talent scarcity:Distribution system operators and engineering-procurement-construction firms face acute shortages of power systems engineers capable of modeling bidirectional power flows at scale.
- Legacy meter infrastructure incompatibility:Utilities in older grid territories must replace electromechanical meters with smart bidirectional units before enabling net metering, requiring capital deployment that strains rate-base filings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Solar Power Generation System Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Inverters, Batteries, Racking Systems Application: Residential, Commercial, Industrial, Government Technology: Thin-Film, Monocrystalline, Polycrystalline, Bifacial End User: Utilities, Homeowners, Businesses, NGOs |
| Companies Covered | General Electric Co., NextEra Energy Inc., TotalEnergies SE, JinkoSolar Holding Co. Ltd., LONGi Solar Technology Co. Ltd., Huawei Technologies Co. Ltd., Siemens Energy AG, Canadian Solar Inc., Tesla Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Solar Power Generation System Market Evolving Landscape
Artificial intelligence-driven predictive maintenance and automated dispatch optimization are embedding intelligence into hardware stacks, shifting value capture from commodity components to software-layer monetization.
Machine learning algorithms trained on satellite imagery and irradiance data are automating site assessment and production forecasting for distributed solar developers. Residential installers and commercial engineering teams now deploy these tools to reduce customer acquisition costs and streamline permitting documentation. This capability compression is enabling smaller regional installers to compete with national vertically integrated developers on project origination speed.
REACH chemical restrictions and the EU F-Gas Regulation are phasing out sulfur hexafluoride in switchgear and hydrofluorocarbon-based heat transfer fluids in inverters, forcing hardware redesigns across European supply chains. Module and inverter manufacturers must recertify products with alternative insulating and cooling chemistries before placing them on the EU market. Commercial and industrial project developers in Germany and the Netherlands face extended procurement timelines as suppliers navigate this materials transition.
Corporate buyers with science-based emissions targets are displacing traditional utility procurement with direct virtual power purchase agreements for distributed solar portfolios. Retail chains and logistics operators now contract for aggregated behind-the-meter capacity across multiple facilities rather than site-by-site ownership. This aggregation model concentrates most visibly in the United States, where C&I offtakers leverage FERC Order 2222-compliant platforms to access wholesale market revenues.
Distributed Solar Power Generation System Market Segmentation
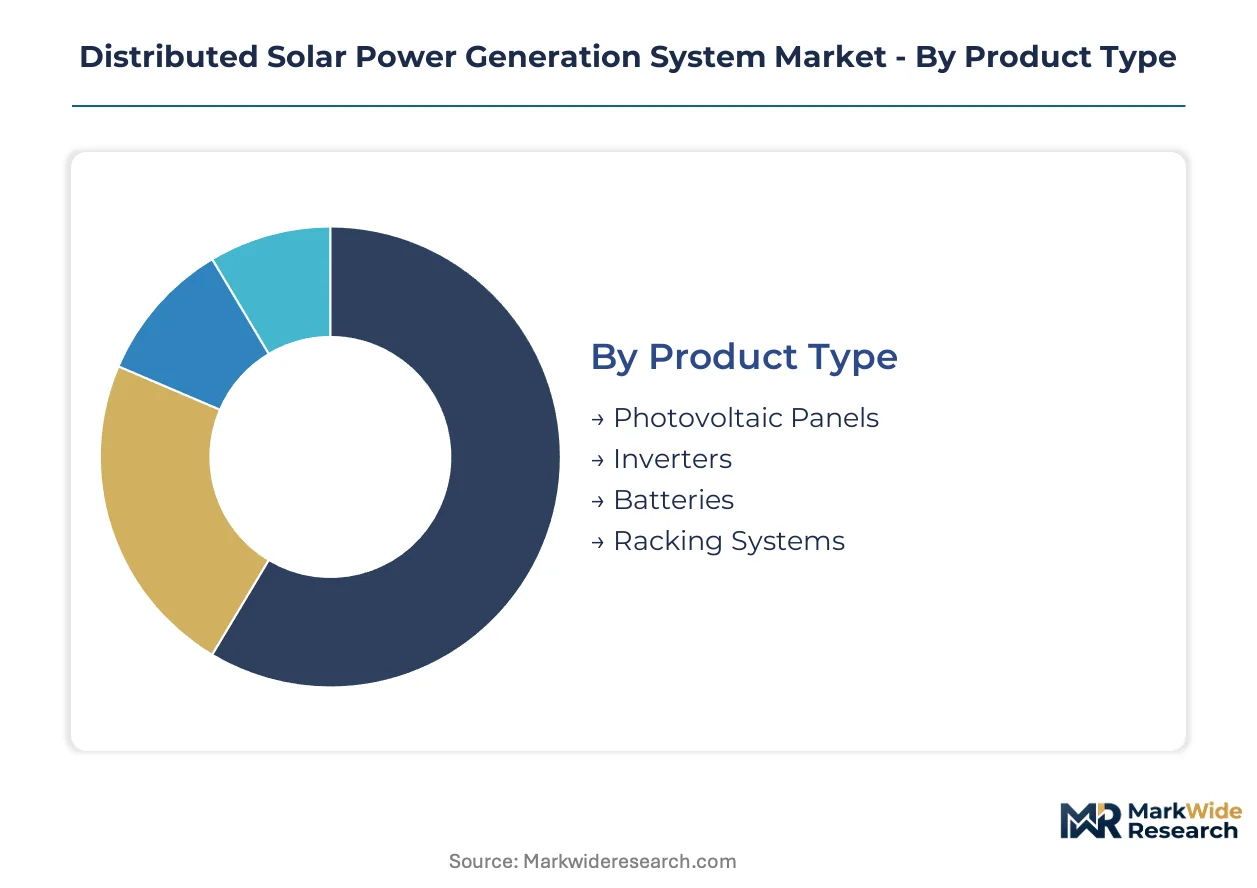
Segmentation in distributed solar power generation reveals how hardware specifications, installation scale, and customer economics intersect to determine procurement patterns. Technology choices cascade through system design, financing structures, and regulatory compliance requirements.
Product Type:
Component specifications define system performance boundaries and warranty economics across residential and commercial deployments.
- Photovoltaic Panels:Silicon-based cells convert sunlight to direct current electricity with efficiency ratings spanning monocrystalline, polycrystalline, and thin-film architectures. Module selection in India and Germany concentrates on ALMM-compliant domestic production and EU-manufactured bifacial units respectively, driven by trade policy and carbon footprint requirements.
- Inverters:Power electronics convert DC output to grid-synchronous alternating current, with string inverters dominating commercial rooftops and microinverters penetrating residential retrofits. String inverter procurement in California and Texas faces extended lead times due to semiconductor supply constraints and FERC interconnection study backlogs.
- Batteries:Lithium-ion storage systems enable time-shifted dispatch and backup power functionality. Homeowners in Hawaii and Arizona attach batteries at accelerating rates following net metering tariff redesigns that devalue simple export.
- Racking Systems:Structural mounting hardware secures panels to rooftops or ground arrays, with ballasted designs preferred for commercial membrane roofs.
Photovoltaic panels lead on scale; batteries lead on momentum.
Application:
Installation scale determines development complexity, financing instruments, and regulatory pathways.
- Residential:Behind-the-meter systems under 20 kilowatts serve single-family homes and small multi-family buildings. Installer networks in Germany and the Netherlands leverage satellite-based site assessment tools to compress customer acquisition timelines.
- Commercial:Rooftop and carport installations from 100 kilowatts to 5 megawatts offset retail electricity rates for retail chains, warehouses, and office portfolios. Warehouse operators across the United States contract for aggregated virtual power purchase agreements spanning multiple facilities.
- Industrial:Larger distributed arrays serve manufacturing campuses and data centers with 24/7 load profiles. Industrial offtakers in India negotiate long-term power purchase agreements with captive solar developers under state-level open access regulations.
- Government:Public sector procurement emphasizes domestic content compliance and prevailing wage requirements. Federal agencies in the United States source systems through the GSA schedule, while Indian public sector undertakings enforce ALMM module restrictions.
Commercial installations capture the largest absolute capacity additions; residential systems expand most quickly in attachment rate terms.
Technology:
Cell architecture and module design determine efficiency, temperature coefficient, and bifacial gain characteristics.
- Monocrystalline:Single-crystal silicon cells achieve the highest commercial efficiencies above 21 percent. Module supply to European and Indian markets concentrates on PERC and TOPCon cell architectures with improved temperature performance.
- Polycrystalline:Multi-crystal silicon cells trade efficiency for lower manufacturing energy intensity. Polycrystalline modules retain cost advantages in price-sensitive utility-scale procurement in India and Southeast Asia.
- Thin-Film:Cadmium telluride and copper indium gallium selenide technologies offer superior low-light performance and temperature coefficients. First Solar's cadmium telluride modules dominate utility-scale deployments in the southwestern United States.
- Bifacial:Double-sided cells capture reflected light from ground surfaces, yielding 5-20 percent energy gains. Bifacial penetration accelerates in China and the Middle East where high-albedo desert conditions maximize rear-side gain.
Monocrystalline technology leads on shipment volume; bifacial designs climb the fastest in new capacity additions.
End User:
Customer type shapes contract structures, risk allocation, and operational priorities.
- Utilities:Distribution utilities procure distributed solar for grid investment deferral and renewable portfolio compliance. Arizona Public Service and Southern California Edison aggregate behind-the-meter resources as non-wires alternatives to substation upgrades.
- Homeowners:Residential adopters prioritize bill reduction and backup power resilience. Homeowner financing in the United States has shifted from leases toward loans and cash purchases as interest rate environments change.
- Businesses:Commercial and industrial offtakers pursue emissions reductions and energy cost predictability. Logistics operators and retail chains across Germany, France, and Italy embed solar-ready requirements into new construction specifications under EU Green Deal building mandates.
- NGOs:Non-governmental organizations deploy solar for rural electrification and disaster resilience applications. International development finance supports distributed solar deployment in sub-Saharan Africa and island nations.
Businesses lead on aggregate procurement scale; utilities gain momentum through FERC Order 2222 aggregation mechanisms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The distributed solar power generation industry traces its commercial roots to Germany's feed-in tariff programs of the early 2000s, which established the first scalable subsidy framework for rooftop photovoltaic deployment. This policy architecture subsequently migrated to California and China, creating the three foundational markets that continue to shape technology trajectories and procurement standards.
United States
Commercial warehouse portfolios and data center campuses drive distributed capacity additions across Texas and Arizona. FERC Order 2222 enables aggregation of behind-the-meter resources into wholesale markets, unlocking new revenue streams for solar-plus-storage configurations. Southern California Edison and Arizona Public Service operate the most advanced distributed resource management systems among investor-owned utilities.
Germany
EU Green Deal building performance standards mandate solar-ready structures for new commercial and residential construction nationwide. The country's national building energy regulator enforces stringent grid code compliance for bidirectional power flows at the distribution level. Bavaria and Baden-Württemberg concentrate industrial rooftop installations serving automotive and precision manufacturing supply chains.
China
Provincial governments in Shandong and Hebei accelerate distributed deployment through county-level whole-roof programs targeting rural and industrial buildings. The Ministry of Ecology and Environment enforces dual carbon goals that cascade into municipal renewable procurement mandates. Yangtze River Delta manufacturing clusters supply inverters and power electronics to domestic and export markets.
India
State-level open access regulations in Maharashtra and Gujarat enable industrial consumers to procure captive solar through long-term power purchase agreements. The Ministry of New and Renewable Energy enforces ALMM domestic content requirements that restrict module sourcing for government-linked projects. Tamil Nadu and Karnataka host the largest concentrations of grid-connected commercial rooftop capacity.
Australia
High retail electricity rates and abundant solar resource quality drive residential penetration rates exceeding 30 percent in Queensland and South Australia. The national Clean Energy Regulator administers small-scale technology certificates that subsidize upfront system costs. New South Wales and Victoria lead commercial deployment through corporate renewable energy procurement frameworks.
Distributed Solar Power Generation System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software-integrated versus hardware-only offerings, with battery-inverter convergence commanding pricing power against standalone module supply. The vendor base spans vertically integrated cell-to-module manufacturers, utility-scale developers with distributed portfolios, and technology conglomerates with proprietary energy management platforms. Three archetypes dominate: integrated hardware-software stacks, pure-play module suppliers with captive upstream polysilicon, and regulated utility affiliates leveraging rate-base expansion. Capacity expansion into battery assembly and strategic partnerships for virtual power plant aggregation represent the dominant competitive vectors.
Within the integrated technology tier, Tesla Inc. and Huawei Technologies Co. Ltd. exemplify the battery-inverter software convergence archetype, while NextEra Energy Inc. occupies a position representing utility-affiliated distributed development. JinkoSolar Holding Co. Ltd. anchors the vertically integrated module manufacturing segment with backward integration into cell production. These three company groupings illustrate how competitive positioning stratifies across hardware commoditization, software differentiation, and regulated market access.
| Leading Market Players |
|---|
| General Electric Co. |
| NextEra Energy Inc. |
| TotalEnergies SE |
| JinkoSolar Holding Co. Ltd. |
| LONGi Solar Technology Co. Ltd. |
| Huawei Technologies Co. Ltd. |
| Siemens Energy AG |
| Canadian Solar Inc. |
| Tesla Inc. |
| Others |
Value Network & Pricing Analysis
Captive polysilicon refining in Xinjiang anchors module manufacturers' supply position while simultaneously exposing them to forced labor compliance audits that reshape pricing power across European and North American procurement. This upstream concentration forces buyers to either absorb compliance premiums or pivot sourcing to higher-cost Southeast Asian cell facilities, compressing margins at every tier.
Pricing Analysis
Project-based long-term offtake contracting dominates procurement across utility and commercial segments, with price differentiation resting on module efficiency tier and domestic content certification status. Cost compression in standard-grade monocrystalline modules is intensifying because Chinese cell manufacturers have expanded PERC and TOPCon capacity faster than demand absorption. Residential adopters in Hawaii and Arizona exhibit highest price sensitivity following net metering tariff redesigns, while data center operators in Texas prioritize dispatch reliability over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Xinjiang-based metallurgical-grade silicon refiners who feed the majority of global polysilicon production. Module assembly draws from China, Vietnam, and Malaysia, with lithium-ion battery cell production anchored in China, South Korea, and Japan. Tariff exposure on Chinese-origin cells and modules under Section 201 and antidumping orders forces developers to maintain dual-qualified supplier bases. Distribution runs through engineering-procurement-construction firms who bundle hardware procurement with installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FERC Order 2222 aggregation mechanisms continuously unlock new revenue streams for distributed solar-plus-storage configurations.
For Market Incumbents: Lock in module supply through multi-year tolling agreements with Southeast Asian cell manufacturers before ALMM compliance requirements tighten further. Secure utility interconnection queue positions in California and Texas where 12-18 month study delays freeze competitor project timelines. Defend margin position by deepening software-layer monetization through virtual power plant aggregation platforms rather than competing on hardware cost alone. For New Entrants and Emerging Players: EU Green Deal building mandates in Germany, France, and Italy open a window for solar-ready construction specification consulting and integrated rooftop development. Target commercial warehouse portfolios across the United States where 60-70% untapped roof area supports megawatt-scale installations with 15-20 year power purchase agreements. Penetrate through virtual power purchase agreement aggregation platforms that displace site-by-site ownership for retail chains and logistics operators. For Investors and Strategic Acquirers: Roll-up economics work for regional engineering-procurement-construction firms because customer acquisition cost compression through satellite-based site assessment tools enables smaller installers to compete with national developers on origination speed. Focus on mid-scale commercial rooftop specialists with established utility interconnection relationships and prevailing wage compliance capabilities. Watch battery attachment rate inflection in Hawaii and Arizona as the signal for storage margin pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Power Plant Aggregation | FERC Order 2222-compliant platforms unlock wholesale market revenues for behind-the-meter solar-plus-storage systems. |
| Domestic Content Compliance Investment | ALMM certification and EU manufacturing carbon footprint requirements secure eligibility for government-linked procurement. |
| Battery-Inverter Software Convergence | Proprietary dispatch optimization stacks capture premium margins against commodity hardware suppliers. |
| Commercial Rooftop Portfolio Aggregation | Warehouse and retail chain contracts concentrate development scale across multiple facilities under single offtake structures. |
| Interconnection Queue Positioning | Early study deposits in California, Texas, and New York lock in grid access before 12-18 month backlogs extend further. |
Research Methodology
Multiple input streams — utility interconnection queue filings, module import customs records, and state-level net metering tariff dockets — were reconciled against primary interviews with distributed solar developers, utility resource planners, and engineering-procurement-construction procurement leads. Secondary validation drew from FERC orders, EIA generation databases, IEA renewable market reports, and state public utility commission filings. Bottom-up project-level capacity additions were triangulated against top-down manufacturer shipment data.
Data-stream reconciliation across the analysis window applied capacity-weighted growth assumptions to derive segment-level CAGRs, with modeling dimensions spanning installation scale, end-use sector, technology architecture, and regulatory framework cluster. Forecast inputs incorporated module efficiency improvement curves, battery cost decline trajectories, and interconnection study delay distributions by ISO region.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated net metering tariff redesign or polysilicon supply disruption scenarios. Projections reflect documented assumptions about policy continuity, supply chain reshoring timelines, and distribution grid upgrade investment rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
Global Solar Module for Electric Vehicle Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
North America Solar Photovoltaic (PV) Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Canada Solar Energy Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Greece Solar Energy Market