
 Statcom Market | 2026-2036
Statcom Market Size, Share, and Industry Trends Forecast 2026-2036
Statcom Market Analysis
China is fragmenting STATCOM manufacturing capacity across state-backed and private production clusters. ABB leverages its power-electronics heritage to dominate high-voltage installations in European transmission networks. Siemens Energy sustains technology leadership through integrated converter-inverter platforms for offshore wind interconnection. Mitsubishi Electric anchors Asian utility procurement with silicon-carbide switching architectures that reduce converter losses.
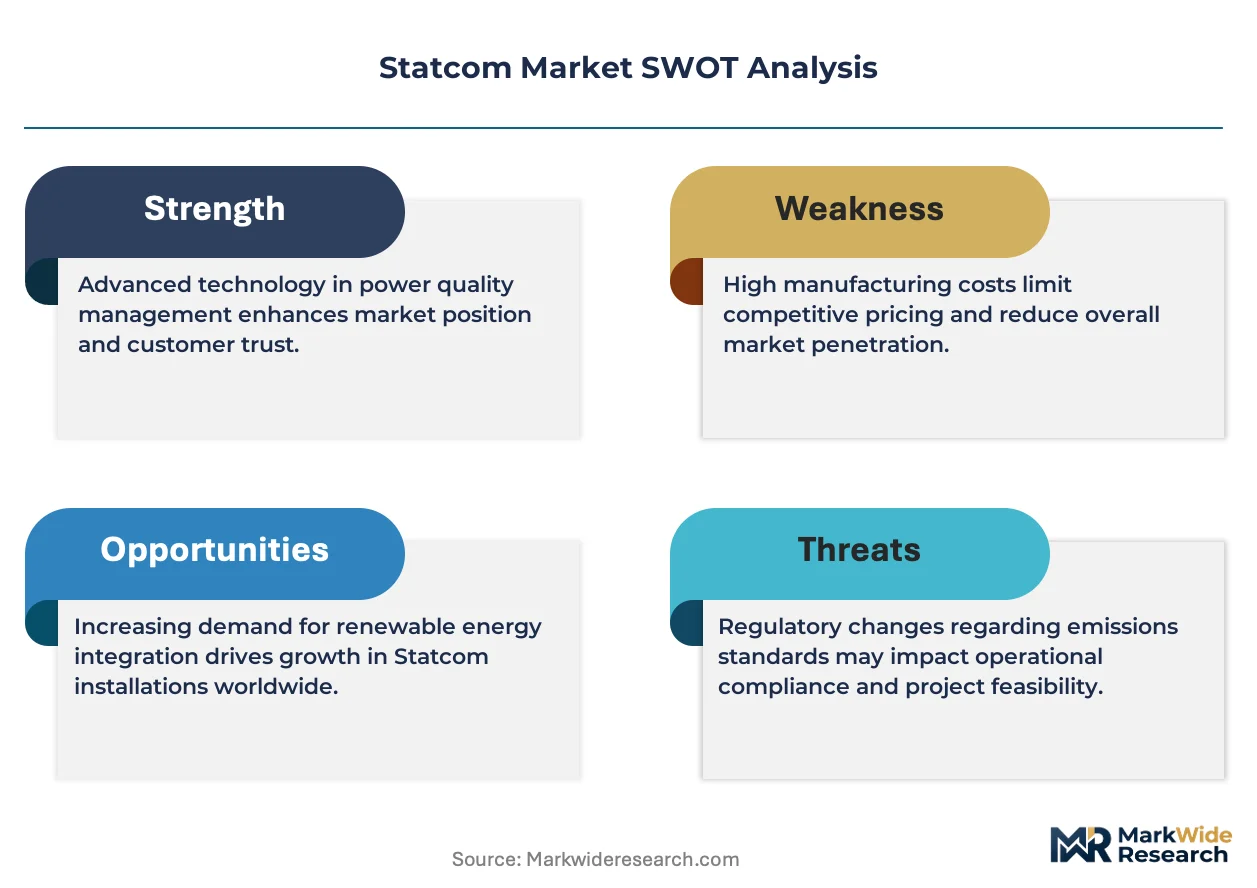
A STATCOM (Static Synchronous Compensator) is a power-electronic shunt device employing voltage-source converters with insulated-gate bipolar transistors or silicon-carbide modules to inject or absorb reactive current, thereby regulating grid voltage within ±5% of nominal. Its primary commercial purpose is dynamic reactive power compensation for stabilizing grids with high renewable-energy penetration. Modular STATCOM systems command premium pricing due to scalable megawatt-class building blocks that slash commissioning time. Conventional STATCOM retains share in legacy utility retrofits where footprint constraints are relaxed. Grid stabilization applications concentrate margin pools as TSOs impose stricter fault-ride-through requirements.
CEA in India mandates dynamic reactive support for renewable-rich zones, compelling DISCOMs to procure STATCOM assets. EMA and EU Green Deal frameworks in Europe accelerate converter-based grid support under F-Gas reduction timelines. IEEE 1547 and IEC 61400-21 shape product certification for interconnection compliance. Stakeholders must monitor silicon-carbide supply constraints and evolving grid-code stringency to time capacity investments.
Market Dynamics
Modular voltage-source converter architectures are compressing commissioning cycles and forcing legacy thyristor-based SVC systems into early retirement across transmission networks with high renewable penetration.
Growth Catalysts
- CEA Grid-Code Mandates:India's Central Electricity Authority requires dynamic reactive compensation in renewable-rich zones, compelling state DISCOMs to tender STATCOM capacity.
- Silicon-Carbide Module Adoption:Wide-bandgap semiconductors slash converter switching losses, enabling compact installations where footprint constraints previously blocked deployment.
- Offshore Wind Interconnection:German and South Korean TSOs procure STATCOM clusters to stabilize HVDC links feeding islanded generation into onshore grids.
Market Restraints
- Silicon-Carbide Supply Concentration:Wafer fabrication capacity concentrates among a limited set of substrate producers, creating input bottlenecks for converter manufacturers.
- Capital Intensity of Grid-Scale Systems:Utility-grade STATCOM installations require substantial upfront expenditure, stretching DISCOM balance sheets in price-regulated markets.
- Technical Talent Scarcity:Power-electronics engineering expertise for voltage-source converter commissioning remains concentrated in legacy industrial clusters.
Strategic Opportunities
- EU Green Deal Alignment:The F-Gas Regulation timeline accelerates converter-based reactive compensation as utilities retire SF6-dependent switchgear.
- Distribution Grid Modernization:India's rural electrification programs create demand for compact STATCOM units at 33kV substations serving agricultural loads.
- Hybrid Synchronous Condenser Integration:Convergence of rotating inertia machines with power-electronic converters offers new product categories for grid-forming applications.
Industry Challenges
- IEC 61400-21 Certification Complexity:Type-testing timelines for wind-interconnection compliance extend product validation cycles, delaying revenue recognition.
- Legacy SCADA Integration Friction:STATCOM controllers must interface with decades-old utility communication protocols, requiring custom middleware development.
- Commissioning Skill Shortages:Field commissioning of modular systems demands specialized expertise in harmonic filtering and protection coordination that utilities struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Statcom Market |
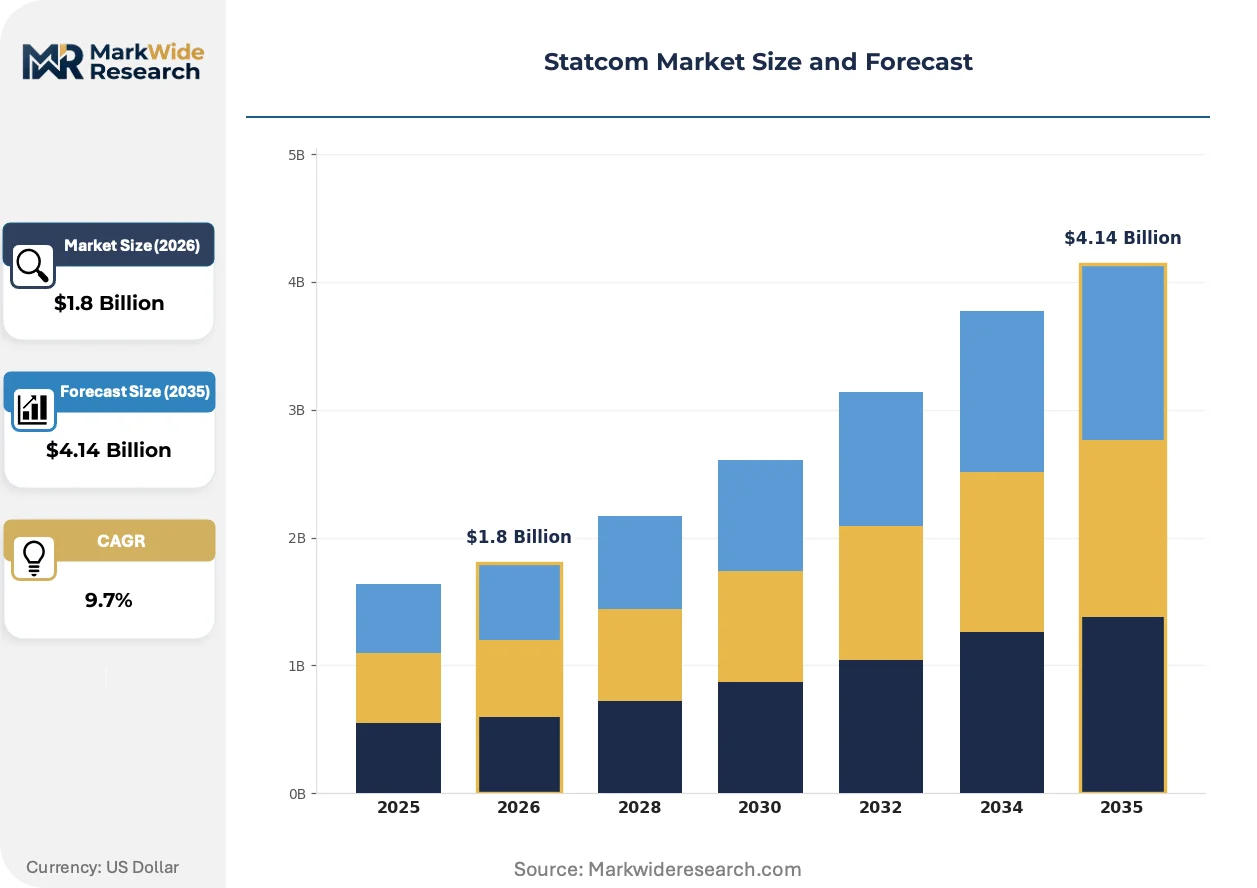
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional STATCOM, Modular STATCOM, Hybrid STATCOM, Advanced STATCOM End User: Utilities, Industrial Plants, Renewable Energy, Power Distribution Companies Application: Voltage Regulation, Reactive Power Compensation, Load Balancing, Grid Stabilization Deployment: Onshore, Offshore, Urban, Rural |
| Companies Covered | ABB, Ingeteam, Siemens Energy, JEMA Energy, American Superconductor Corporation, Hitachi Energy Ltd., Mitsubishi Electric Corporation, Hyosung Heavy Industries, GE Vernova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Statcom Market Emerging Trajectories
Power-semiconductor material transitions and grid-code stringency are compressing product lifecycles and redefining competitive advantage around converter efficiency metrics rather than installed base scale.
Silicon-carbide metal-oxide-semiconductor field-effect transistors in 3.3kV and 6.5kV ratings are rendering obsolete insulated-gate bipolar transistor stacks in medium-voltage STATCOM inverters. European TSOs specify SiC-based converters for new interconnection projects. The technology is rendering obsolete thermal management systems sized for IGBT switching losses, compressing ancillary component markets.
The EU F-Gas Regulation mandates phased reduction of sulfur hexafluoride emissions from electrical equipment, accelerating converter-based alternatives to gas-insulated switchgear. Utilities in Germany and France now prioritize STATCOM procurement that eliminates SF6 dependency entirely. Grid operators in Scandinavia are responding with tender specifications that exclude conventional SVC systems.
Utility procurement committees now unbundle hardware supply from long-term service agreements, compressing vendor margins on aftermarket revenue. German transmission system operators lead this shift, separating converter stack purchases from 15-year maintenance contracts. The pattern is spreading to South Korean KEPCO tenders, where asset ownership models favor capital-light vendor structures.
Statcom Market Segmentation
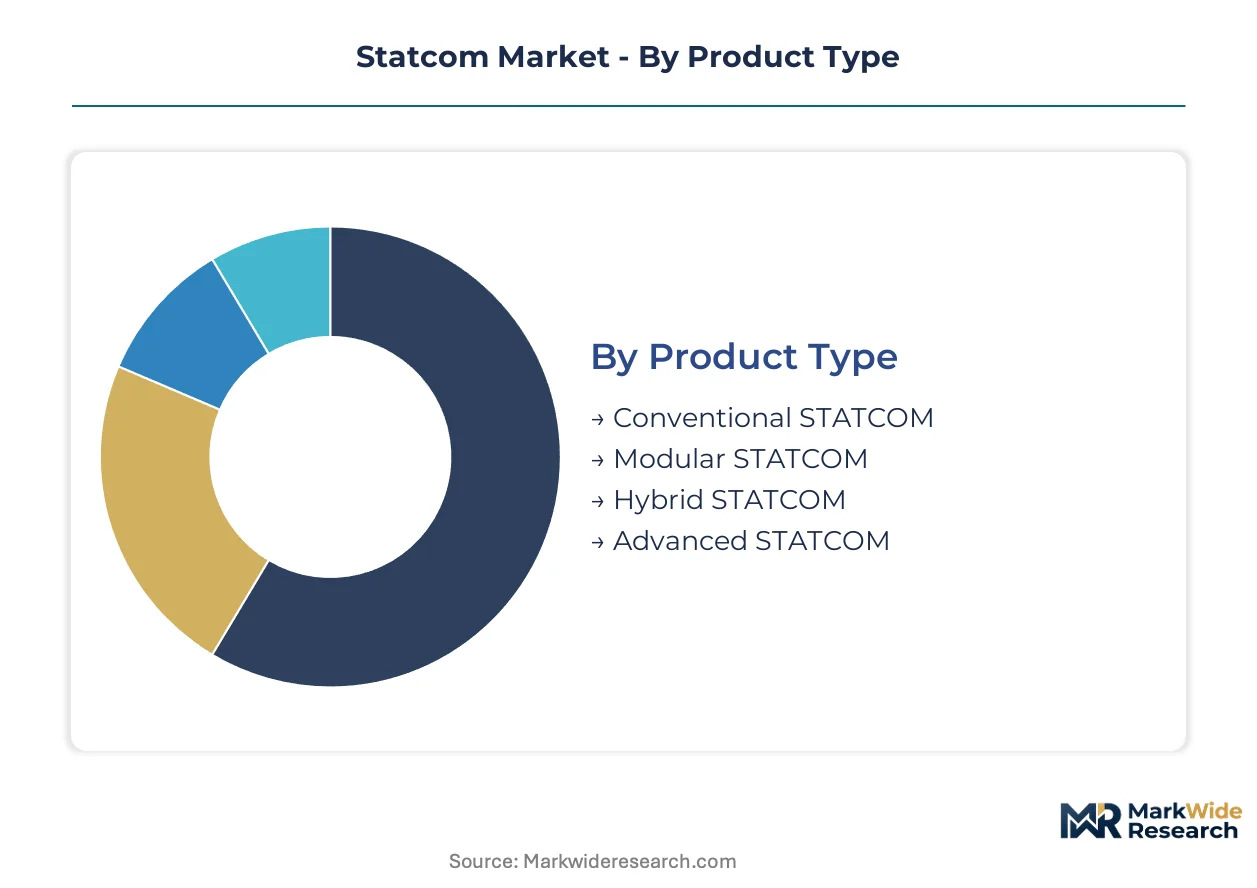
Segmentation in the STATCOM market reveals how converter architectures, end-user procurement patterns, and deployment constraints fragment vendor addressable markets. Each dimension carries distinct margin profiles and after-sales service intensity that shape competitive positioning.
Product Type:
After-sales service intensity varies sharply across converter architectures, with modular systems demanding predictive maintenance contracts and conventional units requiring periodic thyristor stack replacement.
- Modular STATCOM:Scalable voltage-source converter blocks enable rapid capacity expansion without full system replacement. German and South Korean TSOs specify these for offshore wind interconnection projects where commissioning speed determines project economics. Service contracts typically span 15 years with remote diagnostics integration.
- Conventional STATCOM:Centralized thyristor-based designs dominate legacy utility retrofits where footprint constraints are relaxed. Indian DISCOMs under CEA mandates procure these for established transmission corridors with existing maintenance infrastructure. Replacement parts availability extends operational life cycles.
- Hybrid STATCOM:Combines power-electronic converters with synchronous condenser inertia for grid-forming capability.
- Advanced STATCOM:Silicon-carbide switching architectures reduce converter losses for premium installations.
By volume, Conventional STATCOM leads. By growth pace, Modular STATCOM is expanding most quickly.
End User:
Procurement sophistication divides end users, with utilities bundling long-term service agreements and industrial plants prioritizing capital expenditure minimization.
- Utilities:Transmission system operators in Germany and South Korea tender STATCOM clusters as part of HVDC stabilization programs. CEA grid-code compliance drives Indian state DISCOM procurement with strict fault-ride-through specifications. These buyers unbundle hardware from service contracts, compressing vendor aftermarket margins.
- Renewable Energy:Wind and solar developers face IEEE 1547 and IEC 61400-21 certification requirements for grid interconnection. Offshore wind projects in the North Sea and Korean waters command premium converter specifications. Procurement concentrates among developers with balance-sheet capacity for merchant power exposure.
- Industrial Plants:Steel and cement facilities deploy STATCOM units for power quality management.
- Power Distribution Companies:Rural electrification programs in India create demand for compact 33kV installations.
By installed base, Utilities dominate. By expansion trajectory, Renewable Energy is climbing fastest.
Application:
Application-specific performance requirements determine converter sizing and control algorithm complexity, with grid stabilization commanding the highest technical specifications.
- Grid Stabilization:Dynamic voltage support during fault events requires sub-cycle response times. European TSOs impose strict fault-ride-through requirements that only silicon-carbide-based converters satisfy. Procurement concentrates where renewable penetration exceeds 40% of generation mix.
- Voltage Regulation:Continuous reactive power injection maintains grid voltage within ±5% of nominal. Urban distribution networks in Germany and France prioritize SF6-free STATCOM alternatives under EU F-Gas Regulation timelines. Control systems must interface with legacy SCADA protocols.
- Reactive Power Compensation:Bulk compensation for transmission corridors with high inductive loading.
- Load Balancing:Agricultural load centers in rural India require asymmetric phase compensation.
By revenue concentration, Grid Stabilization leads. By specification stringency, Grid Stabilization is also advancing fastest.
Deployment:
Environmental and logistical constraints fragment deployment economics, with offshore installations commanding 3-4x the capital intensity of rural equivalents.
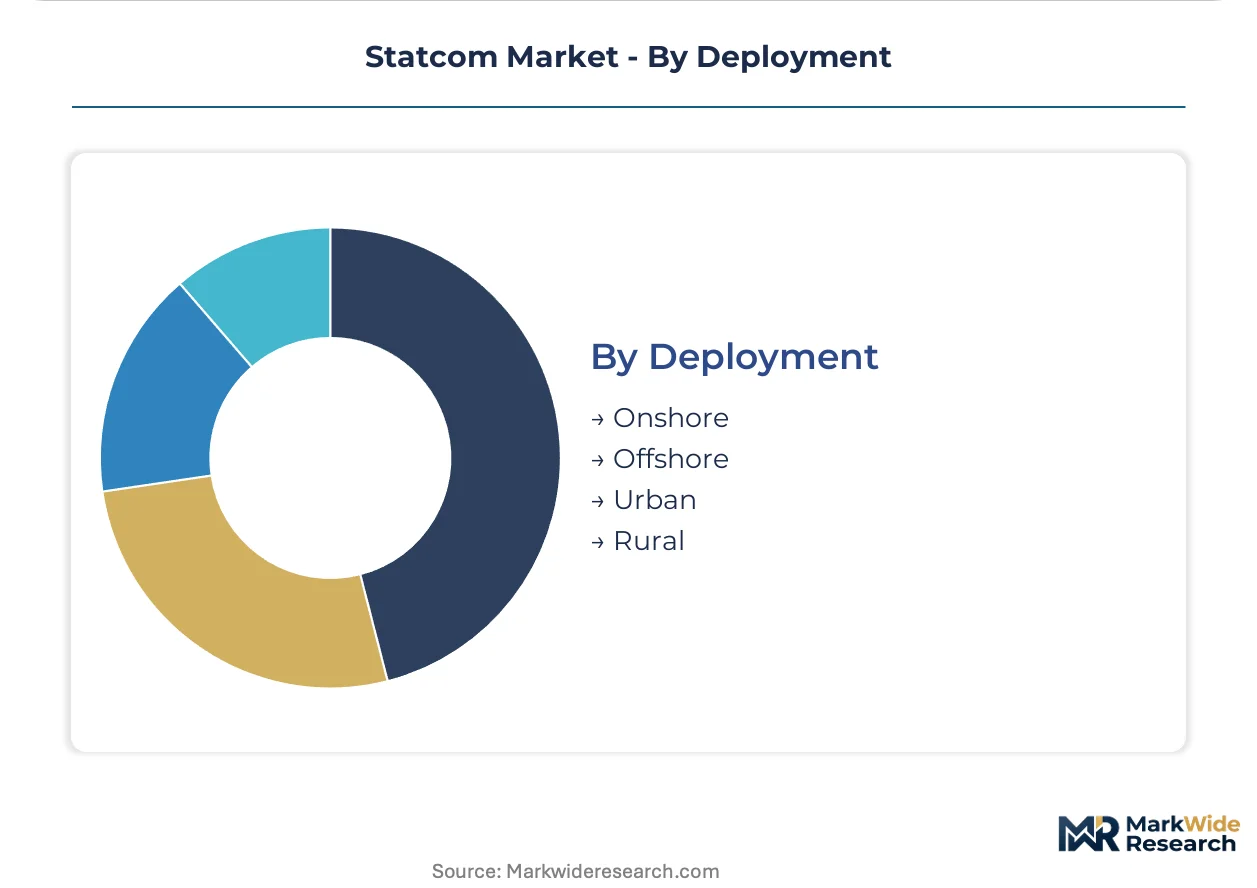
- Offshore:Platform-mounted STATCOM systems stabilize HVDC links from islanded wind generation. North Sea and Korean waters drive demand for salt-corrosion-resistant converter enclosures. Installation requires specialized marine vessels that constrain project scheduling.
- Urban:Footprint-constrained substations in dense European cities favor compact silicon-carbide designs. Noise ordinances and electromagnetic compatibility requirements add certification complexity. Real estate costs dominate total project economics.
- Onshore:Conventional transmission corridor installations with standard environmental protection.
- Rural:India's agricultural electrification programs deploy simplified controls for 33kV substations.
By project count, Onshore leads. By margin per megawatt, Offshore is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer fabrication capacity for silicon-carbide substrates concentrates among a limited set of producers in Japan, Germany, and the United States, creating input bottlenecks that ripple through converter manufacturing clusters worldwide.
Germany
Transmission system operators tender STATCOM clusters for offshore wind interconnection under the EU F-Gas Regulation timeline. The country's national energy regulator mandates SF6-free alternatives in new substation equipment. Converter assembly concentrates in Bavaria and North Rhine-Westphalia where industrial electrification drives demand.
India
State DISCOMs accelerate procurement to comply with CEA grid-code mandates for renewable-rich zones. The Central Electricity Authority requires dynamic reactive compensation in solar and wind corridors. Manufacturing activity clusters in Gujarat and Maharashtra where domestic production scales to serve rural electrification programs.
South Korea
KEPCO tenders favor modular architectures for HVDC link stabilization feeding islanded generation. The country's national grid operator imposes strict fault-ride-through specifications for interconnection compliance. Heavy industry conglomerates anchor converter production in the Seoul Capital Area and Busan-Ulsan corridor.
China
State-backed and private production clusters fragment manufacturing capacity across provincial industrial zones. The Ministry of Industry and Information Technology prioritizes wide-bandgap semiconductor development under dual carbon goals. Yangtze River Delta and Pearl River Delta regions host the densest concentration of voltage-source converter assembly.
United States
FERC interconnection standards and state-level renewable portfolio standards drive utility procurement for grid stabilization. The Federal Energy Regulatory Commission shapes certification requirements for converter-based reactive compensation. Texas and California transmission operators lead deployment in high-renewable penetration zones.
Statcom Market Vendor Landscape
Integrated industrial conglomerates and specialized power-electronics firms split the market along technology-heritage lines. The vendor base concentrates around three strategic archetypes: diversified heavy-industry groups with captive converter platforms, pure-play power-semiconductor specialists, and energy-technology spinoffs from legacy engineering conglomerates. Dominant competitive moves include strategic partnerships for silicon-carbide supply security and geographic expansion into CEA-mandated procurement markets.
Among European-based integrated suppliers, ABB and Siemens Energy exemplify the diversified conglomerate archetype with transmission-network heritage. Mitsubishi Electric Corporation anchors the Asian specialist tier with semiconductor-forward positioning. These three occupy positions that reflect distinct competitive origins: Swiss-Swedish engineering integration, German energy-technology spinoff structure, and Japanese electronics-to-power-systems vertical scope.
| Leading Market Players |
|---|
| ABB |
| Ingeteam |
| Siemens Energy |
| JEMA Energy |
| American Superconductor Corporation |
| Hitachi Energy Ltd. |
| Mitsubishi Electric Corporation |
| Hyosung Heavy Industries |
| GE Vernova |
| Others |
Supply Flow & Price Mechanics
Wafer undercapacity in Japan and Germany is compressing silicon-carbide substrate availability, forcing converter manufacturers to accept price premiums or redesign around inferior silicon-based alternatives while buyers face extended lead times for premium STATCOM installations.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure by mandating SF6-free converter specifications that stratify procurement across premium SiC-based systems, standard IGBT architectures, and economy-tier thyristor retrofits. Price differentiation hinges on certification grade under IEC 61400-21 and after-sales service bundling duration. Cost compression in the standard tier is intensifying because Indian DISCOMs unbundle hardware from maintenance contracts. Industrial plants exhibit highest price sensitivity; European TSOs show least.
Supply Chain Analysis
Silicon-carbide wafer fabrication draws from concentrated substrate production in Japan, Germany, and the United States, with epitaxial layer processing clustering in South Korea and Taiwan. Raw material dependencies span high-purity silicon feedstock, graphite crucibles, and specialized chemical gases for crystal growth. Single-source vulnerability concentrates around 6-inch SiC wafer supply. Distribution runs through direct OEM relationships with utility EPC contractors and specialized power-electronics system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
STATCOM market positioning rests on regulatory entrenchment: CEA grid-code mandates and EU F-Gas timelines create switching costs that cement incumbent relationships with certified converter suppliers.
For Market Incumbents: Pre-empt emerging Chinese voltage-source converter specialists by securing captive silicon-carbide wafer supply through backward integration into Japanese or German substrate producers. Accelerate IEC 61400-21 certification investments to raise compliance barriers against unproven entrants targeting European offshore wind interconnection tenders.
For New Entrants and Emerging Players: Rural India's 33kV agricultural substations present the most penetrable deployment corridor, where simplified control algorithms and local assembly partnerships overcome incumbent service-network advantages. Target compact modular units priced below German TSO specifications, leveraging domestic component sourcing in Gujarat manufacturing clusters.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hybrid STATCOM-synchronous condenser convergence products as shared platform architectures spread R&D costs. Long-term viability favors vendors with semiconductor-forward positioning and utility service-contract backlogs. Monitor silicon-carbide substrate spot pricing as the critical inflection signal for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbide Supply Security Partnership | Locked substrate access insulates converter margins against Japanese wafer fabrication bottlenecks. |
| CEA Grid-Code Certification Fast-Track | Accelerated CEA compliance captures Indian DISCOM procurement waves ahead of competitors. |
| Modular Platform Standardization | Scalable building blocks slash commissioning time for German offshore wind interconnection deadlines. |
| SF6-Free Product Line Conversion | EU F-Gas alignment unlocks French and Scandinavian TSO tender eligibility. |
| Distribution Grid Compact Unit Launch | 33kV rural electrification positioning captures Indian agricultural load-center modernization budgets. |
Methodological Framework
Cross-validation between primary interviews with utility planning officers, EPC contractors, and power-electronics procurement leads and secondary sources including FERC interconnection filings, CEA grid-code notifications, and IEA renewable integration reports anchors the qualitative findings. Bottom-up project pipeline tracking triangulates against top-down regulatory mandate analysis to bound capacity expansion estimates.
Calibration against historical STATCOM deployment trajectories in Germany and South Korea informs the analytical framework across the projection horizon. Segmentation models incorporate converter architecture type, end-user procurement sophistication, application performance tier, and deployment environment constraints. CAGRs derive from installed base replacement cycles and renewable penetration elasticity estimates, with silicon-carbide module adoption curves and grid-code stringency indices as core inputs.
Macroeconomic conditions sit as an overlay; deviation in Indian DISCOM capital expenditure budgets and European offshore wind auction volumes would shift the trajectory. Forecasts reflect documented assumptions around substrate supply expansion and certification timeline stability. Cross-checking against IEA grid investment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
North America Power Market
Power
Digital Power Utility Market
Power
Iran Power Market
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
Asia-Pacific Power Market
Power
Asia-Pacific Power Purchase Agreement Market
Power
Nigeria Power Market
Power
Gas Freeing Fan Market
Power
Canada Power Market
Power
Recloser Control Market
Power
Equatorial Guinea Power Market
Power
Marine Thermal Fluid Heaters Market
Power
Global UPS Market
Power
Italy Power EPC Market
Power
Global Marine Power Systems Market
Power
Mexico Power Market