
 Asia-Pacific Power Market | 2026-2036
Asia-Pacific Power Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Power Market Outlook
Data center operators are reorganizing procurement priorities across the Asia-Pacific power landscape, overtaking steel and cement producers as the fastest-growing buyer archetype for firm renewable capacity. NTPC Limited anchors India's thermal-to-renewable transition with gigawatt-scale solar parks and green hydrogen pilots. Sungrow Power Supply dominates inverter and energy storage system supply across Southeast Asian utility tenders. Brookfield Renewable Partners controls a growing portfolio of operational wind and solar assets in Australia and India, positioning for long-term offtake contracts with corporate buyers seeking 24/7 clean power.
Asia-Pacific power encompasses the production, delivery, and management of electrical energy across generation plants, high-voltage transmission networks, and low-voltage distribution grids serving economies from Mongolia to New Zealand, with system voltages ranging from 220V residential single-phase to 800kV ultra-high-voltage direct current transmission corridors. Its primary purpose is to convert primary energy sources into usable electricity while maintaining grid frequency within 49.5-50.5 Hz across interconnected synchronous zones. Generation services command the largest capital allocation pools, particularly utility-scale solar and offshore wind installations receiving priority dispatch in Vietnam, Australia, and South Korea. Renewable energy technology leads capacity additions, though natural gas generation sustains baseload reliability in markets with intermittent renewable profiles such as the Philippines and Bangladesh. Grid management applications attract software and automation investment as distributed solar penetration rises across Thailand's provincial utilities and Australia's National Electricity Market.
India's Central Electricity Authority mandates renewable purchase obligations and interstate green energy corridors, while Australia's Energy Security Board reshapes market rules around capacity adequacy and distributed resource participation. Thailand's Energy Regulatory Commission governs tariff structures for independent power producers supplying industrial estates in the Eastern Economic Corridor. Stakeholders must monitor how Vietnam's evolving direct power purchase agreement framework allows private offtakers to contract directly with generators, bypassing the single-buyer model that has dominated the region's largest Southeast Asian economy.
Market Dynamics
Data center load growth is forcing grid planners across Southeast Asia to reconceptualize transmission reinforcement schedules, compressing decade-long infrastructure timelines into three-to-five-year procurement windows that favor integrated generation-retail providers over traditional utility structures.
Growth Catalysts
- Direct Power Purchase Agreements:Vietnam's evolving DPPA framework permits private offtakers to contract directly with renewable generators, bypassing the state utility's single-buyer monopoly and unlocking corporate procurement at scale.
- India's PLI Scheme:Production-linked incentives for solar module manufacturing and grid-scale battery storage redirect domestic and foreign capital toward captive clean energy supply chains, reducing import dependency.
- Offshore Wind Auctions:Australia's competitive tender rounds for floating and fixed-bottom offshore capacity attract international developers to Bass Strait and Newcastle waters, diversifying generation geography beyond coal-dependent baseload regions.
Market Restraints
- Transmission Bottlenecks:Vietnam's 220kV and 500kV backbone corridors face saturation near Hanoi and Ho Chi Minh City industrial clusters, forcing curtailment of contracted renewable output and delaying project financial close.
- Polysilicon Supply Concentration:China's Xinjiang and Inner Mongolia production zones control ingot and wafer supply for Asia-Pacific solar deployments, exposing project developers to forced labor scrutiny and tariff volatility.
- LNG Price Volatility:Bangladesh and Philippines gas-fired generators depend on spot-indexed liquefied natural gas cargoes from Qatar and Australia, compressing plant dispatch margins when Asian spot prices spike above long-term contract benchmarks.
Strategic Opportunities
- Indonesia's Archipelago Microgrids:The national utility's 35,000 MW electrification backlog across 17,000 islands creates white space for solar-diesel hybrid developers serving nickel smelters and palm oil processing clusters in Sulawesi and Maluku.
- Green Hydrogen Export Corridors:Australia's Pilbara and Queensland regions combine abundant solar irradiance with deepwater port access, positioning electrolyzer installations to serve Japanese and South Korean steel decarbonization offtake.
- Behind-the-Meter Storage Aggregation:Thailand's provincial utilities and Australia's National Electricity Market enable virtual power plant participation from commercial battery systems, creating new revenue streams for C&I facility operators.
Industry Challenges
- Grid Code Harmonization:Inverter manufacturers face fragmented frequency response and voltage ride-through requirements across Australia's AEMO, India's CEA, and Vietnam's EVN technical standards, multiplying certification costs for multi-country portfolios.
- Interconnection Queue Management:Project developers in India's green energy corridors encounter three-to-four-year transmission connection delays as the Central Electricity Authority prioritizes stranded asset clearance over new renewable injection capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Power Market |
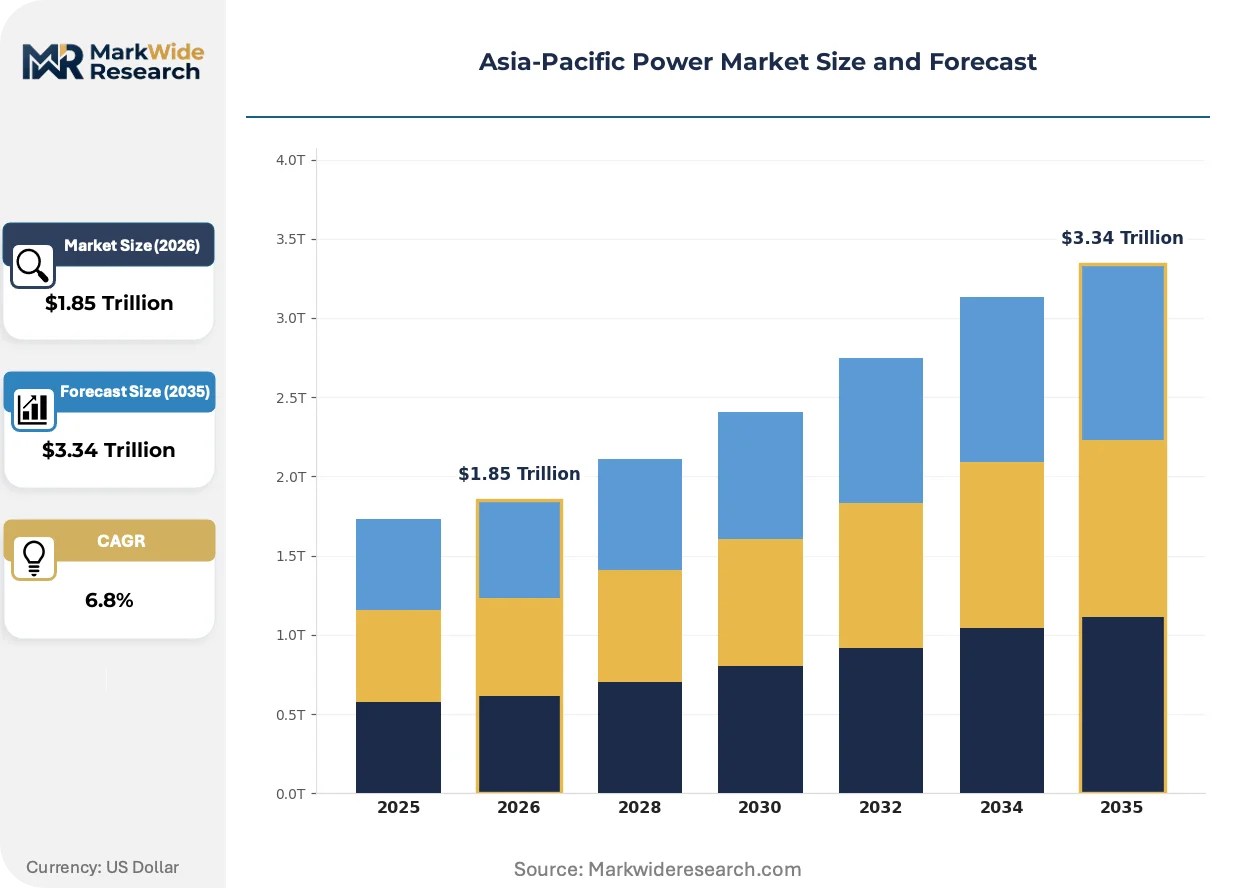
| Market Size in 2026 | $1.85 Trillion |
| Market Size in 2035 | $3.34 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Generation, Transmission, Distribution, Consultation Technology: Renewable Energy, Natural Gas, Nuclear Power, Hydropower End User: Industrial Sector, Commercial Sector, Residential Sector, Government Application: Power Generation, Grid Management, Smart Metering, Load Balancing |
| Companies Covered | PetroVietnam Gas Joint Stock Corporation, Hanoi Power, NTPC Limited, Brookfield Renewable Partners, NextEra Energy, Vingroup, Ho Chi Minh City Power Corporation, Sungrow Power Supply, Electricity Generating Authority of Thailand, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Power Market Strategic Shifts
Technology convergence between power electronics and digital control systems is compressing plant commissioning cycles while regulatory pressure on Scope 3 emissions reshapes corporate offtake contracting structures across the region.
Solid-state inverters with silicon carbide power modules are supplanting conventional silicon IGBT architectures in utility-scale solar and storage installations. Sungrow and Huawei are deploying megawatt-class string inverters at 1500V DC bus voltages across Vietnamese and Australian utility tenders, cutting balance-of-system costs and enabling longer DC string configurations that reduce cabling labor.
Thailand's Energy Regulatory Commission has mandated time-of-use tariff restructuring for industrial estates in the Eastern Economic Corridor, forcing independent power producers to renegotiate long-term supply agreements that previously relied on flat energy charges. Gas-fired generators and renewable developers alike are restructuring contracts to incorporate peak-demand pricing exposure, shifting investment toward battery co-location and demand response capabilities.
Corporate buyers in Singapore and Sydney are consolidating renewable procurement through aggregated virtual power purchase agreements that pool credit exposure across multiple offtakers. Data center operators and semiconductor fabs are bypassing traditional utility intermediaries to contract directly with Australian wind farms and Indian solar parks, securing 24/7 clean power matching through synthetic baseload structures that blend generation profiles with storage dispatch.
Asia-Pacific Power Market Segmentation
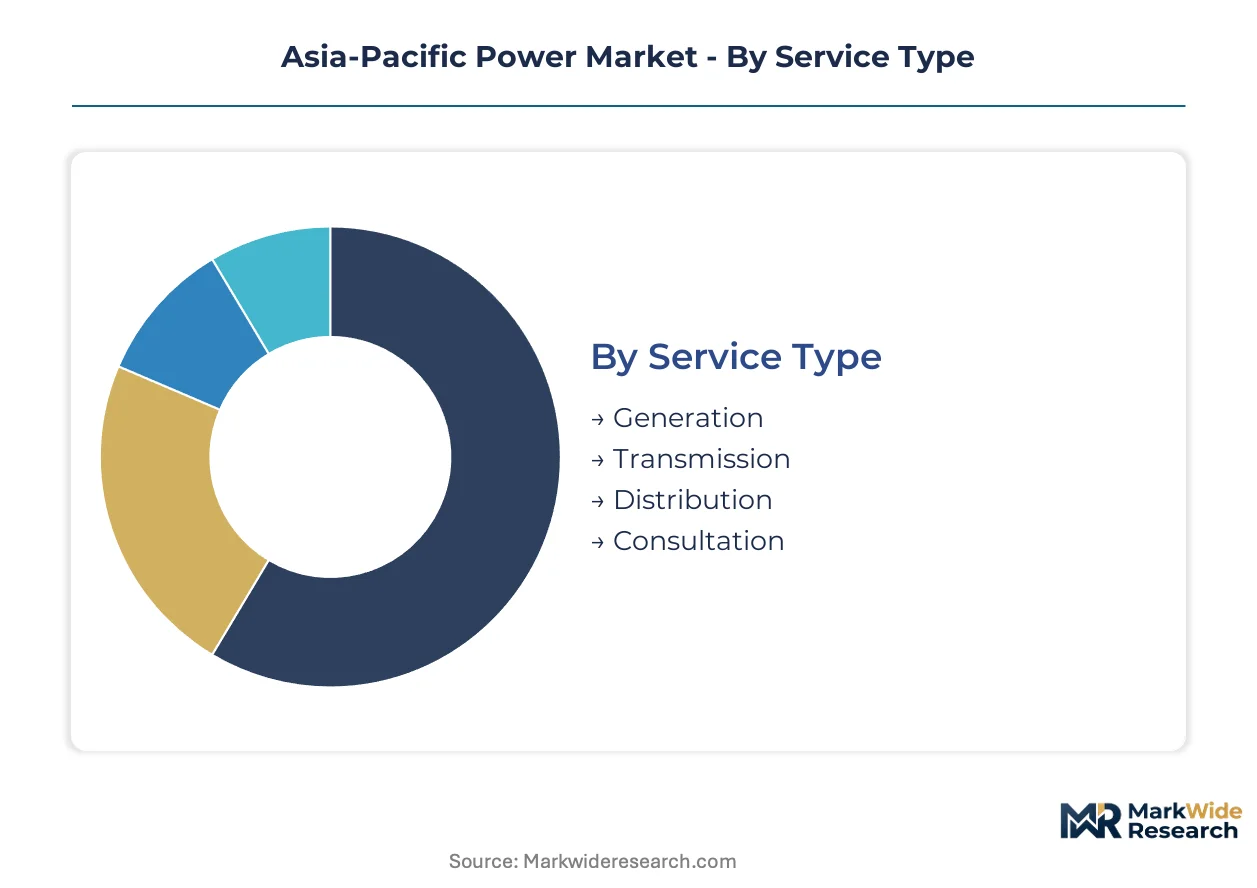
Segmentation of the Asia-Pacific power market reveals how regulatory frameworks, technology cost curves, and end-use electrification intensity reshape capital allocation across generation, network infrastructure, and customer-facing services. Distinct compliance obligations and dispatch priorities in Vietnam, India, and Australia fragment procurement patterns even within the same service category.
Service Type:
Vietnam's Electricity of Vietnam maintains monopoly control over transmission and distribution while liberalizing generation procurement, creating asymmetric regulatory exposure across service tiers.
- Generation:Utility-scale solar and offshore wind installations in Australia's National Electricity Market and Vietnam's central provinces receive priority dispatch under renewable portfolio standards. India's Central Electricity Authority mandates must-run status for solar parks, locking in offtake volumes that shield developers from merit-order dispatch risk.
- Transmission:Ultra-high-voltage direct current corridors at 800kV span China's western renewable bases to eastern load centers, while Vietnam's 500kV backbone near Hanoi and Ho Chi Minh City faces saturation from industrial park expansion. State-owned transmission system operators in Thailand and the Philippines control interconnection queues, delaying project financial close for independent generators.
- Distribution:Provincial utilities in Thailand's Eastern Economic Corridor and Australia's distributed network service providers manage low-voltage grid integration of rooftop solar and commercial battery systems.
- Consultation:Engineering firms advise on grid code compliance across fragmented technical standards in India's CEA, Australia's AEMO, and Vietnam's EVN jurisdictions.
Generation handles the majority of throughput; consultation is the fastest mover on share as grid complexity rises.
Technology:
Cost tier differentiation separates mass-deployed solar from capital-intensive nuclear and firming gas assets.
- Renewable Energy:Utility-scale solar dominates capacity additions in Vietnam, India, and Australia, with Sungrow and Huawei supplying 1500V DC string inverters that cut balance-of-system costs. Corporate offtakers in Singapore and Sydney contract directly for 24/7 clean power through synthetic baseload structures blending generation with storage dispatch.
- Natural Gas:Combined-cycle plants in Bangladesh and the Philippines provide firming capacity where renewable penetration exceeds grid flexibility, though spot-indexed LNG cargoes from Qatar compress dispatch margins during price spikes.
- Nuclear Power:South Korea's APR-1400 reactors and planned small modular reactor deployments in Australia face extended licensing timelines under national nuclear regulators.
- Hydropower:Run-of-river projects in Laos and Nepal export baseload electricity to Thailand and India under long-term power purchase agreements.
Renewable energy commands the largest capital deployment; natural gas is expanding most quickly as a reliability bridge.
End User:
Application intensity varies sharply between continuous-process industrial loads and intermittent commercial demand.
- Industrial Sector:Data center operators across Southeast Asia now outpace steel and cement producers as the fastest-growing buyer archetype for firm renewable capacity. Nickel smelters in Indonesia's Sulawesi and palm oil processing clusters in Maluku drive demand for solar-diesel hybrid microgrids across 17,000 islands.
- Commercial Sector:Semiconductor fabs in Singapore and Sydney bypass utility intermediaries to contract directly with Australian wind farms and Indian solar parks.
- Residential Sector:Distributed solar penetration rises across Thailand's provincial utilities and Australia's National Electricity Market, enabled by net metering tariffs.
- Government:Public buildings and municipal infrastructure in Vietnam and India anchor demand for rooftop solar under national renewable purchase obligations.
Industrial sector absorbs the highest absolute volumes; commercial sector is gaining share fastest through corporate procurement aggregation.
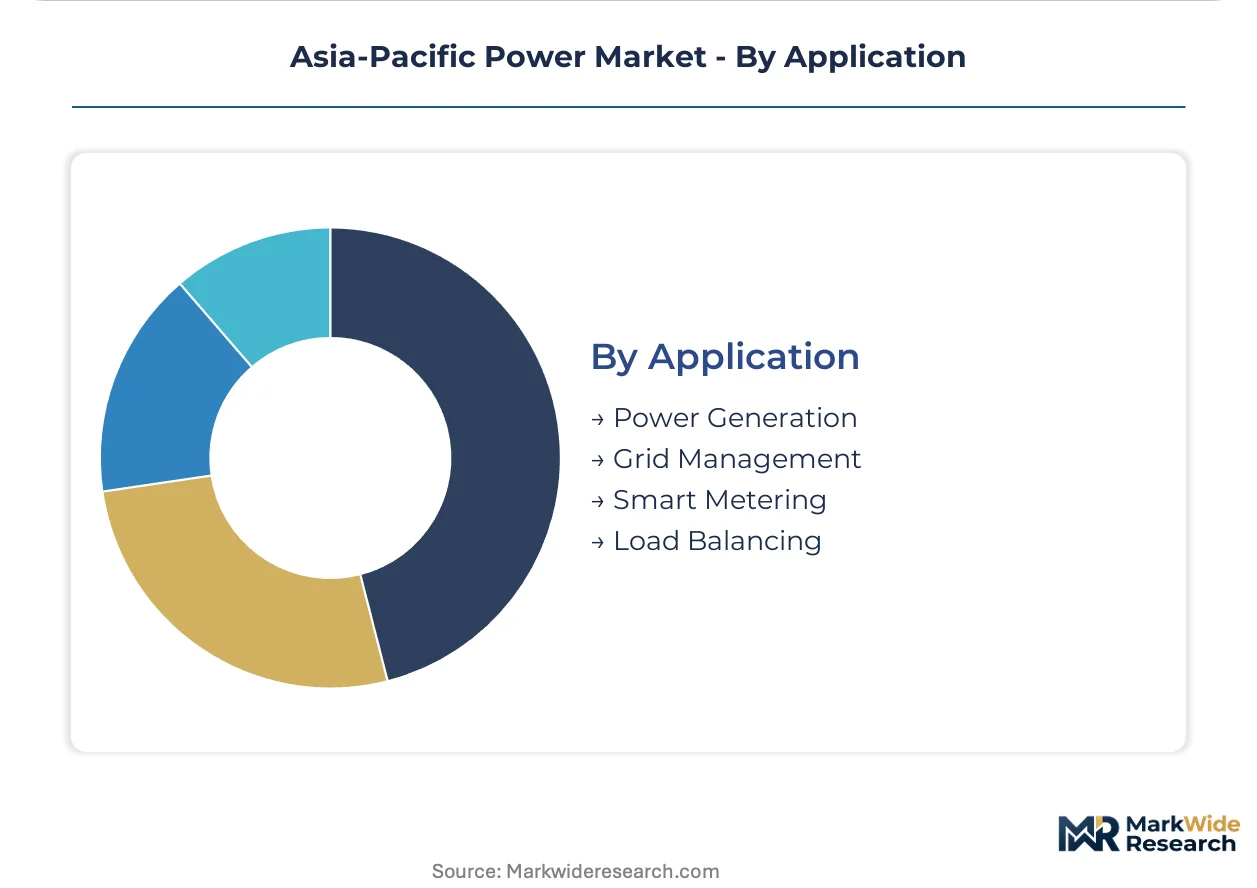
Application:
Technology maturity separates established generation services from emerging digital grid applications.
- Power Generation:Gigawatt-scale solar parks in India's Rajasthan and green hydrogen pilots anchored by NTPC Limited redirect capital toward domestic clean energy supply chains. Australia's competitive offshore wind tender rounds attract international developers to Bass Strait waters.
- Grid Management:Software and automation investment concentrates where distributed solar penetration rises, requiring real-time frequency control across interconnected synchronous zones operating at 49.5-50.5 Hz.
- Smart Metering:Thailand's Energy Regulatory Commission mandates time-of-use tariff restructuring for industrial estates, forcing demand response capability investment.
- Load Balancing:Virtual power plant participation from commercial battery systems creates new revenue streams for C&I facility operators in Australia's National Electricity Market.
Power generation retains dominant capital share; load balancing is climbing the fastest as battery costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 800kV ultra-high-voltage direct current corridors spanning China's western renewable bases to eastern load centers establish the physical backbone for Asia-Pacific power flows, while Vietnam's 500kV backbone saturation near Hanoi and Ho Chi Minh City industrial clusters illustrates the infrastructure strain reshaping procurement patterns.
Vietnam
Data center operators and industrial park developers drive electricity demand growth near Hanoi and Ho Chi Minh City. The Electricity of Vietnam monopoly maintains transmission control while liberalizing generation procurement through direct power purchase agreements. The 500kV backbone corridor saturation forces curtailment of contracted renewable output and delays project financial close.
India
Gigawatt-scale solar parks in Rajasthan and green hydrogen pilots redirect capital toward domestic clean energy supply chains. The Central Electricity Authority mandates renewable purchase obligations and interstate green energy corridors with must-run status for solar parks. Stranded asset clearance in the green energy corridors delays new renewable injection capacity.
Australia
Corporate buyers seeking 24/7 clean power contract directly with wind farms and solar parks through synthetic baseload structures. The Energy Security Board reshapes market rules around capacity adequacy and distributed resource participation. The National Electricity Market enables virtual power plant participation from commercial battery systems.
Thailand
Independent power producers supplying industrial estates in the Eastern Economic Corridor face time-of-use tariff restructuring. The Energy Regulatory Commission governs tariff structures and mandates demand response capability investment. Provincial utilities manage low-voltage grid integration of rooftop solar and commercial battery systems.
Indonesia
Nickel smelters in Sulawesi and palm oil processing clusters in Maluku drive demand for solar-diesel hybrid microgrids across 17,000 islands. The national utility's 35,000 MW electrification backlog creates white space for hybrid developers. Archipelago geography prevents centralized grid extension.
Asia-Pacific Power Market Competitive Environment
Concentration sits with state-owned utilities and integrated generation-retail providers across Vietnam, Thailand, and India. The vendor base fragments across inverter manufacturers, project developers, and renewable asset operators competing for corporate offtake contracts. Three archetypes dominate: state-controlled incumbents with transmission monopolies, international renewable developers with operational wind and solar portfolios, and power electronics specialists supplying utility-scale equipment. Competitive moves center on direct corporate power purchase agreements bypassing traditional utility intermediaries, and battery co-location strategies capturing time-of-use tariff premiums.
Within the state-controlled incumbent tier, PetroVietnam Gas Joint Stock Corporation and Hanoi Power exemplify vertically integrated national champions managing generation, transmission, and retail functions under single-buyer frameworks. Among power electronics specialists, Sungrow Power Supply occupies a position representing the inverter and energy storage system suppliers dominating Southeast Asian utility tenders. At the international developer tier, Brookfield Renewable Partners anchors the operational asset owners positioning for long-term offtake contracts with corporate buyers seeking 24/7 clean power matching.
| Leading Market Players |
|---|
| PetroVietnam Gas Joint Stock Corporation |
| Hanoi Power |
| NTPC Limited |
| Brookfield Renewable Partners |
| NextEra Energy |
| Vingroup |
| Ho Chi Minh City Power Corporation |
| Sungrow Power Supply |
| Electricity Generating Authority of Thailand |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inverter delivery timelines from Chinese manufacturing hubs to Vietnamese project sites concentrate procurement leverage among Sungrow and Huawei, amplifying pricing power for integrated generation-retail providers who can secure firm equipment allocations ahead of utility-scale solar commissioning deadlines.
Pricing Analysis
Volume-discount tiering separates gigawatt-scale independent power producers from sub-hundred-megawatt developers across Vietnamese and Australian utility tenders. Pricing stratifies across premium, standard, and economy tiers based on inverter efficiency ratings and bundled after-sales service coverage. Cost compression in the economy tier is intensifying because Sungrow's silicon carbide module deployments are cutting balance-of-system costs for string inverter configurations. Data center operators exhibit the least price sensitivity due to 24/7 clean power matching requirements, while provincial utilities in Thailand's Eastern Economic Corridor face acute budget constraints.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Ningbo ports to Ho Chi Minh City and Hai Phong terminals fluctuate with container availability across the Asia-Pacific trade lane, forcing project developers to pre-position inverter and battery storage components ahead of financial close. Polysilicon supply concentrates in China's Xinjiang and Inner Mongolia zones, while cell and module assembly spreads across Vietnam, Malaysia, and Thailand. Solar deployments draw from wafer imports, lithium iron phosphate cells, and copper busbar feedstock. Single-source vulnerability in polysilicon ingot supply exposes developers to forced labor scrutiny and tariff volatility. Distribution runs through EPC contractors and independent power producer procurement teams to utility-scale installation sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific power market is recovering from transmission bottleneck-induced project delays, with capital deployment accelerating as Vietnam's direct power purchase agreement framework matures and India's PLI scheme redirects manufacturing investment toward domestic solar module supply chains.
For Market Incumbents: Fortify transmission interconnection queue positions through early engagement with Vietnam's Electricity of Vietnam and India's Central Electricity Authority, securing priority grid access ahead of stranded asset clearance backlogs. Deepen backward integration into battery energy storage system assembly to capture time-of-use tariff premiums in Thailand's restructured industrial estate contracts. The threat of integrated generation-retail providers bypassing traditional utility intermediaries demands captive supply chain control over inverter and storage component sourcing.
For New Entrants and Emerging Players: Behind-the-meter storage aggregation services represent the most penetrable white space, as Thailand's provincial utilities and Australia's National Electricity Market lack mature virtual power plant platforms for commercial battery dispatch. Target Indonesia's archipelago microgrid segment, where 35,000 MW of electrification backlog across 17,000 islands creates demand for solar-diesel hybrid developers serving nickel smelters in Sulawesi. A direct sales model to industrial park operators in Vietnam's northern provinces bypasses entrenched utility procurement channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned utility renewable generation portfolios in Vietnam and Thailand, where governments seek private capital participation to accelerate clean energy transitions. Long-term viability hinges on offtake contract duration and grid code harmonization capabilities across Australia's AEMO, India's CEA, and Vietnam's EVN jurisdictions. The signal to monitor is corporate buyer aggregation momentum in Singapore and Sydney, where synthetic baseload structures blending generation with storage dispatch indicate premium pricing tolerance for 24/7 clean power matching.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Power Purchase Agreement Execution | Vietnam's DPPA framework unlocks corporate procurement at scale, bypassing EVN's single-buyer monopoly. |
| Battery Co-location Investment | Thailand's time-of-use tariff restructuring forces demand response capability into renegotiated industrial supply contracts. |
| Offshore Wind Capacity Buildout | Australia's Bass Strait tenders attract international developers diversifying beyond coal-dependent baseload regions. |
| Green Hydrogen Export Corridor Development | Pilbara and Queensland electrolyzer installations target Japanese and South Korean steel decarbonization offtake. |
| Grid Code Certification Investment | Fragmented frequency response requirements across AEMO, CEA, and EVN multiply costs for multi-country inverter portfolios. |
Study Parameters
The analysis maps generation services, transmission infrastructure, and distributed resource participation, each validated through utility planning officers, independent power producer project developers, EPC contractors, and grid operators, combined with regulatory filings from Vietnam's Electricity of Vietnam, India's Central Electricity Authority, and Australia's Energy Security Board, plus project development databases and IEA power sector reports, using bottom-up capacity addition tracking and top-down market sizing triangulation.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon, with segmentation modeling across fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from installed capacity trajectories and capital expenditure flows, incorporating corporate procurement aggregation patterns and transmission interconnection queue progression as industry-specific forecast inputs.
Forecasts assume regulatory continuity in Vietnam's direct power purchase agreement evolution, India's renewable purchase obligation enforcement, and Australia's distributed resource participation rules; material policy shifts would require re-modeling. Specific risk factors include LNG price volatility affecting Bangladesh and Philippines gas plant dispatch, polysilicon supply concentration exposure, and grid code harmonization delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Spain Power Market
Power
Doubly Fed Induction Generator (DFIG) Market
Power
Power Purchase Agreement Market
Power
North America Micro CHP Market
Power
Asia-Pacific Microturbine Market
Power
Gabon Power Market
Power
Modified Sine Wave Home Inverters Market
Power
Europe Frequency Converter Market
Power
Solar Plants Controllers Market
Power
Colombia Power Market
Power
Qatar Power Market
Power
Middle-East and Africa Power Rental Market
Power
Japan Power Market
Power
Single-Phase Microinverter Market
Power
Water Turbine Market
Power
Middle East and Africa Combined Heat & Power Market