
 Canada Thermal Power Market | 2026-2036
Canada Thermal Power Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Thermal Power Market Outlook
Natural gas is decoupling from coal in baseload dispatch economics across provincial grids. TransAlta Corporation leverages its Alberta fleet transition to gas-fired assets while sustaining coal-to-biomass retrofits at select sites. Capital Power Corporation anchors its growth strategy in combined-cycle capacity additions near Edmonton. Ontario Power Generation Inc. competes through nuclear-thermal hybrid dispatch flexibility in the province's regulated market.
Thermal power denotes electricity generation from heat energy conversion, typically through steam or gas turbines operating at temperatures exceeding 500°C and pressures above 100 bar to drive synchronous generators for grid-connected supply. Natural gas combined-cycle technology leads new capacity additions due to superior heat rates and lower carbon intensity per megawatt-hour, while coal-fired steam turbine installations face accelerated retirement timelines under federal regulations. Biomass co-firing represents a growing retrofit pathway for existing coal units seeking compliance flexibility, though feedstock logistics constrain geographic deployment to forest-product regions.
Environment and Climate Change Canada enforces the federal carbon pricing backstop, while provincial regulators including the Alberta Energy Regulator and Ontario's Independent Electricity System Operator shape dispatch rules and capacity market parameters. The Clean Fuel Regulations from Environment and Climate Change Canada tighten lifecycle emission standards for liquid and gaseous fuels burned in thermal plants. Stakeholders must monitor carbon border adjustment developments and provincial renewable portfolio standards that progressively tighten thermal plant dispatch priority.
Market Dynamics
Carbon pricing under Environment and Climate Change Canada's federal backstop program is forcing baseload generators to restructure dispatch economics and accelerate fuel-switching investments across provincial grids.
Growth Catalysts
- Alberta oil sands baseload demand:Industrial extraction facilities require reliable thermal output for steam-assisted gravity drainage operations, sustaining year-round capacity factors for combined-cycle plants.
- Clean Fuel Regulations lifecycle standards:Tightening emission thresholds for gaseous fuels create compliance-driven retrofit demand for existing natural gas turbines.
- Biomass co-firing technology:Forest-product regions in British Columbia and Quebec enable coal-unit conversions using localized feedstock supply chains.
Market Restraints
- Pipeline capacity constraints:Natural gas delivery bottlenecks into Ontario and Atlantic provinces limit new combined-cycle site selection and raise delivered fuel costs.
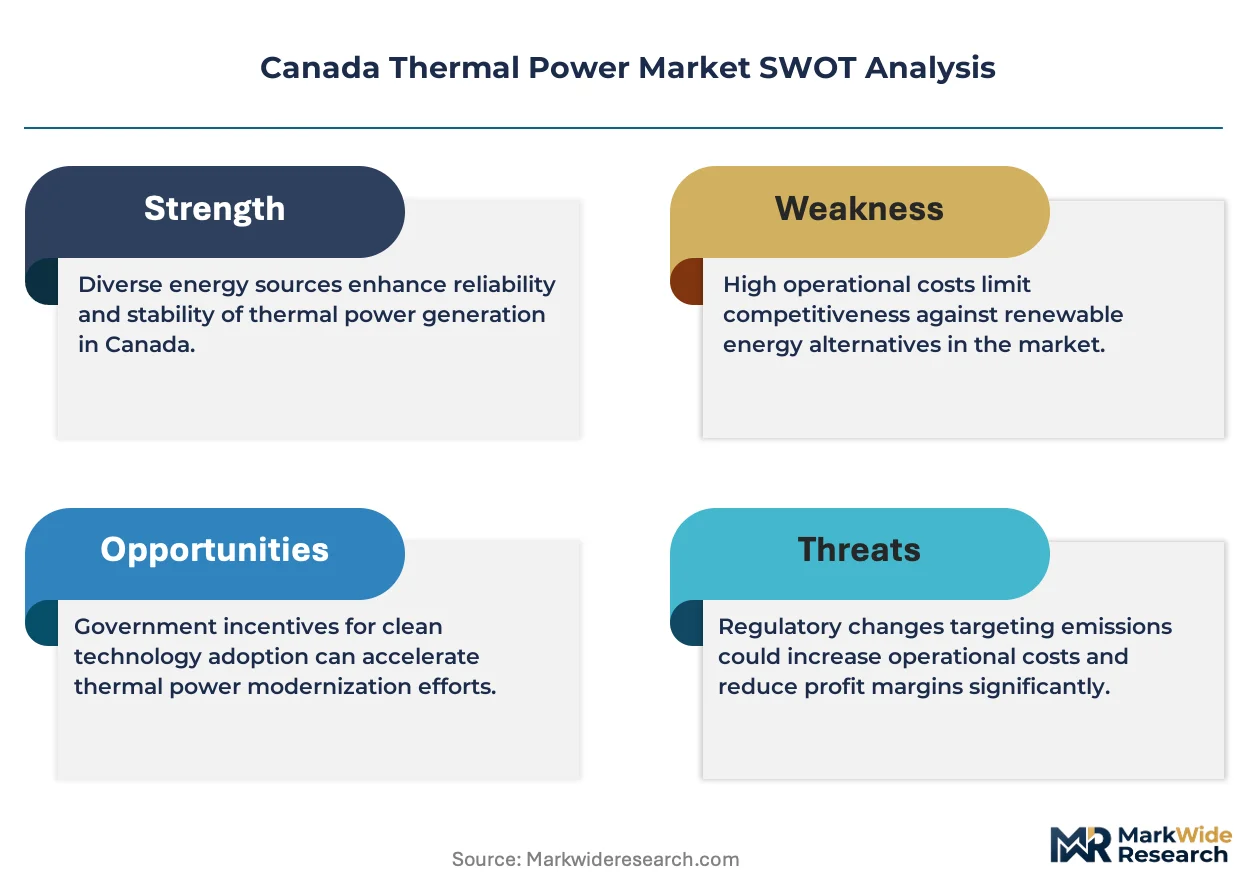
- Carbon price escalation trajectory:Scheduled increases under the federal backstop program compress operating margins for unabated thermal generation.
- Intermittent renewable priority dispatch:Provincial renewable portfolio standards in Ontario and Saskatchewan reduce thermal plant load factors during peak wind and solar output periods.
Strategic Opportunities
- Saskatchewan carbon capture retrofits:The province's coal-dependent grid structure positions existing units for federal investment tax credit eligibility under clean technology provisions.
- District heating integration:Urban combined-cycle installations in Edmonton and Calgary can capture waste heat for municipal thermal networks.
- Small modular reactor hybrid configurations:Nuclear-thermal dispatch pairing offers regulated utilities pathway to firm low-carbon baseload.
Industry Challenges
- Grid interconnection queue delays:Independent Electricity System Operator processing timelines for new thermal capacity in Ontario extend project commissioning schedules.
- Skilled trades shortage:Specialized turbine maintenance and high-pressure welding certifications face demographic retirement pressures across Alberta and Saskatchewan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Thermal Power Market |
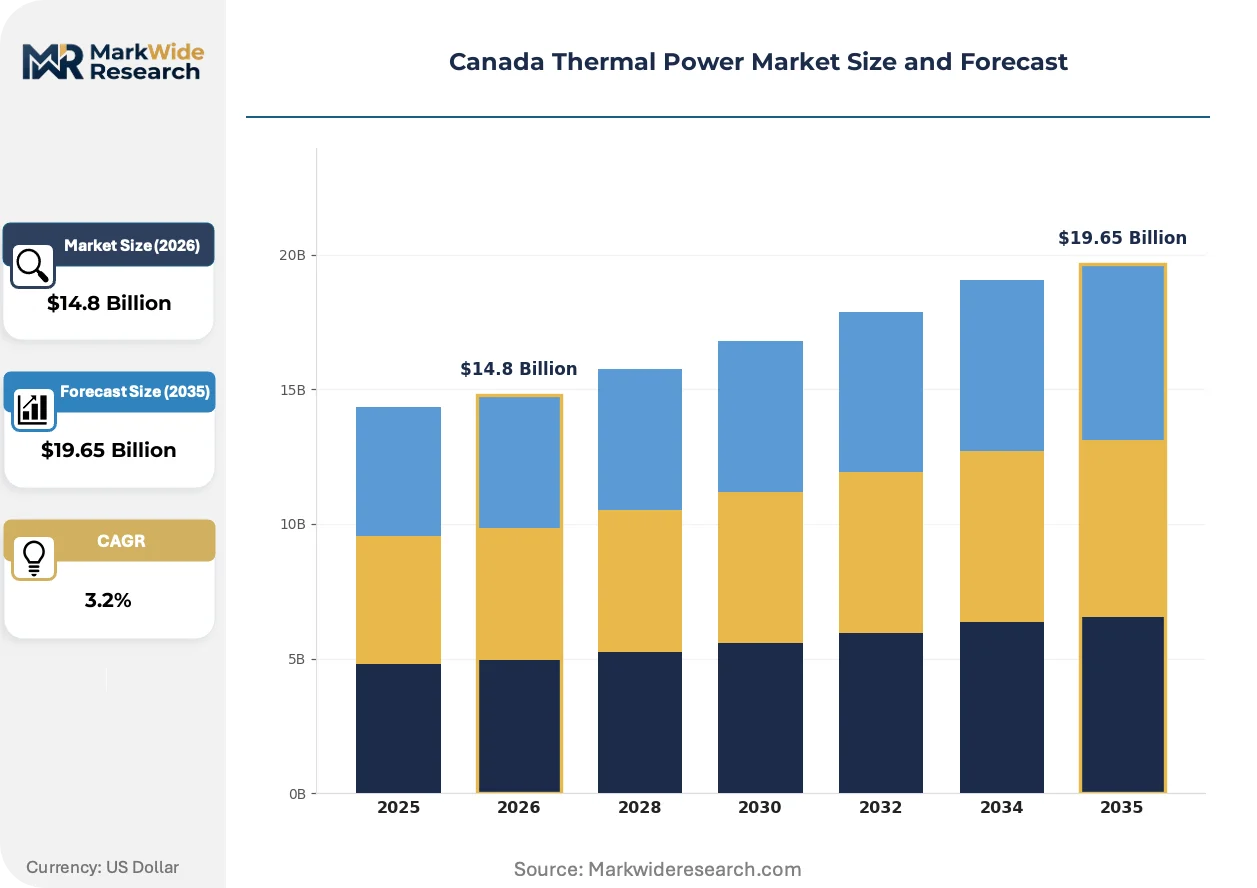
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $19.65 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Coal, Natural Gas, Oil, Biomass Technology: Steam Turbine, Gas Turbine, Combined Cycle, Solar Thermal End User: Utilities, Industrial, Commercial, Residential Application: Power Generation, Heating, Co-Generation, Desalination |
| Companies Covered | TransAlta Corporation, Capital Power Corporation, Ontario Power Generation Inc., SaskPower International Inc., Emera Inc., ATCO Power Ltd., Northland Power Inc., Maxim Power Corp, Bruce Power LP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Thermal Power Market Strategic Shifts
Equipment manufacturers and project developers are reconfiguring plant architectures to align with carbon compliance timelines and evolving provincial dispatch rules. Three developments dominate current investment planning.
Small-scale combined-cycle packages are modularizing to serve distributed industrial loads and remote mining operations. Caterpillar and Wärtsilä are deploying containerized turbine-generator sets below 50 MW for off-grid oil sands camps and northern mineral processing sites. This configuration is modularizing project development timelines from 36 months to 18 months while reducing transmission interdependency.
Environment and Climate Change Canada's Clean Fuel Regulations are tightening lifecycle carbon intensity thresholds for liquid and gaseous transportation and heating fuels. Thermal generators must now document upstream methane leakage and processing emissions in compliance submissions. Alberta-based operators are responding by sourcing certified low-leakage natural gas from Montney basin producers with third-party verification.
Power purchase agreement structures are compressing contract tenors as provincial utilities seek flexibility to accommodate renewable buildouts. Saskatchewan Power Corporation and BC Hydro are offering 10-year agreements rather than traditional 20-year terms for new gas-fired capacity. This shift concentrates in provinces with aggressive wind and solar procurement targets where thermal plants face earlier economic obsolescence risk.
Canada Thermal Power Market Segmentation
Segmentation reveals how fuel type, technology configuration, and end-use application reshape investment priorities across provincial grids. Each dimension exposes distinct compliance pathways and revenue exposure under Canada's carbon pricing regime.
Type:
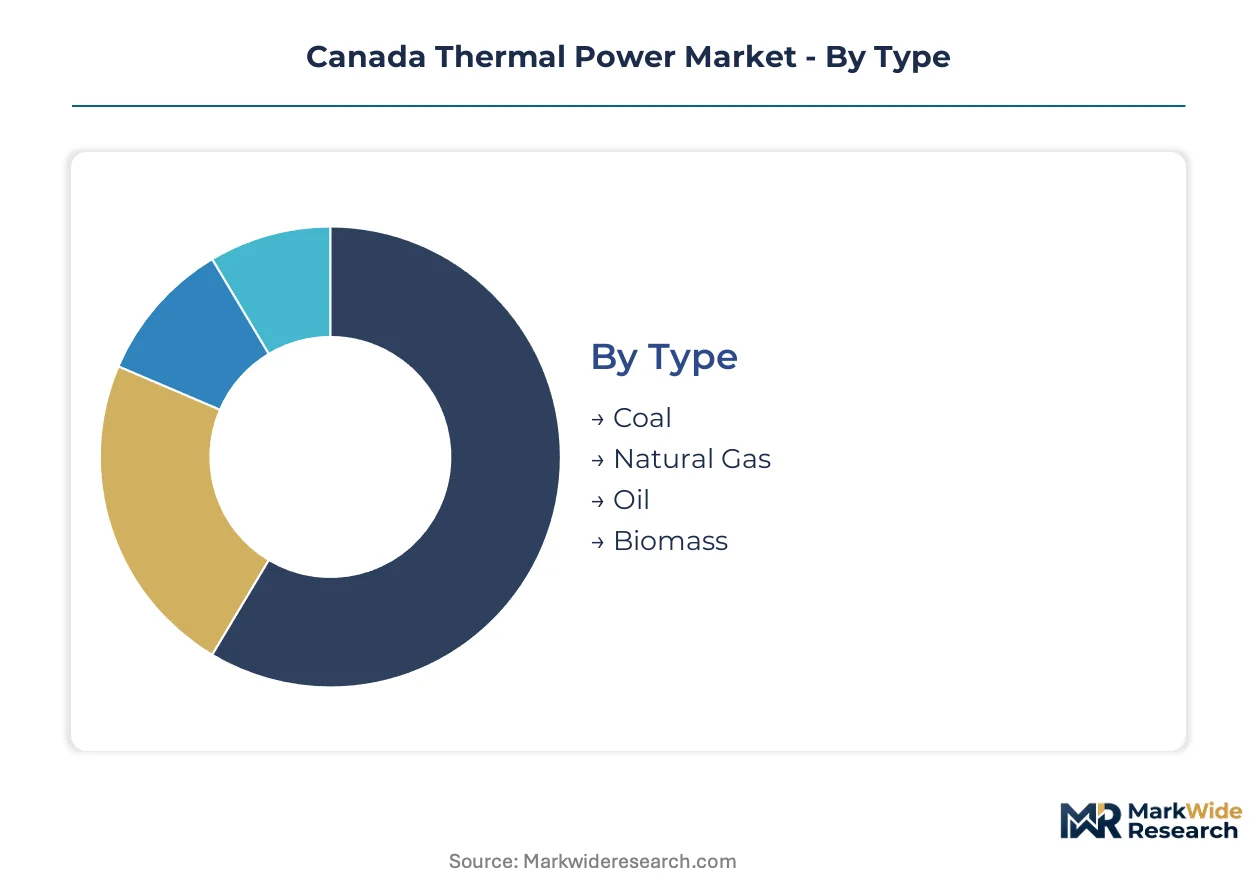
Standalone fuel categories dominate baseload procurement decisions, while embedded hybrid configurations gain traction in retrofit markets.
- Natural Gas:Combined-cycle configurations achieve heat rates below 7,000 Btu/kWh with carbon intensities roughly half those of unabated coal. Alberta's oil sands corridor and Ontario's IESO-regulated grid anchor procurement volumes, though pipeline constraints into Atlantic provinces limit eastern expansion.
- Coal:Subcritical and supercritical steam units face accelerated retirement timelines under Environment and Climate Change Canada's federal carbon backstop. Saskatchewan Power Corporation's fleet sustains operation through carbon capture retrofit eligibility, while Alberta generators accelerate fuel-switching investments.
- Oil:Distillate-fired peaking turbines serve remote northern communities and grid reliability reserves in Newfoundland and Labrador where natural gas infrastructure remains absent.
- Biomass:Forest-product regions in British Columbia and Quebec enable coal-unit co-firing retrofits using localized feedstock supply chains with third-party sustainability certification.
Volume placements concentrate in natural gas; the faster expansion belongs to biomass co-firing retrofits.
Technology:
Cost tier separation distinguishes mature steam infrastructure from next-generation configurations commanding capital premiums.
- Combined Cycle:Integrated gas and steam turbine arrangements extract maximum thermal efficiency from natural gas feedstock. TransAlta Corporation and Capital Power Corporation anchor Alberta capacity additions near Edmonton, with heat recovery steam generators capturing exhaust energy for additional megawatt output.
- Gas Turbine:Simple-cycle aeroderivative and heavy-frame units provide rapid-start grid balancing services. Ontario's IESO procurement mechanisms prioritize these assets for renewable integration support during wind and solar output variability.
- Steam Turbine:Coal and nuclear-fed configurations remain entrenched in Saskatchewan's baseload structure. Federal clean technology investment tax credits sustain retrofit economics for carbon capture-equipped units.
- Solar Thermal:Concentrating parabolic trough and power tower technologies face limited deployment in Canada's latitude-constrained solar resource regions, with pilot installations concentrated in southern Alberta and Saskatchewan.
Capital deployment concentrates in combined cycle; the steepest efficiency gains are emerging in gas turbine grid-balancing configurations.
End User:
Customer type determines contract tenure, dispatch priority, and exposure to provincial renewable portfolio standards.
- Utilities:Provincial crown corporations and independent power producers operate under regulated cost-of-service or competitive market frameworks. Saskatchewan Power Corporation and BC Hydro procure capacity through 10-year power purchase agreements, compressing from traditional 20-year tenors to preserve renewable integration flexibility.
- Industrial:Oil sands extraction facilities in Alberta's Athabasca region require dedicated thermal output for steam-assisted gravity drainage operations. These loads sustain year-round capacity factors exceeding 85 percent for captive combined-cycle plants.
- Commercial:District heating networks in Edmonton and Calgary capture waste heat from urban combined-cycle installations, with municipal thermal distribution infrastructure expanding across Alberta's major metropolitan zones.
- Residential:Distributed natural gas microturbines and combined heat and power units serve remote communities beyond centralized grid infrastructure, particularly in northern territories and Atlantic coastal regions.
Contract volume concentrates in utilities; the fastest share gains are appearing in industrial self-generation.
Application:
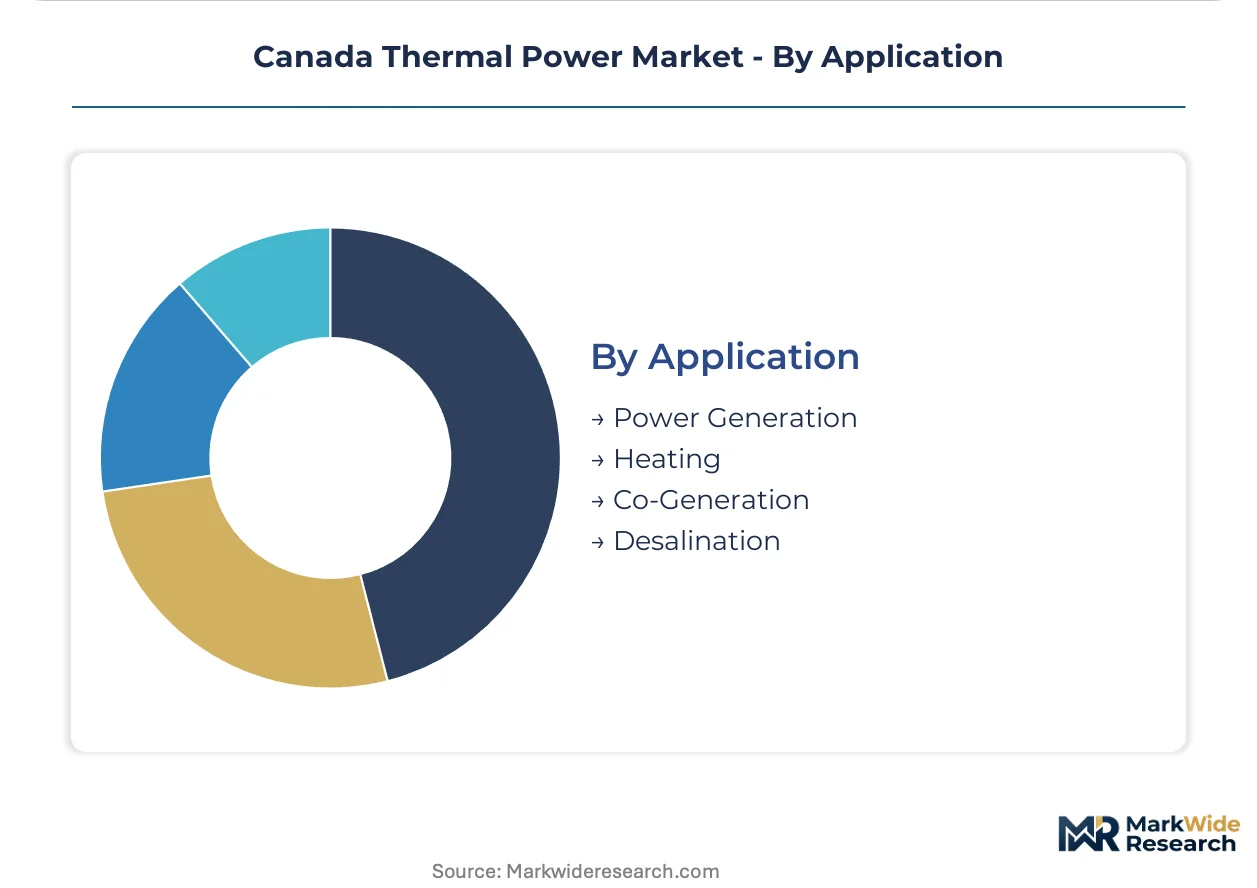
Application scope separates pure electricity merchants from integrated energy service providers capturing multiple revenue streams.
- Power Generation:Grid-connected synchronous generators supply wholesale electricity markets under provincial dispatch rules. Alberta's Energy-only market and Ontario's capacity auction mechanisms shape merchant plant economics.
- Co-Generation:Combined heat and power configurations extract thermal energy for industrial process steam or district heating. Edmonton and Calgary municipal networks integrate with urban combined-cycle installations.
- Heating:Direct thermal output serves industrial process requirements and residential space conditioning through district energy infrastructure.
- Desalination:Thermal desalination applications remain negligible in Canada's freshwater-abundant geography, with limited pilot activity in coastal Atlantic communities.
Revenue concentration sits with power generation; co-generation is climbing the fastest as carbon pricing improves waste heat recovery economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The federal clean technology investment tax credit zones are concentrating thermal power development in provinces with carbon capture retrofit eligibility and established natural gas infrastructure.
Ontario
The Independent Electricity System Operator regulates capacity auctions that favor combined-cycle gas turbines for renewable integration support. Clean Fuel Regulations compliance drives turbine upgrades at existing facilities. The Greater Toronto Area anchors procurement volumes for grid-balancing assets serving the province's nuclear-thermal hybrid dispatch structure.
Alberta
Oil sands extraction facilities in the Athabasca region sustain year-round baseload demand for steam-assisted gravity drainage operations. The Alberta Energy Regulator oversees dispatch rules in the province's energy-only market. Edmonton and Calgary host the province's largest combined-cycle installations, with Capital Power Corporation and TransAlta Corporation anchoring capacity additions near the capital region.
Saskatchewan
Saskatchewan Power Corporation's coal-dependent grid structure positions existing units for federal clean technology investment tax credit eligibility. The province's carbon capture retrofit pipeline aligns with Environment and Climate Change Canada compliance timelines. The Estevan-Weyburn corridor concentrates pilot carbon capture installations serving enhanced oil recovery operations.
British Columbia
Forest-product regions enable biomass co-firing retrofits using localized feedstock supply chains with third-party sustainability certification. The province's clean electricity standard compresses thermal plant dispatch priority during hydroelectric surplus periods. The Prince George pulp corridor anchors biomass-to-energy conversion projects leveraging captive wood waste streams.
Quebec
Industrial process steam demand from aluminum smelters and pulp mills sustains captive cogeneration capacity despite abundant hydroelectric supply. The Régie de l'énergie shapes distribution tariff structures for thermal interconnects. The Saguenay-Lac-Saint-Jean region hosts natural gas turbine installations serving Rio Tinto Alcan's aluminum reduction facilities.
Canada Thermal Power Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated provincial utilities commanding regulated markets while independent power producers compete for merchant capacity. The market exhibits moderate concentration around crown corporations and established Alberta generators. Three archetypes dominate: provincial utilities with rate-base protected positions, independent power producers pursuing merchant opportunities, and integrated oil sands operators with captive generation assets. Competitive moves center on carbon capture retrofit partnerships and combined-cycle site acquisitions near industrial load centers.
Among Alberta-based integrated generators, TransAlta Corporation and Capital Power Corporation occupy positions exemplifying the merchant-to-regulated transition archetype, while Ontario Power Generation Inc. represents the provincial utility model with hybrid nuclear-thermal dispatch flexibility. These three entities anchor competitive dynamics across the two largest provincial markets.
| Leading Market Players |
|---|
| TransAlta Corporation |
| Capital Power Corporation |
| Ontario Power Generation Inc. |
| SaskPower International Inc. |
| Emera Inc. |
| ATCO Power Ltd. |
| Northland Power Inc. |
| Maxim Power Corp |
| Bruce Power LP |
| Others |
Value Chain & Pricing Dynamics
Alberta AECO natural gas price benchmarks cascade through turbine fuel cost structures into three-tier pricing stratification across combined-cycle, gas turbine, and steam turbine procurement tiers. Environment and Climate Change Canada carbon charge escalation compresses operating margins for unabated thermal assets while rewarding low-leakage certified gas sourcing from Montney basin producers.
Pricing Analysis
Short lead-time premiums for modular containerized turbine packages below 50 MW command capital cost premiums against standard 36-month project timelines. The dominant structure runs through long-term power purchase agreements with compressed tenors shifting from 20-year to 10-year terms as provincial utilities preserve renewable integration flexibility. Price differentiation separates carbon-capture-equipped retrofits eligible for federal clean technology investment tax credits from unabated legacy assets facing margin compression. Industrial oil sands offtakers exhibit lowest price sensitivity due to captive steam demand requirements, while merchant grid-connected plants face acute sensitivity to carbon price trajectory uncertainty.
Supply Chain Analysis
Direct-to-utility channels anchor procurement for grid-scale combined-cycle capacity above 300 MW, while EPC contractors handle distributed industrial installations. Manufacturing concentration for heavy-frame gas turbines rests on Germany, Japan, and the United States, with heat recovery steam generator fabrication drawing from South Korean and Chinese fabrication yards. Critical dependencies include nickel-based superalloys for turbine blades, high-grade steel forgings for pressure vessels, and precision control systems for grid synchronization. Single-source vulnerability concentrates in aeroderivative turbine packages where GE Vernova and Siemens Energy command effective duopoly positions. Distribution runs through regional EPC consortiums partnering with provincial utilities and independent power producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Environment and Climate Change Canada's Clean Fuel Regulations lifecycle standards erect compliance barriers that favor incumbent operators with capital reserves for certified low-leakage fuel sourcing and carbon capture retrofit pipelines.
For Market Incumbents: Anchor defensive positioning through carbon capture retrofit partnerships at Saskatchewan coal units and combined-cycle site acquisitions near Edmonton industrial load centers. TransAlta Corporation and Capital Power Corporation demonstrate viable transition archetypes through Montney basin certified gas supply agreements. Threat displacement from small modular reactor hybrid configurations demands monitoring of Ontario Power Generation's nuclear-thermal dispatch experiments. Vertical integration into district heating infrastructure offers margin protection through waste heat revenue capture. For New Entrants and Emerging Players: The 15-20% price-point gap between premium combined-cycle and economy gas turbine configurations creates entry space for modular sub-50 MW packages serving remote mining and oil sands camp demand. Saskatchewan carbon capture retrofit supply chains represent the most penetrable white-space, with federal investment tax credit eligibility reducing capital barrier intensity. British Columbia biomass co-firing retrofits offer secondary entry angle through localized feedstock partnerships with forest-product processors. Go-to-market execution should emphasize 18-month project timelines against incumbent 36-month development cycles. For Investors and Strategic Acquirers: The window for entry favors carbon-capture-retrofit-ready coal assets in Saskatchewan and Alberta combined-cycle installations with district heating integration potential. Long-term viability centers on regulated utility rate-base protection versus merchant exposure to carbon price escalation. Acquisition target archetype: mid-scale independent power producers with 10-year utility offtake contracts and identifiable fuel-switching compliance pathways. Monitor Alberta Energy Regulator dispatch rule modifications as inflection signal for merchant plant economic obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Deployment | Saskatchewan Power Corporation positions existing coal units for federal clean technology investment tax credit eligibility. |
| Certified Low-Leakage Fuel Sourcing | Alberta operators secure Montney basin supply with third-party verification for Clean Fuel Regulations compliance. |
| District Heating Integration | Edmonton and Calgary municipal networks capture waste heat from urban combined-cycle installations. |
| Modular Turbine Package Deployment | Caterpillar and Wärtsilä containerized sets compress project timelines for remote oil sands and mining demand. |
| Compressed Tenor Power Purchase Agreement | Saskatchewan Power Corporation and BC Hydro shift from 20-year to 10-year terms for renewable integration flexibility. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Canada Thermal Power Market assessment. Primary interviews with utility planning officers, independent power producer project developers, EPC contractors, grid operators at the Independent Electricity System Operator and Alberta Electric System Operator, and fuel supply specialists informed demand-side validation. Secondary sources included Environment and Climate Change Canada regulatory impact assessments, Alberta Energy Regulator market reports, FERC-equivalent provincial utility disclosures, and natural gas pipeline capacity filings. Bottom-up project development databases triangulated against top-down provincial grid capacity forecasts.
Data-stream reconciliation across fuel type, technology configuration, and end-use application dimensions shaped the analytical framework. Segmentation modeling incorporated generation capacity tier, project scale, regulatory framework, and regional grid type distinctions. CAGRs were derived through regression analysis of historical capacity additions against carbon price trajectory scenarios and industrial load growth projections. Forecast inputs included oil sands extraction facility expansion timelines, federal clean technology investment tax credit uptake assumptions, and provincial renewable portfolio standard dispatch priority schedules.
Inputs from Environment and Climate Change Canada, provincial regulators, and utility procurement disclosures were available through the study window; gaps in private power purchase agreement pricing terms and carbon capture retrofit cost actuals introduce uncertainty bands around merchant plant economics. Forecasts reflect documented assumptions regarding carbon price escalation trajectories, pipeline capacity expansion timelines, and small modular reactor commercialization schedules. Periodic stress-testing of base assumptions is recommended given regulatory policy volatility and renewable integration pace uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
India Uninterruptible Power Supply (UPS) Market
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
Portugal Power Market
Power
Mexico Power EPC Market
Power
Resonant Power Converters Market
Power
Saudi Arabia Power Market
Power
Residential Portable Inverter Generator Market
Power
North America Microturbine Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Robotic Power Source Market
Power
Power Capacitors Market
Power
Europe Submarine Power Cables Market
Power
Solar UPS Market
Power
Modular PSA Nitrogen Generator Market
Power
Sudan Power EPC Market
Power
Doubly Fed Induction Generator (DFIG) Market