
 Japan Electric Vehicle Charging Station Market | 2026-2036
Japan Electric Vehicle Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Electric Vehicle Charging Station Market Insights
Silicon carbide power modules are displacing conventional silicon IGBTs in DC fast charger inverters, and this semiconductor transition is pivoting unit economics toward higher-efficiency, smaller-footprint designs. ABB Ltd leverages its traction in heavy-industrial power electronics to anchor premium ultra-fast segments. Delta Electronics Inc sustains manufacturing scale through captive component sourcing and in-house magnetics production. Toyota Connected Corporation competes via tight integration with the automaker's vehicle telematics ecosystem, enabling predictive charge scheduling.
An electric vehicle charging station comprises power conversion electronics, grid-interconnection hardware, and user-interface systems engineered to replenish battery electric vehicle energy stores at power levels ranging from sub-7 kW residential AC to 350 kW+ DC outputs. The primary commercial purpose centers on reducing vehicle downtime while managing grid load profiles through scheduled or demand-responsive dispatch. DC Fast installations command disproportionate capital allocation despite smaller unit counts, reflecting margin concentration where utility-scale grid connections and cooling infrastructure create barriers. Wireless charging remains nascent in Japan, with pilot deployments concentrated at fleet depots where automated alignment justifies premium hardware costs.
METI administers subsidy programs covering up to two-thirds of charger installation costs for highway and remote-area sites, while the Ministry of Land, Infrastructure, Transport and Tourism revises building standards to mandate EV-ready electrical capacity in new commercial structures above specified floor areas. JIS standards and CHAdeMO protocol certification govern connector interoperability, with PSE electrical safety marking required for all grid-connected sales. Stakeholders must track municipal ordinance proliferation, as Tokyo, Osaka, and Nagoya implement divergent parking-space electrification mandates that fragment compliance requirements for national operators.
Market Dynamics
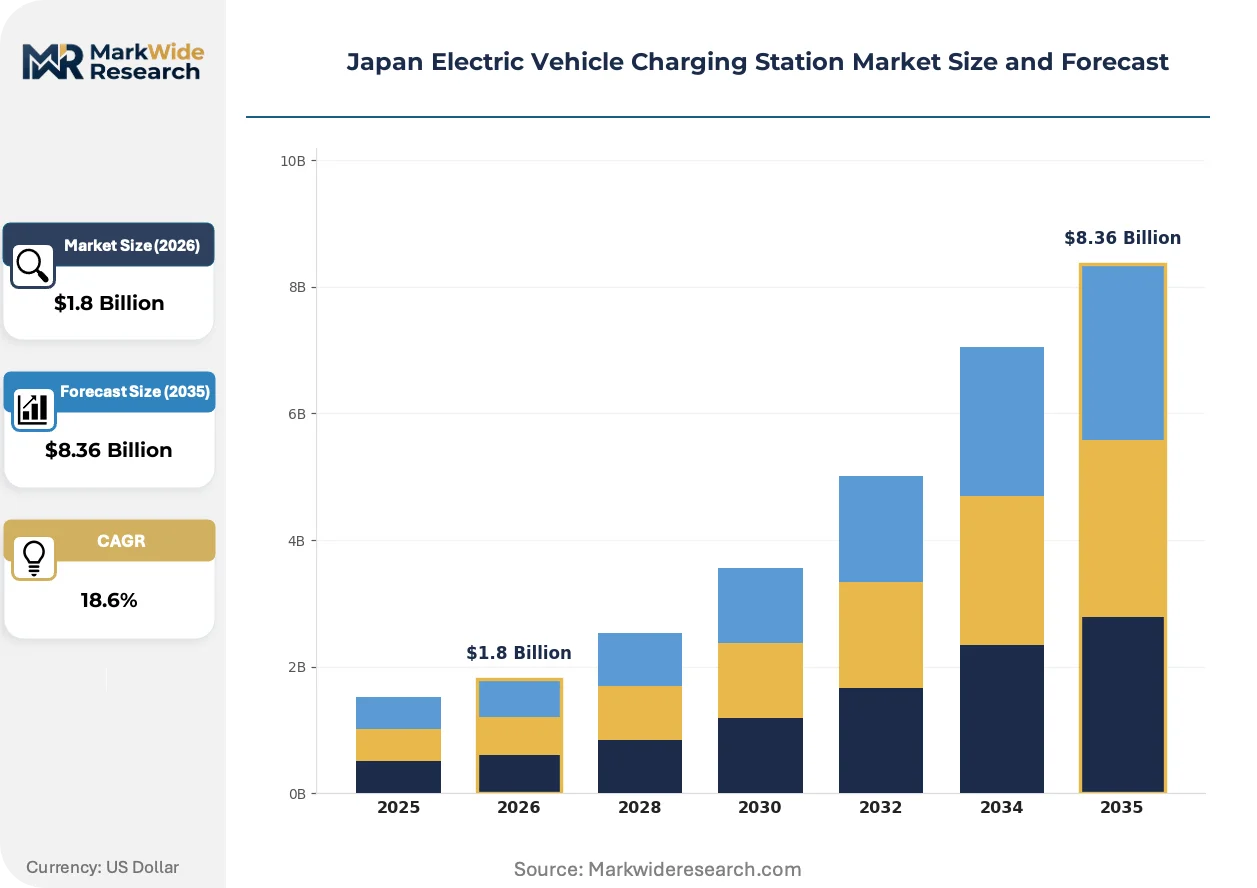
Silicon carbide power electronics are compressing charger footprints while METI subsidy frameworks accelerate highway corridor deployment. Fleet electrification mandates from taxi and logistics operators concentrate demand in Kanto and Kansai metropolitan zones.
Growth Catalysts
- Building Code Revisions:The Ministry of Land, Infrastructure, Transport and Tourism mandates EV-ready electrical capacity in new commercial structures above specified floor areas, expanding addressable infrastructure stock.
- Fleet Electrification Mandates:Taxi and delivery operators across Tokyo and Osaka metropolitan corridors are converting vehicle rosters, creating concentrated demand for DC fast charging hubs.
- Silicon Carbide Transition:Wide-bandgap semiconductors enable higher-efficiency power conversion, reducing cooling requirements and site preparation costs for ultra-fast installations.
Market Restraints
- Land Scarcity in Urban Cores:Tokyo and Osaka face severe site availability constraints, elevating real estate costs and complicating grid connection logistics for high-power equipment.
- Grid Interconnection Queues:Utility-scale power upgrades for 350 kW+ installations face 18-24 month approval timelines from regional electricity transmission operators.
- Import Dependency for Power Modules:Domestic silicon carbide substrate supply remains limited, exposing charger manufacturers to overseas foundry concentration risks.
Strategic Opportunities
- Hokkaido and Tohoku Highway Corridors:METI subsidies covering two-thirds of installation costs in remote regions create first-mover advantages for intercity charging networks.
- Wireless Fleet Depots:Automated alignment systems justify premium hardware costs for bus and taxi fleets operating fixed-route schedules with minimal dwell time.
- Vehicle-to-Grid Integration:Bidirectional charging protocols enable fleet operators to monetize battery assets through grid stabilization services under emerging utility tariffs.
Industry Challenges
- Certification Timeline Compression:CHAdeMO protocol updates and PSE electrical safety recertification cycles delay product launches as standards evolve for higher-power outputs.
- Power Electronics Talent Scarcity:Shortage of engineers with silicon carbide inverter design expertise constrains product development velocity for domestic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Electric Vehicle Charging Station Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charger Type: AC Slow, DC Fast, Wireless, Ultra-Fast, Portable Installation Environment: Public Parking Lots, Commercial Buildings, Residential Complexes, Fleet Depots, Highway Service Areas Connector Standard: CHAdeMO, Type 1 CCS, Type 2 CCS, Tesla Supercharger, J1772 End User: Private Vehicle Owners, Corporate Fleets, Taxi Operators, Government Agencies, Car Sharing Services |
| Companies Covered | ABB Ltd, Delta Electronics Inc, Toyota Connected Corporation, ENECHANGE Ltd, Schneider Electric SE, e-Mobility Power Inc, NEC Telecommunication and Information Technology Ltd, Tesla Inc, Hitachi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Electric Vehicle Charging Station Market Trends and Innovations
Semiconductor material transitions and municipal electrification mandates are restructuring competitive requirements. Charging infrastructure now functions as grid-interactive assets rather than passive loads.
Silicon carbide MOSFETs enable 350 kW+ outputs from compact cabinet designs. Highway operators and urban fleet depots are adopting these modules to minimize site footprint. This technology is overtaking conventional silicon IGBTs in premium charger segments where space constraints dominate site selection.
METI subsidy frameworks now require interoperability certification and open-network access as conditions for reimbursement. This policy shift prevents proprietary network lock-in and forces hardware vendors toward standardized payment and remote monitoring protocols. Highway corridor deployments face the strictest compliance timelines.
Fleet procurement now favors long-term service contracts bundling hardware, maintenance, and energy management. Taxi and logistics operators are displacing capital purchase models with availability-based agreements. This shift concentrates vendor selection around operational uptime guarantees rather than unit cost.
Japan Electric Vehicle Charging Station Market Segmentation
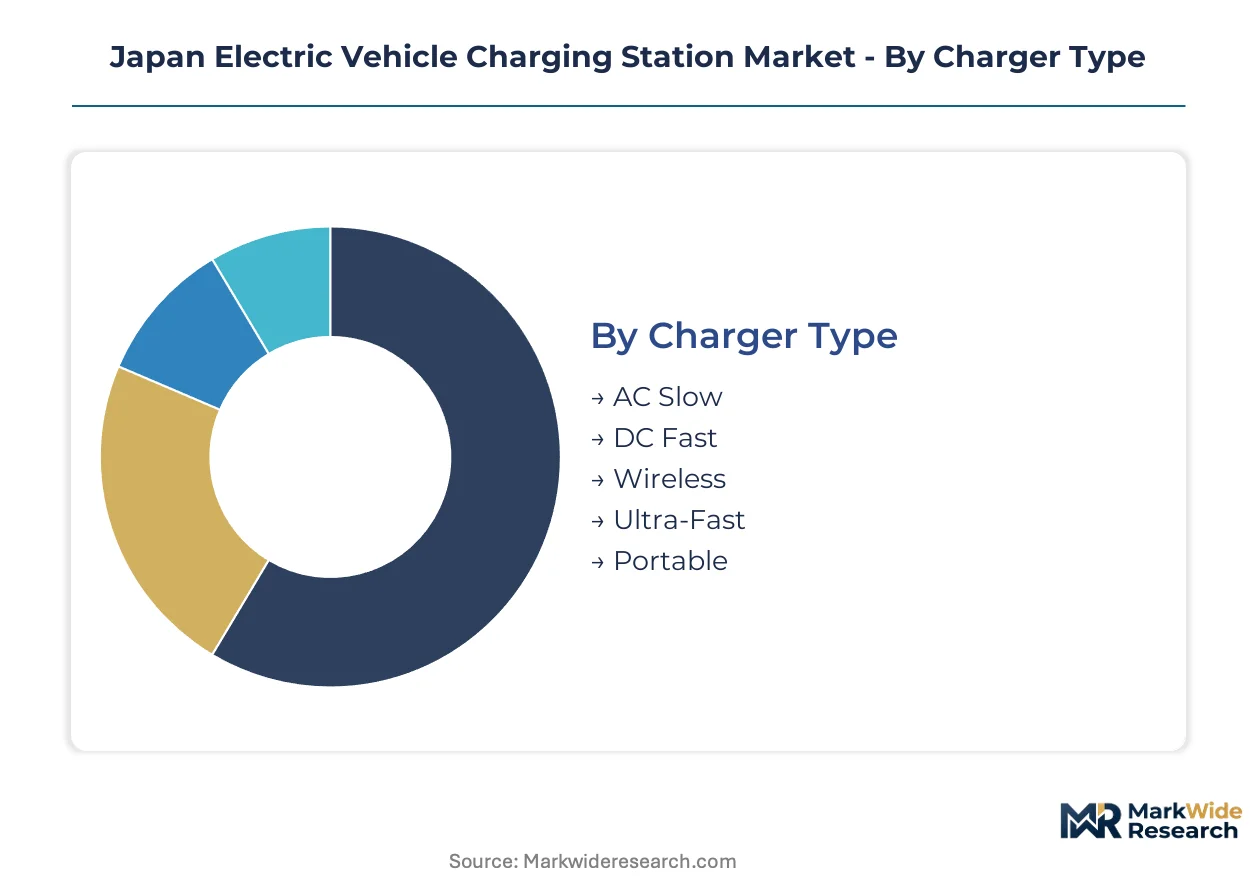
Charger configuration and site placement determine capital deployment patterns across Japan's EV infrastructure buildout. Installation environment and connector standards fragment procurement requirements, while end-user concentration shapes utilization economics and payback timelines.
Charger Type:
Capital intensity escalates sharply from residential AC units to highway-grade ultra-fast systems requiring dedicated substations and liquid cooling infrastructure.
- AC Slow:Single-phase or three-phase alternating current systems deliver 3-22 kW through onboard vehicle inverters. Residential complexes in Tokyo's 23 wards and Osaka's central districts absorb steady deployment volumes as building code mandates expand electrical rough-in requirements.
- DC Fast:Direct current systems bypass onboard conversion to deliver 50-150 kW through rectified power electronics. Fleet depots along the Tomei and Meishin expressway corridors concentrate procurement where taxi and logistics operators electrify vehicle rosters under METI subsidy frameworks.
- Wireless:Inductive charging pads transfer power through magnetic resonance without physical connectors. Pilot installations at municipal bus terminals in Nagoya and Sapporo test automated alignment for fixed-route operations with minimal dwell windows.
- Ultra-Fast:350 kW+ outputs from silicon carbide power modules enable sub-15-minute replenishment cycles. Highway service areas between Tokyo and Osaka anchor deployment where grid interconnection upgrades justify premium hardware costs.
- Portable:Mobile AC units provide emergency roadside assistance and temporary event coverage. Rural prefectures in Tohoku leverage these systems to bridge infrastructure gaps pending permanent installations.
DC Fast absorbs the bulk of installed capacity; Ultra-Fast is expanding most quickly.
Installation Environment:
Site acquisition costs and grid connection complexity stratify deployment economics, with highway corridors commanding multiples of urban parking lot investments.
- Public Parking Lots:Surface and structured parking facilities in commercial zones integrate charging as amenity infrastructure. Municipalities in Yokohama, Kawasaki, and Fukuoka mandate electrification percentages for new and retrofitted facilities.
- Commercial Buildings:Office towers and retail complexes above specified floor areas face EV-ready electrical capacity mandates from the Ministry of Land, Infrastructure, Transport and Tourism. Tokyo's Marunouchi and Osaka's Umeda districts lead retrofit activity.
- Residential Complexes:Multi-unit dwellings deploy shared AC infrastructure where individual metering proves uneconomical. Condominium associations in dense urban wards negotiate bulk procurement to minimize per-unit installation costs.
- Fleet Depots:Dedicated facilities for taxi, delivery, and bus operators centralize high-utilization charging assets. Predictive scheduling systems from Toyota Connected optimize asset turnover where vehicle telematics integrate with depot management platforms.
- Highway Service Areas:Expressway rest stops anchor intercity charging networks with 24-hour accessibility requirements. METI subsidies covering two-thirds of installation costs accelerate deployment along Hokkaido and Tohoku corridors where traffic density supports limited site viability.
Fleet Depots concentrate the highest utilization rates; Highway Service Areas attract the steepest subsidy-driven expansion trajectory.
Connector Standard:
Protocol certification requirements and vehicle fleet composition determine hardware procurement specifications across installation categories.
- CHAdeMO:Japan-origin DC fast charging protocol with bidirectional power flow capability. Domestic OEM vehicle fleets and highway corridor infrastructure anchor demand where JIS certification mandates govern interoperability.
- Type 1 CCS:Combined charging system variant for North American-market vehicles imported to Japan. Port facilities and diplomatic vehicle fleets generate limited but stable procurement volumes.
- Type 2 CCS:European-standard combined charging system gaining traction among premium import brands. Metropolitan dealer networks and luxury residential developments in Minato-ku and Chuo-ku favor this specification.
- Tesla Supercharger:Proprietary connector for Tesla vehicle ecosystem. Destination charging at hotels and retail complexes targets high-net-worth vehicle owners with network-exclusive access models.
- J1772:North American AC charging standard for Level 1 and Level 2 applications. Import vehicle compatibility requirements sustain niche demand in specialized fleet and residential segments.
CHAdeMO retains dominant installed base; Type 2 CCS is gaining share fastest among new premium installations.
End User:
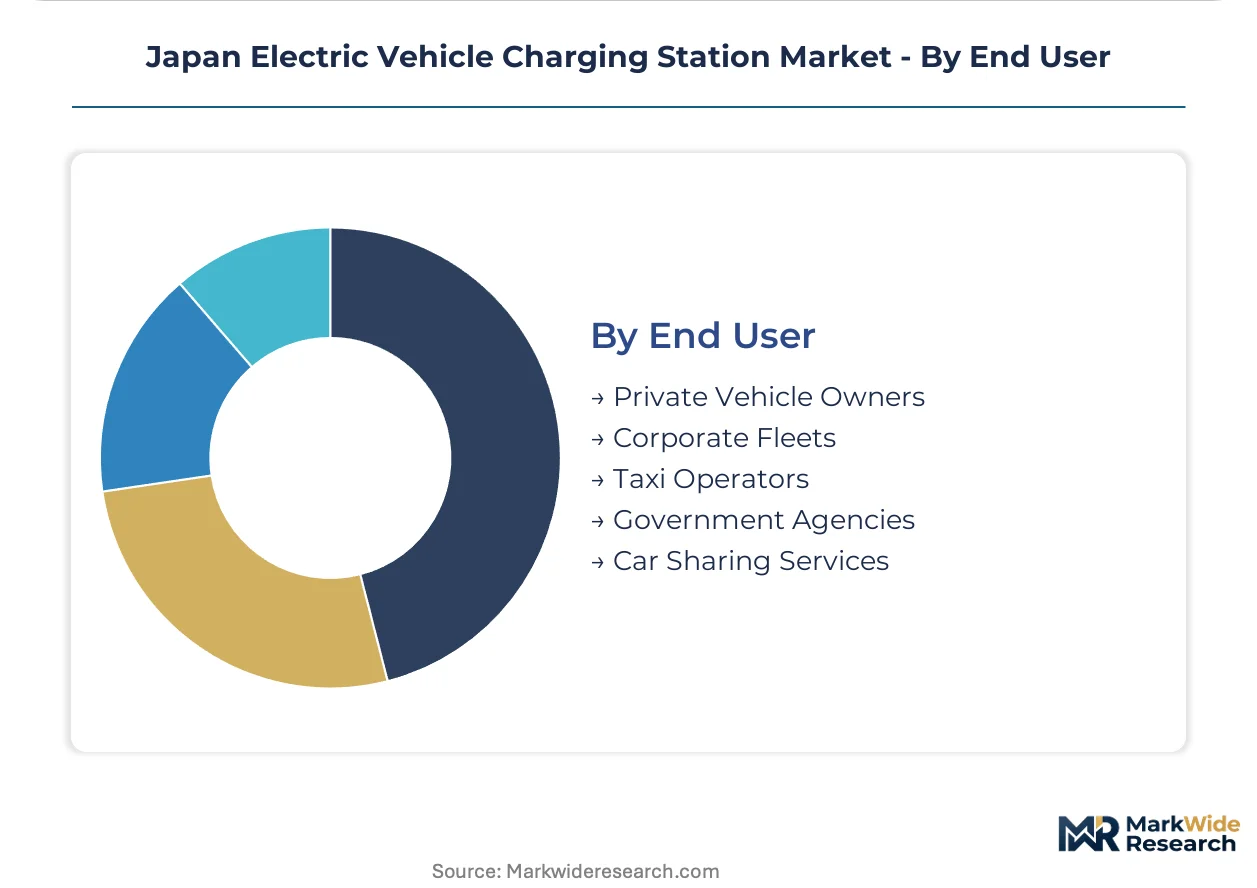
Utilization patterns and contract structures diverge sharply between individual consumers and institutional fleet operators.
- Private Vehicle Owners:Individual consumers utilizing residential, workplace, and public charging assets. Subscription pricing models and roaming network access dominate procurement preferences where interoperability reduces friction.
- Corporate Fleets:Enterprise vehicle pools for sales, service, and executive transport functions. Long-term service contracts bundling hardware, maintenance, and energy management displace capital purchase models.
- Taxi Operators:High-mileage urban transport fleets with stringent uptime requirements. Tokyo and Osaka taxi associations negotiate centralized procurement to standardize depot infrastructure and driver training protocols.
- Government Agencies:Municipal and national fleet electrification mandates drive procurement through public tender processes. Prefectural governments prioritize rural coverage expansion to satisfy universal service obligations.
- Car Sharing Services:Short-term rental operators requiring distributed urban charging access. Point-to-point trip models concentrate demand in dense residential-commercial zones where parking scarcity elevates site costs.
Corporate Fleets anchor contract value; Taxi Operators are climbing the fastest as electrification deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's EV charging infrastructure concentrates in metropolitan corridors where fleet operators and commercial real estate developers drive deployment density.
Kanto/Tokyo
Taxi electrification mandates and Marunouchi district commercial retrofits absorb the majority of DC fast charger procurement. METI subsidy frameworks accelerate highway corridor installations along the Tomei Expressway. Fleet depots in Shinagawa and Ota wards integrate predictive scheduling systems with vehicle telematics platforms.
Kansai/Osaka
Logistics operators electrify delivery rosters across the Keihanshin industrial zone, concentrating demand for high-utilization charging hubs. The Ministry of Land, Infrastructure, Transport and Tourism mandates EV-ready electrical capacity in new commercial structures above specified floor areas. Umeda district office towers anchor retrofit activity where grid interconnection upgrades justify premium hardware investments.
Chubu/Nagoya
Automotive supplier clusters and Toyota's headquarters proximity create integrated charging-vehicle ecosystem trials. Municipal bus terminals pilot wireless charging pads with automated alignment systems for fixed-route operations. Nagoya City implements parking-space electrification mandates that diverge from Tokyo and Osaka compliance requirements.
Hokkaido
Intercity highway networks between Sapporo and Asahikawa attract METI subsidies covering two-thirds of installation costs in remote regions. Limited traffic density constrains site viability, favoring portable AC units as bridge infrastructure. Prefectural government procurement prioritizes rural coverage expansion to satisfy universal service obligations.
Kyushu
Industrial port facilities and semiconductor manufacturing campuses generate stable demand for fleet charging infrastructure. Fukuoka municipal mandates require electrification percentages for new and retrofitted parking facilities. Regional electricity transmission operators manage 18-24 month approval timelines for utility-scale power upgrades.
Japan Electric Vehicle Charging Station Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium ultra-fast hardware commanding concentrated vendor relationships while standardized AC units fragment procurement. The market structure tiers around three strategic archetypes: heavy-industrial power electronics specialists leveraging traction in grid-scale infrastructure, electronics contract manufacturers with captive component sourcing advantages, and automaker-affiliated service platforms integrating vehicle telematics. Competitive moves concentrate on silicon carbide power module transitions and long-term service contract bundling to displace capital purchase models.
Within the heavy-industrial tier, ABB Ltd and Hitachi anchor positions where utility-scale grid connections and cooling infrastructure create barriers to entry. Delta Electronics Inc exemplifies the manufacturing-scale archetype through in-house magnetics production capabilities. Toyota Connected Corporation occupies the automaker-integrated position, enabling predictive charge scheduling through tight vehicle telematics ecosystem alignment.
| Leading Market Players |
|---|
| ABB Ltd |
| Delta Electronics Inc |
| Toyota Connected Corporation |
| ENECHANGE Ltd |
| Schneider Electric SE |
| e-Mobility Power Inc |
| NEC Telecommunication and Information Technology Ltd |
| Tesla Inc |
| Hitachi |
| Others |
Pricing and Supply Chain Analysis
Fleet procurement concentration among Tokyo and Osaka taxi operators anchors contract-based pricing with availability-based service agreements displacing capital purchase models. This buyer archetype consolidation compresses hardware margins while elevating long-term service contract values across DC fast and ultra-fast charger segments.
Pricing Analysis
High-volume AC residential units trade on thin hardware margins against concentrated DC fast and ultra-fast deployments capturing service-attachment premiums. Price differentiation hinges on CHAdeMO certification tier and silicon carbide power module integration grade. Cost compression in standard AC tiers intensifies as Delta Electronics and contract manufacturers exploit captive magnetics production. Municipal fleet operators exhibit highest price sensitivity; highway corridor operators under METI subsidy frameworks absorb premium hardware costs.
Supply Chain Analysis
Power electronics engineering talent scarcity in Japan and Taiwan constrains silicon carbide inverter design velocity for domestic charger manufacturers. Substrate supply concentrates in Japan, the United States, and Germany, with foundry capacity for wide-bandgap semiconductors tethered to overseas concentration risks. Raw material dependencies span silicon carbide wafers, liquid cooling components, and high-frequency magnetics. Single-source vulnerability for SiC substrates exposes lead time volatility. Distribution runs through heavy-industrial equipment channels and direct fleet procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's EV charging infrastructure is consolidating around a vertical-integration race where silicon carbide power module sourcing and in-house magnetics production determine cost position. Control over upstream semiconductor supply and downstream fleet service contracts represents the decisive competitive lever.
For Market Incumbents: Cement grid-interconnection capabilities and utility-scale project execution expertise as defensive moats against manufacturing-scale entrants from Taiwan and China. Deepen backward integration into silicon carbide substrate supply through foundry partnerships or captive wafer sourcing. METI subsidy compliance complexity and CHAdeMO protocol certification timelines protect incumbent positions.
For New Entrants and Emerging Players: METI subsidies covering two-thirds of installation costs in Hokkaido and Tohoku highway corridors open a window for first-mover intercity network buildouts. Wireless charging pilot deployments at municipal bus terminals in Nagoya and Sapporo offer penetrable technology entry points. Target fleet depot service contracts with predictive maintenance software bundling.
For Investors and Strategic Acquirers: Distressed-cycle entries favor power electronics specialists with silicon carbide design capabilities in Japan's Chubu industrial corridor. Long-term viability centers on vendors securing fleet operator offtake agreements under availability-based contracting. Watch METI subsidy renewal trajectories and CHAdeMO protocol evolution as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Integration | Wide-bandgap semiconductors from ABB and Hitachi compress charger footprints while reducing cooling infrastructure costs. |
| Fleet Service Contract Bundling | Availability-based agreements with Tokyo taxi operators displace capital purchase models and lock in recurring revenue streams. |
| Highway Corridor Network Expansion | METI subsidy capture along Tomei and Meishin expressways accelerates intercity charging infrastructure deployment timelines. |
| Wireless Charging Pilot Scaling | Automated alignment systems at Nagoya municipal bus terminals test fixed-route fleet applications with minimal dwell windows. |
| Vehicle-to-Grid Protocol Development | Bidirectional charging integration with Toyota Connected telematics enables battery asset monetization through grid stabilization services. |
Research Methodology
Independent corroboration across METI subsidy disbursement records, regional electricity transmission operator interconnection queues, and fleet operator procurement contracts underwrites the qualitative findings. Primary interviews with charging hardware procurement managers at taxi associations, power electronics engineering directors at industrial equipment manufacturers, and utility planning officers at Tokyo Electric Power and Kansai Electric Power combined with secondary validation from JIS standards documentation, CHAdeMO protocol certification databases, and building code revision filings from the Ministry of Land, Infrastructure, Transport and Tourism. Bottom-up installation volume estimates and top-down infrastructure investment forecasts triangulate market sizing.
Rate-of-change decomposition across charger type, installation environment, connector standard, and end-user segmentation dimensions structures the analytical framework. CAGRs derive from segment-level deployment trajectories weighted by METI subsidy allocation patterns and fleet electrification mandate timelines. Modeled inputs incorporate silicon carbide power module adoption curves, grid interconnection approval velocity, and municipal ordinance proliferation across Tokyo, Osaka, and Nagoya.
Caveats apply where METI subsidy renewal decisions, CHAdeMO protocol update cycles, or silicon carbide substrate supply disruptions could materially shift the outlook. Forecasts reflect assumptions about fleet electrification deadlines and building code enforcement intensity. A small set of named triggers—subsidy framework revisions, semiconductor export restrictions, and regional grid upgrade delays—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
North America Wireless Charging Market
Electric Vehicle Charging
United States Electric Vehicle Charging Systems and Equipment Market
Electric Vehicle Charging
Electric Vehicle Grid Integration Solutions Market
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Multi-Brand Universal Home Charging Pile Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
EV Battery Rental and Swapping Market
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
EV Charging Management Software Platform Market