
 North America CHP Market | 2026-2036
North America CHP Market Size, Share, and Industry Trends Forecast 2026-2036
North America CHP Market Analysis
Modular CHP packaging is realigning how industrial buyers evaluate capital deployment against operational flexibility. Siemens Energy leverages its turbine manufacturing scale to dominate large-scale installations across the United States. FuelCell Energy anchors its position through specialized fuel cell technology for institutional and commercial baseload applications. Wärtsilä competes by extending its reciprocating engine portfolio into containerized configurations that reduce site preparation timelines.
Combined heat and power systems simultaneously generate electricity and useful thermal energy from a single fuel source, typically achieving total system efficiencies of 65-80% through integrated turbine, engine, or fuel cell prime movers. Gas turbine technology leads the North American installed base due to its compatibility with high-pressure steam demands in refining and chemical processing. Reciprocating engine installations represent the fastest-growing technology segment as data centers and healthcare facilities prioritize black-start capability and rapid ramp rates. The industrial end-user category occupies the deepest margin pools, though commercial and institutional buyers are reshaping procurement patterns through energy-as-a-service contracting models.
The Environmental Protection Agency administers CHP partnership programs that certify system efficiency benchmarks and streamline environmental permitting for qualifying projects. The Federal Energy Regulatory Commission shapes market access through interconnection standards and wholesale compensation rules for behind-the-meter generation. State-level public utility commissions in California, New York, and Texas impose divergent standby tariff structures that directly alter project economics. Stakeholders must monitor how evolving carbon border adjustments and natural gas price volatility alter the dispatch hierarchy between CHP assets and grid-purchased power.
Market Dynamics
The Inflation Reduction Act's clean heat and power tax credits are compressing payback periods for fuel cell and gas turbine deployments, forcing industrial buyers to recalculate capital deployment timelines against operational flexibility trade-offs.
Growth Catalysts
- IRA Tax Credits:The Inflation Reduction Act's investment tax credits for clean heat and power slash effective capital costs for qualifying CHP systems, accelerating deployment timelines across Texas and California industrial corridors.
- Grid Volatility Hedging:Refining and chemical processing facilities in the Gulf Coast are expanding on-site generation capacity to insulate operations from transmission congestion and demand charge spikes.
- Carbon Mandate Convergence:State-level clean energy standards in California, New York, and Massachusetts are creating overlapping compliance obligations that CHP systems satisfy through combined efficiency and emissions reductions.
Market Restraints
- Natural Gas Price Volatility:Input fuel cost swings compress operating margins for gas turbine operators, particularly in deregulated markets where spark spreads narrow during price spikes.
- Interconnection Queue Delays:Federal Energy Regulatory Commission interconnection standards create procedural bottlenecks that extend project commissioning timelines by months in congested transmission zones.
- Standby Tariff Friction:State public utility commissions in Texas and California impose divergent backup power charges that erode project economics for behind-the-meter generation.
Strategic Opportunities
- Data Center Load Growth:Hyperscale computing facilities across Virginia and Arizona are adopting reciprocating engine CHP for black-start capability and rapid ramp rates, opening a high-margin application segment.
- Energy-as-a-Service Models:Third-party ownership structures are penetrating commercial and institutional buyer segments that lack capital budgets for direct equipment purchases.
- Hydrogen-Ready Turbine Retrofits:Gas turbine manufacturers are engineering fuel-flexible platforms that future-proof installations against evolving carbon border adjustments and fuel blending mandates.
Industry Challenges
- Specialized Technician Scarcity:Fuel cell stack maintenance and turbine combustion tuning require certified field engineers, creating recruitment bottlenecks in secondary metro markets.
- Legacy System Integration:Brownfield industrial sites face mechanical and control interface complexities when retrofitting CHP into existing steam distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America CHP Market |
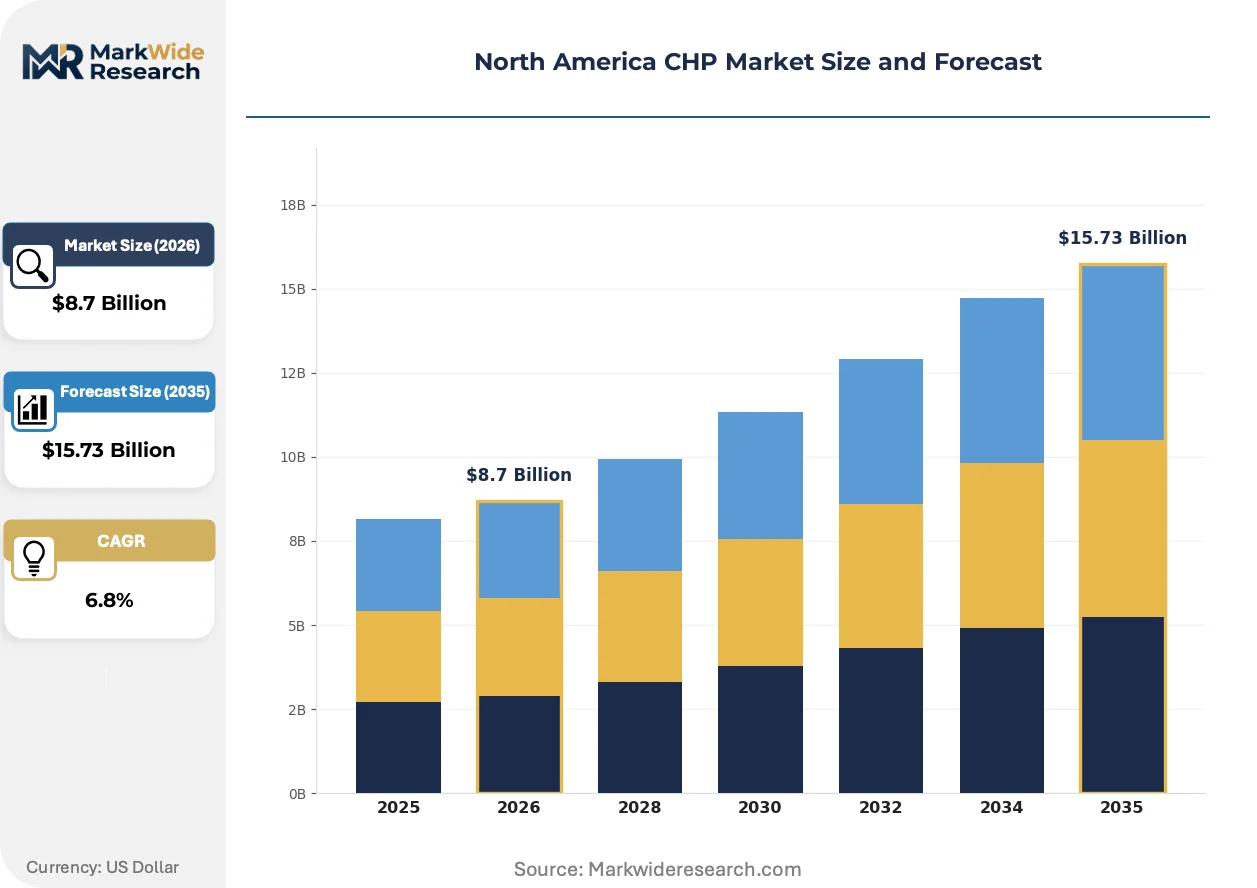
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro CHP, Large CHP, Modular CHP, Conventional CHP Technology: Gas Turbine, Steam Turbine, Reciprocating Engine, Fuel Cell End User: Industrial, Commercial, Residential, Institutional Installation Type: Onsite, District Energy, Cogenerated Facilities, Backup Systems |
| Companies Covered | ABB, Wärtsilä, Siemens Energy, FuelCell Energy, Kawasaki Heavy Industries, GE Vernova, Veolia, Tecogen, Capstone Turbine Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America CHP Market Emerging Trajectories
Modular packaging and containerized configurations are compressing site preparation timelines and reshaping how buyers evaluate deployment speed against customization depth.
Reciprocating engine technology is electrifying backup power strategies for mission-critical facilities. These systems deliver sub-ten-second start times and black-start autonomy that grid-tied alternatives cannot match. Healthcare networks and hyperscale data centers in Texas and Virginia are specifying engine-based CHP as primary resilience infrastructure, compressing procurement cycles for traditional standby generator sets.
The Environmental Protection Agency's CHP partnership certification program is tightening efficiency benchmarks for environmental permitting streamlining. Industrial developers now design systems explicitly to hit these thresholds, altering equipment sizing and thermal load matching calculations. Refining and chemical processing installations in the Gulf Coast corridor are most affected, with permitting timelines compressing for certified projects.
Energy-as-a-service contracting is displacing direct capital purchases among commercial and institutional buyers. Third-party developers assume equipment ownership and operational risk, capturing value through thermal output contracts and demand charge avoidance. University campuses and hospital systems in the Northeast corridor are driving this transition, prioritizing budget predictability over asset control.
North America CHP Market Segmentation
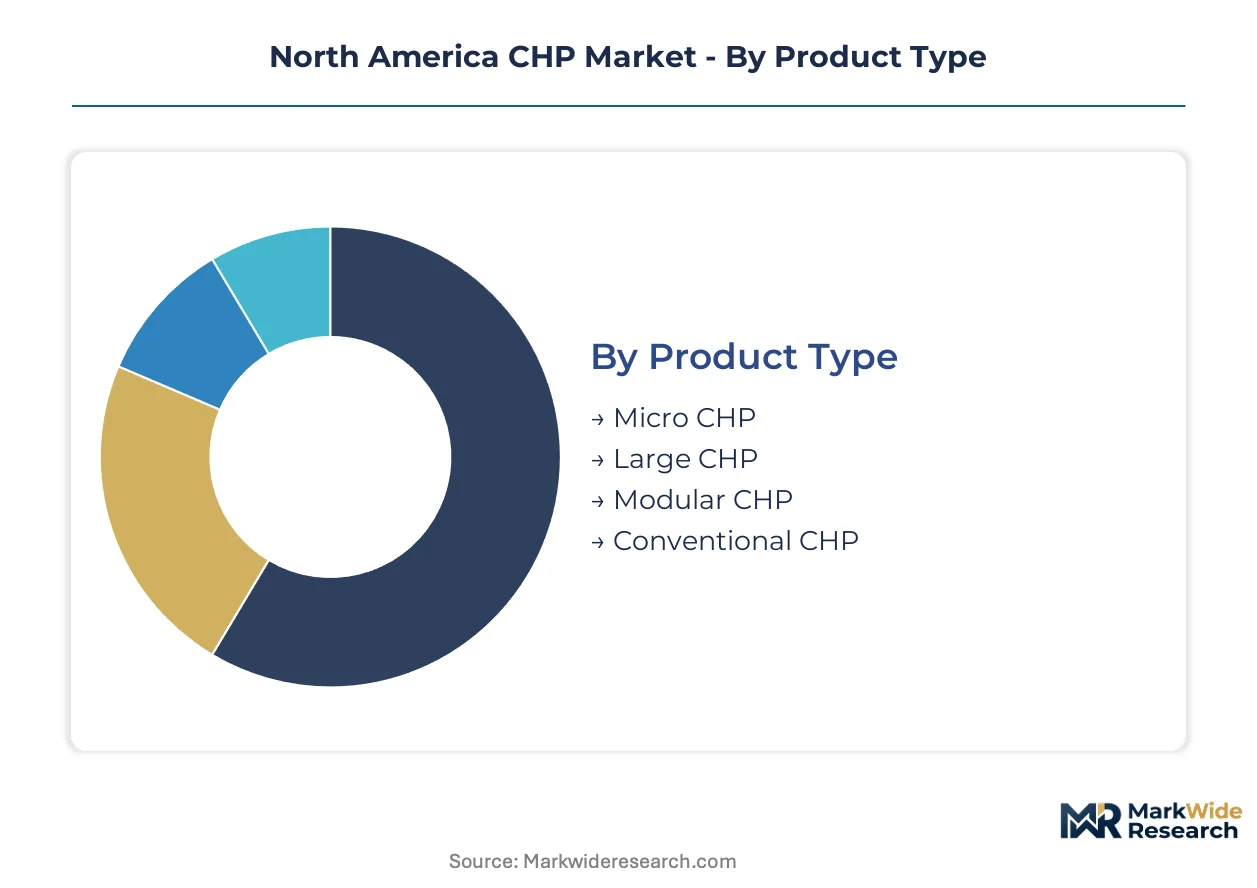
CHP procurement decisions pivot on thermal load profiles, fuel access, and resilience requirements that vary sharply across facility types. Buyers weight capital intensity against operational flexibility differently depending on scale and mission-criticality of their operations.
Product Type:
Scale of thermal demand and site constraints drive product selection more than fuel choice or technology preference.
- Large CHP:These systems exceed 50 MW electrical output and integrate directly with industrial process steam networks. Gulf Coast refineries and petrochemical complexes in Texas deploy these for baseload power and high-pressure steam cogeneration, capturing value from continuous thermal demand and grid independence.
- Modular CHP:Containerized configurations compress site preparation timelines and enable phased capacity expansion. Data centers across Virginia and Arizona specify these for rapid deployment and black-start resilience, trading some efficiency for deployment speed and operational flexibility.
- Micro CHP:Sub-50 kW units serve distributed residential and small commercial thermal loads.
- Conventional CHP:Custom-engineered systems dominate legacy industrial installations.
Volume sits with Large CHP; growth tilts toward Modular CHP.
Technology:
Fuel flexibility and ramp rate capabilities determine technology selection for buyers facing divergent grid interconnection rules and carbon compliance timelines.
- Gas Turbine:These prime movers achieve 35-40% electrical efficiency and integrate with heat recovery steam generators for combined-cycle operation. Refining and chemical processing facilities in Texas and California favor these for high-pressure steam demands, though natural gas price volatility compresses operating margins during supply shocks.
- Reciprocating Engine:Sub-ten-second start times and black-start autonomy suit mission-critical applications. Healthcare networks and hyperscale data centers specify these for resilience infrastructure, with installations expanding fastest across Virginia and Texas where grid reliability concerns intersect with computing load growth.
- Steam Turbine:Bottoming-cycle applications recover waste heat from industrial processes.
- Fuel Cell:Solid oxide and molten carbonate technologies qualify for IRA clean heat credits.
Installed base concentrates in Gas Turbine; steepest expansion trajectory belongs to Reciprocating Engine.
End User:
Capital availability and risk tolerance split procurement patterns between direct ownership and third-party structures.
- Industrial:Refining, chemicals, pulp and paper, and food processing operations deploy CHP for process steam and electricity cost hedging. Gulf Coast petrochemical corridors and Midwest manufacturing belts anchor demand, with facilities recalculating payback periods against IRA tax credit eligibility.
- Institutional:University campuses and hospital systems prioritize budget predictability over asset control. Northeast corridor buyers increasingly adopt energy-as-a-service contracting, transferring operational risk to third-party developers while securing thermal output guarantees.
- Commercial:Office complexes and retail distribution centers favor smaller-scale installations.
- Residential:Limited to micro-CHP pilot programs and high-end distributed generation.
Revenue depth pools in Industrial; contract innovation concentrates in Institutional.
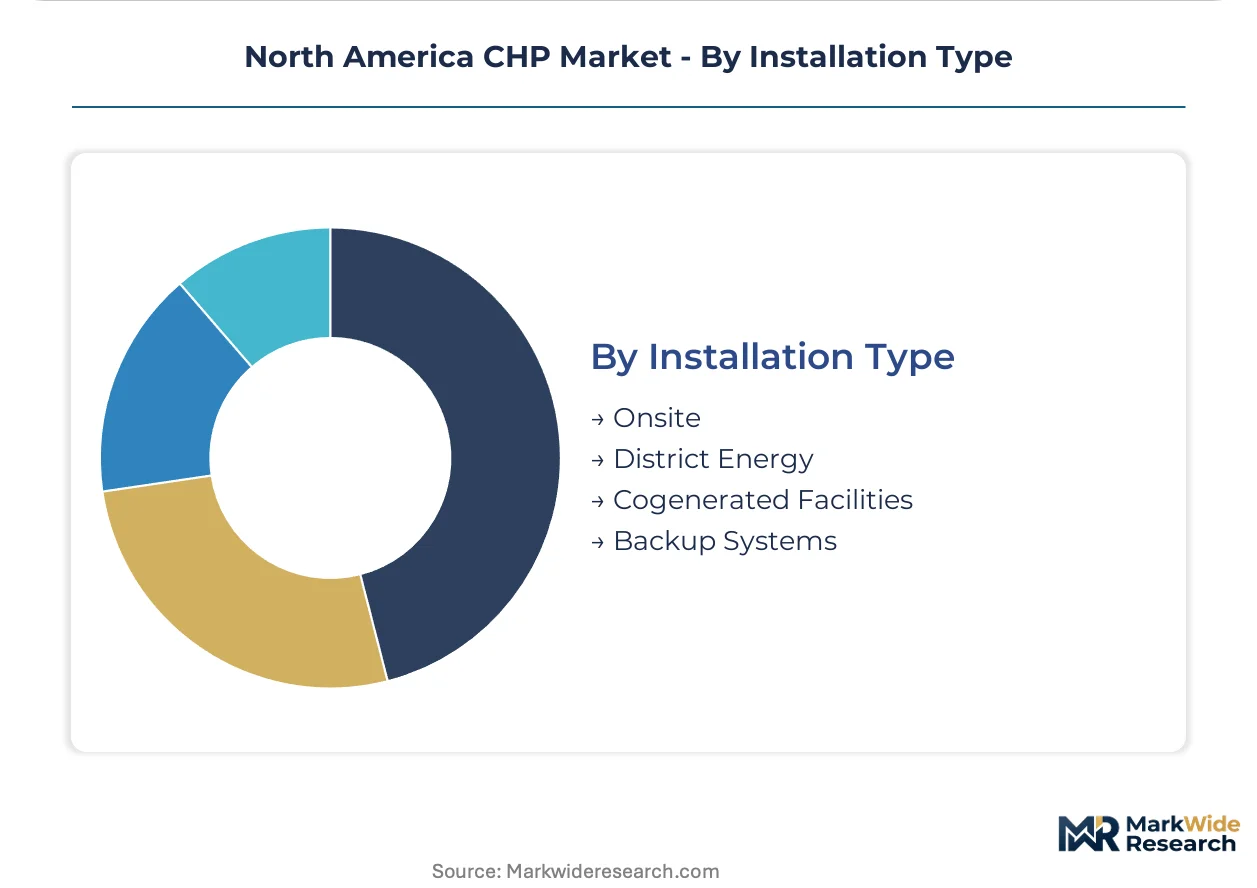
Installation Type:
Interconnection queue delays and standby tariff structures alter the economics of behind-the-meter versus grid-interactive configurations.
- Onsite:Behind-the-meter generation at industrial and commercial facilities insulates operations from transmission congestion and demand charge spikes. Texas and California installations face divergent standby tariff structures that directly alter project economics depending on utility commission jurisdiction.
- District Energy:Centralized thermal distribution serves multiple buildings through underground piping networks. University campuses and urban medical centers in the Northeast corridor leverage these for efficiency gains and carbon compliance, though capital requirements limit expansion.
- Cogenerated Facilities:Purpose-built plants serving single industrial sites or industrial parks.
- Backup Systems:Resilience-focused installations prioritize black-start capability over continuous operation.
Project volume clusters in Onsite; policy tailwinds favor District Energy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the United States while Canadian and Mexican markets absorb cross-border technology flows and specialized component manufacturing. The three-country configuration creates divergent deployment patterns shaped by distinct regulatory frameworks and industrial base compositions.
United States
Texas refineries and California data centers drive divergent technology demands across the largest national market. The Inflation Reduction Act channels investment tax credits toward fuel cell and gas turbine installations, compressing payback periods for qualifying projects. Gulf Coast petrochemical corridors anchor large-scale CHP deployment, while Virginia and Arizona hyperscale computing facilities adopt modular reciprocating engine configurations for black-start resilience.
Canada
Ontario manufacturing belts and Alberta oil sands operations sustain steady demand for industrial cogeneration systems. Provincial carbon pricing mechanisms in British Columbia and Quebec create compliance-driven procurement incentives that favor high-efficiency configurations. The Sarnia-Lambton chemical valley in Ontario represents the densest concentration of large-scale CHP infrastructure, serving polymer and petrochemical process steam requirements.
Mexico
Nuevo León industrial parks and Mexico City metropolitan manufacturing clusters absorb containerized CHP solutions for rapid deployment. Energy reform regulations enable behind-the-meter generation for qualified industrial consumers, altering project economics for multinational facility operators. The Bajío automotive corridor—spanning Guanajuato, Querétaro, and Aguascalientes—exhibits accelerating adoption as tier-one suppliers seek power cost hedging against grid instability.
North America CHP Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology segments, creating a tiered structure where scale advantages intersect with application-specific expertise. The vendor base clusters around three strategic archetypes: turbine manufacturers leveraging manufacturing scale, fuel cell specialists capturing clean energy premiums, and engine fabricators optimizing for modularity and deployment speed. Dominant competitive moves include portfolio diversification into hydrogen-ready platforms and geographic expansion through containerized product configurations that reduce site preparation dependencies.
Within the turbine manufacturing tier, Siemens Energy and GE Vernova occupy positions shaped by installed base scale and aftermarket service networks. Wärtsilä sits among engine specialists competing on fuel flexibility and rapid deployment timelines. FuelCell Energy anchors the electrochemical conversion segment, representing the fuel cell archetype that qualifies for federal clean energy tax credits.
| Leading Market Players |
|---|
| ABB |
| Wärtsilä |
| Siemens Energy |
| FuelCell Energy |
| Kawasaki Heavy Industries |
| GE Vernova |
| Veolia |
| Tecogen |
| Capstone Turbine Corporation |
| Others |
Supply Flow & Price Mechanics
Captive turbine manufacturing by Siemens Energy and GE Vernova anchors both supply security and pricing power across large-scale CHP deployments. This vertical integration shields prime mover costs from commodity volatility while compressing margins for third-party packagers competing on modular configurations.
Pricing Analysis
Margin tightening in modular CHP reflects compressed site preparation timelines and standardized containerized configurations. Project-based pricing dominates large industrial installations, while energy-as-a-service contracts transfer asset ownership risk to third-party developers. Price differentiation rests on IRA tax credit eligibility and black-start capability certification. Commercial buyers exhibit highest price sensitivity; data center operators prioritize resilience premiums over capital efficiency.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for gas turbines and reciprocating engines. Manufacturing concentrates in the United States, Germany, and Finland for prime movers; Mexico and Canada absorb cross-border component assembly. Nickel superalloys, precision castings, and power electronics constitute critical input dependencies. Single-source vulnerability sits with specialized fuel cell stack suppliers. Distribution runs through EPC contractors and regional service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America CHP market functions as a vertical-integration race where turbine manufacturers pursue downstream service revenue and fuel cell specialists seek captive hydrogen supply partnerships.
For Market Incumbents: Cement installed base advantages through aftermarket service contracts and hydrogen-ready turbine retrofits. Expand regional service hubs in Texas and California to counter technician scarcity. Defend against modular CHP entrants by accelerating containerized product launches.
For New Entrants and Emerging Players: Launch via energy-as-a-service platforms targeting institutional buyers in the Northeast corridor. Penetrate district energy retrofits where capital constraints block direct ownership. Exploit interconnection queue delays by offering rapid-deployment reciprocating engine solutions.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified energy conglomerates seeking fuel cell or hydrogen-ready capabilities. Long-term viability hinges on IRA credit durability and carbon border adjustment implementation. Monitor FERC interconnection rulemaking as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Turbine Retrofit | Future-proofs Gulf Coast installations against evolving fuel blending mandates. |
| Energy-as-a-Service Platform Launch | Captures institutional buyers prioritizing budget predictability over asset control. |
| Regional Service Hub Expansion | Addresses certified technician scarcity in secondary metro markets. |
| Fuel Cell Stack Manufacturing Scale-Up | Secures supply for IRA-eligible clean heat credit capture. |
| Reciprocating Engine Modular Packaging | Compresses data center deployment timelines in Virginia and Arizona. |
Methodological Framework
EPA CHP partnership filings, FERC interconnection databases, and EIA power plant records formed the secondary backbone for this analysis. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads validated equipment deployment timelines and procurement patterns. Bottom-up capacity installation tracking combined with top-down regulatory impact assessment across the analysis window.
Bottom-up modeling triangulated project-level data against macroeconomic drivers. Segmentation dimensions included generation capacity tier, fuel source technology, end-user industry vertical, and regional grid interconnection framework. CAGRs were derived from regression analysis of historical deployment trajectories against IRA tax credit phase-in schedules and natural gas price scenario modeling.
IRA credit modification, FERC interconnection standard revisions, and natural gas supply disruption are the dominant revision risks to modeled outputs. Forecasts reflect base-case assumptions regarding policy continuity and commodity price stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Global Ancillary Services Power Market
Power
Global UPS Market
Power
Saudi Arabia Power Market
Power
Germany Solar Inverter Market
Power
Global Hydraulic Turbine Market
Power
Electric Arc Furnaces Market
Power
LNG Power Barge Market
Power
Canada Power Market
Power
Brunei Power Market
Power
Europe Frequency Converter Market
Power
Static Synchronous Compensator (STATCOM) Market
Power
Oxy-Hydrogen Generators Market
Power
Doubly Fed Induction Generator (DFIG) Market
Power
Power Capacitors Market
Power
Norway Power Market
Power
Sudan Power Market