
 Stadium Security Market | 2026-2036
Stadium Security Market Size, Share, and Industry Trends Forecast 2026-2036
Stadium Security Market Intelligence
Municipal governments and university athletic departments is redrawing procurement priorities for stadium security infrastructure. Honeywell International Inc. leverages its building automation heritage to anchor integrated command-and-control installations. Dahua Technology competes aggressively on manufacturing scale for high-definition camera arrays. Axis Communications AB differentiates through open-architecture protocols that reduce vendor lock-in for venue operators.
Stadium security encompasses layered physical and digital protection systems designed to monitor, detect, and neutralize threats within large-capacity entertainment venues, typically integrating video analytics, access credentialing, and perimeter sensors operating at sub-second response thresholds. The primary purpose centers on preventing unauthorized entry, identifying prohibited objects, and enabling coordinated emergency evacuation of crowds exceeding fifty thousand occupants. CCTV Surveillance and Facial Recognition command the largest installed base, though Cloud-Based deployment models represent the fastest-expanding margin pool as venues seek to reduce on-site server capital. Access Control Systems remain mature with slower growth but generate recurring software maintenance revenue that sustains vendor profitability across multi-year contracts.
The U.S. Department of Homeland Security, the U.K. Home Office, and FIFA venue certification standards collectively shape product specifications and market access for stadium security suppliers across their respective jurisdictions. Compliance with these frameworks mandates specific screening throughput rates, data retention protocols, and interoperability requirements that filter which vendors qualify for major venue tenders. Stakeholders must monitor evolving AI governance rules that will determine whether facial recognition algorithms retain deployment permits in European and North American venues.
Market Dynamics
AI-driven threat detection algorithms are compressing response latencies from seconds to milliseconds across venue networks. This computational shift is forcing legacy camera-only installations into accelerated replacement cycles and rewiring vendor competitive advantage toward software-defined architectures.
Growth Catalysts
- FIFA Venue Certification Standards:Qatar's stadium construction program mandated integrated screening systems with sub-second throughput rates, creating template specifications now replicated across Middle Eastern and Asian venues.
- Edge Computing Architectures:On-device video analytics reduce bandwidth dependency and enable real-time facial recognition matching against watchlists without cloud round-trips.
- University Athletic Departments:Campus venues in the United States are retrofitting aging infrastructure following Title IX facility equity investments and expanded football program revenues.
Market Restraints
- Semiconductor Supply Concentration:Advanced image processing chips for 4K/8K camera arrays concentrate among Taiwanese foundries, exposing procurement timelines to geopolitical friction.
- GDPR Algorithmic Governance:The EU AI Act's biometric identification restrictions create compliance uncertainty for facial recognition deployments in European stadiums.
- Legacy System Interoperability:Analog CCTV infrastructure in aging venues requires costly signal conversion hardware to integrate with IP-based analytics platforms.
Strategic Opportunities
- Cloud-Based Deployment Models:Venue operators in Germany are piloting subscription-based security-as-a-service to eliminate on-premise server capital expenditure.
- Drone Detection Integration:Convergence of radar sensors with video analytics addresses emerging airspace threats above open-roof stadiums.
- India Smart Cities Mission:Municipal stadium upgrades under urban renewal programs create procurement pipelines for integrated command-and-control installations.
Industry Challenges
- Cybersecurity Skill Scarcity:Venue IT departments lack personnel trained to harden IoT sensor networks against ransomware targeting physical access systems.
- Multi-Vendor Integration Complexity:Open-architecture protocols reduce lock-in but require specialized system integrators to achieve sub-second interoperability between access control, video analytics, and perimeter sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stadium Security Market |
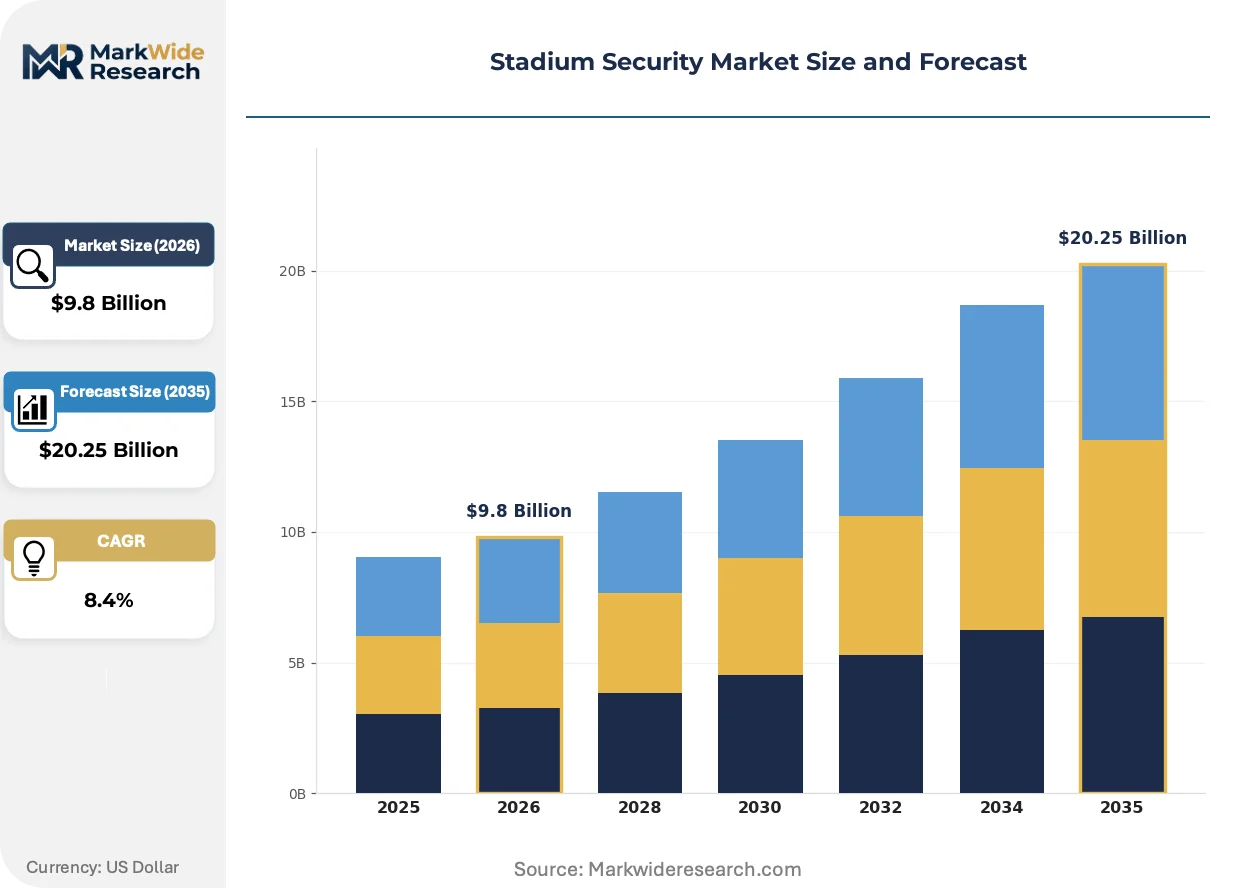
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Access Control Systems, CCTV Surveillance, Intrusion Detection, Metal Detectors, Facial Recognition, Biometric Scanners Application: Crowd Management, Threat Detection, Emergency Response, Perimeter Security, Credential Verification, Incident Reporting End User: Sports Venues, Concert Arenas, Convention Centers, Amusement Parks, Government Facilities, University Campuses Deployment Model: On-Premise, Cloud-Based, Hybrid Cloud, Mobile Security, Integrated Systems, Managed Services |
| Companies Covered | Honeywell International Inc., Dahua Technology, Avigilon Corporation, Bosch Security Systems, Cisco Systems Inc., Genetec Inc., Hikvision Digital Technology, NEC Corporation, Axis Communications AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stadium Security Market Strategic Shifts & Innovations
Computational imaging and federated learning architectures are redistributing intelligence across venue networks. These shifts compress hardware replacement cycles while elevating software and data engineering capabilities as primary vendor differentiators.
Millimeter-wave body scanners with automated threat recognition are supplanting manual pat-downs and metal detector portals at premium venue entry points. NFL and Premier League franchises are deploying these systems at main gates to sustain throughput above 600 spectators per lane per hour. This hardware transition is compressing the addressable market for conventional walk-through metal detectors while expanding recurring software licensing revenue for algorithm providers.
The EU AI Act's risk-based classification system for biometric identification is mandating algorithmic impact assessments and human-in-the-loop verification protocols. European venue operators must now document false positive rates and demographic parity metrics to retain deployment permits. Stadium security vendors are responding by engineering adjustable sensitivity thresholds and audit trail functionalities specifically for French, German, and Spanish compliance frameworks.
Consolidated purchasing through municipal procurement consortia is displacing individual venue RFP processes for mid-sized installations. State university systems in Texas and California are aggregating security infrastructure requirements across multiple campuses to extract volume pricing and standardized maintenance terms. This buyer-side consolidation is most visible in the United States, where public sector procurement rules favor multi-year master service agreements over discrete capital purchases.
Stadium Security Market Segmentation
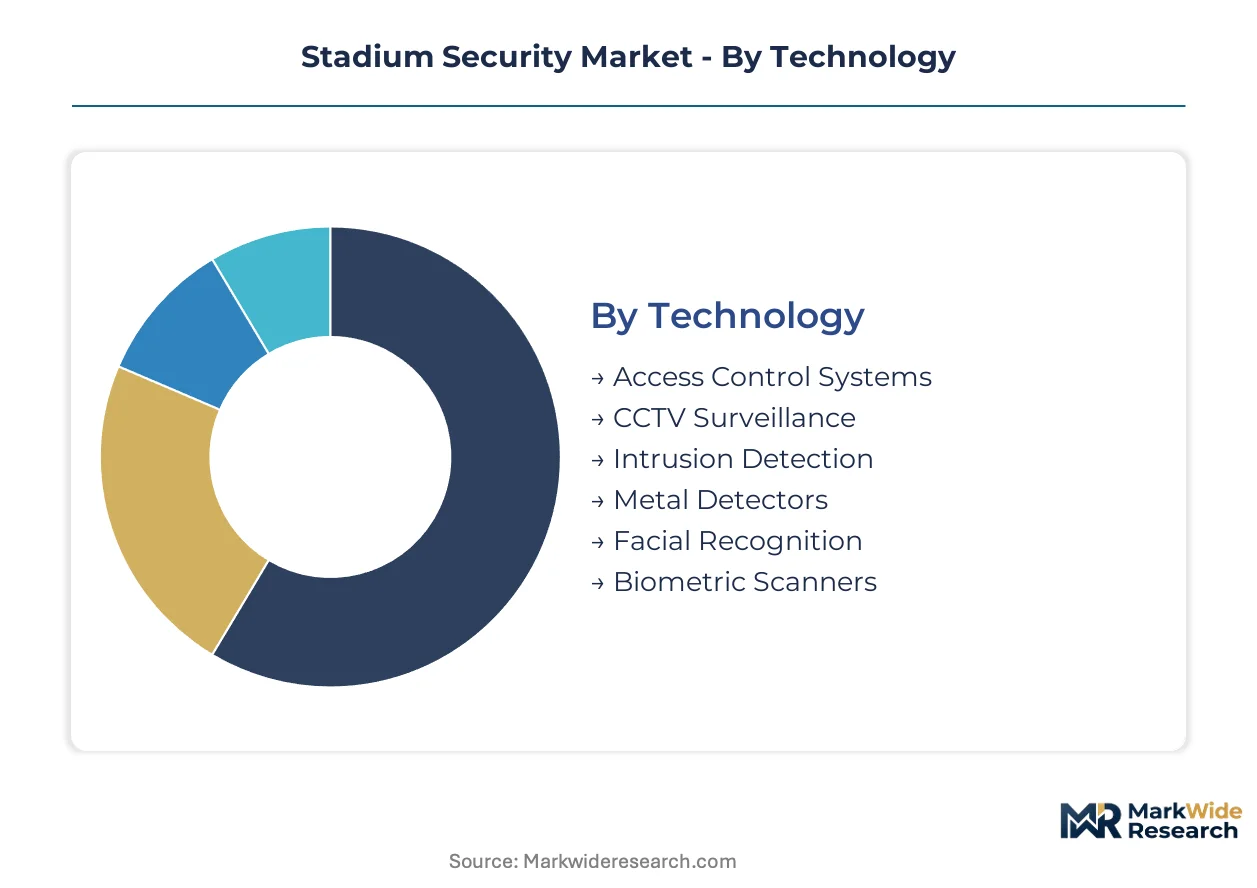
Stadium security procurement splits across technology generations, venue types, and operational models. Buyers optimize capital allocation differently across these dimensions, with cloud migration and AI integration reshaping vendor selection criteria.
Technology:
Geographic demand concentrates in domestic retrofit markets for mature systems, while facial recognition and biometric exports face GDPR and emerging AI governance barriers.
- Access Control Systems:Credential verification infrastructure combining RFID readers, turnstile gates, and mobile ticketing validation. Demand clusters in United States university athletic departments modernizing legacy physical access networks.
- CCTV Surveillance:High-definition camera arrays with edge analytics processing. Qatar's FIFA-mandated installations established throughput benchmarks now driving Middle Eastern procurement specifications.
- Intrusion Detection:Perimeter sensor networks with fiber-optic and radar-based detection.
- Metal Detectors:Walk-through and handheld screening portals for mass entry points.
- Facial Recognition:AI-powered biometric matching against watchlists with millisecond latency.
- Biometric Scanners:Fingerprint and iris verification for restricted zone access.
CCTV Surveillance holds the largest share; momentum sits with Facial Recognition.
Application:
Cost tiering separates premium venues deploying integrated threat detection from budget-constrained facilities relying on single-function systems.
- Threat Detection:AI-driven algorithms identifying weapons, unattended packages, and anomalous behavior patterns. NFL and Premier League franchises in the United States and England deploy these at main gates to sustain 600+ spectators per lane per hour.
- Crowd Management:Density monitoring and flow optimization analytics preventing crush incidents. German venue operators pilot these systems following Love Parade disaster compliance mandates.
- Emergency Response:Coordinated evacuation triggering and first-responder communication protocols.
- Perimeter Security:Layered boundary protection integrating physical barriers with sensor networks.
- Credential Verification:Ticket authentication and staff access validation workflows.
- Incident Reporting:Automated documentation and chain-of-custody protocols for security events.
Threat Detection commands premium pricing; Crowd Management is climbing the fastest as liability frameworks tighten.
End User:
Volume concentration favors sports venues with 50,000+ capacity, while convention centers and government facilities drive specialized customization requirements.
- Sports Venues:Professional and collegiate stadiums requiring sub-second screening throughput. Texas and California state university systems aggregate procurement across multiple campuses to extract volume pricing.
- Concert Arenas:Flexible configurations accommodating rapid load-in/load-out schedules. United Kingdom operators face specific licensing conditions from the Home Office regarding crowd safety certification.
- Convention Centers:Modular security architectures adapting to varying event footprints.
- Amusement Parks:Family-friendly screening protocols with minimal friction for guest experience.
- Government Facilities:Hardened specifications meeting federal security mandates.
- University Campuses:Dual-use infrastructure serving athletic and academic security needs.
Sports Venues generate the highest absolute revenue; University Campuses show steepest expansion trajectory following Title IX facility equity investments.
Deployment Model:
Margin structure differentiates capital-heavy on-premise installations from recurring-revenue cloud and managed service contracts.
- Cloud-Based:Subscription security-as-a-service eliminating on-site server capital. German venue operators pilot these models to convert fixed infrastructure costs to operational expenditure.
- Integrated Systems:Unified command-and-control platforms converging video, access, and perimeter data. Honeywell leverages building automation heritage to anchor these installations in North American municipal stadiums.
- On-Premise:Local server and storage infrastructure with full data sovereignty.
- Hybrid Cloud:Split processing between edge devices and remote analytics platforms.
- Mobile Security:Portable screening and communication units for temporary deployments.
- Managed Services:Outsourced monitoring and maintenance with guaranteed response SLAs.
Integrated Systems dominate current installed base; Cloud-Based deployment is gaining share fastest as venues seek to reduce on-site server capital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers of millimeter-wave screening systems export integrated command platforms to Qatar's FIFA venues, establishing specification templates now replicated across Middle Eastern procurement cycles.
United States
Texas and California state university systems aggregate security infrastructure requirements across multiple campuses to extract volume pricing. The Department of Homeland Security mandates specific screening throughput rates and data retention protocols that filter vendor qualification for municipal stadium tenders. Dallas-Fort Worth and Los Angeles metropolitan clusters anchor retrofit demand as aging venues modernize credential verification networks.
Germany
Venue operators in Munich and Berlin pilot subscription-based security-as-a-service models to convert fixed infrastructure costs to operational expenditure. The EU AI Act's biometric identification restrictions mandate algorithmic impact assessments and human-in-the-loop verification protocols for facial recognition deployments. Bavarian stadium clusters face specific compliance mandates following Love Parade disaster liability frameworks.
Qatar
FIFA venue certification standards mandated integrated screening systems with sub-second throughput rates during stadium construction programs. The national procurement authority established performance benchmarks now replicated across Saudi Arabian and Emirati venue tenders. Doha's Lusail Stadium complex anchors regional demand for converged video analytics and access credentialing platforms.
United Kingdom
Premier League franchises deploy millimeter-wave body scanners at main gates to sustain throughput above 600 spectators per lane per hour. The Home Office issues specific licensing conditions regarding crowd safety certification for concert arena operators. London's Wembley and Emirates Stadium clusters drive premium-tier demand for AI-driven threat detection algorithms.
India
Municipal stadium upgrades under the Smart Cities Mission create procurement pipelines for integrated command-and-control installations. The Bureau of Indian Standards issues technical specifications for video analytics interoperability in public venue networks. Maharashtra's Mumbai-Pune corridor and Karnataka's Bengaluru cluster anchor domestic demand as urban renewal programs accelerate.
Stadium Security Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with building automation heritage and specialized video surveillance manufacturers competing on manufacturing scale. The market structure concentrates around vendors capable of converging access control, video analytics, and perimeter sensors into unified platforms. Two strategic archetypes dominate: integrated systems providers leveraging cross-infrastructure software stacks, and component specialists supplying high-definition camera arrays and edge processing hardware. Competitive moves center on strategic partnerships with municipal procurement consortia and portfolio diversification into cloud-based deployment models.
Within the integrated systems tier, Honeywell International Inc. and Axis Communications AB exemplify contrasting approaches to vendor lock-in reduction. Honeywell leverages its building automation heritage to anchor municipal stadium installations in North America. Axis occupies a position emphasizing open-architecture protocols that reduce switching costs for venue operators managing multi-vendor environments. Dahua Technology represents the scale-driven archetype, competing aggressively on manufacturing volume for high-definition camera arrays deployed across Middle Eastern and Asian venues.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Dahua Technology |
| Avigilon Corporation |
| Bosch Security Systems |
| Cisco Systems Inc. |
| Genetec Inc. |
| Hikvision Digital Technology |
| NEC Corporation |
| Axis Communications AB |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Taiwanese foundries producing advanced image processing chips for 4K/8K camera arrays shapes both supply concentration and price floors for stadium security hardware. Scale economies in semiconductor fabrication compress margins for second-tier camera manufacturers while elevating pricing power for vendors with captive chip supply or long-term foundry contracts.
Pricing Analysis
Next-generation AI-powered threat detection systems command 40-60% price premiums over legacy camera-only installations, while prior-generation analog CCTV infrastructure trades at distressed valuations amid accelerated replacement cycles. Three-tier pricing structure across premium, standard, and economy levels separates FIFA-certified integrated platforms from municipal retrofit specifications and budget university deployments. Pricing pressure stems from semiconductor supply concentration exposing procurement timelines to geopolitical friction, particularly for venues requiring rapid deployment. University athletic departments exhibit highest price sensitivity due to Title IX facility equity budget constraints, whereas Qatar and Saudi Arabian FIFA venues demonstrate lowest sensitivity given sovereign infrastructure mandates.
Supply Chain Analysis
Taiwan anchors advanced image processing chip fabrication for 4K/8K camera arrays, while China dominates high-volume camera assembly and Germany specializes in millimeter-wave screening system engineering. Raw material dependencies span silicon wafers, rare earth elements for sensor components, and specialized optical glass for lens arrays. Supply chain risk centers on single-source vulnerability for leading-edge semiconductor nodes concentrated among two Taiwanese foundries. Distribution runs through municipal procurement consortia in Texas and California, systems integrators serving European venue operators, and direct government contracts across Middle Eastern stadium programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stadium security procurement is reconfiguring around service-attach revenue models, with cloud-based security-as-a-service and algorithm licensing expanding faster than hardware replacement cycles. Recurring software maintenance contracts now generate margin profiles that exceed capital equipment sales across multi-year venue agreements.
For Market Incumbents: Secure long-term foundry allocation agreements for image processing chips before capacity constraints intensify. Deepen backward integration into edge computing hardware to defend against software-defined entrants displacing legacy camera arrays. Prioritize certification investment for EU AI Act compliance to maintain European venue access as biometric governance tightens.
For New Entrants and Emerging Players: Anchor in Indian municipal stadium upgrades under Smart Cities Mission procurement pipelines, where integrated command-and-control demand outpaces established vendor presence. Target German security-as-a-service pilots converting fixed infrastructure costs to operational expenditure. Pursue channel partnerships with Texas and California state university procurement consortia as aggregation accelerates volume pricing leverage.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with cloud-based deployment models and algorithm licensing portfolios. Long-term viability favors platforms converging video analytics, access control, and perimeter sensors into unified software stacks. Monitor EU AI Act enforcement patterns as inflection indicator for facial recognition deployment permits and associated hardware demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Expansion | Recurring revenue from threat detection software exceeds hardware margins across NFL and Premier League venue contracts. |
| Foundry Partnership Securement | Long-term wafer supply agreements with Taiwanese producers insulate against semiconductor procurement delays. |
| EU AI Act Compliance Certification | Algorithmic impact assessment capabilities unlock continued facial recognition deployment in German and French stadiums. |
| Cloud Migration Enablement | Security-as-a-service architectures convert municipal stadium capital expenditure to operational budgets in Bavaria. |
| Drone Detection Integration | Radar-video convergence addresses emerging airspace threats above open-roof venues in Qatar and Saudi Arabia. |
Research Approach
Initial hypotheses were tested against primary input from stadium security directors, municipal procurement officers, university athletic department facility managers, and systems integration specialists, then refined through secondary validation. Primary fieldwork encompassed venue operator interviews across Texas, California, Qatar, and Germany procurement clusters. Secondary sources included FIFA venue certification standards, EU AI Act regulatory filings, U.S. Department of Homeland Security screening specifications, and municipal procurement database records. Bottom-up segment sizing triangulated against top-down market construction across technology, application, end-user, and deployment model dimensions.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within technology-generation replacement cycles and geographic procurement waves. Segmentation modeling spans access control systems, CCTV surveillance, facial recognition, and cloud deployment architectures, with end-user splits across sports venues, university campuses, and concert arenas. CAGRs derive from installed base growth, replacement cycle acceleration, and attach-rate expansion for software and services. Industry-specific inputs incorporate FIFA mandate propagation patterns, Title IX facility investment flows, and EU biometric governance enforcement trajectories.
Material uncertainties — semiconductor supply disruptions, EU AI Act biometric restrictions, and municipal budget cycles — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued FIFA specification adoption, cloud migration adoption curves, and edge computing hardware cost trajectories. Recalibration cycles align with material shifts in regulatory enforcement patterns, foundry capacity announcements, and sovereign stadium construction program awards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Security Product Integration Services Market
Security and Surveillance
Europe Rockfall Radar Market
Security and Surveillance
Alarm Monitoring Software Market
Security and Surveillance
Security System Integrators Market
Security and Surveillance
Security Operations Center Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Middle East Manned Security Services Market
Security and Surveillance
Home Security Solution Market
Security and Surveillance
Global Security Orchestration Market
Security and Surveillance
Specialized Threat Analysis and Protection Market
Security and Surveillance
North America Wireless Monitoring and Surveillance Market
Security and Surveillance
Threat Detection Systems Market
Security and Surveillance
APAC Security Testing Market
Security and Surveillance
Airport Security Market