
 United States Surveillance IP Camera Market | 2026-2036
United States Surveillance IP Camera Market Size, Share, and Industry Trends Forecast 2026-2036
United States Surveillance IP Camera Market Insights
Critical infrastructure operators are repositioning their surveillance procurement toward cyber-hardened IP cameras with onboard analytics. Bosch Security Systems leverages its German-engineered manufacturing base to sustain premium positioning in federal installations. Hanwha Vision America anchors its growth through American-assembled product lines that navigate Buy American compliance requirements.
Surveillance IP cameras are network-connected digital video capture devices transmitting encrypted footage over Ethernet or wireless protocols, typically supporting resolutions from 2MP to 8MP with H.265 compression for bandwidth efficiency. Their primary purpose is real-time security monitoring and forensic evidence collection across commercial, institutional, and governmental environments. Dome cameras dominate indoor retail and hospitality deployments where vandal resistance and discreet positioning matter, while bullet cameras occupy the fastest-growing outdoor perimeter security segment driven by industrial site expansion. Network technology leads the connectivity landscape as POE infrastructure becomes standard in new commercial construction, though Wi-Fi segments are gaining traction in residential retrofit applications where cabling costs prove prohibitive.
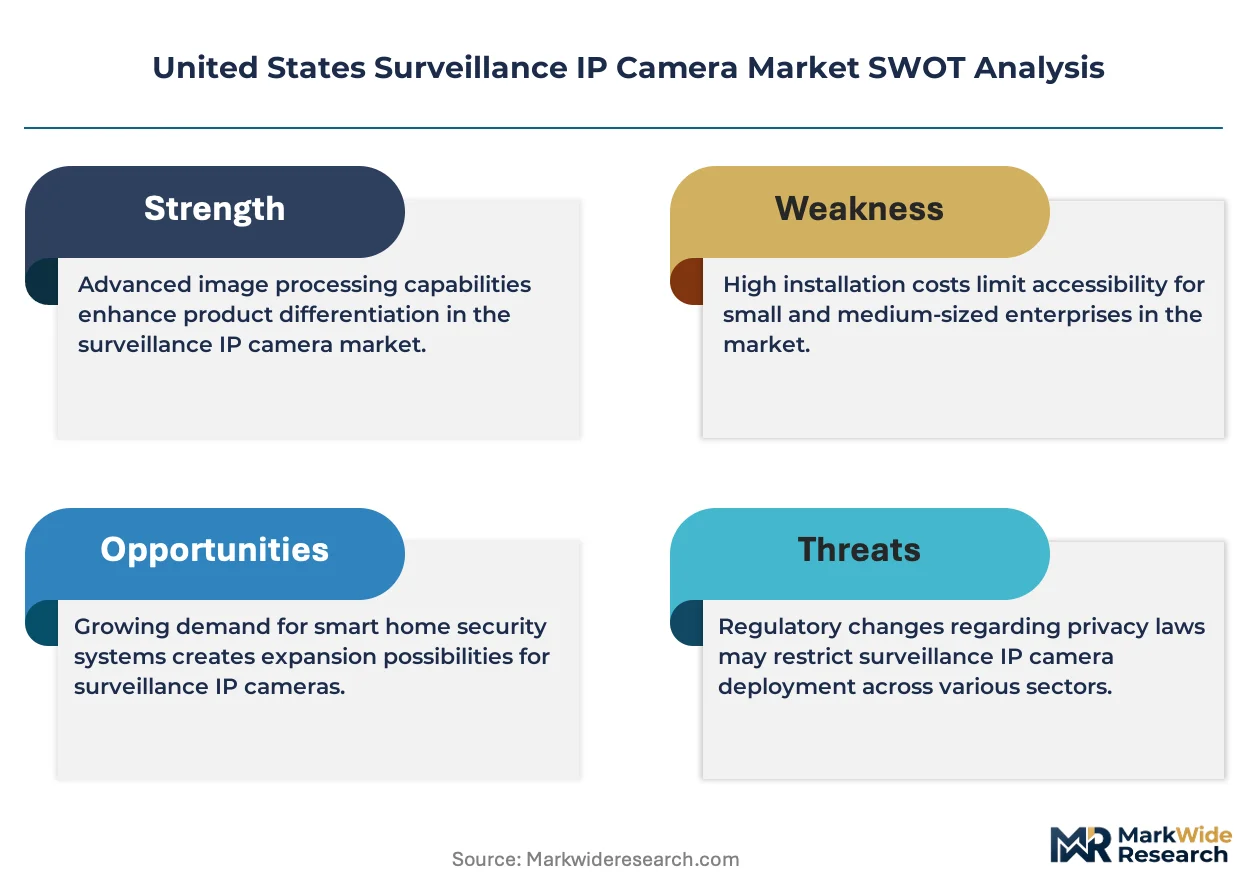
FCC equipment authorization requirements govern radio frequency emissions for wireless camera models, while NDAA Section 889 compliance restrictions bar federal procurement from specific foreign-origin vendors, directly reshaping competitive eligibility. State-level data privacy statutes in California and Illinois impose footage retention and facial recognition limitations that influence product feature roadmaps. Stakeholders must monitor evolving municipal procurement standards that increasingly mandate domestic supply chain verification and encrypted edge storage capabilities.
Market Dynamics
NDAA Section 889 compliance requirements are restructuring vendor eligibility across federal, state, and municipal procurement channels, forcing security integrators to requalify supply chains and manufacturers to relocate final assembly operations.
Growth Catalysts
- Critical infrastructure hardening mandates:CISA directives require cyber-secure edge devices at power generation and transmission facilities, accelerating replacement cycles for legacy analog systems.
- Smart city capital programs:Municipal governments in Texas, California, and Florida are bundling surveillance networks with traffic management and public safety platforms.
- Onboard AI analytics:Edge-based video processing reduces bandwidth costs and enables real-time threat detection without cloud dependency.
Market Restraints
- Semiconductor supply concentration:Image sensor fabrication depends on concentrated Asian foundry capacity, creating lead time volatility for domestic assemblers.
- POE infrastructure retrofit costs:Existing commercial buildings lack Category 6 cabling density, forcing expensive electrical upgrades for IP camera deployment.
- Illinois Biometric Information Privacy Act:Strict facial recognition consent requirements limit analytics feature deployment in retail and hospitality verticals.
Strategic Opportunities
- Data center perimeter expansion:Hyperscale facility construction in Northern Virginia and Phoenix creates demand for thermal-visible fusion cameras with kilometer-range detection.
- Cellular-enabled construction site monitoring:Temporary security deployments favor LTE-connected bullet cameras eliminating trenching and permanent infrastructure.
- California SB 327 IoT security law:Mandatory default password requirements and encryption standards create compliance-driven replacement demand across state-funded installations.
Industry Challenges
- Cybersecurity certification bottlenecks:FedRAMP and StateRAMP authorization timelines stretch 18-24 months, delaying federal market entry for new product lines.
- Legacy VMS integration complexity:Proprietary protocols from established video management platforms fragment interoperability, forcing custom middleware development.
- Edge storage thermal management:MicroSD card reliability in outdoor enclosures fails under extreme temperature cycling, driving warranty costs and field service demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Surveillance IP Camera Market |
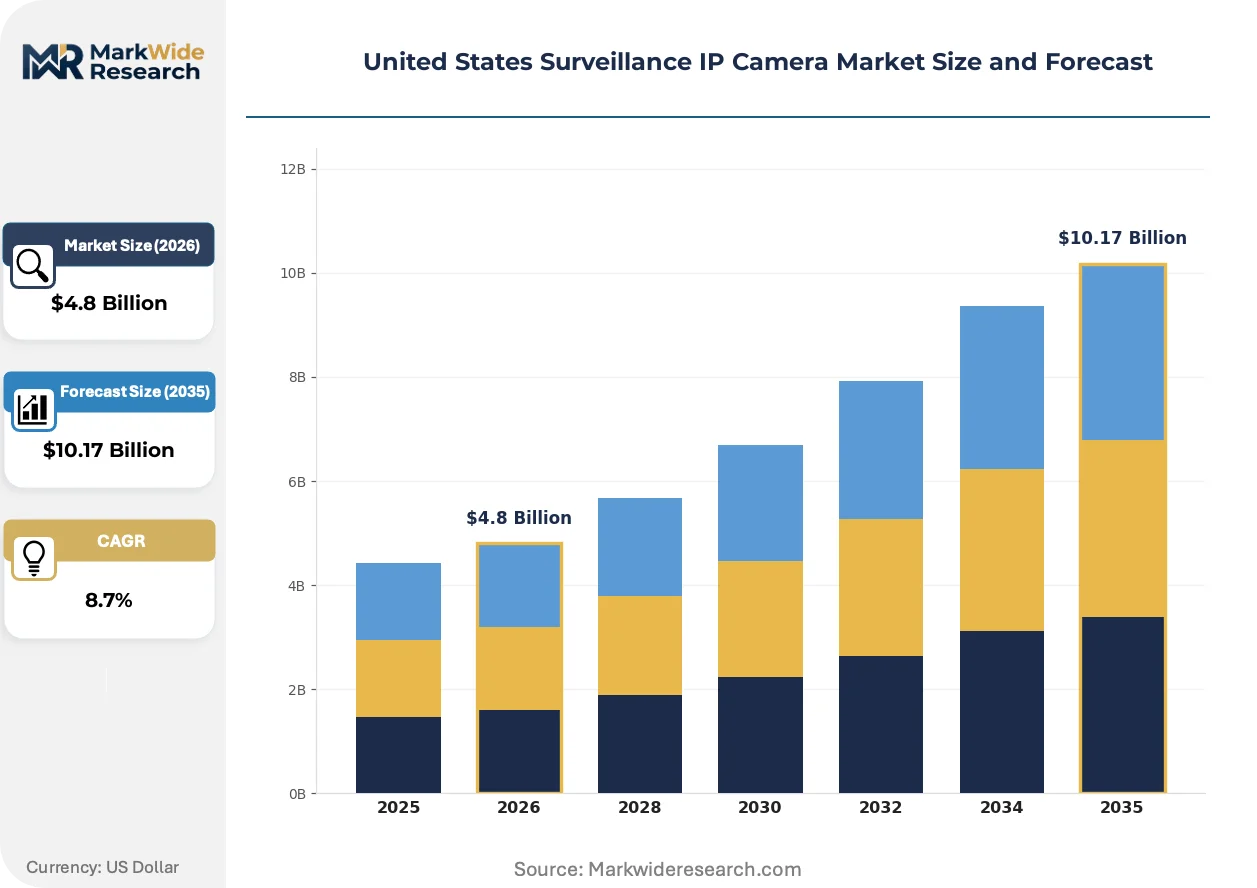
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, PTZ Cameras, Box Cameras Technology: Wi-Fi, POE, Analog, Network End User: Retail Stores, Government Facilities, Residential, Industrial Installation Type: Indoor, Outdoor, Wireless, Wired |
| Companies Covered | Bosch Security Systems, ACTi Corporation, Hanwha Vision America, Panasonic, Lorex, Axis Communications, Avigilon, Pelco, Verkada, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Surveillance IP Camera Market Trends and Innovations
Video analytics processing is migrating from centralized servers to camera edge compute, compressing hardware architectures and reshaping how security operations centers architect their technology stacks.
Multi-sensor fusion cameras combining visible, thermal, and radar detection are consolidating perimeter security architectures. Critical infrastructure operators in Texas and Arizona are adopting these unified platforms to reduce pole-mounted device counts and simplify maintenance logistics. This consolidation is collapsing the traditional separation between physical security and process control system procurement.
FCC equipment authorization timelines for Wi-Fi 6E surveillance cameras have lengthened due to spectrum coordination requirements with incumbent 6 GHz users. Manufacturers are responding by pre-certifying modular radio designs that accelerate customer deployment schedules. The industrial and logistics vertical, with its dense RF environments, faces the steepest compliance burden.
Security-as-a-service subscription models are displacing capital-heavy upfront purchases among mid-market commercial buyers. Integrators in Florida and Georgia are bundling hardware, installation, and cloud storage into monthly per-camera fees. This shift is most pronounced in retail and restaurant chains with distributed footprints and limited internal IT staffing.
United States Surveillance IP Camera Market Segmentation
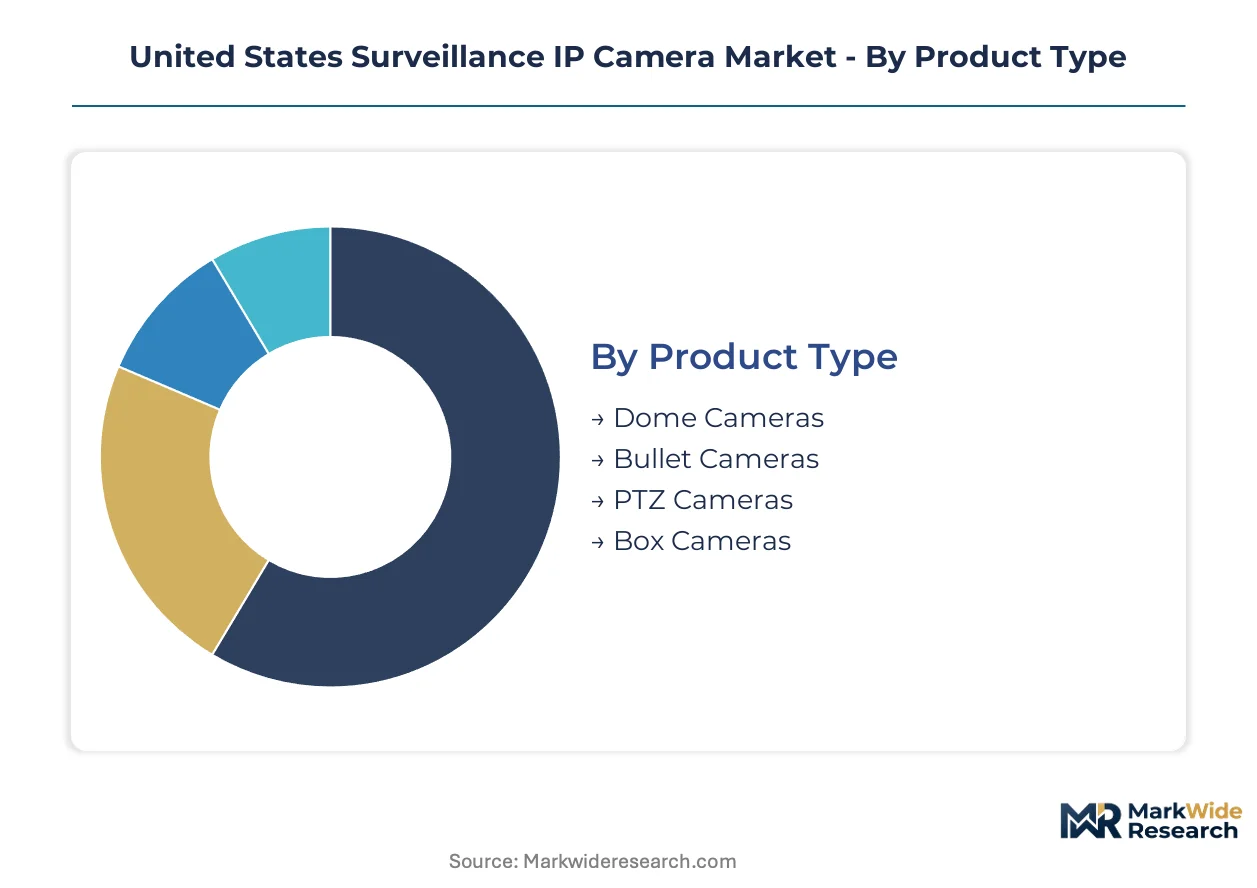
Segmentation reveals how procurement patterns diverge across federal, commercial, and municipal buyers. Each dimension—product form factor, connectivity protocol, end-use environment, and mounting configuration—carries distinct compliance burdens and replacement economics that reshape vendor prioritization.
Product Type:
Upgrade cycles vary sharply by housing design, with vandal-resistant indoor units and long-range outdoor models commanding divergent replacement timelines.
- Dome Cameras:Hemispherical housings with IK10 impact resistance and 360-degree coverage capabilities. Demand concentrates in Texas and California retail environments where discreet positioning and ceiling-mount aesthetics matter, driven by municipal smart city grants requiring unobtrusive public space deployment.
- Bullet Cameras:Cylindrical weather-sealed enclosures with integrated IR illumination extending 100+ meters. Industrial site expansion across Florida and Arizona is accelerating perimeter deployments, constrained by NDAA-compliant supply chain verification requirements for federal-adjacent facilities.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms with preset patrol patterns and optical zoom exceeding 30x.
- Box Cameras:Modular lens-interchangeable designs supporting C/CS-mount optics for specialized focal length requirements.
Dome cameras sit at the top of the volume ranking, with bullet cameras climbing the fastest.
Technology:
Connectivity infrastructure investments in new commercial construction are tilting procurement toward standardized power and data delivery methods.
- POE:IEEE 802.3af/at/bt standards delivering 15-90W over single Category 6 cable runs. New data center construction in Northern Virginia and Phoenix mandates POE++ for thermal-visible fusion cameras, eliminating separate electrical permits and accelerating installation timelines.
- Network:Ethernet-based transmission with H.265+ compression reducing bandwidth consumption 50% versus H.264. Government facilities in California and Illinois are standardizing on encrypted network architectures, driven by CISA directives for cyber-secure edge devices.
- Wi-Fi:802.11ac/ax protocols with WPA3 encryption for cable-inaccessible deployments.
- Analog:Coaxial-based CVI/TVI/AHD protocols preserving legacy infrastructure investments.
Network technology commands the largest installed base, while POE is gaining share fastest in new construction verticals.
End User:
Budget authority and compliance stringency fragment sharply across buyer categories, with federal procurement rules cascading to state and municipal channels.
- Government Facilities:Federal, state, and municipal installations subject to NDAA Section 889 vendor restrictions and FedRAMP cybersecurity certification. Texas and California municipal governments are bundling surveillance with traffic management platforms, accelerating replacement of legacy analog systems through smart city capital programs.
- Industrial:Critical infrastructure operators under CISA directives requiring cyber-hardened edge devices. Power generation facilities in Florida and Arizona are deploying thermal-visible fusion cameras with kilometer-range detection, constrained by 18-24 month StateRAMP authorization timelines.
- Retail Stores:Loss prevention and liability documentation deployments in franchise and independent operations.
- Residential:Consumer-grade Wi-Fi cameras with cloud subscription models for homeowner monitoring.
Industrial end users generate the highest average selling prices, with government facilities expanding most quickly.
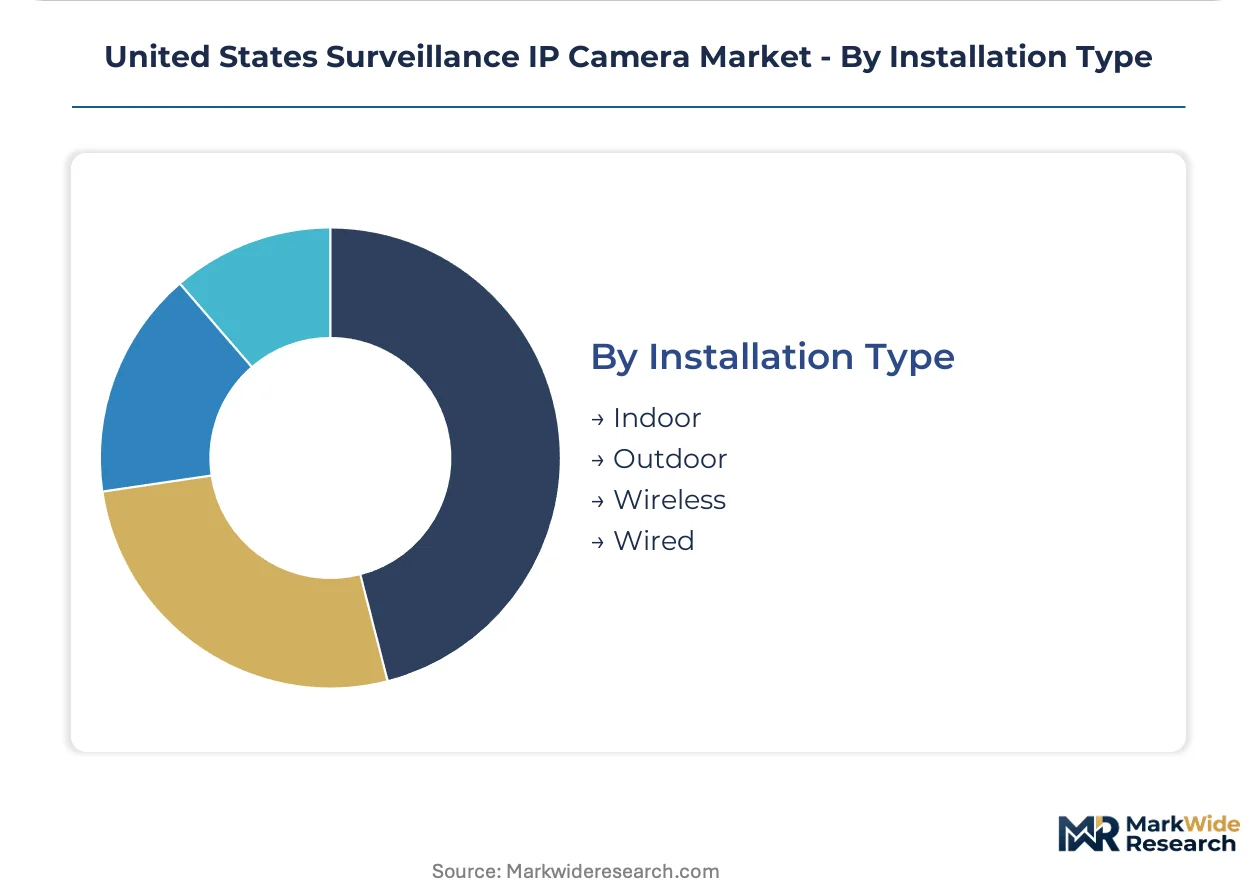
Installation Type:
Environmental sealing ratings and mounting logistics drive divergent labor cost structures and maintenance schedules.
- Outdoor:IP66/IP67-rated enclosures with integrated heaters and hydrophobic lens coatings. Construction site monitoring across Florida and Georgia favors cellular-enabled bullet cameras eliminating trenching requirements, though extreme temperature cycling degrades microSD edge storage reliability.
- Indoor:Climate-controlled environments with lower IK impact resistance requirements and simplified cable routing. Retail and hospitality deployments in California face Illinois BIPA-style biometric consent limitations constraining analytics feature activation.
- Wireless:Battery or solar-powered cellular/LTE cameras for temporary or remote locations.
- Wired:Permanent Ethernet or coaxial infrastructure with centralized power distribution.
Outdoor installations dominate project value, with wireless configurations expanding most quickly in temporary security applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing final assembly capacity toward states with lower compliance-cost structures, while federal procurement rules cascade down to reshape municipal vendor pools across jurisdictions with divergent smart-city investment timelines.
California
SB 327 IoT security mandates and CCPA footage retention rules are accelerating replacement cycles in state-funded installations. Municipal governments in Los Angeles and San Francisco bundle surveillance networks with traffic management platforms. Data center construction in Silicon Valley and Sacramento corridor demands thermal-visible fusion cameras with encrypted edge storage.
Texas
Critical infrastructure hardening directives from ERCOT and CISA drive cyber-secure edge device procurement at power generation facilities. Smart city capital programs in Dallas, Houston, and Austin reposition municipal procurement toward integrated public safety platforms. The Permian Basin energy corridor generates concentrated demand for perimeter security with kilometer-range detection capabilities.
Florida
Hurricane-resilient infrastructure standards and coastal facility hardening requirements shape outdoor camera specifications. Construction site monitoring across Miami-Dade and Tampa Bay favors cellular-enabled deployments eliminating trenching requirements. Security-as-a-service subscription models displace capital purchases among mid-market commercial buyers in the hospitality vertical.
Illinois
BIPA biometric consent requirements constrain facial recognition analytics deployment in retail and hospitality verticals. Chicago municipal procurement increasingly mandates domestic supply chain verification for federal-adjacent installations. The I-55 logistics corridor drives demand for warehouse perimeter security with onboard AI analytics reducing bandwidth costs.
Arizona
Extreme temperature cycling in desert environments degrades microSD edge storage reliability, driving thermal management innovation. Hyperscale data center construction in Phoenix creates demand for POE++ infrastructure supporting thermal-visible fusion cameras. Border security and critical infrastructure operators adopt multi-sensor fusion platforms consolidating perimeter architectures.
United States Surveillance IP Camera Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with federal compliance requirements creating tiered eligibility pools that advantage domestic assemblers over import-dependent competitors. The vendor base concentrates around three strategic archetypes: German-engineered premium specialists, American-assembled compliance navigators, and cloud-native subscription platforms. Dominant competitive moves include supply chain relocation to satisfy Buy American requirements and strategic partnerships with security integrators bundling hardware into managed service offerings.
Within the federal-eligible tier, Bosch Security Systems and Hanwha Vision America exemplify divergent approaches to NDAA compliance—one leveraging German-engineered manufacturing heritage, the other anchoring growth through American-assembled product lines. Axis Communications occupies a position bridging commercial and government verticals with modular platform architectures. These three represent how geographic origin and assembly location have become primary sorting mechanisms for procurement eligibility across federal, state, and municipal channels.
| Leading Market Players |
|---|
| Bosch Security Systems |
| ACTi Corporation |
| Hanwha Vision America |
| Panasonic |
| Lorex |
| Axis Communications |
| Avigilon |
| Pelco |
| Verkada |
| Others |
Pricing and Supply Chain Analysis
Embedded firmware engineers concentrated in Austin and San Diego command 35-40% wage premiums over assembly technicians in Phoenix and Dallas, widening spreads between cyber-hardened premium tiers and standard commercial offerings as labor-cost differentials transmit directly into product positioning.
Pricing Analysis
Distributor margins compressing 8-12 points since NDAA compliance verification became standard procurement language. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-certified federal-eligible lines from municipal-grade products and residential Wi-Fi cameras. Pricing pressure stems from security-as-a-service subscription models displacing upfront capital purchases among mid-market buyers. Government facilities show lowest price sensitivity due to mandated compliance budgets, while retail chains negotiate aggressively on per-camera fees.
Supply Chain Analysis
Regional distribution centers in Memphis and Louisville anchor hub-and-spoke patterns reaching integrators within 48 hours. Image sensor fabrication draws from Taiwan, South Korea, and Japan, while final assembly concentrates in Mexico, Vietnam, and domestic facilities in Texas and California. POE chipset supply rests on single-source vulnerability at two Taiwanese foundries. Distribution runs through security integrators bundling installation and VMS licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in edge-analytics tiers where onboard AI processing commands 40-60% premiums over standard encoding models, with cost-down drivers emerging from H.265+ compression IP maturation and domestic assembly scale economies.
For Market Incumbents: Anchor federal eligibility through Buy American assembly investments in Texas and Arizona, while hardening supply chains against semiconductor concentration risk. Defensive moves require StateRAMP pre-certification for new product lines and exclusive distribution agreements with top-ten security integrators. Cloud-native subscription platforms threaten hardware-centric margin pools. For New Entrants and Emerging Players: Direct-to-installer digital channels bypass incumbent distributor relationships and accelerate customer acquisition in underserved municipal verticals. White-space targets include cellular-enabled construction site monitoring across Florida and Georgia, plus thermal-visible fusion cameras for data center perimeter expansion in Northern Virginia. Go-to-market angle emphasizes FedRAMP-fast-track partnerships with compliance consultancies. For Investors and Strategic Acquirers: Valuations sit cheapest among American-assembled compliance navigators with NDAA-clean supply chains and pending StateRAMP authorizations. Long-term viability hinges on sustained federal procurement preference for domestic assembly and edge-analytics differentiation. Acquisition target archetype: mid-tier manufacturers with relocatable final assembly and existing CISA cyber-hardening certifications. Signal to watch: FedRAMP authorization timeline compression as competitive moat.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Relocation | Buy American compliance unlocks federal and municipal procurement channels previously restricted. |
| Edge AI Analytics Integration | Onboard processing reduces bandwidth costs and enables real-time threat detection without cloud dependency. |
| Security-as-a-Service Launch | Subscription models displace capital purchases among mid-market retail and hospitality chains. |
| Multi-Sensor Fusion Development | Thermal-visible-radar consolidation collapses perimeter device counts for critical infrastructure operators. |
| FedRAMP Pre-Certification Investment | Accelerated authorization timelines compress competitive entry barriers for federal-adjacent installations. |
Research Methodology
Multiple input streams — security integrator interviews, municipal procurement officer discussions, federal contracting database analysis, and secondary trade data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged product managers at camera manufacturers, chief security officers at critical infrastructure operators, video management software engineers, and GSA schedule contracting specialists. Secondary validation drew from FCC equipment authorization filings, CISA directive documentation, GSA Advantage procurement records, and state-level smart city capital program disclosures.
Historical shipment data cross-referenced against panel input from distribution channel partners anchored the forecast framework across the analysis window. Segmentation dimensions modeled include product form factor, connectivity protocol, end-user vertical, and installation environment. CAGRs derived from elasticity-adjusted replacement cycle analysis and infrastructure spending correlation. Industry-specific inputs encompassed NDAA compliance timeline assumptions and municipal bond issuance patterns for smart city deployments.
Semiconductor supply volatility, regulatory enforcement intensity variations across states, and subscription model adoption speed are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
Video Surveillance Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
China Surveillance Analog Camera Market
Video Surveillance Systems
Brazil Video Surveillance Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
China Surveillance IP Camera Market
Video Surveillance Systems
AI Surveillance System Market
Video Surveillance Systems
People Counting System Market