
 Global Public Safety and Security Market | 2026-2036
Global Public Safety and Security Market Size, Share, and Industry Trends Forecast 2026-2036
Global Public Safety and Security Market Foresight
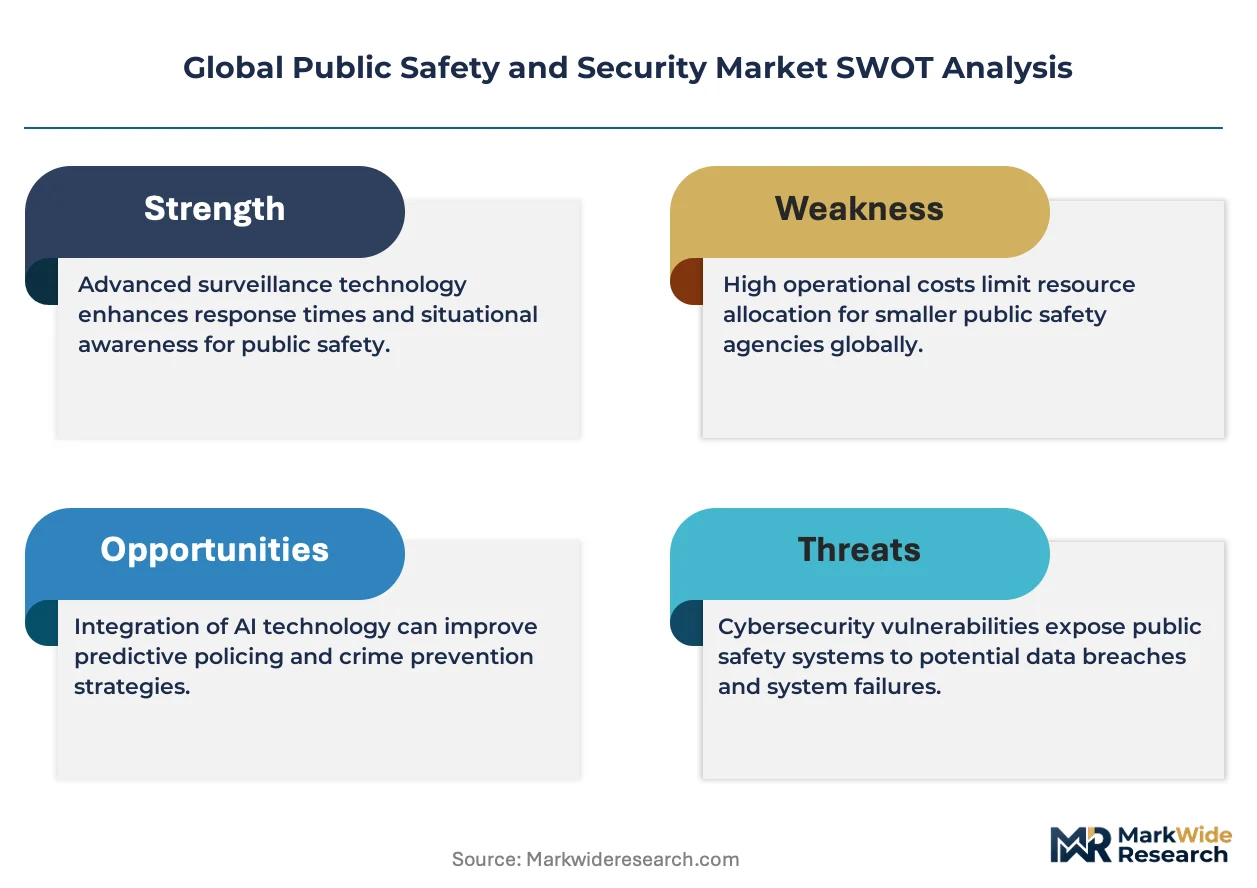
Cloud-native command-and-control architectures is reshaping how public safety agencies deploy surveillance and emergency response systems. Motorola Solutions leverages its LMR heritage to anchor mission-critical communications contracts with federal and municipal buyers. Cisco Systems competes through IT infrastructure integration, extending its networking dominance into secure public safety backbones. Honeywell International specializes in building management and access control convergence, positioning its portfolio across industrial facilities and transportation hubs.
Public safety and security encompasses integrated systems for threat detection, incident response, and critical infrastructure protection, typically operating across IP-based networks with sub-second latency requirements for emergency dispatch and real-time video analytics. The primary purpose is to reduce response times to security incidents while ensuring continuous monitoring of high-risk environments. Surveillance systems and AI-powered monitoring command the largest share of solution spending as agencies replace analog infrastructure with intelligent video platforms. Cloud-based deployment is expanding fastest among mid-sized municipalities seeking to avoid capital-intensive on-premise data centers, though hybrid architectures retain strong traction where air-gapped networks remain mandatory.
FCC spectrum allocations shape device interoperability standards for US first responders, while the EU AI Act imposes conformity requirements on biometric authentication and automated incident detection systems sold across member states. India's BIS certification and China's GB standards create divergent compliance pathways that fragment vendor go-to-market strategies. Stakeholders must evaluate which regulatory frameworks their technology roadmaps can satisfy without proliferating product variants beyond manageable scope.
Market Dynamics
Cloud-native command-and-control architectures are compressing deployment cycles for public safety agencies, displacing capital-intensive on-premise infrastructure with subscription-based platforms that reduce time-to-operational status from months to weeks.
Growth Catalysts
- EU AI Act conformity requirements:Biometric authentication systems with privacy-by-design architectures face mandatory certification, accelerating procurement of compliant platforms across European metropolitan command centers.
- Smart city infrastructure modernization:Metropolitan areas in the United States, China, and India are expanding AI-powered monitoring platform procurement to integrate surveillance, traffic management, and emergency dispatch.
- FCC spectrum allocation reforms:First responder device interoperability standards are driving replacement cycles for legacy Land Mobile Radio systems with LTE-enabled mission-critical communications.
Market Restraints
- Semiconductor supply concentration:AI accelerator chips and edge computing processors face sourcing risk from Taiwan and South Korea foundries, constraining video analytics platform production.
- GDPR biometric data friction:Automated facial recognition deployment in EU public spaces requires explicit legal basis documentation, slowing municipal procurement timelines.
- Air-gapped network mandates:Critical infrastructure protection frameworks in defense and energy sectors prohibit cloud connectivity, forcing vendors to maintain parallel hybrid product lines.
Strategic Opportunities
- India BIS certification pathway:Domestic manufacturing incentives under PLI schemes create localized production advantages for foreign vendors establishing Indian subsidiaries.
- Convergence of drone surveillance and AI analytics:Real-time aerial threat detection paired with automated object classification opens emergency response and border security applications.
- Subscription-based SaaS channels:Mid-sized municipalities lacking IT infrastructure expertise prefer managed service procurement over capital expenditure models.
Industry Challenges
- Cyber-physical systems integration:Merging legacy analog surveillance with IP-based AI platforms requires specialized system integrators scarce in secondary cities.
- Multi-jurisdiction certification timelines:Vendors must sequence FCC, EU AI Act, BIS, and GB standard approvals, fragmenting product launch coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Public Safety and Security Market |
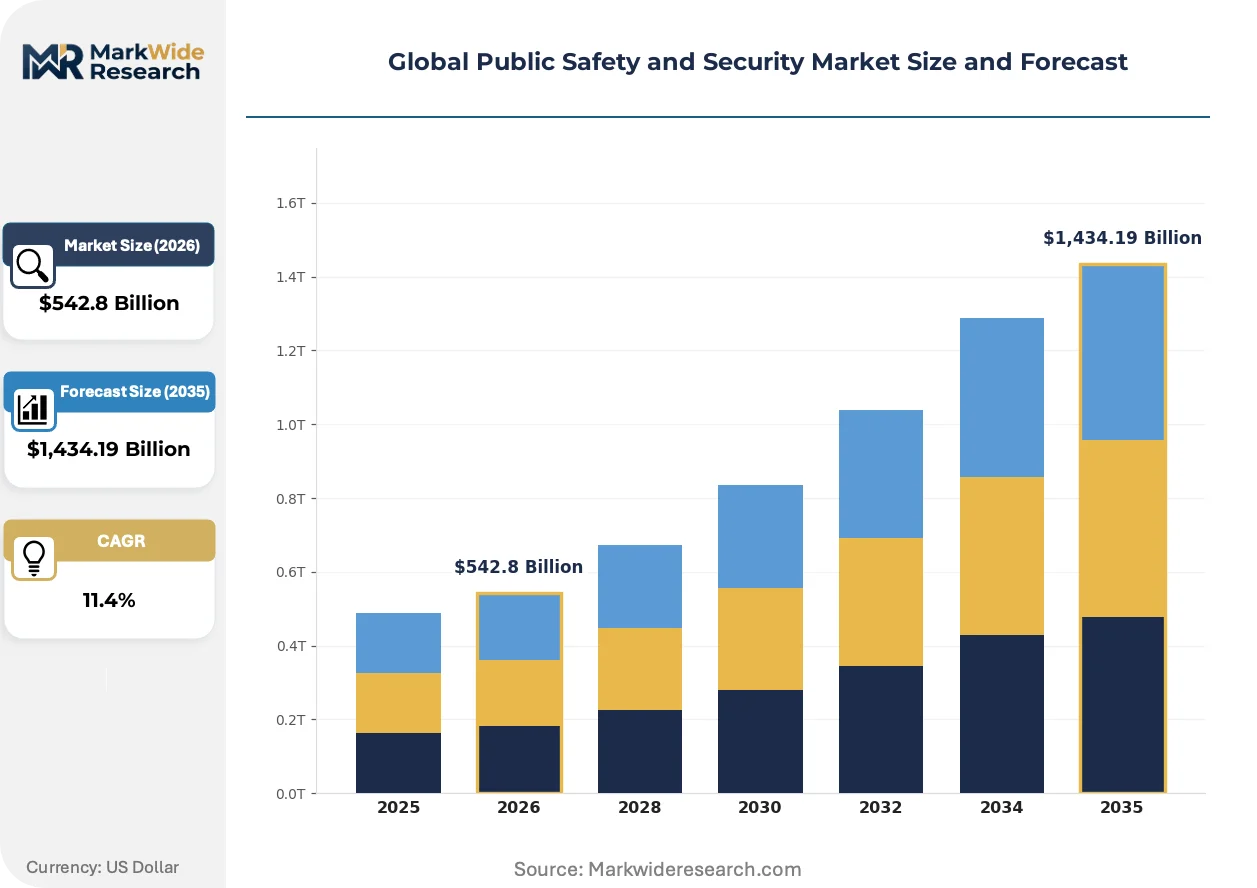
| Market Size in 2026 | $542.8 Billion |
| Market Size in 2035 | $1,434.19 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Surveillance Systems, Access Control, Fire Detection, Intrusion Detection, Emergency Management Deployment Mode: Cloud-Based, On-Premise, Hybrid, Edge Computing End User: Law Enforcement, Military Agencies, Emergency Response Teams, Transportation Authorities, Industrial Facilities Technology: Video Analytics, Biometric Authentication, Incident Detection, Wireless Sensor Networks, AI Powered Monitoring |
| Companies Covered | Motorola Solutions, Cisco Systems, Honeywell International, Siemens, General Dynamics, IBM, Axis Communications, NEC Corporation, Hexagon AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Public Safety and Security Market Shifts & Advancements
Edge AI inference engines are redistributing computational load from centralized data centers to camera-mounted processors, enabling real-time threat detection without bandwidth dependency.
Intelligent video analytics with on-device machine learning is rendering obsolete centralized server farms for facial recognition and behavioral analysis. Municipal police departments in Singapore and Dubai are deploying these platforms at neighborhood scale. The shift eliminates network latency bottlenecks that previously constrained emergency response automation.
China's GB standards for intelligent security systems mandate domestic encryption protocols for government procurement, creating technical barriers for foreign platform vendors. Compliance requires hardware architecture modifications that fragment engineering resources. European and North American suppliers are responding with China-specific product variants that sacrifice interoperability with global fleets.
Outcome-based service contracts are displacing equipment-centric procurement in mid-sized US municipalities lacking dedicated IT security staff. Vendors assume operational responsibility for system uptime and threat detection accuracy. This model concentrates fastest in Rust Belt cities where legacy infrastructure replacement coincides with constrained municipal budgets.
Global Public Safety and Security Market Segmentation
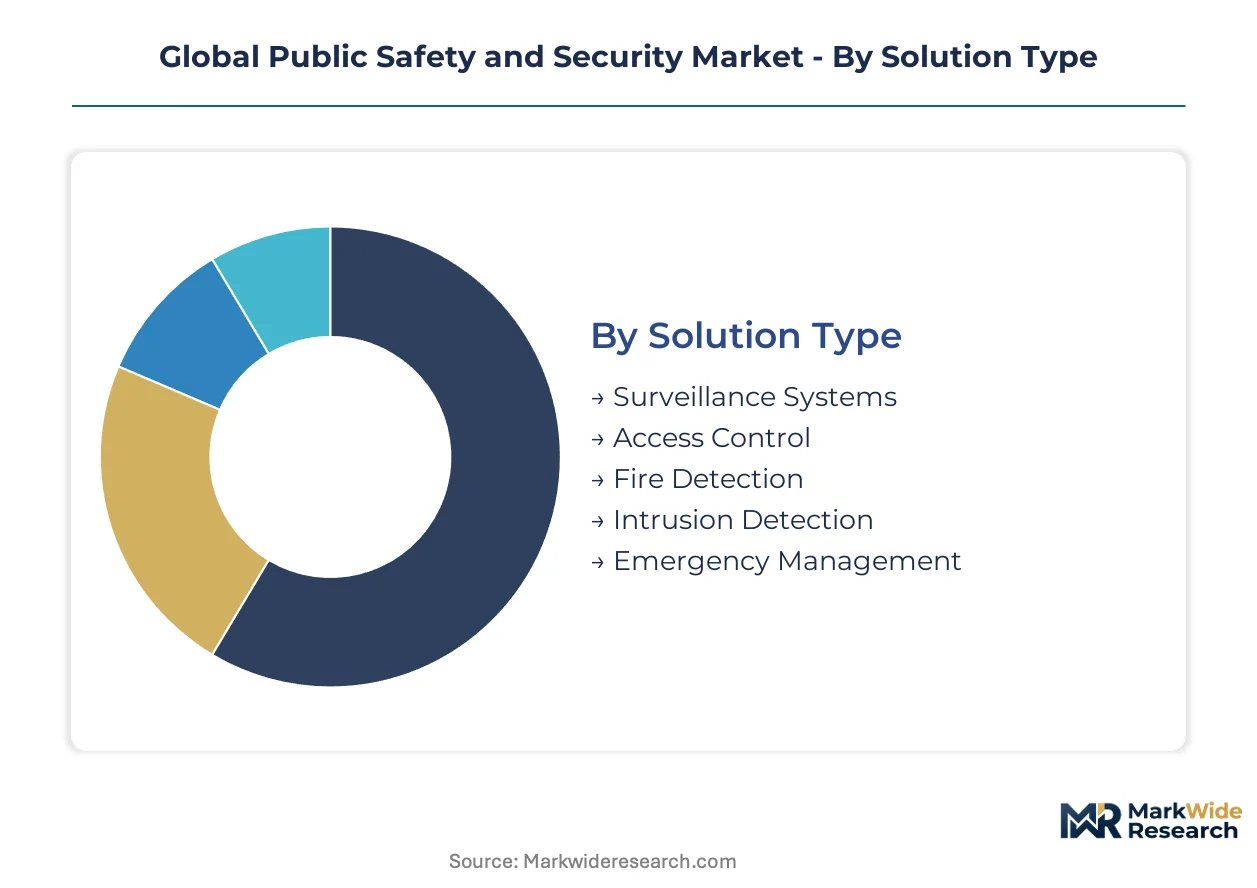
Segmentation in public safety and security reflects divergent procurement rhythms across federal, municipal, and private buyers. Solution architectures must reconcile mission-critical reliability mandates with budget constraints that vary sharply by deployment scale and jurisdiction.
Solution Type:
After-sales service intensity varies dramatically across solution categories, with surveillance systems demanding continuous firmware updates and intrusion detection requiring rapid on-site response capabilities.
- Surveillance Systems:Intelligent video platforms with edge AI inference engines process footage locally before cloud transmission. Demand concentrates in smart city command centers across Singapore, Dubai, and metropolitan India where 24/7 monitoring is mandatory.
- Access Control:Biometric readers and credential management systems integrate physical and logical security layers. European municipal buildings under EU AI Act jurisdiction prioritize privacy-by-design authentication with explicit consent workflows.
- Fire Detection:Multi-sensor arrays with thermal imaging and air sampling capabilities serve industrial facilities and transportation tunnels. BIS certification requirements in India drive localized manufacturing partnerships.
- Intrusion Detection:Perimeter sensors and motion analytics protect critical infrastructure. Air-gapped network mandates in defense and energy sectors force hybrid architecture support.
- Emergency Management:Dispatch platforms coordinating multi-agency response require sub-second latency. FCC spectrum reforms accelerate LTE-enabled replacement of legacy Land Mobile Radio systems in US first responder agencies.
Surveillance systems hold the largest share; momentum sits with emergency management platforms.
Deployment Mode:
Cost tier stratification separates capital-intensive on-premise builds from subscription models favored by budget-constrained municipalities.
- Cloud-Based:SaaS delivery eliminates data center capital expenditure for mid-sized cities. Rust Belt municipalities lacking IT security staff prefer outcome-based service contracts with uptime guarantees.
- On-Premise:Dedicated hardware stacks serve agencies with classified data handling requirements. Defense and intelligence sectors mandate air-gapped architectures prohibiting external connectivity.
- Hybrid:Split workloads keep sensitive processing local while leveraging cloud analytics. European command centers under GDPR deploy this model to satisfy data residency requirements.
- Edge Computing:Camera-mounted processors enable real-time threat detection without bandwidth dependency. Singapore and Dubai police departments deploy neighborhood-scale intelligent video analytics with on-device machine learning.
Hybrid architectures dominate current procurement; edge computing is climbing the fastest as latency requirements tighten.
End User:
Application severity shapes technology specifications, with military and law enforcement demanding encryption standards beyond commercial grades.
- Law Enforcement:Body-worn cameras and real-time crime centers require chain-of-custody evidence management. US municipal departments modernize analog infrastructure with AI-powered monitoring platforms.
- Military Agencies:Secure communications and perimeter defense systems operate under classified network protocols. China's GB standards mandate domestic encryption for government procurement, fragmenting vendor engineering resources.
- Emergency Response Teams:Mobile command units need rapid-deployment connectivity. FCC spectrum allocation reforms drive device interoperability standards for first responders.
- Transportation Authorities:Integrated video and sensor networks monitor airports, rail, and ports. Indian metro expansions under PLI schemes create localized production incentives for foreign vendors.
- Industrial Facilities:Converged physical and cybersecurity protects critical infrastructure. Honeywell positions building management and access control systems across energy and manufacturing sites.
Law enforcement represents the largest installed base; transportation authorities are gaining share fastest.
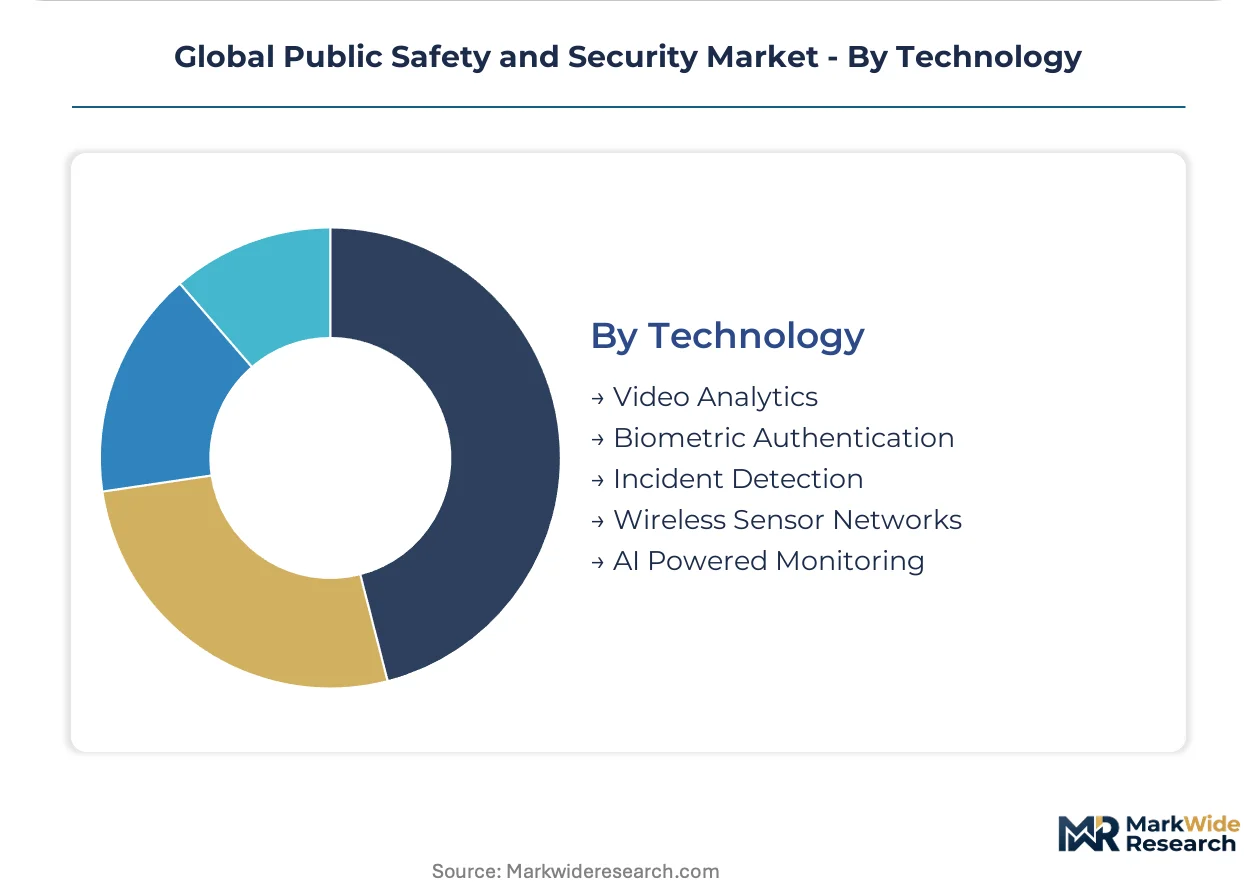
Technology:
Supply concentration in AI accelerator chips from Taiwan and South Korea foundries constrains production scaling for advanced analytics platforms.
- Video Analytics:Behavioral recognition and object classification algorithms run on edge or centralized infrastructure. GDPR biometric data friction slows automated facial recognition deployment in EU public spaces.
- Biometric Authentication:Fingerprint, iris, and facial recognition systems require EU AI Act conformity certification. European metropolitan command centers accelerate procurement of compliant privacy-by-design platforms.
- Incident Detection:Multi-sensor fusion correlates anomalies across video, audio, and environmental feeds. Smart city infrastructure modernization in the United States, China, and India expands platform procurement.
- Wireless Sensor Networks:Low-power mesh topologies extend coverage to remote or mobile assets. Border security and emergency response applications drive drone surveillance convergence with automated object classification.
- AI Powered Monitoring:Machine learning platforms integrate surveillance, traffic management, and emergency dispatch. Semiconductor supply concentration creates sourcing risk for video analytics production.
Video analytics commands the largest share; AI powered monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German security technology exporters supply AI-powered monitoring platforms to municipal buyers across the European Union. Cross-border procurement flows concentrate in smart city command centers seeking GDPR-compliant biometric authentication systems.
United States
FCC spectrum allocation reforms drive replacement cycles for legacy Land Mobile Radio systems with LTE-enabled mission-critical communications. Federal procurement mandates prioritize domestic manufacturing under Buy American provisions. Metropolitan police departments in Chicago and Los Angeles modernize analog surveillance infrastructure with intelligent video analytics.
China
GB standards for intelligent security systems mandate domestic encryption protocols for government procurement, fragmenting vendor engineering resources. MIIT certification requirements accelerate localized production partnerships for foreign platform providers. Smart city deployments in Shenzhen and Hangzhou integrate AI-powered monitoring across traffic management and emergency dispatch functions.
Germany
EU AI Act conformity requirements accelerate procurement of privacy-by-design biometric authentication platforms across metropolitan command centers. BSI technical guidelines shape federal cybersecurity procurement for critical infrastructure protection. Industrial security clusters in Munich and Stuttgart converge building management with access control systems.
India
PLI scheme incentives create localized production advantages for foreign vendors establishing Indian subsidiaries. BIS certification requirements for fire detection and intrusion systems drive domestic manufacturing partnerships. Metro rail expansions in Mumbai and Delhi generate concentrated demand for integrated video and sensor networks.
United Arab Emirates
Dubai Police deploy neighborhood-scale intelligent video analytics with on-device machine learning at city-wide scale. MOHAP data residency requirements shape procurement for healthcare facility security systems. Abu Dhabi command centers integrate drone surveillance with automated object classification for border security applications.
Global Public Safety and Security Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Federal and municipal buyers operate through distinct contracting vehicles that favor different vendor capabilities. Three archetypes dominate: legacy communications infrastructure providers, IT systems integrators, and building automation specialists. Competitive moves concentrate on strategic partnerships with system integrators and portfolio diversification into adjacent security domains.
Within the mission-critical communications tier, Motorola Solutions and Cisco Systems occupy positions shaped by legacy infrastructure entrenchment. Honeywell International sits within the building automation convergence segment. These three exemplify how vendor archetypes align with buyer procurement patterns across federal, municipal, and industrial segments.
| Leading Market Players |
|---|
| Motorola Solutions |
| Cisco Systems |
| Honeywell International |
| Siemens |
| General Dynamics |
| IBM |
| Axis Communications |
| NEC Corporation |
| Hexagon AB |
| Others |
Supply & Pricing Matrix
Undercapacity in Taiwan and South Korea foundries is tightening AI accelerator chip availability, forcing surveillance platform vendors to absorb cost increases while pushing subscription pricing toward longer contract terms with volume commitments.
Pricing Analysis
Current-generation edge AI inference engines command substantial premiums over prior-generation centralized server architectures, while next-generation neuromorphic processors remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service intensity. Cost compression in mid-tier municipal procurement is intensifying because Rust Belt cities bundle outcome-based service contracts with uptime guarantees. Federal agencies with classified mandates show least price sensitivity; mid-sized municipalities lacking IT security staff exhibit highest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing decisions for biometric authentication hardware. Taiwan, South Korea, and Japan anchor semiconductor fabrication for video analytics processors. Raw material dependencies span gallium nitride substrates, high-purity silicon wafers, and rare-earth magnets. Single-source vulnerability concentrates in TSMC's advanced node capacity. Distribution runs through systems integrators with federal contracting vehicles and direct OEM relationships with municipal procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among federal and large metropolitan procurement consortia, fragmenting vendor pricing leverage as multi-jurisdiction certification requirements proliferate compliance costs.
For Market Incumbents: Pre-empt emerging SaaS-native entrants by embedding outcome-based service contracts into existing LMR infrastructure relationships. Anchor federal channel control through Buy American compliance while absorbing EU AI Act certification costs to lock out smaller competitors. Threat substitution from cloud-native dispatch platforms demands accelerated hybrid architecture development. For New Entrants and Emerging Players: Secondary Indian cities under smart city mission funding represent the most penetrable geographic white space. Target BIS-certified fire detection and intrusion systems through PLI scheme manufacturing partnerships. Go-to-market angle: position subscription-based managed security services to municipalities lacking capital expenditure flexibility. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because multi-jurisdiction certification fragmentation creates acquisition targets with compliant product variants that larger vendors cannot replicate without engineering resource strain. Watch FCC spectrum auction outcomes and EU AI Act enforcement timelines as inflection signals for platform consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-by-Design Certification Investment | EU AI Act conformity accelerates procurement access across German and French metropolitan command centers. |
| Edge Computing Platform Launch | Camera-mounted inference engines eliminate latency bottlenecks for Singapore Police real-time crime centers. |
| Strategic Partnership with System Integrators | Federal contracting vehicles require specialized cybersecurity clearances that channel partners already hold. |
| Acquisition of Drone Surveillance Specialist | Aerial threat detection paired with automated object classification opens Abu Dhabi border security applications. |
| Geographic Expansion via Indian Subsidiary | PLI scheme incentives and BIS certification pathways localize production for Mumbai metro rail expansions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with public safety technology procurement officers, system integration specialists, and federal contracting vehicle managers; and secondary validation against FCC spectrum allocation records, EU AI Act conformity databases, BIS certification registries, and customs trade data for semiconductor component flows. Bottom-up triangulation across municipal budget disclosures and top-down reconciliation with federal infrastructure appropriations anchored volume estimates.
Forecast inputs span solution type, deployment mode, end-user segment, and technology architecture across the analysis window. Modeled dimensions include mission-critical reliability tiers, data residency requirements, and spectrum allocation regime clusters. CAGRs derive from weighted average procurement cycle analysis and replacement rate assumptions for legacy analog infrastructure. Edge computing adoption curves and biometric authentication regulatory compliance timelines shaped trajectory inflections.
Practitioners should monitor FCC spectrum auction outcomes, EU AI Act enforcement precedents, and Taiwan foundry utilization rates for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Middle East Crime and Combat Market
Public Safety
Europe Road Safety Market
Public Safety
Crime Risk Report Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Public Safety Market
Public Safety
Counter Terror and Public Safety Technology Market
Public Safety
Outdoor Public Safety Market
Public Safety
Public Safety LTE Market
Public Safety
Crowd Management System Market
Public Safety
Global Public Safety Solution Market
Public Safety
Global IoT for Public Safety Market
Public Safety
Asia-Pacific Public Safety Market
Public Safety
Global Public Safety Analytics Market