
 Airport Security Market | 2026-2036
Airport Security Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Security Market Analysis
Middle East terminal expansion is fragmenting procurement patterns across legacy and next-generation security architectures. Smiths Detection leverages computed tomography baggage screening to sustain technology leadership in hold-baggage applications. Rapiscan Systems anchors North American manufacturing scale through dense airport retrofit programs. Leidos competes on integrated command-and-control platforms that fuse multiple sensor streams into unified operational pictures.
Airport security encompasses the integrated systems, procedures, and technologies deployed to detect threats, control access, and protect passengers, crew, and aircraft across civil aviation facilities. X-ray scanners operate at 160 kV or higher tube voltages to achieve the material discrimination resolution required for automated explosives detection under EASA and TSA certification protocols. Biometrics represents the fastest-growing technology segment as facial recognition gates displace manual document checks at boarding pinch points. Passenger screening commands the largest application share, though cargo screening accelerates as e-commerce air freight volumes strain existing inspection throughput.
TSA certification requirements and EASA implementing regulation 2015/1998 shape product development roadmaps by mandating specific detection thresholds and operational availability metrics. The EU AI Act adds algorithmic transparency obligations to biometric deployment contracts, while ICAO standards harmonize international interoperability frameworks. Stakeholders must weigh upgrade cycles against emerging millimeter-wave and passive screening technologies that promise higher throughput with lower passenger friction.
Market Dynamics
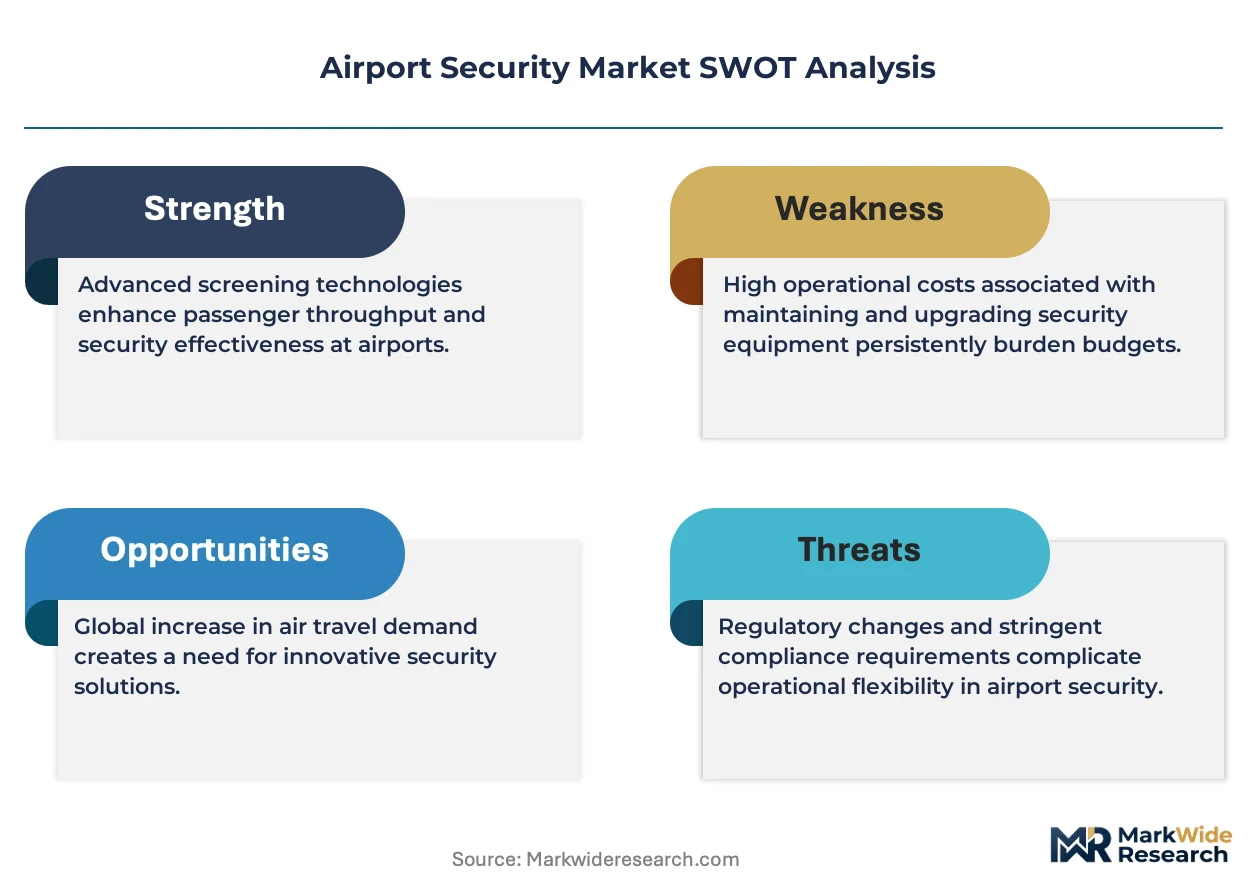
The transition from 2D X-ray to computed tomography hold-baggage screening is compressing replacement cycles across major aviation hubs, forcing capital allocation toward detection algorithms and throughput optimization rather than mechanical reliability alone.
Growth Catalysts
- EU EASA Implementing Regulation 2015/1998:Mandates for Standard 3 hold-baggage screening accelerate terminal retrofit programs across member states.
- Biometric passenger processing:Facial recognition gates at Dubai International Airport and Singapore Changi Airport reduce boarding friction and lane staffing requirements.
- E-commerce air freight volumes:Parcel screening throughput constraints at integrator hubs drive demand for automated explosives detection systems.
Market Restraints
- Tube voltage supply concentration:Specialized 160-300 kV X-ray tube manufacturing concentrates in Germany and Japan, creating single-source vulnerability for CT scanner OEMs.
- Certification timeline friction:TSA certification protocols for new detection algorithms extend product launch windows by 18-24 months.
- Passive millimeter-wave substitution:Emerging walk-through screening technologies threaten to displace active millimeter-wave portals in low-risk lane configurations.
Strategic Opportunities
- India airport privatization wave:Greenfield terminals at Navi Mumbai and Jewar under construction create first-mover positioning for integrated security system providers.
- EU AI Act algorithmic transparency:Biometric deployment contracts now require explainable AI documentation, favoring vendors with in-house machine-learning development.
- Cargo-to-passenger screening convergence:Dual-use CT platforms capable of hold-baggage and air-cargo inspection reduce hub capital duplication.
Industry Challenges
- Detection algorithm training data scarcity:Curated threat image libraries for machine-learning model development remain concentrated among national laboratories and incumbent OEMs.
- Legacy 2D X-ray integration:Hybrid architectures combining existing conveyor infrastructure with CT reconstruction engines create software-hardware compatibility failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Security Market |
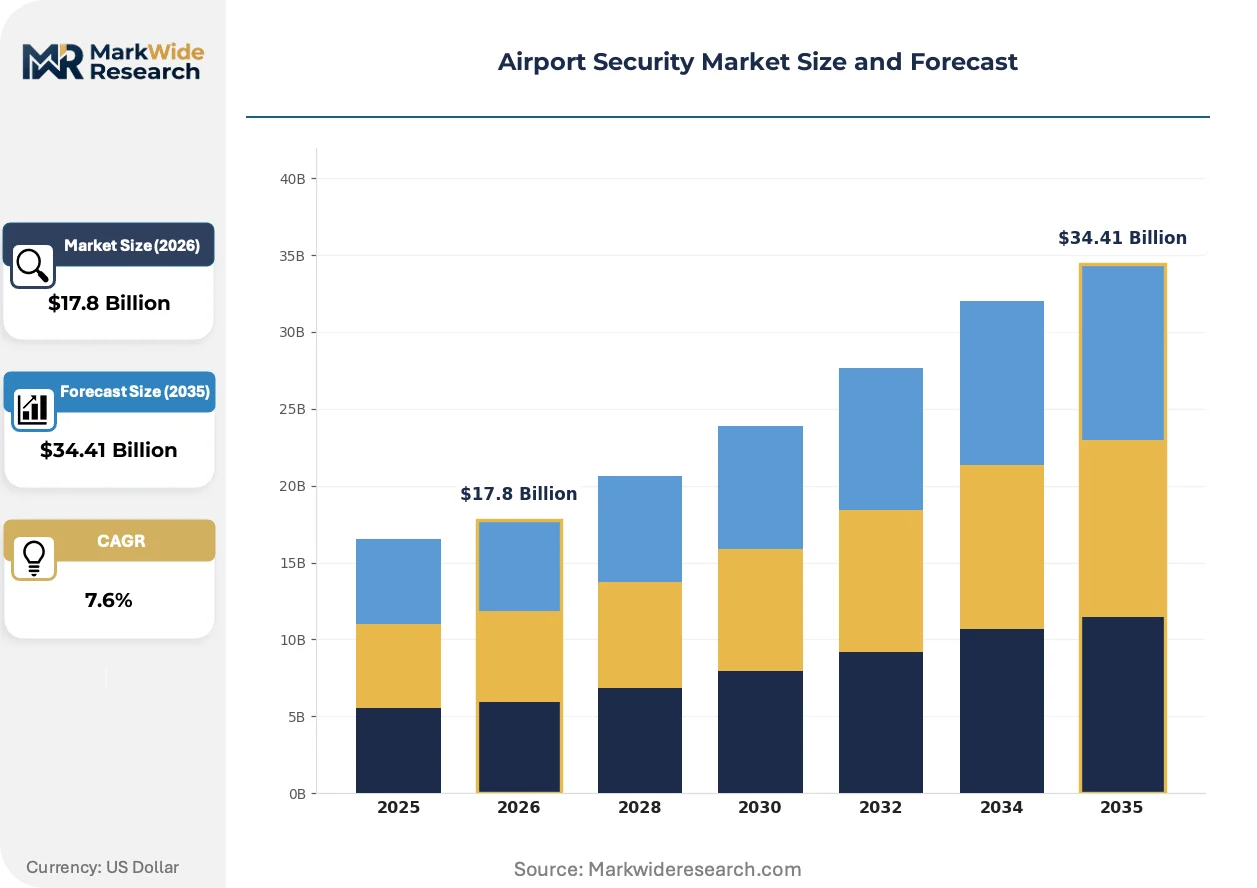
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $34.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: X-ray Scanners, Metal Detectors, Biometrics, Explosives Trace Detection Application: Passenger Screening, Baggage Screening, Cargo Screening, Access Control End User: Airports, Airlines, Government Agencies, Security Providers Installation: Fixed Systems, Mobile Systems, Integrated Solutions, Temporary Installations |
| Companies Covered | Smiths Detection, Rapiscan Systems, Leidos, Thales Group, Honeywell International, OSI Systems, Bosch Sicherheitssysteme GmbH, L3Harris Technologies, SITA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Security Market Emerging Trajectories
Computational detection methods and regulatory mandates for automated decision-making are restructuring how screening performance is validated, purchased, and operated across civil aviation infrastructure.
Deep-learning-based automated threat detection is collapsing the historical trade-off between false-alarm rates and detection probability in hold-baggage screening. Major hub operators in the United Arab Emirates and the Netherlands are deploying these algorithms in live operational environments. The technology is collapsing inspection lane staffing models by enabling single-operator monitoring of multiple CT streams.
The EU AI Act imposes algorithmic transparency and human-oversight requirements on biometric identification systems deployed at Schengen Area airports. Equipment vendors must now document training data provenance and decision-logic interpretability to secure procurement contracts. Facial recognition gate deployments at Paris Charles de Gaulle and Frankfurt airports are restructuring vendor qualification criteria around explainability documentation.
Airport authorities are consolidating security system procurement under long-term service contracts bundling hardware, software maintenance, and detection algorithm updates. This displaces traditional capital-purchase models with availability-based payment structures. The shift is most visible in Saudi Arabia's GACA terminal developments and Indonesia's Soekarno-Hatta expansion, where operators prioritize operational expenditure predictability over asset ownership.
Airport Security Market Segmentation
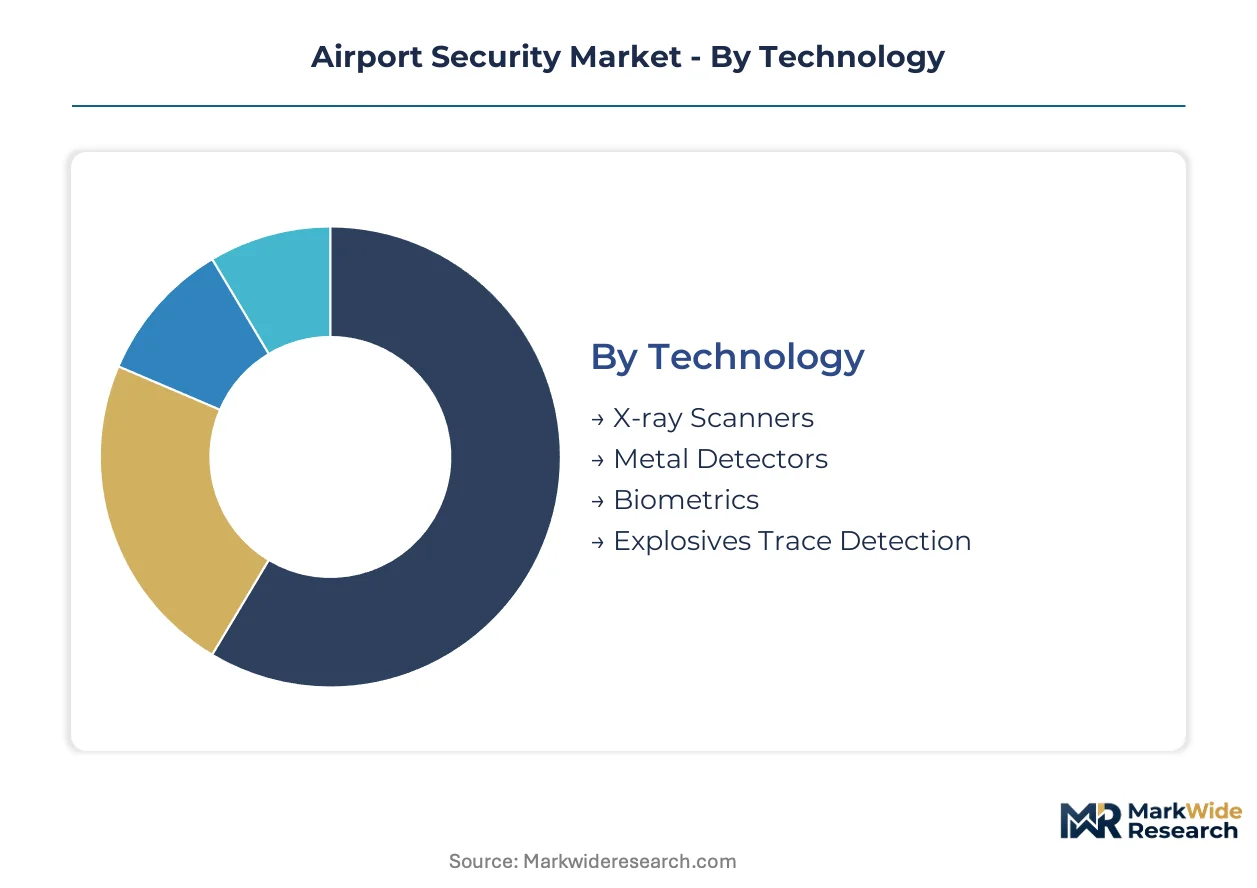
Technology refresh cycles vary dramatically across airport security equipment, with biometric systems turning over every 3-5 years while fixed X-ray infrastructure persists for 15-20 years. Understanding these differential replacement velocities shapes capital planning and vendor relationship strategies for hub operators and system integrators.
Technology:
Replacement velocity separates short-cycle software-driven segments from long-cycle hardware infrastructure, creating divergent vendor margin profiles and customer switching costs.
- X-ray Scanners:Tube voltages of 160-300 kV enable material discrimination for automated explosives detection under TSA and EASA certification protocols. Demand concentrates at Dubai International Airport and Amsterdam Schiphol as these hubs replace legacy 2D systems with computed tomography reconstruction engines.
- Biometrics:Facial recognition gates process passengers through document-free boarding corridors using deep-learning matching algorithms. Singapore Changi Airport and Paris Charles de Gaulle drive procurement as EU AI Act transparency mandates reshape vendor qualification criteria around explainable AI documentation.
- Metal Detectors:Active millimeter-wave portals remain the workhorse for primary passenger screening lanes at high-throughput terminals.
- Explosives Trace Detection:Ion mobility spectrometry and mass spectrometry systems target trace particle and vapor detection at checkpoint pinch points.
X-ray scanners dominate installed base across major aviation hubs. Biometrics is where expansion concentrates, climbing the fastest as facial recognition gates displace manual document verification.
Application:
Throughput pressure and regulatory scrutiny intensity vary sharply across screening domains, with cargo facing the most severe capacity constraints relative to existing infrastructure.
- Passenger Screening:Checkpoint lanes integrate multiple sensor modalities—millimeter-wave portals, X-ray divestiture systems, and biometric identity verification—into unified operational flows. Staffing optimization at London Heathrow and Frankfurt Airport drives demand for single-operator multi-lane monitoring configurations.
- Cargo Screening:E-commerce air freight volumes strain inspection capacity at integrator hubs, forcing adoption of automated explosives detection systems with throughput rates exceeding 1000 parcels per hour. Dual-use CT platforms capable of hold-baggage and air-cargo inspection reduce capital duplication for operators.
- Baggage Screening:Hold-baggage systems operate under EASA Standard 3 and TSA-certified detection thresholds with mandatory operational availability metrics.
- Access Control:Perimeter and restricted zone entry systems deploy biometric and credential-based verification for crew, ground handling, and maintenance personnel.
Passenger screening commands the largest revenue pool. Cargo screening is where investment urgency is most acute, gaining share fastest as parcel volumes outpace inspection capacity expansion.
End User:
Procurement authority fragmentation creates multiple entry points for equipment vendors, with each stakeholder type wielding distinct technical specifications and contract structures.
- Airports:Terminal operators at mega-hubs like Dubai International and Singapore Changi specify integrated security architectures bundling hardware, software maintenance, and algorithm updates under long-term service contracts. Saudi Arabia's GACA developments prioritize operational expenditure predictability over asset ownership.
- Government Agencies:National aviation security regulators mandate certification protocols and detection thresholds that shape product development roadmaps for the entire supply base.
- Airlines:Carrier-specific requirements for crew screening and VIP lounge access drive niche procurement outside terminal operator contracts.
- Security Providers:Contract screening companies operate equipment under airport concession agreements with limited capital authority.
Airports dominate capital deployment decisions. Government agencies control market access through certification requirements, concentrating influence over vendor qualification.
Installation:
Capital intensity and operational flexibility trade-offs structure procurement choices, with mobility premiums justified by specific operational scenarios rather than general deployment.
- Fixed Systems:Permanent conveyor infrastructure and portal installations anchor primary screening lanes at established terminals. Legacy 2D X-ray integration challenges create software-hardware compatibility failures when upgrading to CT reconstruction engines.
- Integrated Solutions:Command-and-control platforms fuse multiple sensor streams into unified operational pictures for security operations centers. Leidos competes on these architectures at US hub retrofits.
- Mobile Systems:Trailer-mounted and portable screening units address temporary capacity surges, construction phases, and emergency response requirements.
- Temporary Installations:Rapidly deployable screening lanes serve event-driven demand spikes and terminal renovation periods.
Fixed systems anchor the installed base across major aviation infrastructure. Integrated solutions attract the steepest expansion trajectory as operators consolidate fragmented sensor networks under unified management platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai International Airport's Terminal 3 expansion anchors Middle Eastern procurement intensity for next-generation screening infrastructure. This hub's biometric passenger processing deployment sets throughput benchmarks adopted across emerging aviation markets.
United States
TSA certification protocols compress product launch timelines for detection algorithm developers. The FAA coordinates airport security standards with national aviation safety frameworks. Atlanta Hartsfield-Jackson and Dallas-Fort Worth anchor retrofit programs replacing legacy 2D X-ray with computed tomography reconstruction engines.
Germany
EASA Standard 3 mandates accelerate hold-baggage screening replacement cycles at Frankfurt and Munich hubs. The country's national aviation regulator enforces implementing regulation 2015/1998 detection thresholds. Hamburg's specialized 160-300 kV X-ray tube manufacturing concentrates supply for CT scanner OEMs.
United Arab Emirates
Dubai International Airport's facial recognition gate deployment reduces boarding friction and lane staffing requirements. The General Civil Aviation Authority prioritizes operational expenditure predictability over asset ownership in terminal developments. Abu Dhabi International mirrors this procurement model for integrated security system contracts.
Singapore
Changi Airport's biometric passenger processing corridors displace manual document verification at boarding pinch points. The Civil Aviation Authority of Singapore harmonizes standards with ICAO interoperability frameworks. The airport-city cluster drives facial recognition gate procurement volume across Southeast Asian retrofit programs.
India
Greenfield terminals at Navi Mumbai and Jewar create first-mover positioning for integrated security system providers. The Bureau of Civil Aviation Security mandates detection thresholds shaping vendor qualification. Delhi Indira Gandhi International anchors capacity expansion with dual-use CT platforms for hold-baggage and air-cargo inspection.
Airport Security Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying detection algorithms and sensor modules. The vendor base concentrates among defense-electronics conglomerates with aviation security divisions and specialized screening equipment manufacturers. Three archetypes dominate: CT baggage screening specialists, biometric identity platform providers, and integrated command-and-control architects. Competitive positioning hinges on TSA/EASA certification maintenance and long-term service contract capture.
Within the integrated platform tier, Smiths Detection, Leidos, and Rapiscan Systems exemplify divergent strategic positions. Smiths Detection anchors hold-baggage applications through computed tomography reconstruction engines. Leidos occupies a position in unified operational picture platforms fusing multiple sensor streams. Rapiscan Systems represents North American manufacturing scale through dense airport retrofit program execution.
| Leading Market Players |
|---|
| Smiths Detection |
| Rapiscan Systems |
| Leidos |
| Thales Group |
| Honeywell International |
| OSI Systems |
| Bosch Sicherheitssysteme GmbH |
| L3Harris Technologies |
| SITA |
| Others |
Supply Flow & Price Mechanics
Hamburg's specialized 160-300 kV X-ray tube manufacturing cluster anchors upstream capacity for CT scanner OEMs, concentrating supply-side pricing power among German and Japanese component vendors while downstream terminal operators face compressed margins on detection algorithm upgrades.
Pricing Analysis
EASA Implementing Regulation 2015/1998 dictates the pricing tier structure across hold-baggage screening equipment, separating certified Standard 3 systems from legacy 2D X-ray platforms. Three-tier pricing structure across premium, standard, and economy levels reflects detection algorithm sophistication, throughput capacity, and bundled service contract duration. Cost compression in the standard tier is intensifying because airport operators prioritize operational expenditure predictability over capital ownership. Regional carriers and contract screening companies exhibit the highest price sensitivity, while mega-hubs like Dubai International and Singapore Changi prioritize performance specifications over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German and Japanese X-ray tube manufacturers have become critical liquidity tools for CT scanner OEMs managing 18-24 month TSA certification timelines. Manufacturing concentrates in Germany, Japan, and the United States for specialized high-voltage components, detection sensors, and reconstruction engines. Raw material dependencies include tungsten filament supplies, scintillator crystals, and high-purity aluminum housing alloys. Single-source vulnerability in 160-300 kV tube production creates structural risk for equipment delivery schedules. Distribution runs through direct OEM-terminal operator contracts and systems integrator partnerships for retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity because long-term availability-based contracts bundling hardware, software maintenance, and detection algorithm updates are expanding faster than standalone equipment sales across Saudi GACA and Indonesian terminal developments.
For Market Incumbents: Pre-empt passive millimeter-wave substitution threats by accelerating deep-learning algorithm deployment in live operational environments at UAE and Netherlands hubs. Secure backward integration into scintillator crystal and high-voltage power supply manufacturing to reduce exposure to German and Japanese component concentration. Maintain TSA and EASA certification currency as a competitive moat against emerging detection technology vendors.
For New Entrants and Emerging Players: Establish a beachhead in India's greenfield terminal developments at Navi Mumbai and Jewar, where first-mover positioning remains open for integrated security system providers. Target biometric identity platforms for mid-tier airports in Southeast Asia, where EU AI Act transparency mandates have disqualified incumbent vendors lacking explainable AI documentation. Pursue cargo-to-passenger screening convergence opportunities with dual-use CT platforms that reduce hub capital duplication.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because terminal operators are consolidating procurement under 10-15 year service contracts with availability-based payment structures. Acquisition targets should emphasize vendors with in-house machine-learning development capabilities and established EASA/TSA certification portfolios. Watch for inflection when India airport privatization wave accelerates from greenfield into brownfield retrofit phases.
| Strategic Initiative | Industry Significance |
|---|---|
| Detection Algorithm Acquisition | Deep-learning threat detection capabilities collapse false-alarm rates at Dubai International CT deployments. |
| Biometric Platform Integration | Facial recognition gates at Paris Charles de Gaulle restructure vendor qualification around EU AI Act compliance. |
| Dual-Use CT Platform Development | Hold-baggage and air-cargo inspection convergence reduces capital duplication for Delhi Indira Gandhi International. |
| Long-Term Service Contract Capture | Availability-based payment structures at Saudi GACA terminals displace traditional capital-purchase models. |
| Explainable AI Documentation Investment | Algorithmic transparency requirements under EU AI Act reshape procurement criteria for biometric deployment contracts. |
Methodological Framework
The analysis maps hold-baggage screening, biometric passenger processing, cargo inspection, and access control sub-sectors, each validated through airport security directors, TSA certification engineers, EASA regulatory affairs leads, and terminal procurement managers. Primary interview findings triangulate against EASA implementing regulation filings, TSA certification databases, ICAO standards documentation, and airport operator annual procurement disclosures. Bottom-up equipment unit economics and top-down terminal capital expenditure forecasts converge to establish market sizing boundaries.
Assumptions around EASA Standard 3 compliance timelines, biometric passenger processing adoption curves, and e-commerce air freight volume trajectories were held fixed across the projection horizon while detection algorithm performance parameters and certification protocol modifications were stress-tested. Segmentation modeling spans technology type, application domain, end-user authority, and installation configuration. CAGRs derive from terminal capacity expansion pipelines and replacement cycle compression analysis. Forecast inputs include Dubai International and Singapore Changi procurement benchmarks, plus India greenfield terminal development schedules.
Stress conditions across TSA certification timeline extensions, EU AI Act enforcement intensity, and X-ray tube supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and boundary conditions. Macroeconomic contraction affecting aviation passenger volumes, regulatory deviation from EASA Standard 3 mandates, or breakthrough passive screening technology maturation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Alarm Monitoring [Central Stations] Software Market
Security and Surveillance
Night Vision Scopes Market
Security and Surveillance
Burglar Alarm Systems Market
Security and Surveillance
Latin America Security Services Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
Home Security Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Global Integration Security Services Market
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Europe Security Testing Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
Global Security and Vulnerability Management Market
Security and Surveillance
Global School and Campus Security Market
Security and Surveillance
Global Wireless Doorbells Market
Security and Surveillance
Europe People Screening Market
Security and Surveillance
Global Alarm Monitoring Market