
 Europe Rockfall Radar Market | 2026-2036
Europe Rockfall Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Rockfall Radar Market Insights
European ground-based sensor manufacturing is consolidating around specialized geotechnical firms. IDS GeoRadar leverages its interferometric radar heritage to dominate alpine slope monitoring contracts. Geobrugg AG anchors its position through captive supply of steel protection systems paired with radar validation. Hexagon AB extends its metrology expertise into integrated rockfall detection networks across Nordic infrastructure authorities.
Rockfall radar encompasses ground-based, UAV-based, satellite, and lidar technologies that detect millimetric surface displacement across unstable rock faces using Doppler or phase-shift principles, primarily to trigger automated traffic halts or evacuation alerts before mass detachment. Ground-based radar retains the largest installed base due to proven all-weather reliability in steep terrain, though UAV-based radar captures the fastest expansion as battery endurance and payload miniaturization improve. Infrastructure monitoring commands the deepest margin pools because long-term service contracts attach to detection hardware, while mining operations compete predominantly on upfront equipment cost.
The EU Green Deal's natural hazard resilience targets and the F-Gas Regulation's constraints on cooling-dependent lidar systems shape product development trajectories across the continent. ECHA's chemical restrictions on sensor coatings and the EU AI Act's transparency requirements for automated alert algorithms complicate certification timelines for new entrants. Stakeholders must weigh interoperability standards against proprietary data formats as procurement shifts toward multi-hazard platform integration.
Market Dynamics
The EU AI Act's transparency mandates for automated alert systems are compressing certification timelines and forcing vendors to reengineer algorithmic validation workflows before alpine railway contracts can close.
Growth Catalysts
- Alpine corridor infrastructure mandates:Switzerland's Federal Office of Transport requires continuous slope monitoring along Gotthard and Lötschberg axes, mandating radar deployment for tunnel portals and cuttings.
- F-Gas Regulation constraints:Cooling-dependent lidar systems face phase-out timelines under EU fluorinated gas restrictions, redirecting procurement toward solid-state radar alternatives.
- Interferometric SAR advances:Phase-unwrapping algorithms now resolve millimetric displacement across kilometer-scale rock faces, extending monitoring range without sensor densification.
Market Restraints
- Gallium arsenide supply concentration:High-frequency radar front-end components depend on wafer fabrication concentrated in East Asian foundries, exposing lead times to geopolitical friction.
- EU Green Deal implementation gaps:Member state transposition timelines for natural hazard resilience targets remain uneven, delaying centralized procurement in Mediterranean jurisdictions.
- Line-of-sight geometry constraints:Steep alpine topography creates radar shadow zones requiring redundant sensor placement, inflating installed cost per monitored kilometer.
Strategic Opportunities
- Italian Apennine underpenetration:Central Italy's clay-rich slopes experience frequent detachment events yet carry sparse radar coverage compared to Alpine benchmarks.
- UAV-radar convergence:Battery endurance improvements now enable 90-minute autonomous flight profiles, allowing rapid post-event damage assessment without helicopter mobilization.
- CSRD disclosure requirements:Corporate sustainability reporting mandates for climate-related physical risks are pushing mining operators toward documented slope monitoring investments.
Industry Challenges
- Geotechnical-radar interdisciplinary talent scarcity:Vendors struggle to hire engineers conversant in both rock mechanics and microwave signal processing.
- CE marking timeline compression:ECHA chemical restrictions on sensor coatings add validation loops to hardware certification, delaying product launches.
- Legacy SCADA integration friction:Railway operators operate decades-old traffic control architectures that resist API-based alert injection from modern radar systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Rockfall Radar Market |
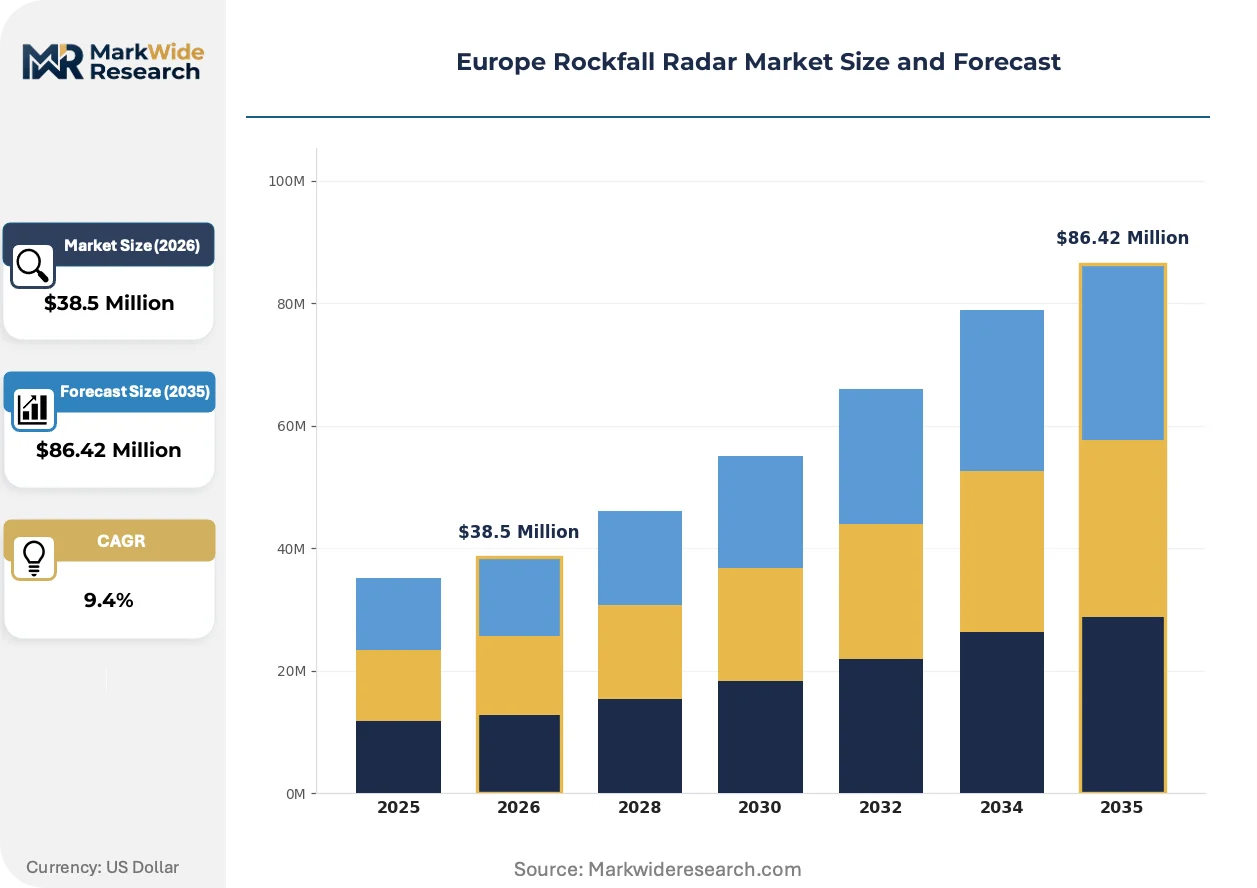
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $86.42 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ground-Based Radar, UAV-Based Radar, Satellite Radar, Lidar Application: Mining Operations, Infrastructure Monitoring, Environmental Protection, Natural Disaster Management End User: Construction Companies, Government Agencies, Environmental Consultants, Mining Firms Distribution Channel: Direct Sales, Online Channels, Distributors, Resellers |
| Companies Covered | IDS GeoRadar, Geobrugg AG, Hexagon AB, GroundProbe, Geosense Ltd, SkyGeo, RIEGL Laser Measurement Systems GmbH, GeoSIG Ltd, Sisgeo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Rockfall Radar Market Trends and Innovations
Signal processing architectures and procurement frameworks are undergoing parallel reinvention as buyers demand platform interoperability and vendors pursue hardware-software unification.
Ground-based interferometric radar is converging with edge-computing inference engines to enable on-slope debris trajectory prediction without cloud latency. Austrian Federal Railways pilots this architecture along Arlberg corridor sections. The convergence compresses alert issuance from detection to traffic halt from 30 seconds to under 8 seconds.
REACH authorization requirements for persistent organic pollutants in electronic substrates are forcing substrate material substitutions in radar transceiver modules. German component suppliers report 14-month validation cycles for halogen-free laminates. Nordic infrastructure authorities now specify REACH-compliant hardware in tender technical annexes.
Swiss cantonal procurement offices are consolidating multi-hazard monitoring contracts that bundle rockfall radar with debris-flow sensors and avalanche detection under single-service agreements. The model displaces point-solution vendors unable to integrate across threat categories. Ticino and Valais cantons executed the first such consolidated awards in 2024.
Europe Rockfall Radar Market Segmentation
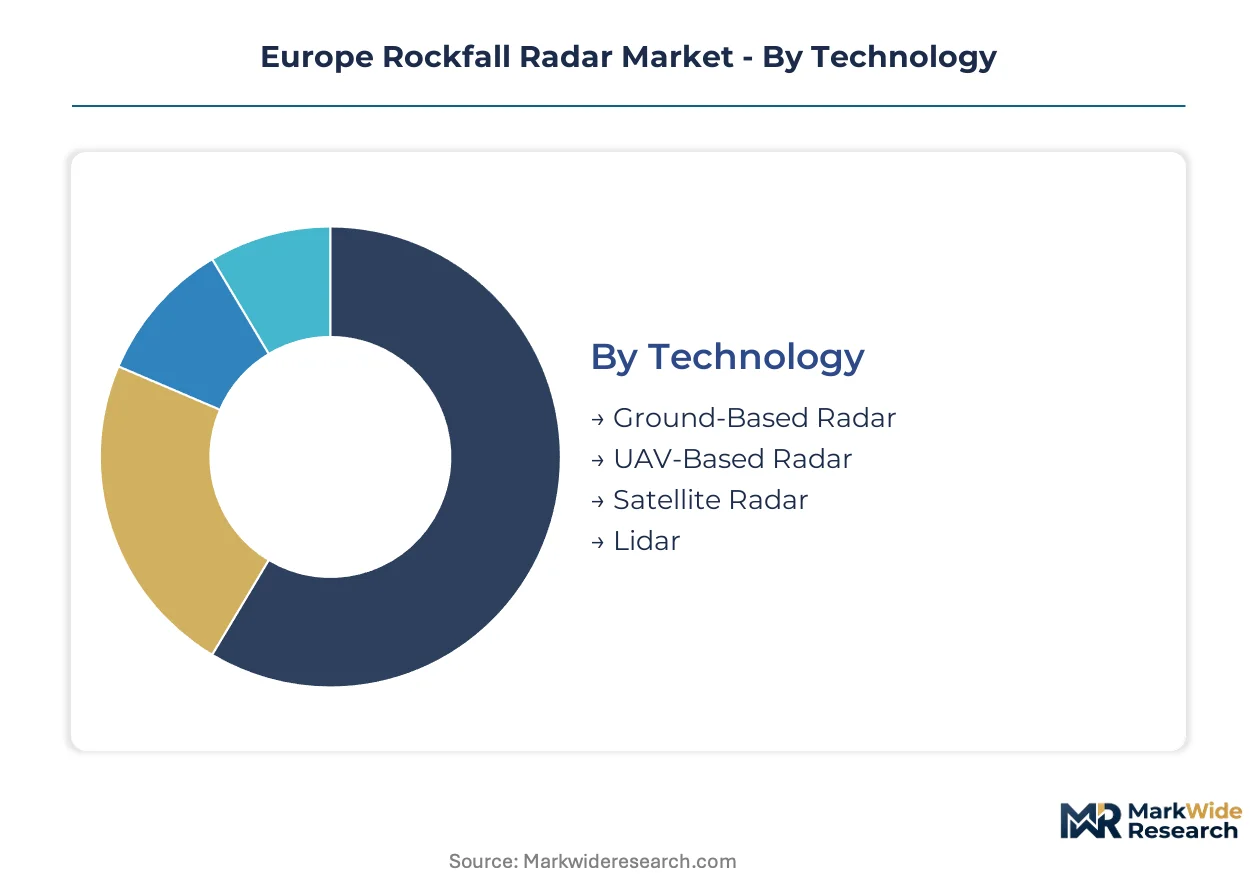
Rockfall radar procurement splits across four distinct axes: sensing modality, operational deployment, institutional buyer type, and supply pathway. Each dimension carries different capital thresholds, contract structures, and regulatory compliance burdens that reshape vendor go-to-market economics.
Technology:
Capital intensity peaks with fixed infrastructure installations requiring civil works and power grid connections, while portable and aerial platforms shift cost structures toward operational expenditure.
- Ground-Based Radar:Permanent interferometric installations with tripod or tower mounting achieve all-weather reliability in alpine shadow zones. Swiss Federal Railways and Austrian Federal Railways anchor demand along transalpine corridors where 24/7 monitoring is mandatory. CE marking and ECHA coating compliance extend deployment timelines but lock in decade-long service contracts.
- UAV-Based Radar:Miniaturized synthetic aperture payloads on extended-endurance drones enable rapid post-event surveys without helicopter mobilization. Italian civil protection agencies in Ticino and Lombardy drive adoption for emergency damage assessment where road access fails. Battery chemistry improvements and payload weight reduction are accelerating procurement cycles.
- Satellite Radar:Orbital interferometric platforms cover vast catchment areas with revisit intervals measured in days. European Space Agency data access programs lower entry costs for national geological surveys.
- Lidar:Laser scanning systems face phase-out pressure under EU F-Gas Regulation cooling restrictions, redirecting investment toward solid-state alternatives.
Most installed capacity flows through Ground-Based Radar. Expansion is steepest in UAV-Based Radar.
Application:
Contract duration and margin structure diverge sharply between short-cycle mining tenders and multi-decade infrastructure concessions.
- Infrastructure Monitoring:Railway and highway operators commission continuous slope surveillance with automated traffic integration. Alpine tunnel portals in Switzerland, Austria, and France command the deepest recurring revenue pools through integrated detection-alert-halt systems.
- Mining Operations:Open-pit extraction sites in Scandinavia and Iberia prioritize rapid deployment and equipment mobility over permanent installation. Procurement competes predominantly on upfront capital cost with limited service attachment.
- Environmental Protection:National park authorities and watershed managers track cliff retreat and sediment yield for long-term geomorphological studies. EU Green Deal resilience targets are channeling cohesion funds into Apennine and Pyrenean coverage gaps.
- Natural Disaster Management:Regional civil protection commands deploy rapid-response radar units following seismic events or extreme precipitation. Italian and French alpine prefectures maintain standby contracts with specialized geotechnical firms.
Infrastructure Monitoring captures the largest contract value. Mining Operations represent the fastest-growing trajectory by unit volume.
End User:
Buyer sophistication and procurement authority determine sensor specification, integration complexity, and vendor selection criteria.
- Government Agencies:National transport ministries and regional civil protection commands mandate interoperability with legacy SCADA and traffic management architectures. Swiss cantonal procurement offices now bundle multi-hazard monitoring under consolidated service agreements.
- Mining Firms:Nordic and Iberian extraction operators face Corporate Sustainability Reporting Directive disclosure requirements for climate-related physical risks, pushing documented slope monitoring investments.
- Construction Companies:Major alpine tunneling consortia deploy temporary radar arrays during excavation phases with mandatory monitoring of adjacent slopes.
- Environmental Consultants:Specialized geotechnical firms contract radar services for project-specific risk assessments and regulatory compliance filings.
Government Agencies dominate installed base. Mining Firms are expanding procurement most quickly as CSRD compliance deadlines approach.
Distribution Channel:
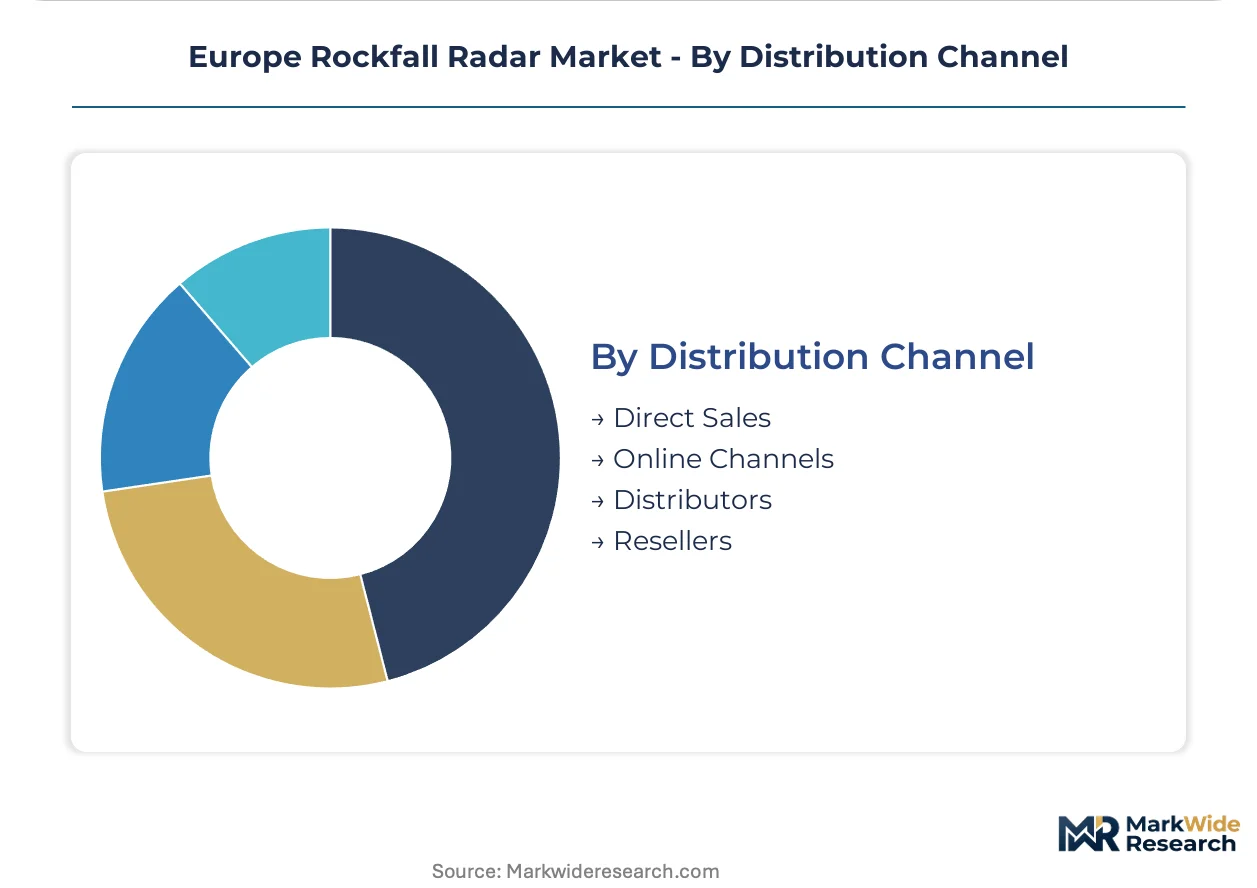
Channel selection reflects contract scale, technical complexity, and buyer procurement maturity.
- Direct Sales:Large infrastructure operators and mining houses negotiate directly with radar manufacturers for customized system integration and long-term maintenance. Austrian Federal Railways and Swiss Federal Office of Transport award multi-year framework agreements.
- Distributors:Regional geotechnical equipment specialists stock standardized radar units for mid-tier construction and environmental consultancy clients. German and Italian distributors anchor continental coverage.
- Resellers:System integrators bundle radar hardware with software platforms and installation services for buyers lacking in-house technical capacity.
- Online Channels:Limited to consumables, spare transceiver modules, and documentation for existing installations.
Direct Sales capture the majority of contract value. Distributors are gaining share fastest among mid-market environmental and construction segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radar manufacturers face divergent compliance burdens across European jurisdictions, with CE marking timelines stretching longest in Mediterranean states where ECHA coating restrictions encounter weaker administrative capacity. This regulatory-arbitrage dynamic concentrates new production qualification activity in German and Swiss testing facilities.
Switzerland
Federal Office of Transport mandates govern continuous slope monitoring along Gotthard and Lötschberg rail corridors, requiring radar deployment at every tunnel portal. Swissmedic-equivalent certification for automated alert systems operates faster than EU notified body timelines. Ticino and Valais cantons executed consolidated multi-hazard monitoring contracts in 2024, bundling rockfall radar with debris-flow and avalanche detection.
Austria
Austrian Federal Railways pilots edge-computing radar architectures along the Arlberg corridor, compressing alert-to-halt intervals from 30 seconds to under 8 seconds. National transport safety regulations align closely with Swiss standards, facilitating cross-border equipment qualification. Vorarlberg and Tyrol provinces anchor alpine deployment density, with Innsbruck-based integrators handling installation workflows.
Italy
Central Apennine slopes experience frequent detachment events yet carry sparse radar coverage compared to Alpine benchmarks, creating procurement gaps that cohesion funds now target. EU Green Deal resilience targets channel investment toward clay-rich slope monitoring in Abruzzo and Marche regions. Lombardy and Ticino civil protection agencies drive UAV-based radar adoption for post-event damage assessment.
France
Alpine prefectures maintain standby contracts with specialized geotechnical firms for rapid-response radar deployment following seismic events. ANSM-equivalent safety oversight applies to automated traffic halt systems integrated with national railway infrastructure. Provence-Alpes-Côte d'Azur and Auvergne-Rhône-Alpes regions concentrate both permanent installations and mobile response capacity.
Germany
Bavarian and Baden-Württemberg transport authorities specify REACH-compliant hardware in tender technical annexes, responding to ECHA restrictions on sensor substrate materials. Component suppliers report 14-month validation cycles for halogen-free laminates in radar transceiver modules. Stuttgart and Munich industrial clusters host qualification laboratories serving adjacent alpine markets.
Europe Rockfall Radar Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue UAV-platform miniaturization and satellite-data integration. The vendor base clusters around three strategic archetypes: geotechnical instrumentation specialists leveraging interferometric heritage, integrated protection system providers bundling steel barriers with radar validation, and metrology conglomerates extending precision measurement expertise into slope monitoring networks. Dominant competitive moves include backward integration into sensor substrate manufacturing to escape gallium arsenide supply constraints, and geographic expansion through cantonal procurement consolidation in alpine jurisdictions.
Within the geotechnical instrumentation tier, IDS GeoRadar and Geosense Ltd exemplify firms anchored by radar heritage and slope-monitoring specialization respectively. Hexagon AB occupies a position representing metrology-to-infrastructure extension, while Geobrugg AG exemplifies the integrated protection-system archetype through its captive supply of steel validation structures. GroundProbe and RIEGL Laser Measurement Systems GmbH sit within adjacent technology domains that compete for overlapping procurement budgets.
| Leading Market Players |
|---|
| IDS GeoRadar |
| Geobrugg AG |
| Hexagon AB |
| GroundProbe |
| Geosense Ltd |
| SkyGeo |
| RIEGL Laser Measurement Systems GmbH |
| GeoSIG Ltd |
| Sisgeo |
| Others |
Pricing and Supply Chain Analysis
Alpine railway procurement offices in Switzerland and Austria anchor contract values through decade-long framework agreements that lock in premium pricing for interferometric radar systems with automated traffic integration. This buyer concentration rewards vendors who bundle hardware validation with multi-hazard service contracts, compressing price competition among point-solution providers.
Pricing Analysis
Distributor margins in German and Italian geotechnical equipment channels compress pricing for standardized ground-based radar units sold to mid-tier construction consultancies. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked alpine installations from temporary mining deployments and bare-bones sensor hardware. Cost compression in portable UAV-based systems is intensifying because payload miniaturization advances enable new entrants to undercut established interferometric suppliers. Mining operators in Scandinavia exhibit highest price sensitivity due to procurement competing predominantly on upfront capital cost, while Swiss Federal Railways demonstrates lowest sensitivity given mandatory continuous monitoring requirements.
Supply Chain Analysis
Gallium arsenide wafer fabrication rests on East Asian foundry concentration in Taiwan, South Korea, and Japan, exposing European radar manufacturers to geopolitical friction in high-frequency front-end component sourcing. German component suppliers report extended validation cycles for REACH-compliant halogen-free laminates in radar transceiver modules, while Austrian integrators handle installation workflows anchored in Vorarlberg and Tyrol industrial clusters. Single-source vulnerability in specialized geotechnical-radar interdisciplinary talent pools constrains production scaling. Distribution runs through direct sales channels for large infrastructure operators and regional distributors for mid-market environmental consultancy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European rockfall radar procurement has shifted toward premium specifications as EU AI Act transparency mandates and ECHA coating restrictions force algorithmic revalidation and substrate material substitutions. This quality migration favors vendors with established certification infrastructure and captive supply chain control.
For Market Incumbents: Extend service contract bundling into consolidated multi-hazard monitoring agreements that displace point-solution competitors unable to integrate across rockfall, debris-flow, and avalanche detection categories. Deepen backward integration into gallium arsenide alternative substrates to escape East Asian foundry concentration risks. Invest in edge-computing inference architectures to compress alert-to-halt intervals below competitor benchmarks along alpine corridor contracts. For New Entrants and Emerging Players: Capture white-space deployment in Italy's clay-rich Apennine slopes where cohesion fund inflows now target coverage gaps compared to sparse existing radar infrastructure. Exploit UAV-radar convergence through extended-endurance battery platforms for rapid post-event damage assessment contracts with Lombardy and Ticino civil protection agencies. Position around REACH-compliant hardware specifications that German transport authorities now mandate in tender technical annexes. For Investors and Strategic Acquirers: Integrated protection system providers with captive steel barrier manufacturing are the most active acquirer in this space, pursuing radar validation capabilities to complete slope-safety solution stacks. Over the medium-term horizon, acquisition targets cluster around geotechnical instrumentation specialists with established interferometric heritage and alpine railway contract relationships. Watch for cantonal procurement consolidation in Swiss Ticino and Valais as inflection indicator for multi-hazard platform integration tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Substrates | Escapes gallium arsenide supply concentration in East Asian foundries for European radar manufacturers. |
| Edge-Computing Architecture Deployment | Compresses Austrian Federal Railways alert-to-halt intervals from 30 seconds to under 8 seconds. |
| Multi-Hazard Platform Integration | Displaces point-solution vendors as Swiss cantons consolidate rockfall, debris-flow, and avalanche contracts. |
| REACH-Compliant Hardware Qualification | Unlocks German and Bavarian transport authority tenders specifying halogen-free laminate validation. |
| UAV Payload Miniaturization | Enables 90-minute autonomous flight profiles for Italian civil protection post-event damage assessment. |
Research Methodology
Multiple input streams — primary interviews with railway infrastructure planners, geotechnical instrumentation specialists, and alpine corridor safety officers; secondary validation through ECHA regulatory filings, EU transport safety directives, and European Space Agency data access program documentation — were reconciled through bottom-up installation base enumeration and top-down market sizing across technology and application segments.
Data-stream reconciliation anchored projections across the analysis window through segmentation modeling across sensing modality, operational deployment, institutional buyer type, and supply pathway dimensions. CAGRs were derived from slope-monitoring investment trajectories tied to EU Green Deal resilience target transposition timelines and Corporate Sustainability Reporting Directive disclosure requirements for mining operators.
Geopolitical friction in semiconductor supply chains, uneven member state implementation of natural hazard resilience targets, and algorithmic validation timeline compression under EU AI Act mandates are the dominant revision risks that could alter trajectory assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Anti-Piracy Protection Market
Security and Surveillance
Signal Jamming Systems Market
Security and Surveillance
North America Security Screening Market
Security and Surveillance
Global School and Campus Security Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Asia-Pacific Security Screening Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Night Vision Scopes Market
Security and Surveillance
Underwater Security (Systems and Services) Market
Security and Surveillance
Destructible Security Labels Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
Security Operations Center Market
Security and Surveillance
Global Cargo Inspection Market
Security and Surveillance
Global Security Orchestration Market
Security and Surveillance
Manned Guarding Services Market