
 Flame Detector System Market | 2026-2036
Flame Detector System Market Size, Share, and Industry Trends Forecast 2026-2036
Flame Detector System Market Intelligence
The replacement of single-spectrum UV or IR sensors with advanced multi-spectrum detector arrays is restructuring product performance and cost hierarchies. This technological shift favors vendors with deep R&D capabilities. Honeywell International Inc. leverages its extensive portfolio in industrial automation to integrate these advanced systems. Siemens AG competes by offering comprehensive safety solutions for power generation clients, while Emerson Electric Co. specializes in solutions for hazardous environments within the oil and gas sector.
A flame detector system is an electro-optical device designed to identify the presence of a flame or fire through its characteristic radiation. It operates by analyzing specific spectral bands, such as ultraviolet or infrared, and triggers an alarm when a fire's unique signature is detected within milliseconds. UV/IR combination and multi-spectrum detectors command higher price points and are gaining share over standalone UV or IR models. Demand from oil & gas processing applications continues to dominate the market, while fire detection in power plants represents a critical secondary segment.
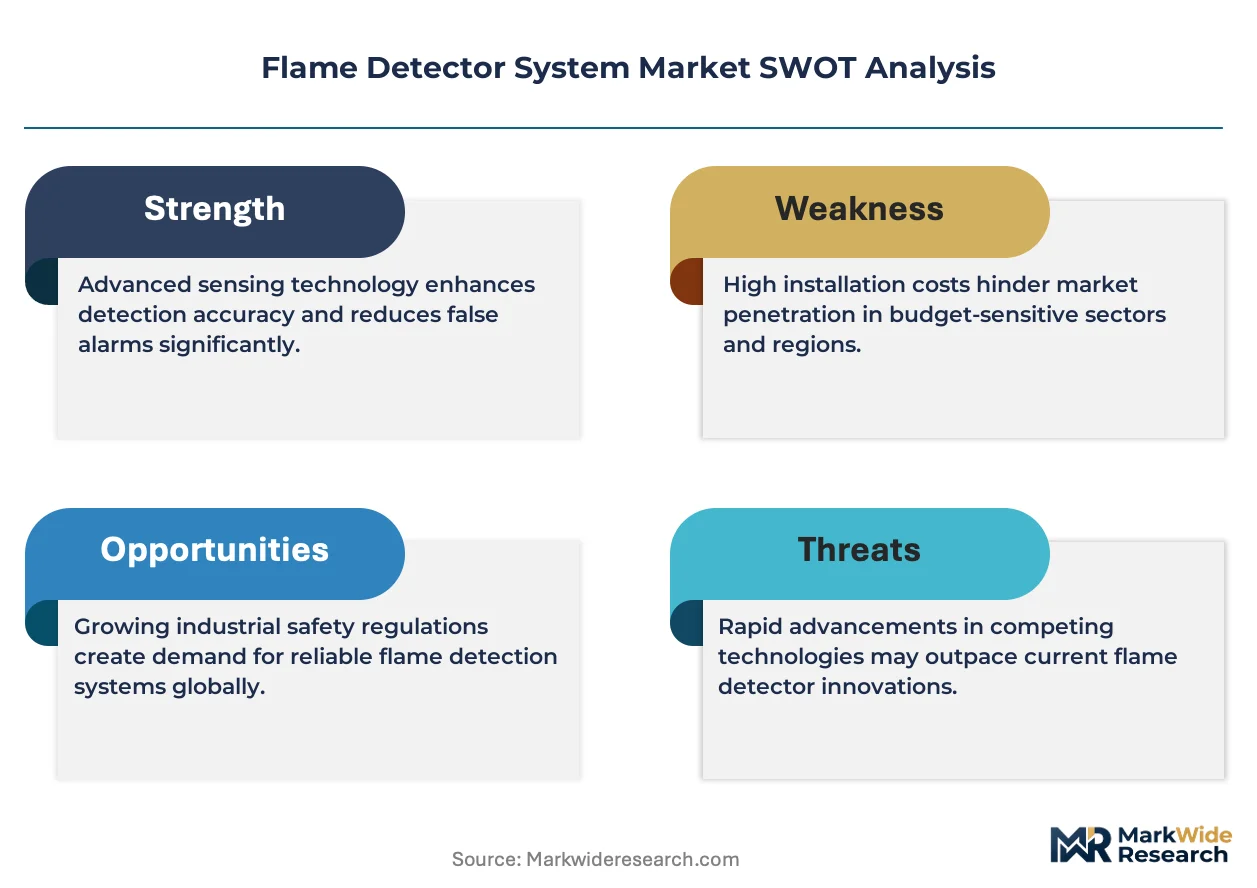
Product design and market access are governed by stringent safety certifications, including the ATEX directives in Europe and NFPA standards in the United States. Additionally, IECEx certification provides a framework for international compliance, ensuring equipment is safe for use in explosive atmospheres. Vendor success will depend on navigating the complex certification landscape and integrating AI-driven analytics to reduce false alarm rates.
Market Dynamics
The convergence of sophisticated multi-spectrum sensor technologies with increasingly stringent international safety mandates defines the market's core dynamic. This forces vendors to compete on both R&D innovation and the ability to navigate complex, multi-jurisdictional certification pathways like ATEX and IECEx.
Growth Catalysts
- Regulatory Mandates:Europe's ATEX directives and similar standards in other regions compel the adoption of certified flame detectors in industries like oil & gas, chemicals, and mining to ensure worker safety and prevent catastrophic events.
- Infrastructure Investment:Expansive capital projects in the Middle East, particularly for new oil refineries and petrochemical facilities, create sustained demand for advanced fire and gas detection systems as a fundamental component of plant design.
- Technology Advancement:The superior false alarm immunity of multi-spectrum UV/IR detectors compared to older single-spectrum models drives replacement cycles in critical applications, including power generation plants and offshore platforms, where operational continuity is paramount.
Market Restraints
- High Capital Cost:The significant price premium for advanced multi-spectrum and triple-IR detectors over basic UV or IR models can deter adoption for cost-sensitive end-users or in non-critical applications, slowing replacement cycles.
- Integration Complexity:Integrating new, digitally-native flame detection systems with legacy analog-based plant control systems and fire alarm panels presents significant technical hurdles and additional costs for industrial operators.
- Certification Barriers:The lengthy and expensive process of obtaining and maintaining multiple safety certifications, such as ATEX, IECEx, and NFPA, for different global markets creates a high barrier to entry for smaller manufacturers.
Strategic Opportunities
- Emerging Applications:The rapid buildout of battery energy storage systems (BESS) creates a new, high-value application for specialized flame detectors capable of identifying unique fire signatures associated with lithium-ion battery thermal runaway.
- AI Integration:Embedding artificial intelligence and machine learning algorithms directly into detector firmware offers a path to drastically reduce false alarms by analyzing environmental data and distinguishing real fires from non-threatening sources.
- Geographic Expansion:Rapid industrialization and a growing focus on safety standards in Southeast Asian nations, including Vietnam and Indonesia, present untapped growth opportunities for vendors beyond traditional markets.
Industry Challenges
- System Interoperability:A primary operational challenge is ensuring seamless communication and data exchange between flame detectors from different vendors and a facility's overarching Distributed Control System (DCS) or safety instrumented system.
- Technician Skill Gap:A shortage of field technicians with the combined expertise in electro-optics, network communications, and industrial safety protocols hinders the proper installation, calibration, and maintenance of advanced detection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flame Detector System Market |
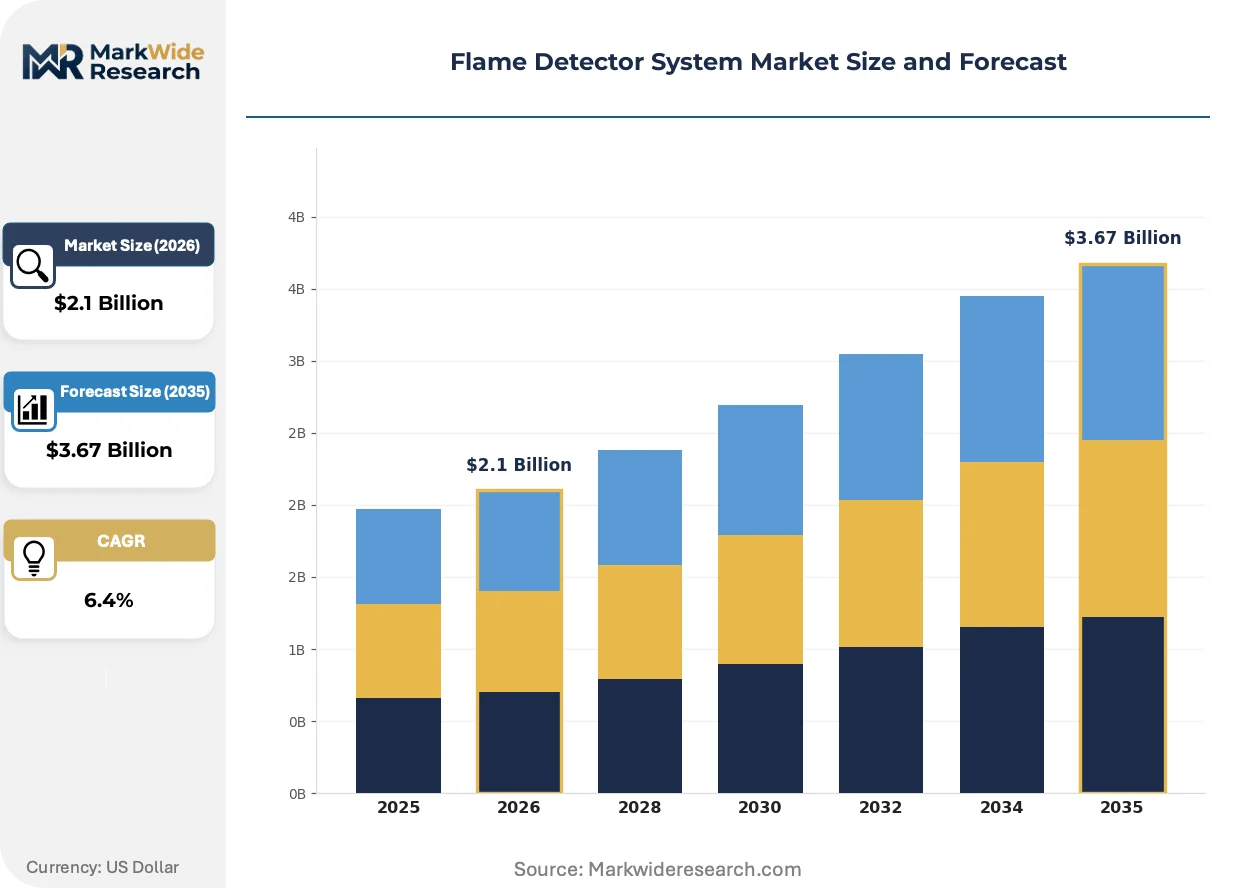
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Flame Detectors, IR Flame Detectors, UV/IR Combination Detectors, Multi-Spectrum Detectors, Solar-Blind Flame Detectors Technology: Optical Sensing, Infrared Thermography, Ultraviolet Detection, Ultraviolet-Infrared Fusion, Acoustic Flame Detection Application: Oil & Gas Processing, Fire Detection in Power Plants, Chemical Manufacturing Safety, Aerospace Testing Facilities, Industrial Furnaces End User: Refineries, Petrochemical Plants, Power Generation Plants, Manufacturing Units, Research Laboratories |
| Companies Covered | Emerson Electric Co., Det-Tronics, Honeywell International Inc., Teledyne Gas & Flame Detection, Micropack Engineering Ltd., Johnson Controls International Plc., Siemens AG, Hochiki Corp., MSA Safety Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flame Detector System Market Strategic Shifts & Innovations
The market is transitioning from a focus on simple event detection to intelligent, data-driven fire risk assessment. This evolution is propelled by advancements in sensor fusion, wireless connectivity, and embedded analytics that improve reliability and provide deeper operational insight beyond a basic alarm trigger.
Wireless flame detection technology, utilizing protocols like WirelessHART, enables flexible and rapid deployment in remote or difficult-to-wire locations. Oil and gas operators are adopting these for monitoring wellheads and temporary processing sites where hardwired infrastructure is cost-prohibitive. This trend is decentralizing system architecture, shifting intelligence from a central controller to autonomous, battery-powered nodes at the network's edge.
The IECEx certification scheme provides a globally harmonized framework for equipment intended for use in explosive atmospheres. This international standard simplifies global commerce by establishing a single conformity assessment process, reducing the need for duplicative national testing. Detector manufacturers are prioritizing IECEx compliance to accelerate market access into high-growth industrial sectors across the Middle East, Asia-Pacific, and Latin America.
A notable behavioral shift sees end-users in critical infrastructure moving away from simple capital equipment purchases toward performance-based service contracts. This model bundles the detector hardware with ongoing remote system monitoring, proof-testing, and software updates, often replacing traditional distributor sales channels for large-scale operators. This demand-side change is most visible within the power generation and LNG terminal segments, where certified operational uptime is the primary purchasing driver.
Flame Detector System Market Segmentation
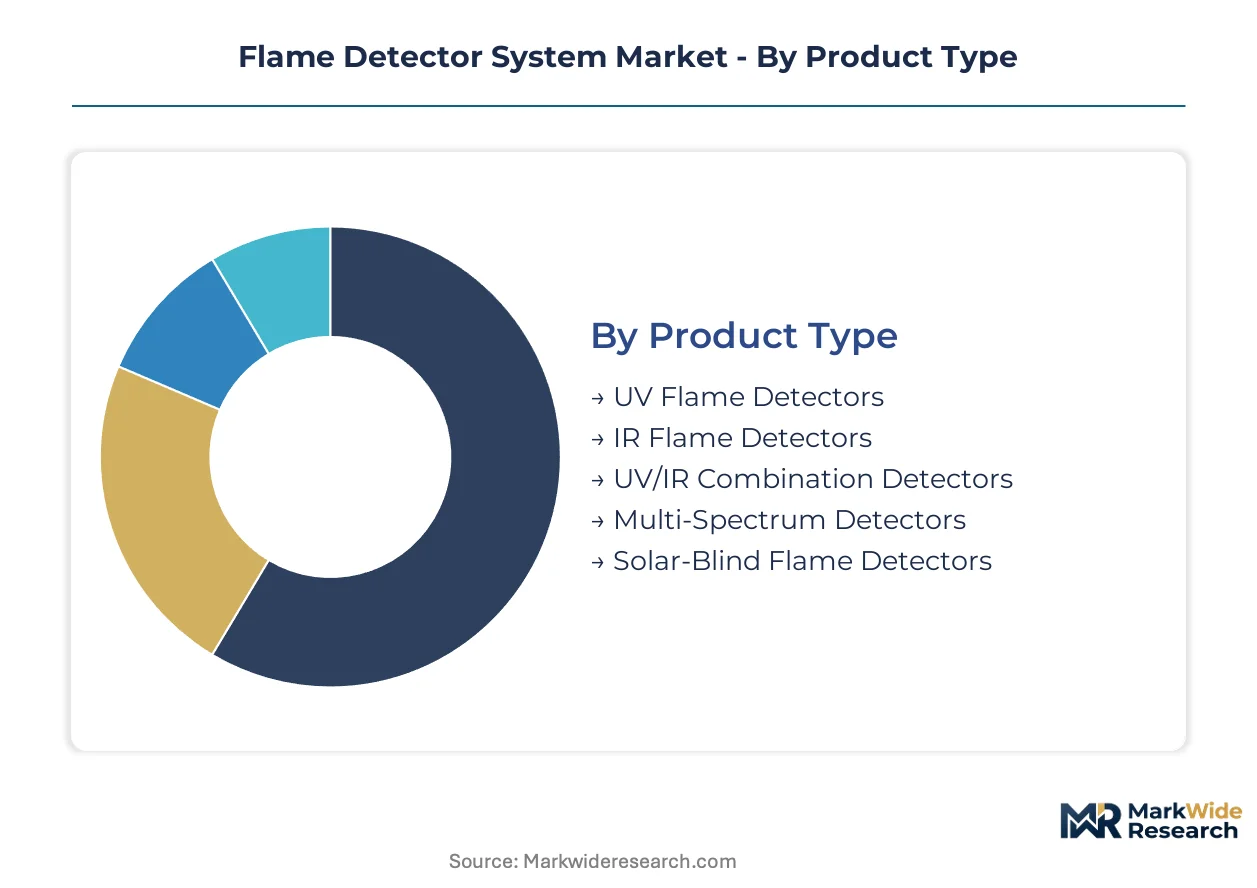
Market segmentation provides a critical framework for understanding the diverse needs and technological preferences within the flame detector system industry. This analysis highlights how varying product capabilities, underlying technologies, specific applications, and distinct end-user requirements shape demand and competitive dynamics across the sector.
Product Type:
Investment in flame detector systems often correlates with the upfront capital required for specific product types, influencing adoption rates in different industrial contexts.
- Multi-Spectrum Detectors:These advanced devices analyze multiple infrared (IR) spectral bands simultaneously to identify flame characteristics. Demand concentrates in high-risk environments like oil and gas processing, driven by superior false alarm immunity compared to single-spectrum models.
- UV/IR Combination Detectors:Combining ultraviolet (UV) and infrared (IR) sensors, these detectors provide enhanced reliability by requiring both signatures for alarm activation. Offshore platforms and petrochemical facilities represent key demand centers, valuing their improved detection capabilities in complex atmospheres.
- UV Flame Detectors:These units detect the ultraviolet radiation emitted by flames, offering rapid response times for clean-burning fires.
- IR Flame Detectors:Monitoring specific infrared wavelengths, these detectors are widely used for hydrocarbon fires and in areas prone to smoke.
- Solar-Blind Flame Detectors:Designed to ignore solar radiation, these UV detectors are specifically engineered for reliable outdoor use without nuisance alarms.
Most installed capacity flows through IR Flame Detectors. Expansion is steepest in Multi-Spectrum Detectors.
Technology:
Technological advancements in flame detection directly influence system reliability and response times across diverse industrial settings.
- Optical Sensing:This foundational technology utilizes light-based detection principles to identify flame characteristics across various spectral bands. Industrial furnaces and manufacturing units widely adopt optical sensing for its versatility and proven performance.
- Ultraviolet-Infrared Fusion:This technology integrates data from both UV and IR sensors, applying algorithms to cross-verify flame presence. Hazardous environments within the oil and gas sector drive its adoption, valuing the significant reduction in false alarms.
- Infrared Thermography:Utilizing thermal imaging, this technology detects heat signatures indicative of fire, often applied in remote monitoring and predictive maintenance.
- Ultraviolet Detection:This method specifically identifies the UV radiation produced by combustion, offering fast detection for certain types of fires.
- Acoustic Flame Detection:These systems detect the unique sound frequencies generated by flames, providing an alternative detection method in environments with visual obstructions.
Ultraviolet-Infrared Fusion technology is gaining market share most quickly, driven by demand for improved accuracy.
Application:
Regulatory mandates and inherent fire risks dictate the specific flame detection requirements across various industrial applications.
- Oil & Gas Processing:This application segment involves monitoring hydrocarbon fires in critical infrastructure such as refineries, pipelines, and offshore rigs. Demand concentrates in the Middle East and North America, driven by stringent ATEX and IECEx compliance requirements.
- Fire Detection in Power Plants:Flame detectors protect turbines, generators, and fuel storage areas within thermal and nuclear power generation facilities. Asia-Pacific and Europe represent significant markets, prioritizing operational continuity and asset protection.
- Chemical Manufacturing Safety:Flame detection systems are crucial for safeguarding highly volatile processes and storage tanks within chemical plants, preventing catastrophic events.
- Aerospace Testing Facilities:These facilities utilize specialized flame detectors to monitor engine test cells and fuel handling operations, requiring extremely rapid response capabilities.
- Industrial Furnaces:Flame detectors are integrated into industrial furnaces to monitor combustion processes and prevent uncontrolled fires in high-temperature manufacturing environments.
Oil & Gas Processing continues to represent the largest application segment, with Chemical Manufacturing Safety showing significant expansion.
End User:
The scale and operational complexity of an end-user facility significantly influence the selection and deployment of flame detection systems.
- Refineries:Large-scale industrial complexes processing crude oil into various petroleum products, refineries require extensive and robust flame detection coverage for high-value assets. Demand is concentrated in the Middle East and China, driven by the inherent explosion risks.
- Power Generation Plants:Facilities producing electricity from diverse fuel sources, these plants deploy flame detectors to protect critical infrastructure like turbines and fuel storage. India and Germany represent key markets, prioritizing uninterrupted energy supply and worker safety.
- Petrochemical Plants:These facilities produce chemicals from petroleum and natural gas, requiring specialized flame detection for a wide range of flammable feedstocks and products.
- Manufacturing Units:Diverse industrial sites, from automotive assembly to electronics production, utilize flame detectors to mitigate fire hazards specific to their processes.
- Research Laboratories:These environments require precise flame detection for experimental setups involving flammable materials and hazardous chemical handling.
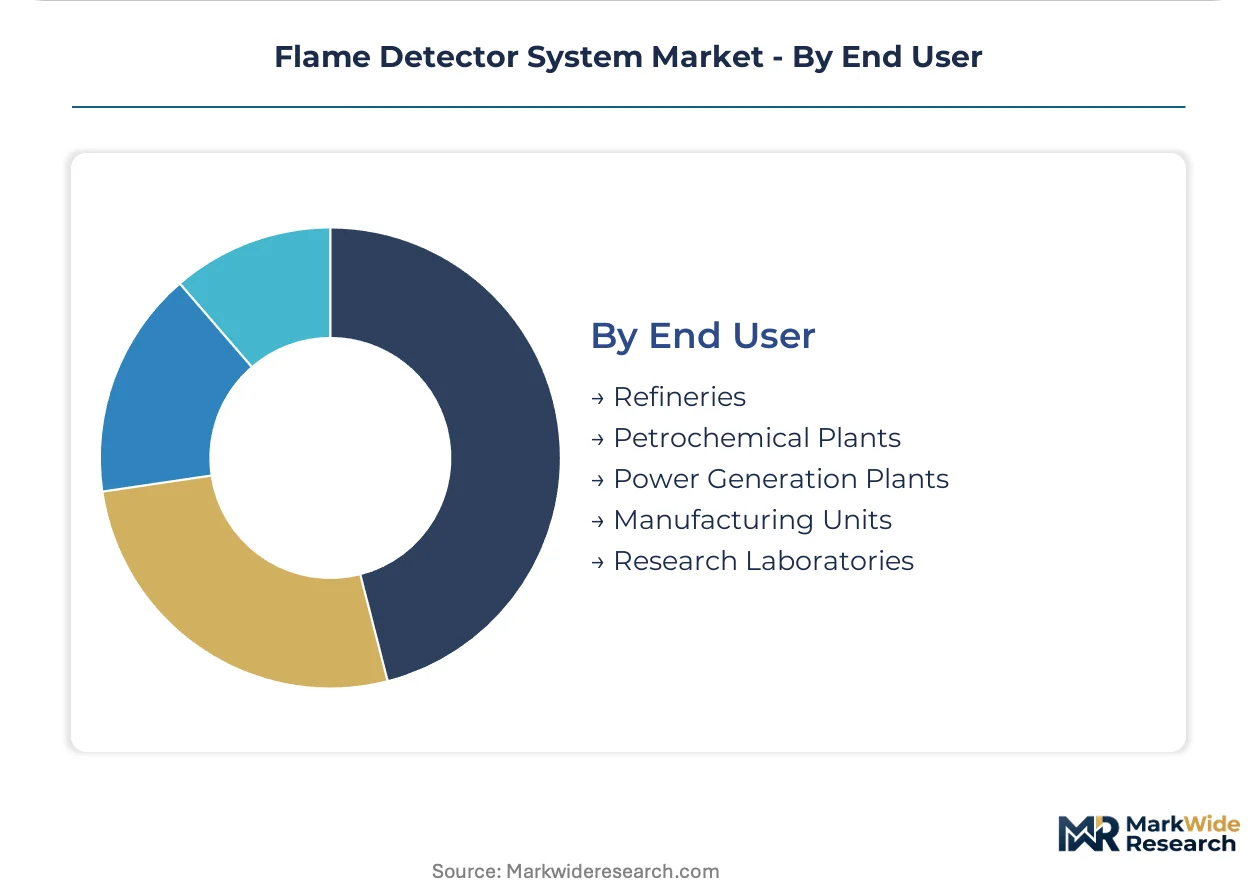
Refineries remain the dominant end-user segment, while Manufacturing Units are demonstrating accelerated adoption rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's significant investments in new refinery and petrochemical plant construction drive substantial demand for advanced flame detection systems. This market expansion is further influenced by diverse industrial requirements across major economic regions globally. Each region presents unique regulatory landscapes and infrastructure development patterns.
Saudi Arabia
Expansive capital projects in the oil and gas sector create sustained demand for sophisticated fire and gas detection systems. The Kingdom's Vision 2030 initiatives emphasize industrial safety and diversification, necessitating compliance with stringent industrial safety mandates. Industrial cities like Jubail and Yanbu, home to major petrochemical complexes, are central to this demand.
United States
Stringent NFPA standards and OSHA regulations compel the adoption of certified flame detectors across critical infrastructure. Demand stems from the large oil and gas processing facilities and power generation plants. The Gulf Coast region, with its extensive refining and chemical manufacturing footprint, represents a significant concentration of this market.
Germany
Europe's ATEX directives mandate the use of certified detection equipment in hazardous environments within the chemical and manufacturing sectors. The country's focus on renewable energy and modernization of existing power plants also contributes to demand. Industrial clusters in Bavaria and North Rhine-Westphalia are key adopters of advanced safety solutions.
China
Rapid industrialization and a growing emphasis on safety standards in manufacturing and power generation facilities fuel market expansion. Compliance with GB standards for industrial equipment is essential for market access. The Yangtze River Delta region, a hub for diverse industries, shows high adoption rates for advanced flame detection.
India
Infrastructure development in the power generation and refinery sectors drives the need for reliable flame detection technologies. The Bureau of Indian Standards (BIS) promotes equipment quality and safety across industrial applications. Major industrial corridors in Maharashtra and Gujarat are experiencing increased deployment of these systems.
Flame Detector System Market Key Industry Players
Global majors compete with regional champions across R&D capabilities, certification expertise, and extensive market access. The market structure exhibits a tiered approach, with large diversified industrial technology firms alongside specialized safety equipment manufacturers. Strategic partnerships and portfolio diversification represent dominant competitive moves.
Within the diversified industrial technology segment, Honeywell International Inc. leverages its extensive portfolio in industrial automation to integrate advanced systems. Siemens AG occupies a position as a comprehensive safety solutions provider for power generation clients, emphasizing integrated platforms. Emerson Electric Co. exemplifies specialization in solutions for hazardous environments, particularly within the oil and gas sector.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Det-Tronics |
| Honeywell International Inc. |
| Teledyne Gas & Flame Detection |
| Micropack Engineering Ltd. |
| Johnson Controls International Plc. |
| Siemens AG |
| Hochiki Corp. |
| MSA Safety Inc. |
| Others |
Cost & Logistics Intelligence
Multi-spectrum sensor technologies are reshaping cost economics and supply concentration within the flame detector system market. This advanced technology demands specialized components, influencing both production costs and distribution models.
Pricing Analysis
Component costs for advanced optical sensors directly influence the final pricing of flame detector systems. Project-based pricing dominates for large industrial installations, reflecting complex integration and customization requirements. Certification level, such as IECEx compliance, and brand premium from established vendors like Honeywell International Inc., drive significant price differentiation, with pricing softness stemming from intense competition. Oil & gas processing operators demonstrate lower price sensitivity for mission-critical applications, unlike manufacturing units which often prioritize cost-effectiveness.
Supply Chain Analysis
Global freight costs impact the delivery of flame detector components and finished systems, particularly for specialized sensors. Manufacturing of critical components like multi-spectrum optical sensors concentrates in Germany, the United States, and China. The supply chain sources from specialized semiconductor components and advanced optical materials, with single-source vulnerability for these technical parts representing a significant structural risk. Distribution channels primarily involve direct sales to large industrial clients and specialized distributors for smaller projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flame detector system market is a stable compounder, driven by the ongoing enforcement of stringent safety regulations like ATEX and NFPA standards. This consistent regulatory push ensures sustained demand for certified detection equipment across critical industrial sectors.
For Market Incumbents: Cement market leadership by deepening R&D investments in AI-driven analytics, directly addressing the threat of false alarms that erode user trust. Consolidate market share through strategic acquisitions of smaller firms specializing in niche technologies like lithium-ion battery fire detection. Leverage extensive certification expertise, such as IECEx compliance, to maintain a competitive moat against new entrants. Focus on long-term service contracts to lock in high-value customers in the power generation segment.
For New Entrants and Emerging Players: Capture market share by specializing in emerging applications like battery energy storage systems (BESS), where unique fire signatures demand novel detection solutions. Target the rapidly industrializing Southeast Asian nations, particularly Vietnam and Indonesia, as the most penetrable geography due to less entrenched competition. Develop AI-driven detector firmware to offer superior false alarm immunity as a key go-to-market angle. Focus on cost-effective, wireless deployment solutions for remote industrial sites.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized safety equipment manufacturers with strong regional certifications but limited global reach. Long-term viability for the flame detector system market is driven by non-discretionary safety spending and continuous regulatory updates, ensuring stable, predictable demand over the next decade. Target acquisition archetypes should focus on firms with deep expertise in multi-spectrum sensor development or AI integration. The signal to watch is the adoption rate of performance-based service contracts in critical infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-driven False Alarm Reduction | Honeywell International Inc. can improve system reliability and reduce operational costs for oil & gas processing clients. |
| Expand Multi-Spectrum Detector Portfolio | Siemens AG can address growing demand for superior false alarm immunity in power generation facilities. |
| Pursue IECEx Certification for New Products | Teledyne Gas & Flame Detection can accelerate market access into high-growth industrial sectors across the Middle East. |
| Develop Solutions for Battery Energy Storage Systems (BESS) | Emerson Electric Co. can capitalize on a new, high-value application with unique lithium-ion fire signatures. |
| Offer Performance-Based Service Contracts | Johnson Controls International Plc. can meet end-user demand for certified operational uptime in LNG terminal segments. |
Research Approach
Multiple input streams — primary interviews, proprietary databases, and public financial filings — were reconciled to construct a robust market view. Primary engagement included discussions with plant engineers, safety managers, R&D directors, and procurement leads across various industrial sectors. Secondary validation drew from industry association reports, government safety standards (e.g., NFPA, ATEX), and academic literature on electro-optical sensing. A rigorous bottom-up and top-down triangulation process ensured data accuracy and consistency.
Historical market data was cross-referenced against expert panel input to establish the forecast framework across the analysis window. Segmentation dimensions modeled include product type, technology, application, and end-user, alongside regional adoption patterns. Compound annual growth rates were derived from a detailed analysis of market drivers and restraints. Infrastructure investment cycles in the Middle East and evolving safety regulations serve as key forecast inputs.
Technological breakthroughs, shifts in global industrial investment, and unforeseen regulatory changes are the dominant revision risks for market projections. Forecasts reflect assumptions regarding economic stability and industrial safety priorities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Global Smoke Evacuation Systems Market
Fire Safety & Protection
Fire Suppression Equipment Market
Fire Safety & Protection
Deflagration Flame Arresters Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Fire and Rescue Helmets Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
Heptafluoropropane Fire Suppression System Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
Fire Suppression Market
Fire Safety & Protection
Global Fire Barrier Sealant Market