
 Manned Guarding Services Market | 2026-2036
Manned Guarding Services Market Size, Share, and Industry Trends Forecast 2026-2036
Manned Guarding Services Market Outlook
Shift from in-house security departments to outsourced contract guarding is broadening the addressable base for specialized service providers. Securitas AB leverages its technology-integrated guarding platform to compete in corporate and industrial accounts across Northern Europe. Allied Universal sustains market presence through its extensive North American branch network and bundled facility service offerings. G4S plc anchors its positioning in critical infrastructure and government contracts through accredited training academies and cleared personnel pools.
Manned guarding services deploy trained security personnel to protect assets, personnel, and premises through physical presence, access control, and incident response; operations typically require state or national licensing, background vetting, and compliance with use-of-force protocols. Static guarding commands the largest revenue share due to persistent demand at commercial and institutional entry points, while event security represents the fastest-expanding service type as live entertainment and corporate gatherings rebound post-pandemic. Corporate offices and government facilities within the end-user dimension concentrate margin pools where multi-year contracts and specialized clearance requirements create switching costs.
The UK's Security Industry Authority, the EU's private security services directives under national transpositions, and India's Private Security Agencies Regulation Act collectively shape training mandates, licensing reciprocity, and operational liability frameworks across major markets. Compliance with these regimes determines market access and contract eligibility, particularly for cross-border service providers seeking to standardize personnel quality. Stakeholders must monitor regulatory divergence between jurisdictions as data protection rules increasingly intersect with guard-deployed surveillance technologies.
Market Dynamics
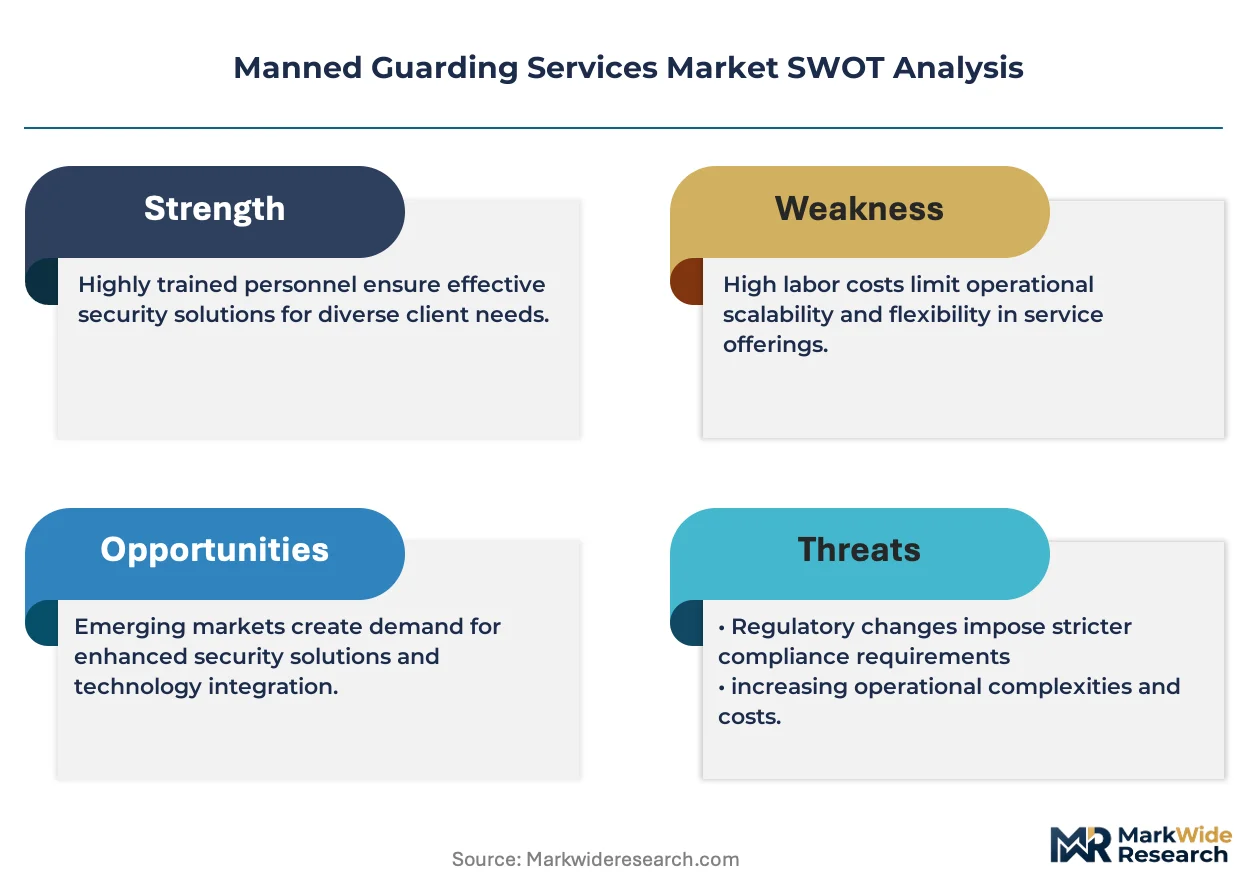
The manned guarding services sector is experiencing a fundamental reconfiguration as risk transfer agreements displace in-house security departments across corporate and institutional buyers. This structural shift toward outsourced accountability is compressing contract award cycles and elevating vendor liability thresholds.
Growth Catalysts
- India's PSARA Licensing Expansion:The Private Security Agencies Regulation Act mandates standardized training and vetting protocols that legitimize organized providers and disqualify informal operators across Maharashtra, Gujarat, and Karnataka.
- Critical Infrastructure Protection Mandates:EU member states are transposing the NIS2 Directive requirements for physical security at energy, transport, and digital infrastructure nodes into national procurement specifications.
- Live Event Security Surge:Post-pandemic entertainment calendars and corporate gathering rebounds are generating surge demand for temporary guarding deployments with specialized crowd management competencies.
Market Restraints
- Wage Cost Escalation:Minimum wage legislation across Germany, France, and the Netherlands is compressing gross margins for labor-intensive guarding contracts without proportional price indexation clauses.
- Technology Substitution Pressure:AI-enabled video analytics and remote monitoring platforms are capturing perimeter surveillance functions previously requiring human presence at industrial and logistics facilities.
- Regulatory Fragmentation:Non-reciprocal licensing regimes between EU member states and divergent SIA-equivalent standards create operational friction for cross-border service standardization.
Strategic Opportunities
- Greenfield Manufacturing Corridors:India's Dedicated Freight Corridors and semiconductor fabrication investments in Gujarat and Tamil Nadu are creating multi-year guarding requirements for construction-through-operations phases.
- Technology Convergence:Integration of body-worn cameras with real-time incident reporting platforms is enabling outcome-based contract structures that tie compensation to response time metrics.
- UK Regulatory Tailwind:The Security Industry Authority's proposed licensing tier for armed response and close protection services is creating premium service categories with elevated certification barriers.
Industry Challenges
- Vetting Pipeline Bottlenecks:Enhanced background check requirements under the UK's BS7858 standard and EU equivalents are extending deployment timelines and inflating pre-employment screening costs.
- Retention of Accredited Personnel:Competition from gig-economy platforms and logistics sectors is siphoning licensed guards, forcing providers to absorb elevated training amortization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manned Guarding Services Market |
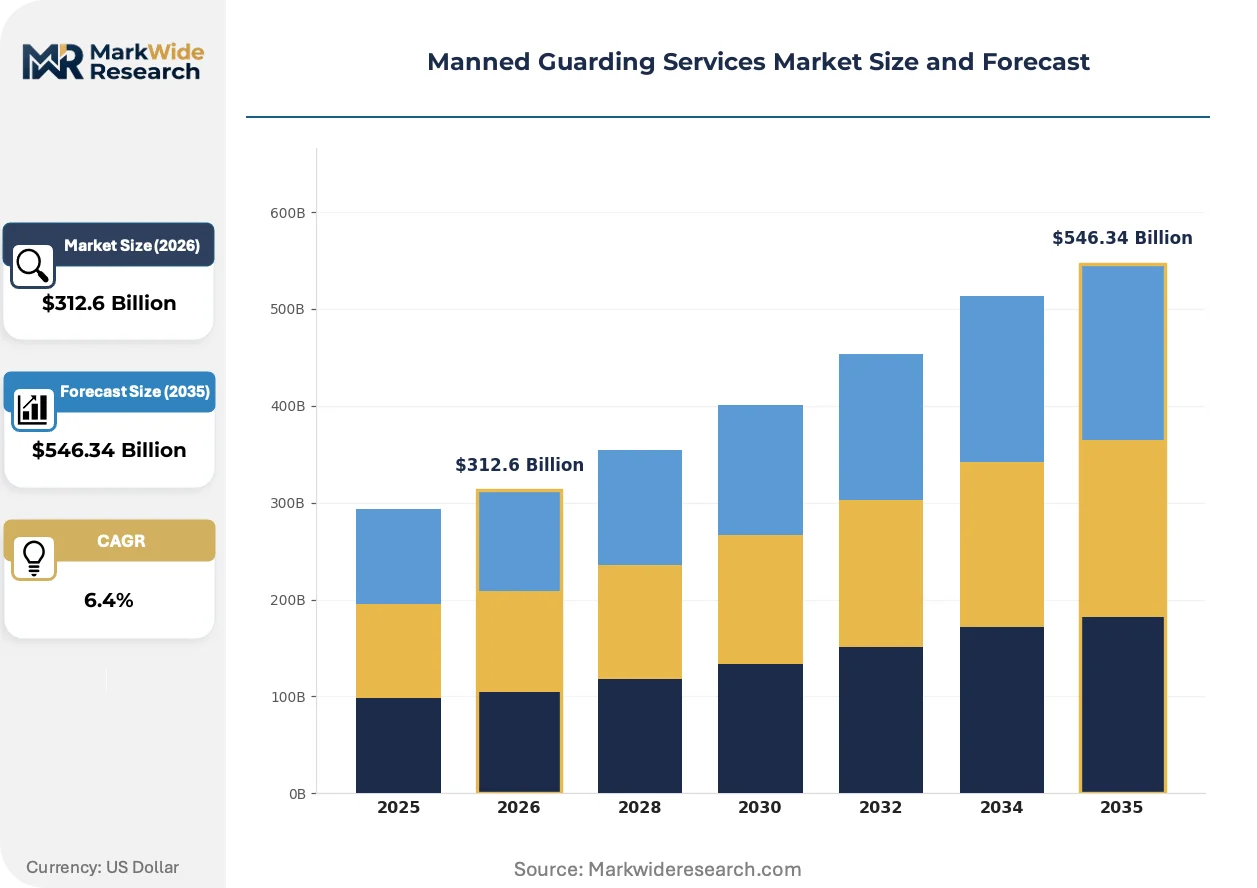
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $546.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Static Guarding, Mobile Patrol, Event Security, Concierge Services End User: Retail Sector, Government Facilities, Corporate Offices, Residential Communities Security Level: Armed Security, Unarmed Security, High-Risk Security, VIP Protection Industry Vertical: Healthcare Facilities, Education Institutions, Financial Services, Transportation |
| Companies Covered | G4S plc, Securitas AB, Allied Universal, Prosegur, GardaWorld, ICTS Europe, SIS India, Transguard Group, Axis Security, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manned Guarding Services Market Strategic Shifts
Digitization of guard force management is collapsing traditional supervisory hierarchies and enabling real-time performance verification. Technology vendors and incumbent service providers are racing to deploy platforms that integrate scheduling, incident logging, and client reporting into unified interfaces.
Mobile workforce management platforms are decentralizing command structures within guarding operations. Facility managers at UK retail and logistics sites are adopting smartphone-based patrol verification systems that eliminate paper logs and enable geofenced checkpoint compliance. This shift is compressing supervisor-to-guard ratios and enabling smaller branch footprints without coverage degradation.
The EU's Corporate Sustainability Reporting Directive is extending disclosure obligations to social metrics within outsourced service supply chains. German and French procurement departments are now mandating living wage certifications and carbon footprint reporting from guarding contractors. Tier-one providers are responding by deploying electric vehicle patrol fleets and publishing audited workforce welfare metrics.
Buyer contracting behavior is pivoting from input-based to outcome-based specifications across Nordic and Benelux markets. Procurement teams at Danish pharmaceutical campuses and Belgian port authorities are tendering for incident response time guarantees rather than guard headcount minimums. This compression of the traditional unit-rate model is favoring providers with integrated technology stacks and predictive analytics capabilities.
Manned Guarding Services Market Segmentation
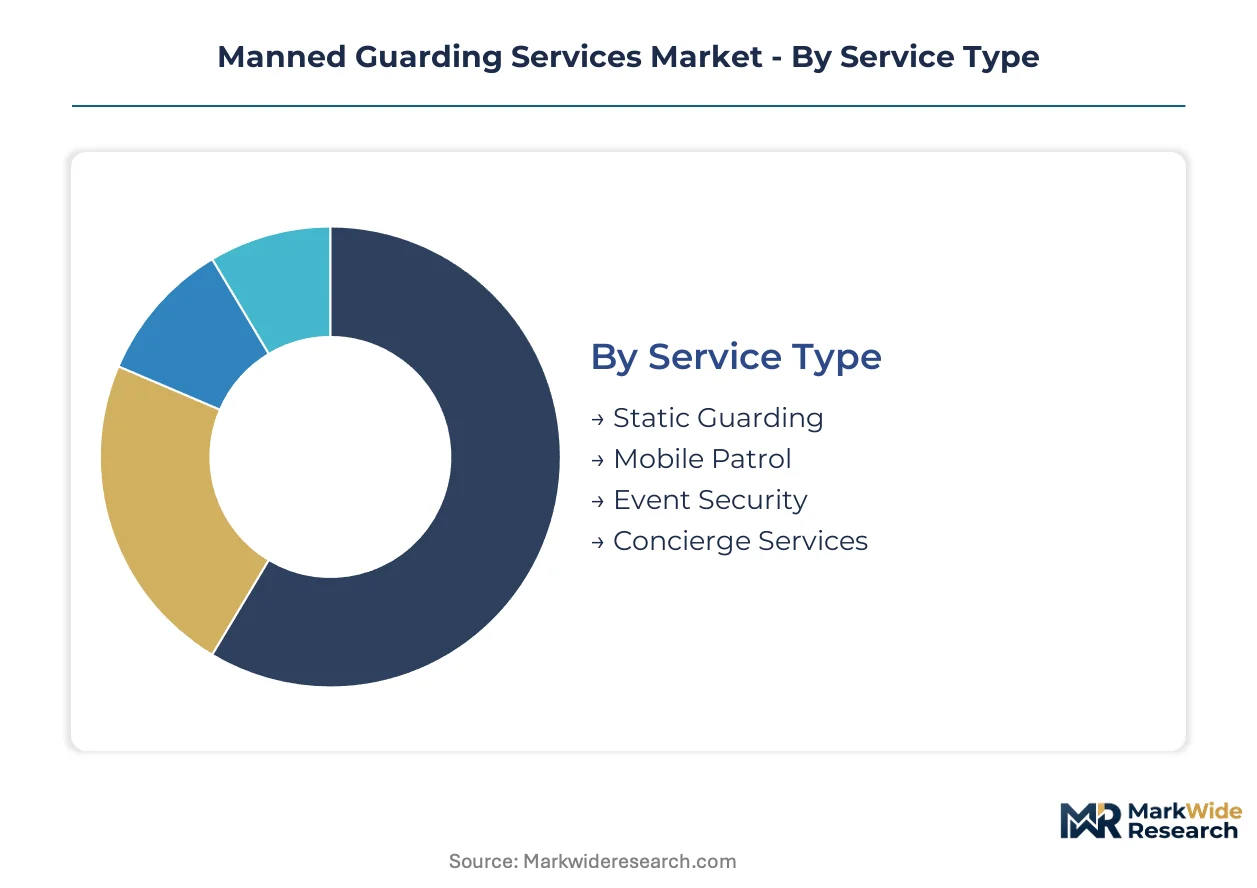
Segmentation in manned guarding services reflects divergent risk profiles, regulatory thresholds, and procurement sophistication across buyer categories. Contract terms, pricing models, and technology integration requirements vary substantially by service type and end-user context.
Service Type:
Cost tier differentiation separates buyers seeking permanent presence from those requiring intermittent or surge capacity.
- Static Guarding:Personnel stationed at fixed posts perform access control, visitor screening, and perimeter monitoring. Demand concentrates at corporate campuses in Germany and the Netherlands where facilities managers prioritize visible deterrence over technology substitution.
- Event Security:Temporary deployments manage crowd flow, credential verification, and emergency response for entertainment and corporate gatherings. Post-pandemic rebound in live events across the UK and Denmark is driving specialized training investments for surge staffing.
- Mobile Patrol:Vehicle-based guards conduct randomized perimeter checks and alarm response across distributed industrial sites.
- Concierge Services:Hybrid security-reception roles blend access control with hospitality functions at premium residential and commercial addresses.
Static guarding leads volumes today; event security is gaining share fastest.
End User:
Application maturity determines whether buyers accept outcome-based contracts or cling to headcount-based specifications.
- Corporate Offices:Technology and finance sector campuses in London and Frankfurt are expanding outsourced procurement as risk transfer agreements displace in-house departments. Multi-year contracts with integrated technology stacks create elevated switching costs for established providers.
- Government Facilities:Critical infrastructure and administrative sites require cleared personnel pools and accredited training academies. EU member states transposing NIS2 Directive mandates are tightening procurement specifications for energy and transport node protection.
- Retail Sector:Loss prevention and customer safety patrols at shopping centers and logistics warehouses.
- Residential Communities:Gated developments and mixed-use complexes seeking amenity-enhanced security presence.
Government facilities anchor contract values; corporate offices show the steepest expansion trajectory.
Security Level:
Margin concentration tracks certification barriers and liability exposure across deployment categories.
- Unarmed Security:Standard patrol and access control functions dominate contract volumes but face technology substitution pressure from AI-enabled video analytics.
- Armed Security:Weapon-carrying personnel deployed for high-value asset protection and critical infrastructure. The UK's Security Industry Authority proposed licensing tier for armed response is creating premium service categories with elevated training barriers.
- High-Risk Security:Specialized deployment for conflict zones, maritime protection, and hazardous material sites.
- VIP Protection:Close protection details for corporate executives, dignitaries, and high-net-worth individuals.
Unarmed security dominates headcount; armed security commands premium pricing expansion.
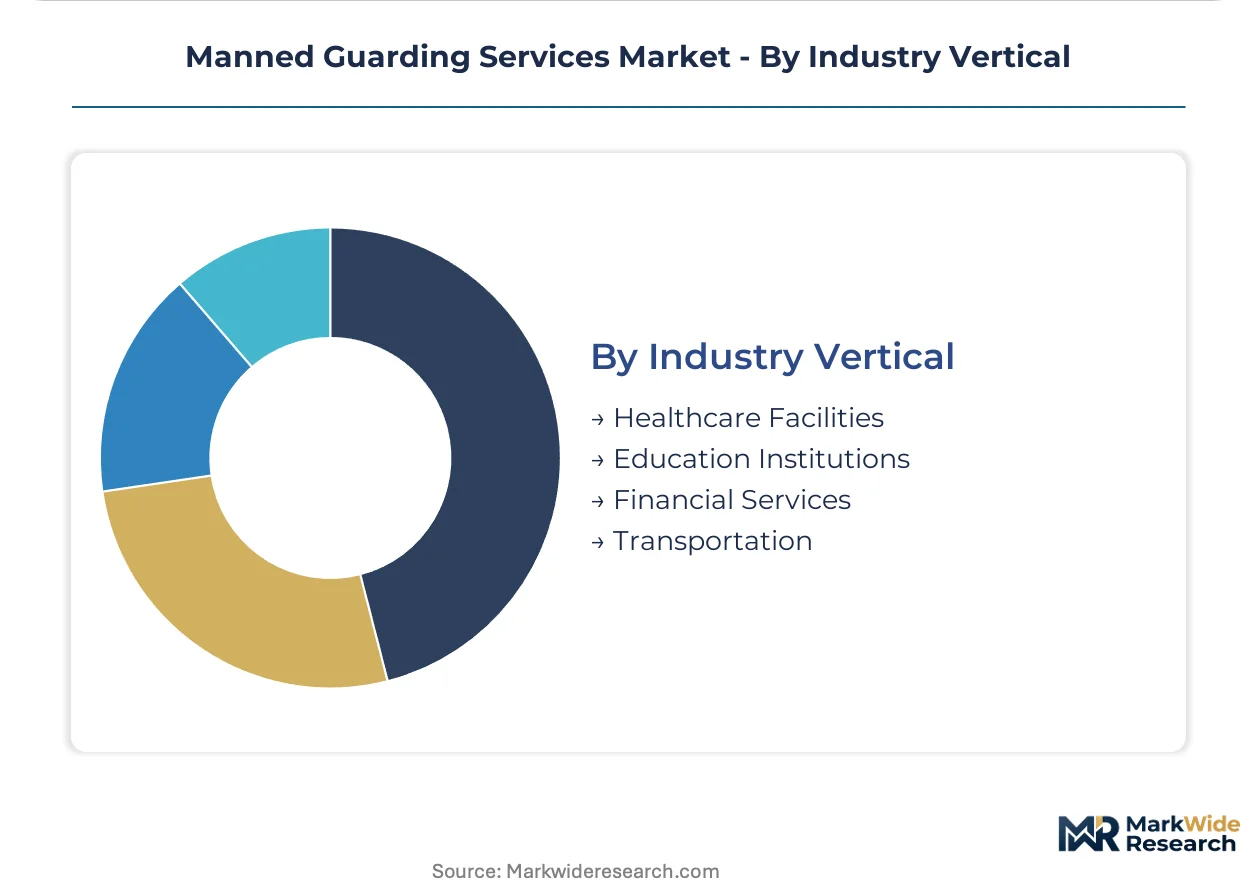
Industry Vertical:
Customer type dictates regulatory compliance layers and workforce specialization requirements.
- Healthcare Facilities:Patient safety, controlled substance security, and emergency department de-escalation protocols. Hospital networks in France and Belgium are mandating living wage certifications and carbon footprint reporting under EU Corporate Sustainability Reporting Directive obligations.
- Financial Services:Cash handling, vault protection, and executive security for banking headquarters. Data protection rules intersecting with guard-deployed surveillance technologies are elevating compliance complexity across German and Swiss financial centers.
- Education Institutions:Campus safety, event security, and student residence monitoring.
- Transportation:Airport, port, and rail facility protection with customs coordination requirements.
Healthcare facilities lead procurement volume; financial services vertical shows fastest technology integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping competitive positioning as providers migrate operations toward jurisdictions with streamlined licensing regimes and lower compliance friction. The cost-of-compliance gap between mature European frameworks and emerging market standardization creates contract migration patterns that favor organized operators with cross-border accreditation capabilities.
United States
Corporate campuses in technology and finance sectors are expanding outsourced security procurement as facilities managers prioritize risk transfer over in-house staffing. The Department of Homeland Security's critical infrastructure protection mandates tighten procurement specifications for energy and transport node protection. Silicon Valley and Manhattan financial districts concentrate multi-year contracts with integrated technology stacks.
United Kingdom
The Security Industry Authority licensing regime elevates baseline training standards for personnel deployment across commercial and institutional accounts. Proposed licensing tiers for armed response and close protection services create premium service categories with elevated certification barriers. London's corporate headquarters cluster drives demand for concierge-hybrid security roles at premium addresses.
Germany
Minimum wage legislation is compressing gross margins for labor-intensive guarding contracts without proportional price indexation clauses. The EU's Corporate Sustainability Reporting Directive extends disclosure obligations to social metrics within outsourced service supply chains. Frankfurt's banking headquarters and Hamburg's port facilities anchor high-value government and financial services contracts.
India
Urban commercial construction and foreign direct investment into manufacturing corridors create sustained contract opportunities for established providers. The Private Security Agencies Regulation Act mandates standardized training and vetting protocols that legitimize organized providers across Maharashtra, Gujarat, and Karnataka. Dedicated Freight Corridors and semiconductor fabrication investments in Gujarat and Tamil Nadu generate multi-year guarding requirements.
France
Procurement departments mandate living wage certifications and carbon footprint reporting from guarding contractors under EU sustainability obligations. The country's national security regulator enforces competency frameworks that elevate personnel deployment standards. Paris commercial districts and Lyon pharmaceutical campuses drive outcome-based contracting with incident response time guarantees.
Manned Guarding Services Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue technology-integrated platforms and specialized clearance capabilities. The vendor base concentrates around three strategic archetypes: multinational providers with accredited training academies, regional specialists with government contract relationships, and technology-enabled platforms with real-time workforce management systems. Dominant competitive moves include strategic partnerships for cross-border service standardization and portfolio diversification into bundled facility services.
Among multinational service providers, Securitas AB and Allied Universal exemplify the technology-integrated guarding archetype, while G4S plc anchors positioning in critical infrastructure and government contracts. These entities represent contrasting strategic postures: Nordic-origin operators emphasize predictive analytics and outcome-based contract structures, while North American and UK-based providers leverage extensive branch networks and bundled service offerings. The competitive terrain favors operators with cleared personnel pools and multi-jurisdiction licensing reciprocity.
| Leading Market Players |
|---|
| G4S plc |
| Securitas AB |
| Allied Universal |
| Prosegur |
| GardaWorld |
| ICTS Europe |
| SIS India |
| Transguard Group |
| Axis Security |
| Others |
Value Chain & Pricing Dynamics
Corporate campuses in technology and finance sectors concentrate procurement authority among facilities managers who prioritize risk transfer agreements over in-house staffing, locking contract structures around headcount-based unit rates with limited price indexation clauses. This buyer concentration compresses margin recovery when wage legislation escalates labor costs faster than pass-through mechanisms activate.
Pricing Analysis
Direct-to-corporate contracts dominate channel economics, with branch-level account managers negotiating multi-year agreements that bundle guarding headcount with technology platform access. Price differentiation hinges on SIA licensing tier and clearance level—armed response commands premium multiples over static unarmed posts—while minimum wage compression in Germany and the Netherlands squeezes gross margins without proportional rate adjustments. Procurement teams at Danish pharmaceutical campuses and Belgian port authorities exhibit lowest price sensitivity, accepting outcome-based premiums for response time guarantees.
Supply Chain Analysis
Regional distribution of guard force management platforms follows hub-and-spoke patterns anchored in Mumbai, London, and Frankfurt where training academies and vetting pipelines cluster. Personnel supply draws from India's PSARA-licensed agencies, UK's SIA-accredited providers, and Germany's competency-framework operators, with background check dependencies extending deployment timelines. Single-source vulnerability concentrates in cleared personnel pools for government contracts. Distribution runs through branch networks with localized hiring and centralized platform licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor providers capturing premium-tier shifts toward armed response licensing and technology-integrated outcome contracts, while wage cost compression forces operational efficiency investments that deepen competitive moats.
For Market Incumbents: Anticipate technology substitution pressure from AI-enabled video analytics by accelerating body-worn camera integration with real-time incident reporting platforms. Secure SIA armed response licensing tier accreditation before regulatory barriers elevate. Backward integration into proprietary training academies insulates against vetting pipeline bottlenecks and retention volatility. For New Entrants and Emerging Players: Begin with India's Dedicated Freight Corridor construction-through-operations phases where PSARA standardization disqualifies informal operators and creates white-space for organized entrants. Target event security surge demand across UK and Denmark live entertainment calendars. Lead with smartphone-based patrol verification platforms that compress supervisor ratios and enable outcome-based contract bidding. For Investors and Strategic Acquirers: Facility services conglomerates are the most active acquirer in this space, pursuing guarding capabilities to complete bundled service portfolios. Long-term viability rests on technology convergence enabling response-time-based compensation structures. Monitor SIA licensing tier implementation velocity as inflection indicator for premium service category formation.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Platform Integration | Body-worn cameras with real-time reporting enable outcome-based contracts at Danish pharmaceutical campuses. |
| Accreditation Investment | SIA armed response licensing creates premium tiers with elevated certification barriers before competitors enter. |
| Geographic Expansion | PSARA-compliant operations in Gujarat and Tamil Nadu capture semiconductor fabrication guarding requirements. |
| Strategic Partnership | Cross-border licensing reciprocity agreements reduce operational friction for EU multi-jurisdiction contracts. |
| Workforce Management Scale-Up | Mobile patrol verification systems compress supervisor-to-guard ratios across UK retail and logistics sites. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with security operations directors, facilities procurement managers, SIA licensing officials, and PSARA compliance officers with secondary validation against EU NIS2 Directive transposition documents, UK Security Industry Authority regulatory filings, and Indian Private Security Agencies Regulation Act enforcement records. Bottom-up contract value aggregation and top-down macroeconomic sizing were triangulated for convergence.
Historical reference periods anchored the projection horizon, with analytical frameworks modeling service type segmentation across static guarding, event security, mobile patrol, and concierge functions alongside end-user verticals and security level tiers. CAGRs were derived from regression analysis of contract award velocity and technology adoption curves, incorporating wage legislation trajectories and critical infrastructure protection mandate expansion as industry-specific inputs.
Caveats apply where regulatory divergence between EU member states or accelerated AI-enabled video analytics substitution could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Home Security Solution Market
Security and Surveillance
Security Operations Center Market
Security and Surveillance
Explosive Detection Kit Market
Security and Surveillance
Private Security Market
Security and Surveillance
Speed Limit Radar Signs Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Forensic Technologies Market
Security and Surveillance
Global Wireless Monitoring and Surveillance Market
Security and Surveillance
Multi-Layer Security Market
Security and Surveillance
Global Alarm Monitoring Market
Security and Surveillance
Night Vision Binoculars Market
Security and Surveillance
Swimming Pool Alarm Market
Security and Surveillance
Prison Management Systems Market
Security and Surveillance
Global Adaptive Security Market
Security and Surveillance
Europe Cargo and Vehicle Screening Market