
 Security System Integrators Market | 2026-2036
Security System Integrators Market Size, Share, and Industry Trends Forecast 2026-2036
Security System Integrators Market Intelligence
The traditional silo separating IT network engineers from physical security technicians is collapsing, creating a critical need for hybrid skill sets in system deployment. This convergence of expertise is a primary constraint on growth for smaller firms. Pavion leverages its scale to integrate disparate systems for large commercial clients. M.C. Dean specializes in securing complex government and critical infrastructure projects, while Diversified focuses on corporate enterprise environments.
Security system integrators are specialized firms that design, install, and manage converged security solutions combining hardware with software for monitoring. Their primary purpose is creating a unified security posture by integrating disparate systems, like access control and video surveillance, onto a single platform. Among service types, video surveillance and access control command the largest share, but cybersecurity solutions are expanding most rapidly. The deployment of AI-based analytics technology is also accelerating, shifting value from reactive monitoring to proactive intelligence.
Integrators must navigate a complex web of regulations that dictate system design and data handling protocols across geographies. For example, compliance with Europe's GDPR, the US HIPAA for healthcare data, and China's GB standards for equipment is non-negotiable for market access. The forthcoming EU AI Act will further regulate the use of analytics in surveillance. The key strategic decision for integrators becomes whether to specialize in high-compliance verticals or pursue broader, less-regulated commercial sectors.
Market Dynamics
The convergence of information technology (IT) and operational technology (OT) networks is the central force shaping the market. This requires integrators to develop hybrid expertise in both physical security hardware and complex network cybersecurity protocols to deliver unified solutions.
Growth Catalysts
- IoT Proliferation:Connecting devices like sensors and cameras to a unified network enables more sophisticated data collection for proactive security strategies in commercial facilities and smart city projects.
- Critical Infrastructure Mandates:Government requirements for enhanced security at utilities, transportation hubs, and data centers, particularly in the United States, compel investment in advanced integrated systems.
- Legacy System Obsolescence:Aging analog surveillance and access control systems in the commercial sector lack the capabilities of modern IP-based solutions, creating a strong replacement and upgrade cycle.
Market Restraints
- Component Scarcity:Supply chain concentration for specialized semiconductors and high-resolution sensors creates price volatility and potential project delays for system integrators.
- Interoperability Standards Gaps:The absence of universal communication protocols between devices from different manufacturers complicates system integration, increases deployment costs, and can lead to vendor lock-in.
- Data Privacy Regulation:Strict rules like Europe's GDPR and the US's HIPAA impose significant compliance burdens on how integrators handle and store sensitive surveillance and biometric data.
Strategic Opportunities
- Managed Security Services:Shifting clients from one-time installation contracts to recurring revenue models for remote monitoring, maintenance, and software updates offers more stable and predictable income streams.
- AI-Powered Analytics:Offering advanced analytics for threat detection, behavioral analysis, and operational efficiency moves the value proposition from simple monitoring to actionable business intelligence.
- Cybersecurity Service Integration:Expanding service offerings to include network security assessments and cyber-physical threat mitigation addresses a critical and growing vulnerability for enterprise clients.
Industry Challenges
- Hybrid Skill Shortage:A significant talent gap exists for technicians and engineers who possess certified expertise in both physical security hardware and complex IT network engineering.
- Legacy System Integration:Integrating modern IP-based systems with clients' existing, often proprietary, legacy infrastructure is technically complex and can lead to performance issues and security vulnerabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security System Integrators Market |
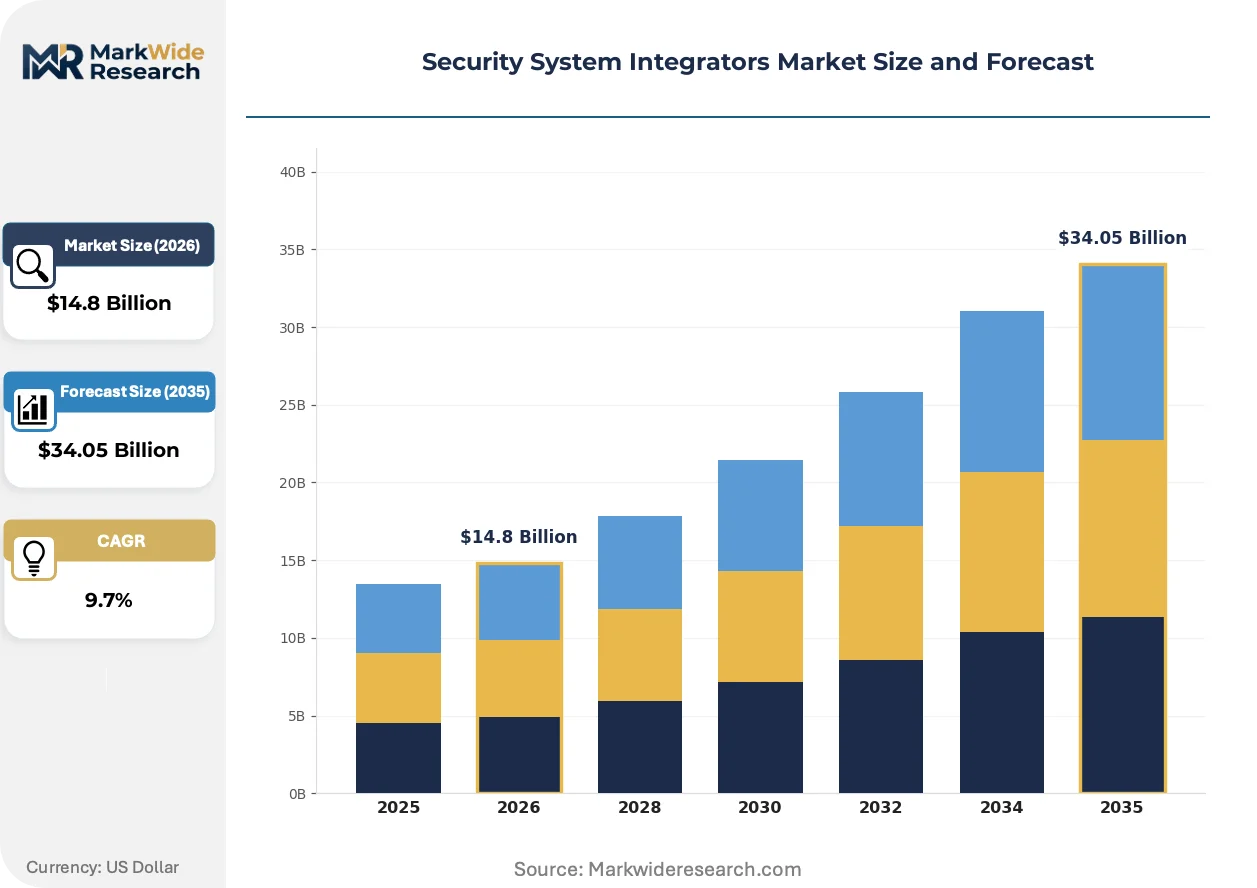
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Access Control, Video Surveillance, Intrusion Detection, Fire Alarm, Perimeter Security, Cybersecurity Solutions Technology: Biometric Recognition, IoT Integration, Cloud-Based Management, AI-Based Analytics, Wireless Systems, RFID End User Industry: Commercial Facilities, Critical Infrastructure, Transportation Hubs, Educational Institutions, Government Complexes, Residential Developments Deployment Model: On-Premises, Managed Security Service, Hybrid Deployment, Remote Monitoring, Cloud-Hosted, Edge Computing |
| Companies Covered | Pavion, Ricoh, AVI-SPL, Security 101, EOS IT Solutions, Diversified, M.C. Dean, RoviSys, FORTÉ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security System Integrators Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift from hardware-centric installations toward software-defined, service-oriented models. Value is migrating from the physical device to the data it generates and the intelligence extracted from it, fundamentally altering integrator business strategies.
AI-powered video analytics automates the real-time detection of threats, objects, and specific behaviors from surveillance footage. Large commercial and public sector clients are driving adoption for applications beyond simple security monitoring, such as process optimization and customer behavior analysis. This technology is bifurcating the market into firms offering basic reactive monitoring versus those providing advanced, proactive intelligence as a premium service.
The forthcoming EU AI Act establishes a risk-based framework for artificial intelligence systems, directly impacting video surveillance analytics. It mandates strict compliance, transparency, and human oversight for high-risk applications, such as those used in public spaces. Integrators operating in Europe must now embed these regulatory requirements into system design and data governance protocols from the project's inception.
Enterprise procurement is moving away from large, upfront capital expenditures for security systems toward subscription-based Security-as-a-Service (SaaS) models. This change disrupts the traditional project-based revenue of integrators, favoring firms that can provide ongoing managed services, remote diagnostics, and software updates. This demand pattern is most pronounced within the corporate enterprise and multi-site retail sectors in North America and Europe.
Security System Integrators Market Segmentation
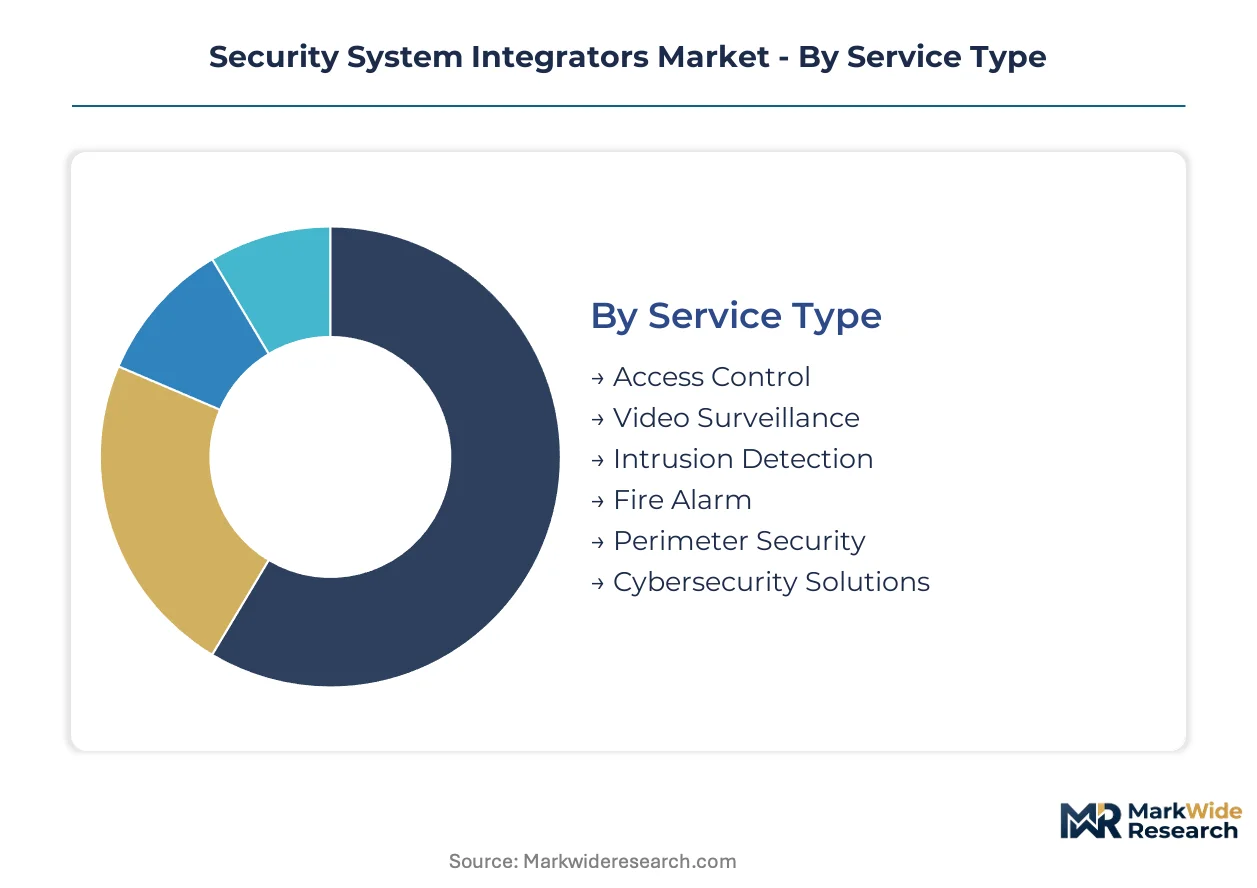
Understanding the segmentation of the security system integrators market reveals the diverse needs and technological preferences across various client environments. This detailed classification helps integrators tailor their offerings to specific regulatory demands, technological advancements, and end-user requirements.
Service Type:
Integrators must navigate diverse regulatory landscapes, influencing the specific security services offered and their technical implementation.
- Video Surveillance:These systems encompass cameras, recording devices, and monitoring software for visual oversight of premises. Commercial facilities and critical infrastructure clients drive demand for enhanced monitoring and proactive intelligence capabilities.
- Cybersecurity Solutions:This segment involves protecting digital assets, networks, and data from unauthorized access or damage. Corporate enterprise and government clients prioritize these solutions for converged IT/OT security and data compliance.
- Access Control:Systems manage entry permissions to restricted areas using credentials, biometrics, or other authentication methods.
- Intrusion Detection:Sensors and alarms identify unauthorized entry, triggering immediate alerts for security personnel.
- Fire Alarm:Integrated systems detect smoke, heat, or fire, activating alarms and often notifying emergency services.
- Perimeter Security:Solutions protect property boundaries through physical barriers, sensors, and surveillance.
Established volume favors Video Surveillance; emerging adoption favors Cybersecurity Solutions.
Technology:
Technology adoption within security integration is driven by specific application requirements, from identity verification to network-wide data management.
- AI-Based Analytics:Algorithms process video and sensor data for automated threat detection, behavioral analysis, and operational insights. Commercial facilities and public sector clients drive adoption for advanced, proactive intelligence capabilities.
- IoT Integration:This involves connecting disparate security devices like sensors, cameras, and access points into a unified network. Smart city projects and commercial facilities leverage IoT for comprehensive data collection and sophisticated security strategies.
- Biometric Recognition:Verifies identity through unique physical characteristics, such as fingerprints or facial scans, for secure access control.
- Cloud-Based Management:Offers remote system management, data storage, and accessible monitoring capabilities from any location.
- Wireless Systems:Enables flexible deployment of security devices without extensive physical cabling, reducing installation complexity.
- RFID:Uses radio-frequency identification tags for tracking assets, managing inventory, or controlling access in specific zones.
IoT Integration drives network expansion; AI-Based Analytics enhances intelligence capabilities.
End User Industry:
Customer types dictate the scale and complexity of integrated security solutions, ranging from large-scale government projects to individual residential needs.
- Commercial Facilities:Businesses upgrade aging analog surveillance and access control systems with modern IP-based solutions. This sector drives significant replacement and upgrade cycles, particularly for office buildings and retail spaces.
- Critical Infrastructure:Government mandates for enhanced security at utilities, transportation hubs, and data centers compel investment. The United States shows particular demand for these advanced integrated systems protecting essential services.
- Transportation Hubs:Airports, seaports, and train stations require extensive integrated surveillance, access control, and screening systems.
- Educational Institutions:Schools and universities implement comprehensive solutions for campus safety, emergency response, and access management.
- Government Complexes:Secure facilities demand stringent access control, advanced surveillance, and robust data protection protocols.
- Residential Developments:Multi-dwelling units and gated communities deploy systems for property protection and resident safety.
Commercial Facilities lead in upgrade cycles; Critical Infrastructure mandates drive advanced system adoption.
Deployment Model:
Deployment models influence operational efficiency and long-term service margins, differentiating between one-time installations and recurring revenue streams.
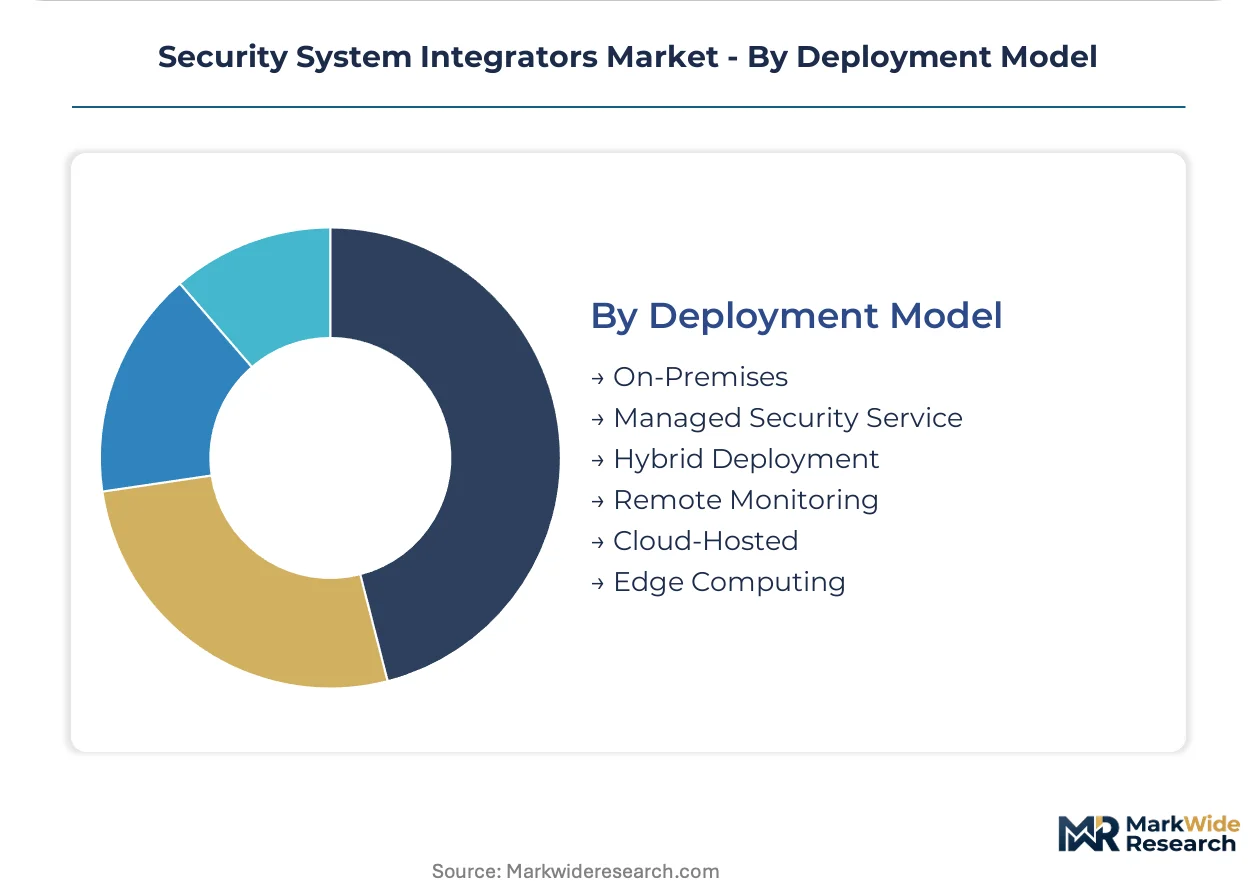
- Managed Security Service:Integrators provide remote monitoring, maintenance, and software updates as a recurring revenue stream. This shifts clients from capital expenditures to predictable operational expenses, offering stable income to providers.
- Cloud-Hosted:Security system data and applications reside on remote servers, accessible via the internet. This model supports subscription-based Security-as-a-Service, particularly for multi-site corporate enterprise clients.
- On-Premises:Security hardware and software are installed directly on the client's property, managed internally.
- Hybrid Deployment:Combines on-premises systems with cloud-based components for enhanced flexibility and data backup.
- Remote Monitoring:Off-site security professionals oversee client systems, providing alerts and incident response.
- Edge Computing:Data processing occurs closer to the source, reducing latency and bandwidth requirements for real-time analytics.
Managed Security Service models provide stable income; Cloud-Hosted solutions support scalable enterprise deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HIPAA compliance anchors the dominant United States market for security system integrators. This country shows significant demand for advanced integrated systems, especially for critical infrastructure protection. Commercial facilities also drive substantial upgrade cycles across the region.
United States
Demand for enhanced security at critical infrastructure assets drives significant investment. The US's HIPAA regulations impose strict data handling protocols for healthcare sector integrations. Silicon Valley and other tech hubs are developing advanced AI-based analytics solutions for proactive intelligence.
Germany
Commercial facilities in Germany are upgrading legacy systems to modern IP-based solutions. The forthcoming EU AI Act mandates strict compliance for video surveillance analytics across the country. Munich's industrial sector sees increased adoption of IoT integration for sophisticated security strategies.
China
Government mandates for critical infrastructure protection compel investment in integrated security systems. China's GB standards for equipment are non-negotiable for market access and system design. Shenzhen's technology manufacturing base is driving innovation in sensor and camera development.
India
Smart city projects and commercial facility expansion are driving IoT integration for security solutions. The country's national cybersecurity policies encourage the adoption of robust digital protection measures. Bengaluru's IT sector is a hub for developing and deploying advanced cybersecurity services.
United Kingdom
Aging analog systems in the commercial sector create a strong replacement and upgrade cycle. The UK's data protection laws influence how integrators handle sensitive surveillance data. London's financial district is a key area for high-compliance security solutions and managed services.
Security System Integrators Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the security system integrators market. This market structure features a mix of large-scale providers and niche solution specialists, each targeting specific client segments. Strategic archetypes include firms focusing on complex government projects, those serving large commercial clients, and others specializing in corporate enterprise environments with unique compliance needs. Companies are primarily engaging in portfolio diversification and strategic partnerships to enhance their service offerings and expand their geographic reach.
Within the large commercial client segment, Pavion represents an integrated leader leveraging scale for disparate system integration across various industries. M.C. Dean occupies a position as a specialist in securing complex government and critical infrastructure projects, often requiring high-compliance expertise. Diversified anchors the corporate enterprise environment, providing tailored security solutions for demanding business needs, including advanced cybersecurity and cloud-based management. These entities exemplify the diverse approaches to market penetration and client service, highlighting the segmentation by client type and project complexity. Their presence underscores the importance of specialized capabilities in different market verticals.
| Leading Market Players |
|---|
| Pavion |
| Ricoh |
| AVI-SPL |
| Security 101 |
| EOS IT Solutions |
| Diversified |
| M.C. Dean |
| RoviSys |
| FORTÉ |
| Others |
Cost & Logistics Intelligence
Software-defined security solutions are displacing hardware-centric installations, simultaneously shifting supply chain emphasis from physical components to digital platforms and altering pricing dynamics towards recurring service models.
Pricing Analysis
Project-based installation contracts still characterize a significant portion of integrator revenue, but subscription-based managed security services are rapidly gaining traction. Price differentiation stems from the customization level required for complex integrated systems and the specialized certification level needed for high-compliance verticals like critical infrastructure. Pricing softness affects basic hardware installations due to commoditization, while advanced AI analytics and cybersecurity services command premium rates. Commercial facilities seeking basic surveillance upgrades often represent the most price-sensitive segment, contrasted by government and critical infrastructure clients prioritizing compliance and reliability over upfront cost.
Supply Chain Analysis
Concentration of specialized semiconductor and high-resolution sensor manufacturing in East Asia, particularly China and Taiwan, creates a chokepoint for physical security hardware components. The market draws from a global base of suppliers for these critical inputs, alongside specialized software from the United States and Europe. Single-source vulnerability for niche AI-powered sensors represents a significant supply chain risk, exacerbated by geopolitical trade tensions. Distribution runs through a network of original equipment manufacturers (OEMs) and value-added distributors before reaching system integrators for client deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
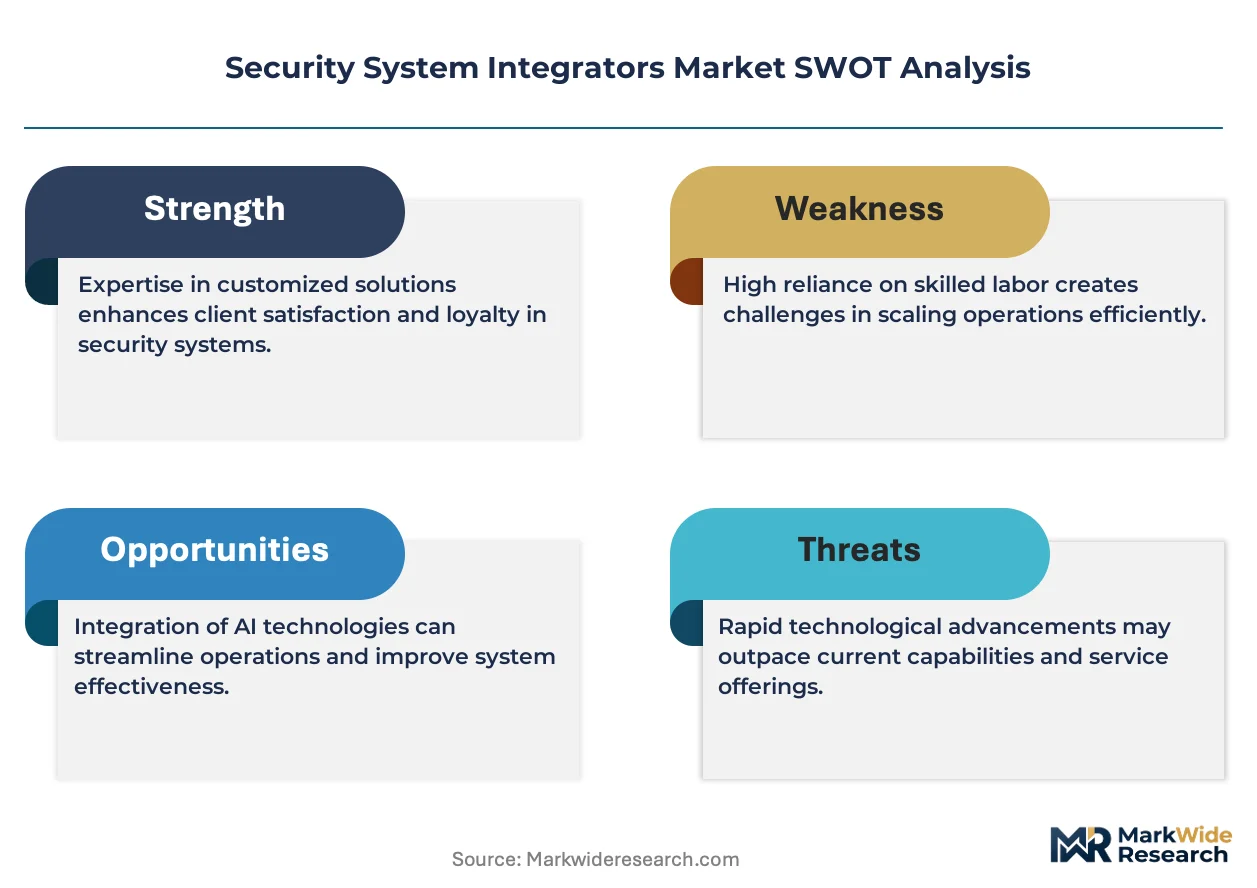
The security system integrators market presents a defensive moat story, primarily justified by the high regulatory entrenchment and associated switching costs for compliant, integrated solutions.
For Market Incumbents: Secure specialized hybrid talent through aggressive recruitment and internal upskilling programs to counter the critical skill shortage. Consolidate market share by acquiring smaller firms with niche expertise in rapidly expanding areas like AI analytics or cyber-physical security, addressing the threat of fragmented competition. Invest in R&D for proprietary software platforms to enhance integration capabilities and reduce reliance on third-party solutions.
For New Entrants and Emerging Players: Anchor in under-served regional markets or specialized high-compliance verticals, such as healthcare facilities requiring HIPAA-compliant solutions. Target small to medium-sized commercial enterprises with cost-effective, cloud-hosted security-as-a-service (SaaS) offerings, which represent a penetrable segment. A go-to-market strategy focusing on simplified deployment and predictable operational expenses can differentiate new players from traditional project-based integrators.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed integrators that have achieved regional scale but lack deep specialization in emerging technologies. The long-term viability favors firms capable of delivering converged IT/OT security solutions with strong regulatory compliance. Identify mid-sized integrators possessing certified expertise in critical infrastructure protection or advanced AI-based analytics as prime acquisition targets. Increasing enterprise procurement of managed security services across North America and Europe serves as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Managed Security Services | Shifts revenue to recurring models, provides stable income streams for integrators. |
| Invest in AI Analytics R&D | Offers advanced proactive intelligence, differentiates from basic monitoring services. |
| Acquire Cybersecurity Expertise | Addresses IT/OT convergence, mitigates cyber-physical threats for enterprise clients. |
| Pursue High-Compliance Certifications | Unlocks access to critical infrastructure and highly regulated market verticals. |
| Form IoT Integration Partnerships | Broadens solution capabilities, enhances data collection for smart city projects. |
Research Approach
Operator-level perspectives from physical security managers, IT network architects, facility directors, and compliance officers anchored the qualitative base for this analysis. This primary research was triangulated with extensive secondary validation from industry association reports, regulatory body publications like NIST and ENISA, technology vendor whitepapers, and public company financial filings. Both bottom-up market sizing and top-down validation were employed to ensure data accuracy.
Sensitivity analysis framed the forecast framework, modeling market dynamics across the modeling period. Segmentation dimensions included service type, technology, end-user industry, deployment model, and regional regulatory compliance. Compound annual growth rates were derived through statistical regression analysis, incorporating historical trends and expert consensus. Key forecast inputs included IoT device adoption rates in commercial facilities and critical infrastructure spending plans across the United States and Europe.
Material uncertainties — geopolitical events, rapid technological breakthroughs, and major regulatory shifts — sit outside the modeled envelope, influencing market trajectory. Forecasts reflect assumptions regarding component supply chain stability and the pace of hybrid skill development within the integrator workforce. Practitioners should keep alternative scenarios live as cyber-physical threats and regulatory frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Global Security Assurance Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Consumer Security Market
Security and Surveillance
Destructible Security Labels Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Lawful Interception Market
Security and Surveillance
Europe Security Assurance Market
Security and Surveillance
Surveillance Radars Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
Security Analytics Market
Security and Surveillance
Resale Authentication Services Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Threat Detection Systems Market
Security and Surveillance
Narcotics Scanner Market