
 Asia-Pacific Urban Security Screening Market | 2026-2036
Asia-Pacific Urban Security Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Urban Security Screening Market Analytics
Chinese security equipment manufacturing is restructuring around higher-throughput screening architectures for dense urban corridors. Nuctech Company leverages its domestic supply base to anchor large-scale deployments across Beijing and Shanghai metro networks. Smiths Detection competes through sustained R&D intensity in threat detection algorithms. Rapiscan Systems specializes in aviation-linked urban gateway installations across Southeast Asian hub cities.
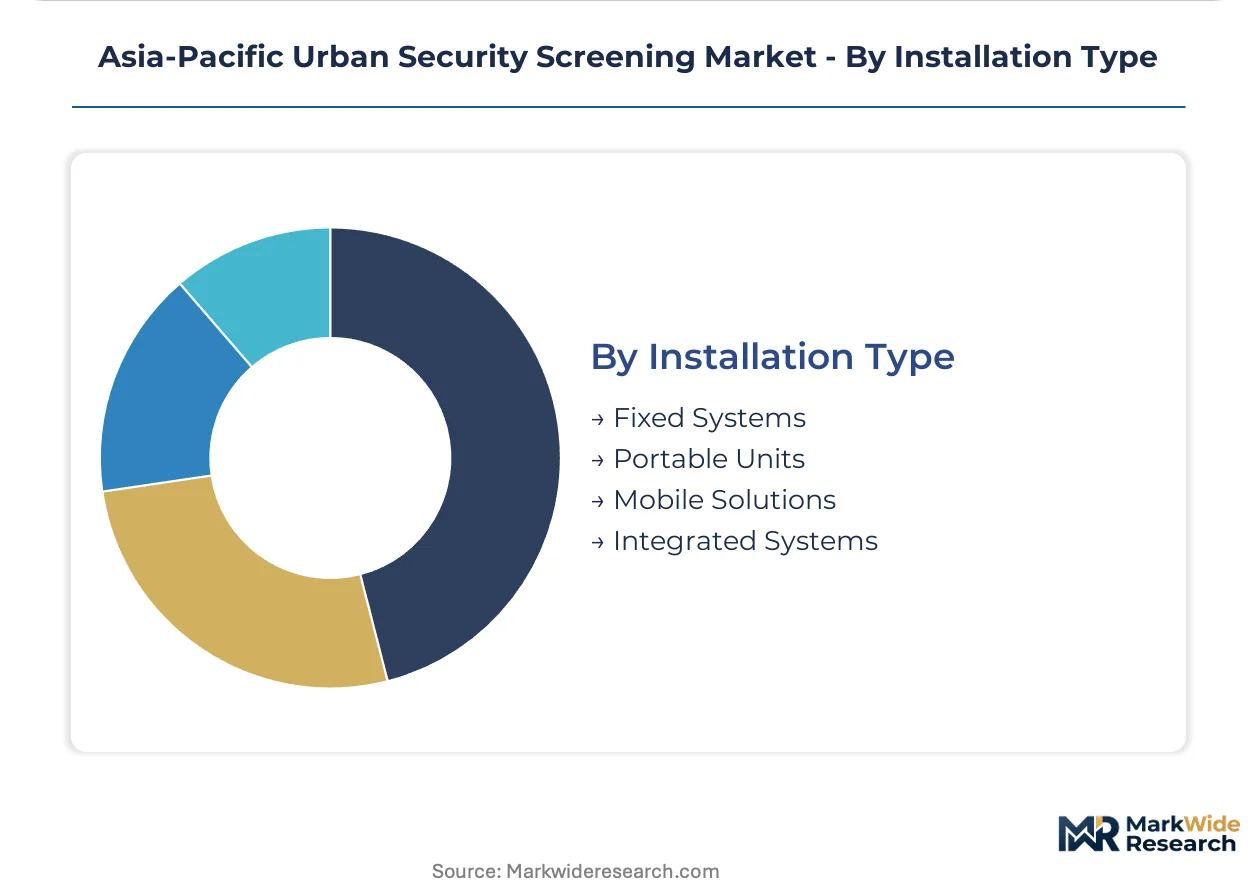
Asia-Pacific Urban Security Screening comprises integrated detection and identification systems engineered to intercept weapons, explosives, and unauthorized materials at pedestrian throughput rates exceeding 2,000 persons per hour, employing ionizing radiation, millimeter-wave, or multispectral sensor arrays. X-ray Machines dominate procurement volumes across public transportation terminals where baggage throughput demands exceed manual inspection capacity. AI-based Solutions represent the fastest-expanding technology segment as neural network classifiers reduce false alarm rates in biometric and explosive detection workflows. Fixed Systems retain the largest installed base, though Mobile Solutions are gaining traction for temporary event security and emergency response protocols.
China's SAMR enforces GB standards that mandate electromagnetic compatibility and radiation safety certifications for all deployed screening equipment. India's BIS operates parallel conformity assessment protocols for imported security systems entering government facilities and critical infrastructure. Japan's METI coordinates with rail operators to align JIS standards with next-generation passenger screening architectures. Stakeholders must weigh certification reciprocity costs against localized production incentives when configuring regional supply strategies.
Market Dynamics
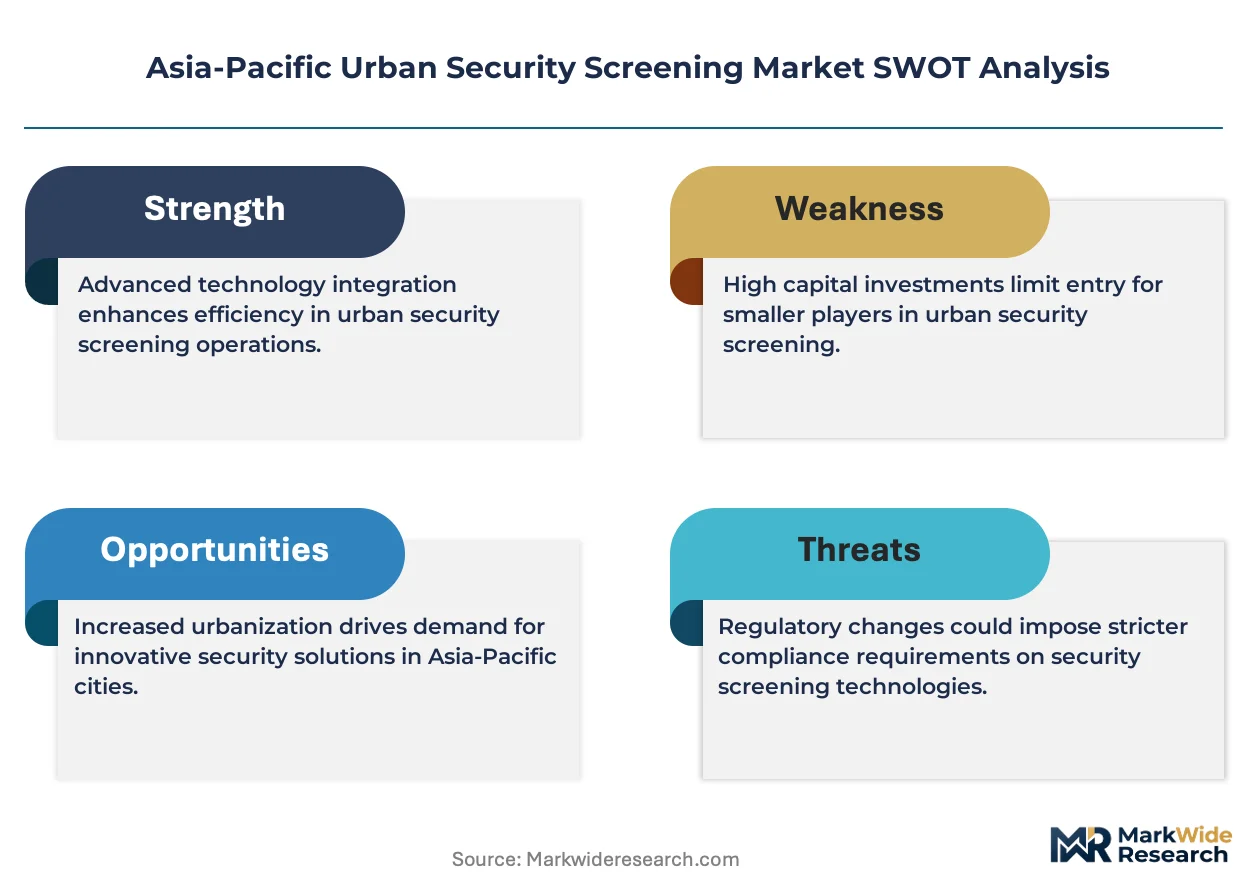
China's GB standards tightening under SAMR authority is compressing supplier qualification timelines and forcing domestic security equipment manufacturers to accelerate electromagnetic compatibility certification cycles ahead of foreign competitors.
Growth Catalysts
- Mass Transit Expansion:Seoul and Singapore metro authorities are mandating passenger screening protocols at new underground stations, creating sustained equipment procurement pipelines for ionizing radiation detection systems.
- India's PLI Scheme:Production-linked incentives for domestic manufacturing of critical infrastructure equipment are attracting component suppliers to establish screening equipment assembly near Mumbai and Delhi rail networks.
- Millimeter-Wave Maturation:Neural network classifiers integrated into biometric detection workflows are reducing false alarm rates below manual inspection thresholds, accelerating replacement of legacy metal detection arches.
Market Restraints
- Input Cost Volatility:Rare earth magnet supply from Chinese processors faces price instability, squeezing margins for permanent magnet-based sensor array manufacturers.
- Technical Throughput Ceiling:Current multispectral sensor architectures hit resolution-degradation thresholds above 2,500 persons per hour, limiting deployment at highest-density urban corridors.
- Regulatory Reciprocity Friction:India's BIS conformity assessment protocols for imported systems create 6-12 month entry delays versus domestic certification pathways.
Strategic Opportunities
- Vietnam's Emerging Urban Rail:Ho Chi Minh City and Hanoi metro construction phases lack established screening equipment suppliers, creating first-mover positioning for integrated detection system vendors.
- AI-Edge Convergence:On-device inference chips combined with millimeter-wave arrays enable real-time threat classification without cloud dependency, opening temporary event security deployments.
- Japan's METI Coordination:Alignment of JIS standards with next-generation passenger screening architectures creates regulatory tailwind for compliant equipment refresh cycles across Tokyo-Osaka corridors.
Industry Challenges
- Certification Timeline Compression:China's SAMR reduced GB standard compliance windows from 18 to 12 months, straining testing laboratory capacity and delaying product launches.
- Integration Complexity:Legacy X-ray baggage systems from 2010-2015 procurement waves lack API compatibility with AI-based threat detection overlays, forcing costly middleware development.
- Specialized Technician Scarcity:Ionizing radiation equipment maintenance requires certified engineers that training institutions in India and Southeast Asia have not scaled to meet deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Urban Security Screening Market |
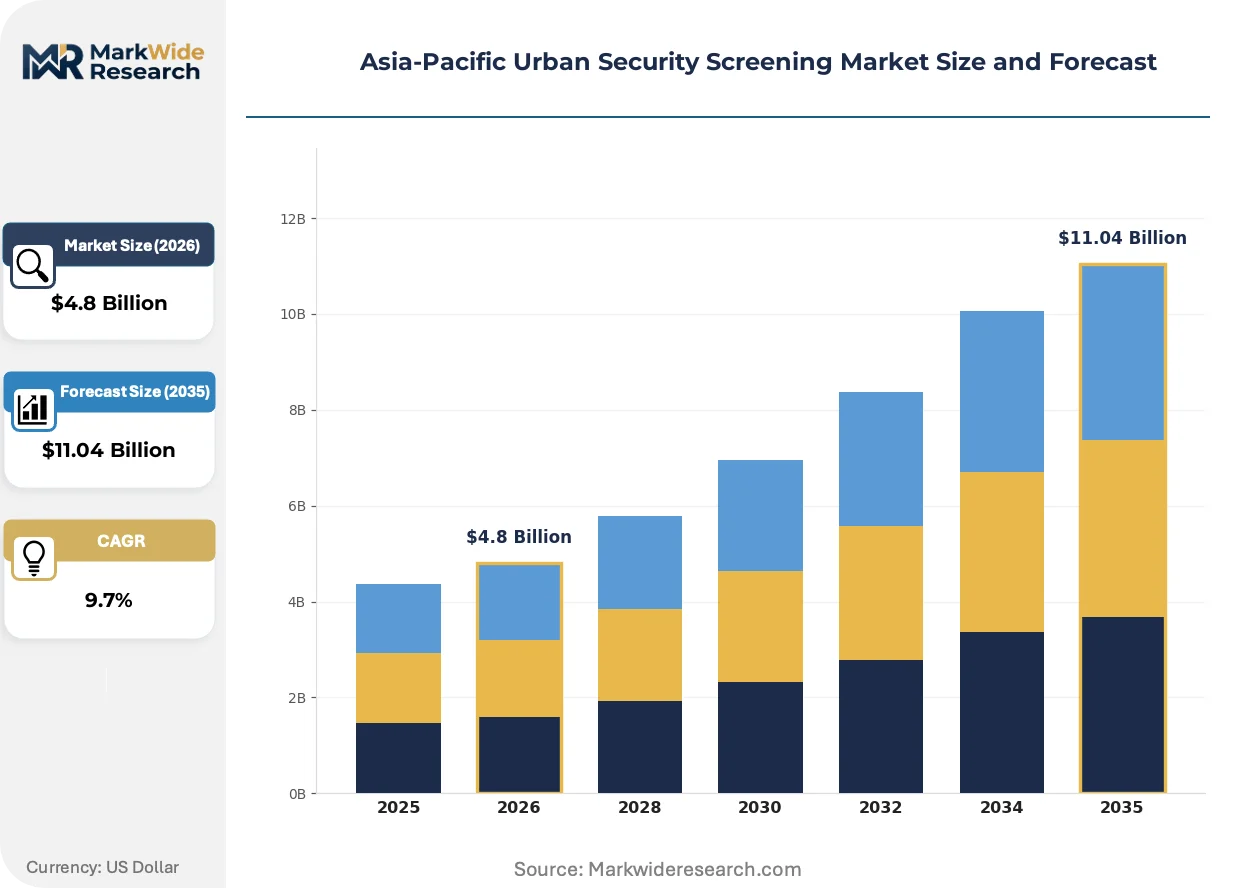
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Detectors, X-ray Machines, Explosive Detection Systems, Biometric Systems End User: Public Transportation, Government Facilities, Commercial Buildings, Airports Technology: AI-based Solutions, RFID, Optical Systems, Under Vehicle Surveillance Installation Type: Fixed Systems, Portable Units, Mobile Solutions, Integrated Systems |
| Companies Covered | Nuctech Company, Rapiscan Systems, Smiths Detection, 3DX-RAY, Astrophysics, L3Harris Technologies, Leidos, NEC Corporation, OSI Systems, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Urban Security Screening Market Evolving Landscape
Neural network architectures trained on explosive residue spectroscopy are compressing detection latency windows and enabling screening throughput rates that manual inspection protocols cannot match.
Millimeter-wave body scanners with embedded edge inference is consolidating passenger screening workflows at Beijing and Shanghai metro networks. Rail operators in these corridors are replacing walk-through metal detectors with volumetric imaging arrays that capture concealed objects under clothing without physical pat-downs. This hardware convergence is compressing the installed base of single-function detection equipment into unified threat-interception platforms.
China's SAMR enforcement of electromagnetic compatibility and radiation safety certifications under GB standards is disqualifying uncertified equipment from government facility tenders. Domestic manufacturers with captive testing facilities are accelerating product validation cycles while import-dependent vendors face extended approval timelines. The certification burden falls heaviest on mobile screening units deployed for temporary event security, where rapid deployment requirements clash with 12-month compliance windows.
Mass transit authorities across Asia-Pacific are unbundling after-sales service contracts from initial equipment procurement, creating standalone maintenance revenue pools. Seoul Metro and Singapore's LTA now separately tender 10-year service agreements for algorithm updates and sensor calibration, displacing the bundled warranty model that dominated 2015-2020 procurement cycles. This purchasing pattern shift is most visible in India's metropolitan rail networks, where Delhi Metro's recent tenders explicitly separate hardware supply from 15-year lifecycle support obligations.
Asia-Pacific Urban Security Screening Market Segmentation
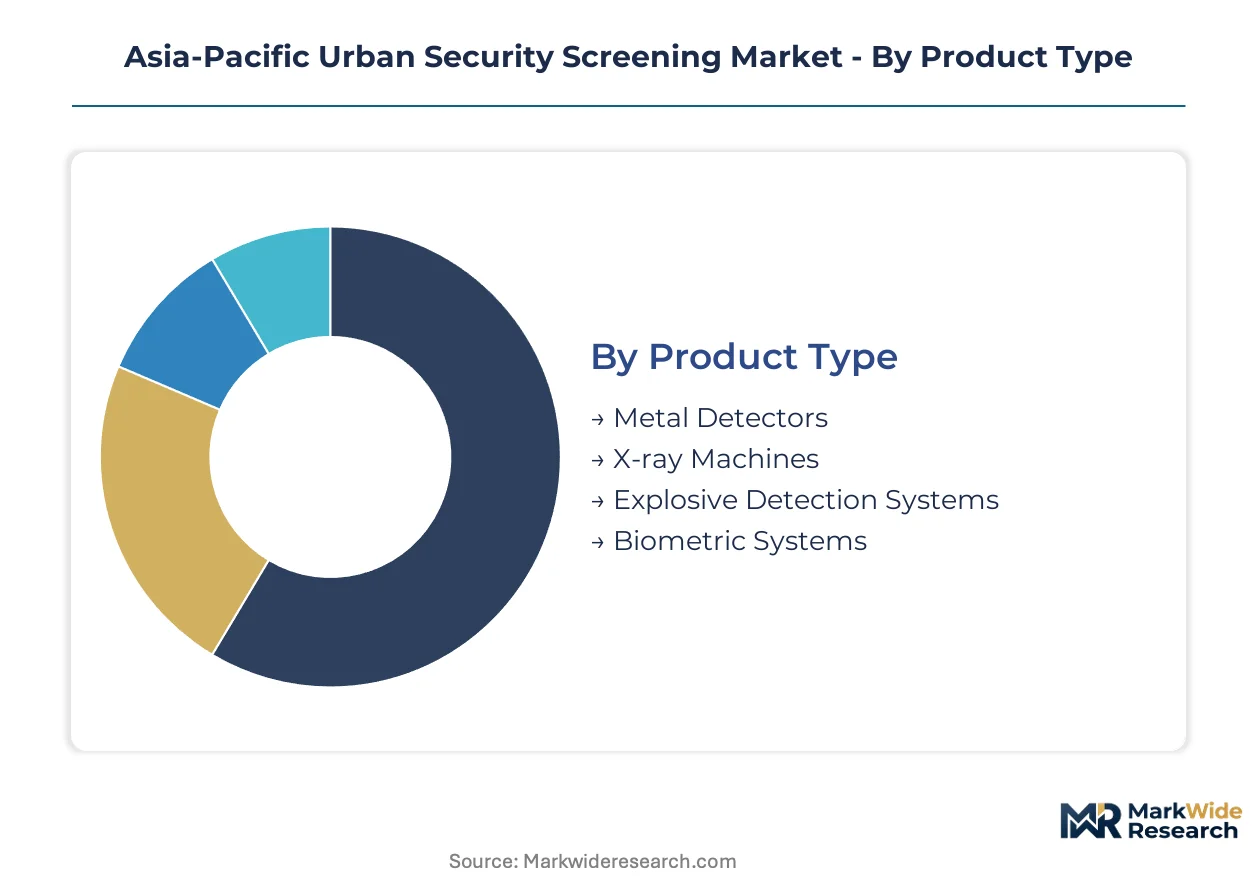
Urban security screening procurement in Asia-Pacific follows distinct technical and operational logics across product categories, end-use environments, and deployment architectures. Buyers segment investments by throughput requirements, threat profiles, and infrastructure integration constraints.
Product Type:
Procurement volumes concentrate where baggage and passenger throughput demands exceed manual inspection capacity, with technology selection driven by detection specificity versus speed trade-offs.
- X-ray Machines:These systems employ dual-energy or computed tomography arrays to discriminate organic from inorganic materials in baggage streams. Seoul Metro and Singapore's LTA mandate deployment at underground station entry points where passenger volumes exceed 2,000 persons per hour.
- Explosive Detection Systems:Ion mobility spectrometry and chemiluminescence sensors trace particulate residues on surfaces and in vapor phases. India's metropolitan rail networks are expanding procurement of these units for platform-level screening as urbanization accelerates through Mumbai and Delhi corridors.
- Metal Detectors:Walk-through and handheld units remain baseline screening tools for lower-threat environments.
- Biometric Systems:Facial recognition and iris scanning modules integrate with access control workflows.
Volume sits with X-ray Machines; growth tilts toward Explosive Detection Systems.
End User:
Application context dictates sensor configuration, with threat models and passenger flow patterns shaping equipment specifications.
- Public Transportation:Metro and rail operators require high-throughput screening that minimizes passenger delay. Beijing and Shanghai networks are replacing legacy metal detection arches with millimeter-wave volumetric imaging arrays that capture concealed objects without physical pat-downs.
- Airports:Aviation-linked gateways demand multi-layered detection combining baggage X-ray, body scanning, and explosive trace portals. Southeast Asian hub cities are expanding integrated screening lanes to accommodate transfer passenger volumes.
- Government Facilities:China's SAMR-enforced GB standards mandate electromagnetic compatibility and radiation safety certifications for all equipment entering state infrastructure.
- Commercial Buildings:Corporate and retail installations prioritize unobtrusive form factors and rapid deployment.
Procurement scale concentrates in Public Transportation; technology refresh cycles are steepest in Airports.
Technology:
Algorithm sophistication is displacing hardware-centric detection, with neural network classifiers reducing false alarm rates below manual inspection thresholds.
- AI-based Solutions:Deep learning architectures trained on explosive residue spectroscopy and anomaly detection compress classification latency. Edge inference chips enable real-time threat assessment without cloud dependency, opening temporary event security deployments.
- RFID:Radio-frequency identification tracks screened items and personnel through secure zones.
- Optical Systems:Camera-based analytics monitor crowd behavior and abandoned object detection.
- Under Vehicle Surveillance:Scanning arrays inspect vehicle undercarriages at facility entry points.
Installed base favors Optical Systems; capability investment flows fastest into AI-based Solutions.
Installation Type:
Deployment flexibility requirements split procurement between permanent infrastructure integration and rapid-repositioning architectures.
- Fixed Systems:Hardwired screening lanes with embedded power and data infrastructure dominate metro network buildouts. Delhi Metro's recent tenders specify 15-year lifecycle support obligations separate from hardware supply.
- Mobile Solutions:Trailer-mounted and rapid-deploy units serve temporary event security and emergency response protocols. China's 12-month GB certification windows strain rapid deployment requirements for these units.
- Portable Units:Battery-powered handheld and lightweight systems support checkpoint flexibility.
- Integrated Systems:Unified threat-interception platforms consolidate multiple sensor modalities into single operational interfaces.
Revenue concentration rests with Fixed Systems; specification momentum favors Mobile Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing clusters in Jiangxi and Inner Mongolia anchor sensor array manufacturing for the Asia-Pacific Urban Security Screening Market. Procurement patterns diverge sharply across national regulatory environments, with certification timelines and transit infrastructure investment cycles reshaping equipment deployment geography.
China
Beijing and Shanghai metro networks are replacing legacy metal detection arches with millimeter-wave volumetric imaging arrays. SAMR's GB standards enforcement compresses certification windows to twelve months, advantaging domestic manufacturers with captive electromagnetic compatibility testing facilities. Nuctech Company leverages its Zhengzhou supply base to anchor large-scale deployments across these corridors.
India
Mumbai and Delhi metropolitan rail networks are expanding platform-level explosive detection procurement as urbanization accelerates. BIS conformity assessment protocols for imported systems create six-to-twelve month entry delays versus domestic certification pathways. The PLI scheme for critical infrastructure equipment is attracting component suppliers to establish assembly operations near these rail networks.
Japan
Tokyo-Osaka rail corridors are refreshing fixed screening installations under METI-coordinated JIS standard alignments. The regulator's coordination with rail operators creates regulatory tailwind for next-generation passenger screening architectures. Kanto and Kansai industrial clusters supply precision sensor components for these integrated detection systems.
South Korea
Seoul Metro is mandating passenger screening protocols at new underground stations, creating sustained equipment procurement pipelines. The national rail authority's specifications favor ionizing radiation detection systems with throughput rates exceeding two thousand persons per hour. Gyeonggi-do manufacturing zones produce high-density sensor arrays for these deployments.
Singapore
Singapore's LTA is unbundling after-sales service contracts from initial equipment procurement, creating standalone maintenance revenue pools. The authority now separately tenders ten-year service agreements for algorithm updates and sensor calibration. Jurong industrial estates host calibration facilities serving Southeast Asian hub city deployments.
Asia-Pacific Urban Security Screening Market Competitive Landscape
Global majors compete with regional champions across certification velocity and domestic supply chain integration. Market structure tilts toward consolidated procurement at the metro-network tier, with fragmented competition for temporary event security deployments. Two archetypes dominate: domestic manufacturers with captive testing facilities, and technology licensors with sustained algorithm R&D intensity. Competitive moves concentrate on vertical integration into rare earth magnet supply and strategic partnerships for AI-edge inference chip sourcing.
Within the domestic-manufacturer archetype, Nuctech Company represents the vertically integrated model with Zhengzhou-based production. Smiths Detection and Rapiscan Systems exemplify the technology-licensor tier, with the former anchoring sustained R&D positioning and the latter specializing in aviation-linked gateway installations. These three occupy distinct competitive positions: domestic supply base control, algorithm development intensity, and hub-city deployment specialization respectively.
| Leading Market Players |
|---|
| Nuctech Company |
| Rapiscan Systems |
| Smiths Detection |
| 3DX-RAY |
| Astrophysics |
| L3Harris Technologies |
| Leidos |
| NEC Corporation |
| OSI Systems |
| Others |
Value Network & Pricing Analysis
China's dual carbon goals under MEE authority are gating qualified supply access for high-throughput screening equipment, compressing supplier pools to certified domestic manufacturers and elevating premium-tier pricing for GB-compliant architectures across Beijing and Shanghai metro procurement cycles.
Pricing Analysis
Warranty and service-bundling unbundling now separates hardware procurement from 10-15 year lifecycle support obligations at Seoul Metro and Singapore's LTA, shifting toward transactional per-unit equipment sales with standalone algorithm update contracts. Price differentiation stems from SAMR certification velocity and electromagnetic compatibility testing access, with import-dependent vendors facing 6-12 month approval delays that compress their pricing power. Cost compression in mobile screening units intensifies because rapid deployment requirements clash with China's 12-month GB compliance windows. Government facility buyers exhibit lowest price sensitivity given mandate-driven procurement timelines, while temporary event security operators face acute margin pressure from certification timeline compression.
Supply Chain Analysis
Rare earth magnet supply rests on Chinese processors in Jiangxi and Inner Mongolia, feeding permanent magnet-based sensor array production for millimeter-wave and ionizing radiation detection systems. Component dependencies include edge inference chips from Taiwanese foundries, precision optics from Japanese industrial clusters in Kanto and Kansai, and electromagnetic shielding materials from South Korean suppliers in Gyeonggi-do. Single-source vulnerability concentrates in rare earth processing capacity, where price instability squeezes margins for sensor manufacturers. Distribution runs through metro-network tier procurement offices with consolidated tender structures, displacing fragmented channel competition for temporary deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around certification velocity and captive testing infrastructure, with SAMR's compressed GB compliance windows forcing import-dependent vendors toward exit or domestic partnership structures.
For Market Incumbents: Deepen backward integration into rare earth magnet supply through offtake agreements with Jiangxi processors, securing input cost stability against price volatility that threatens sensor array margins. Accelerate electromagnetic compatibility certification cycles at captive Zhengzhou testing facilities to maintain 12-month product launch velocity versus foreign competitors facing extended SAMR approval timelines. Lock in 15-year service contract separations at Delhi Metro and Singapore LTA to capture standalone maintenance revenue pools before competitors replicate unbundled procurement structures. For New Entrants and Emerging Players: Begin with Vietnam's Ho Chi Minh City and Hanoi metro construction phases, where established screening equipment suppliers remain absent and first-mover positioning for integrated detection systems is achievable. Target temporary event security deployments leveraging AI-edge convergence with on-device inference chips that bypass cloud dependency and enable rapid repositioning. Pursue joint certification pathways with domestic Chinese manufacturers to circumvent SAMR's 12-month standalone approval barriers for imported equipment. For Investors and Strategic Acquirers: METI's coordination of JIS standard alignment with next-generation passenger screening architectures is the leading indicator that Tokyo-Osaka corridor equipment refresh cycles will accelerate compliant system replacement demand. Position acquisition screening toward domestic manufacturers with captive electromagnetic compatibility testing facilities and established SAMR certification track records, as these assets compound competitive moats under compressed compliance windows. Watch for BIS reciprocity friction resolution between India and major supplier countries as the signal for import-dependent vendor re-entry viability in Mumbai and Delhi metropolitan rail procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | Captive SAMR testing facilities compress product validation cycles ahead of foreign competitors facing 12-month approval windows. |
| AI-Edge Inference Partnership | On-device chip integration enables real-time threat classification without cloud dependency for temporary event deployments. |
| Rare Earth Magnet Offtake Agreement | Upstream control over Jiangxi processor supply stabilizes sensor array input costs against price volatility squeezing margins. |
| Service Contract Unbundling | Standalone 10-15 year maintenance agreements at Seoul Metro and Singapore LTA displace bundled warranty revenue models. |
| Vietnam Metro First-Mover Positioning | Ho Chi Minh City and Hanoi construction phases lack established suppliers, creating integrated detection system entry opportunity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with metro procurement officers, SAMR certification specialists, rail network engineering directors, and aftermarket service heads with secondary validation against BIS conformity assessment protocols, METI JIS standard documentation, and Seoul Metro tender disclosures. Bottom-up equipment deployment counts across Beijing, Shanghai, Mumbai, Delhi, Tokyo, Osaka, Seoul, and Singapore corridors were triangulated against top-down market sizing from regional transit infrastructure investment pipelines.
Data-stream reconciliation across sensor modality procurement volumes, certification timeline distributions, and service contract unbundling patterns shaped the analytical framework. Segmentation dimensions modeled include product type, end-use environment, technology sophistication, and installation architecture across the projection horizon. CAGRs were derived from equipment replacement cycle analysis and urban rail network expansion pipelines, with neural network classifier adoption curves and millimeter-wave deployment velocities serving as technology-specific forecast inputs.
Underlying measurement precision varies by segment; fixed system procurement at established metro networks carries tighter precision than mobile solution deployment for temporary event security where rapid repositioning requirements clash with certification windows. Forecasts reflect assumptions around SAMR enforcement consistency, BIS reciprocity pathway evolution, and rare earth magnet supply stability. Regulatory timeline compression, input cost volatility, and technician training scalability gaps constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
North America Security Services Market
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Middle East and Africa Cargo and Vehicle Screening Market
Security and Surveillance
Smart Security Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Smart Home Security Market
Security and Surveillance
Security Intelligence Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Europe Rockfall Radar Market
Security and Surveillance
Global School and Campus Security Market
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Alarm Monitoring Software Market
Security and Surveillance
Middle East and Africa Cargo Inspection Market
Security and Surveillance
Commercial Security Market
Security and Surveillance
Security and Surveillance Equipment Market
Security and Surveillance
Explosive Trace Detection Market