
 Middle East Manned Security Services Market | 2026-2036
Middle East Manned Security Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Manned Security Services Market Foresight
Saudi Arabia's giga-project pipeline is rewriting procurement patterns for manned guarding across the Middle East. Transguard Group LLC leverages its integrated facilities management platform to bundle security with logistics and aviation services across the UAE. G4S plc anchors its regional footprint through long-term government and critical infrastructure contracts in multiple Gulf states. Spark Security Services LLC differentiates through specialized event security and VIP protection capabilities targeting Riyadh's entertainment and tourism expansion.
Manned security services comprise the deployment of trained personnel for asset protection, access control, and threat response, typically operating under licensed frameworks with specified training hours, weapon authorization tiers, and duty-cycle limitations; these services function as the frontline layer in multi-tiered physical security architectures for commercial, governmental, and residential assets. On-site security dominates current revenue flows due to persistent demand from oil refineries, diplomatic compounds, and luxury retail malls across Dubai and Abu Dhabi. Event security represents the fastest-expanding service category as Saudi Arabia scales its entertainment and sporting calendar, while contract-based operational models capture the deepest margin pools through multi-year facility management agreements that embed security within broader service portfolios.
The UAE's Security Industry Regulatory Agency and Saudi Arabia's Private Security Departments Directorate enforce licensing, training accreditation, and equipment standards that determine market access for service providers across their jurisdictions. Compliance with these national frameworks shapes workforce costs, technology integration requirements, and competitive eligibility for government tenders throughout the Gulf. Stakeholders must monitor evolving localization mandates and cross-border labor mobility restrictions that will determine staffing economics and regional expansion feasibility.
Market Dynamics
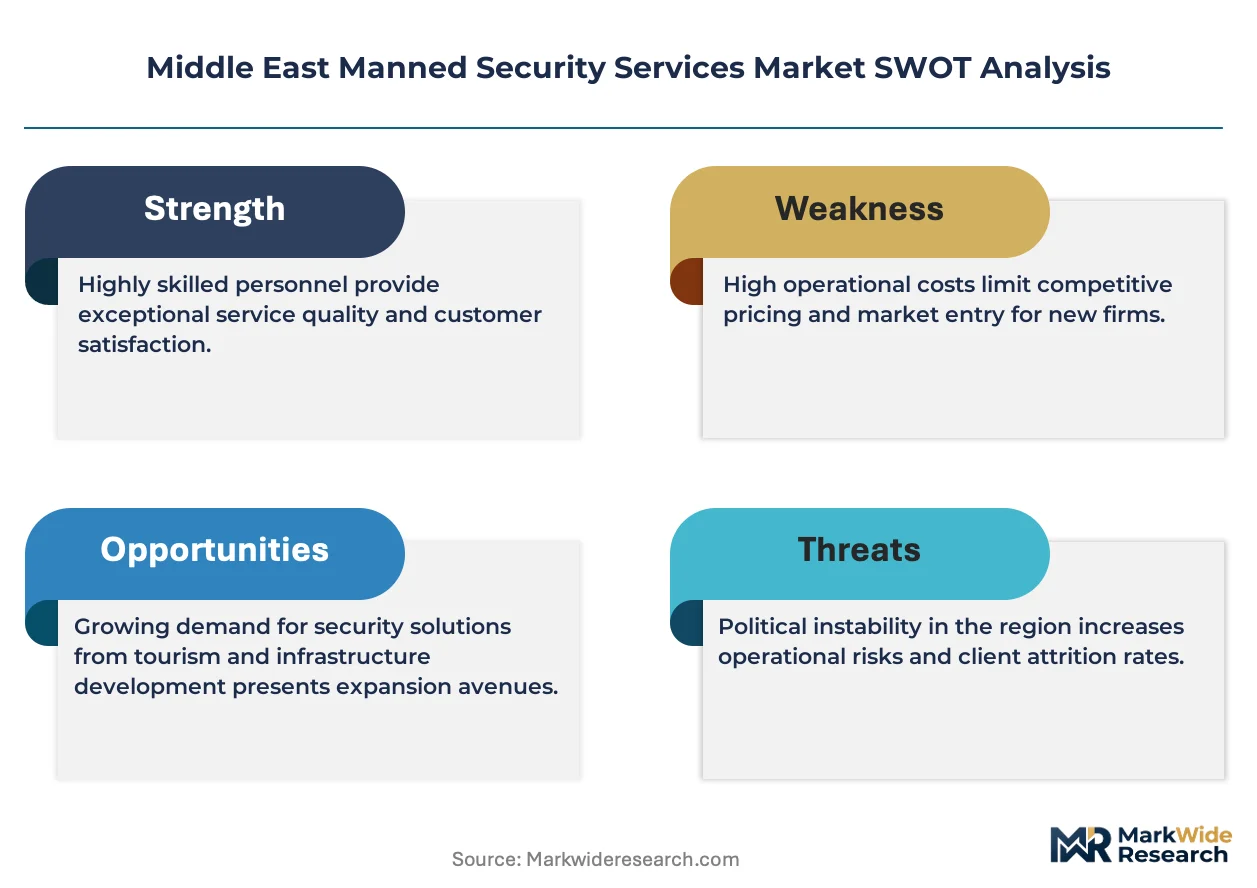
Localization mandates across the Gulf Cooperation Council are fundamentally restructuring workforce economics and competitive eligibility for security service providers. The UAE's Emiratisation quotas and Saudi Arabia's Saudization programs are forcing operators to rebuild recruitment pipelines and training infrastructure around citizen labor pools rather than traditional expatriate-dependent models.
Growth Catalysts
- Critical Infrastructure Expansion:Oil and gas operators across Saudi Arabia, Kuwait, and the UAE are expanding armed guarding contracts to protect downstream refining complexes and strategic petroleum reserves against asymmetric threats.
- Vision 2030 Entertainment Buildout:Saudi Arabia's giga-projects along the Red Sea coast and in Riyadh are generating concentrated demand for integrated manned guarding and electronic surveillance solutions at scale.
- Smart City Integration:Dubai's command-and-control centers and Abu Dhabi's Safe City initiatives are embedding security personnel within networked urban monitoring architectures.
Market Restraints
- Labor Cost Inflation:Citizen recruitment premiums and mandatory training investments under Emiratisation and Saudization frameworks are compressing margins for mid-tier operators.
- Technology Substitution Pressure:AI-powered video analytics and drone perimeter surveillance are displacing routine manned patrol functions at airports and logistics hubs.
- Cross-Border Mobility Restrictions:Visa quota limitations and bilateral labor agreements are constraining workforce flexibility between Gulf Cooperation Council jurisdictions.
Strategic Opportunities
- Event Security Specialization:Saudi Arabia's entertainment calendar expansion creates white space for providers with crowd management and VIP protection capabilities.
- Integrated Facilities Management Bundling:Long-term government tenders increasingly favor operators combining security with logistics, aviation, and soft services under single accountability.
- Regulatory Compliance Services:The UAE's Security Industry Regulatory Agency and Saudi Arabia's Private Security Departments Directorate are creating advisory revenue streams around licensing and accreditation support.
Industry Challenges
- Certification Pipeline Bottlenecks:Mandatory training hours and weapon authorization tiers under national regulatory frameworks are extending time-to-deployment for new personnel.
- Legacy System Integration:Manned guarding operators face complexity embedding human response protocols within existing electronic access control and video management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Manned Security Services Market |
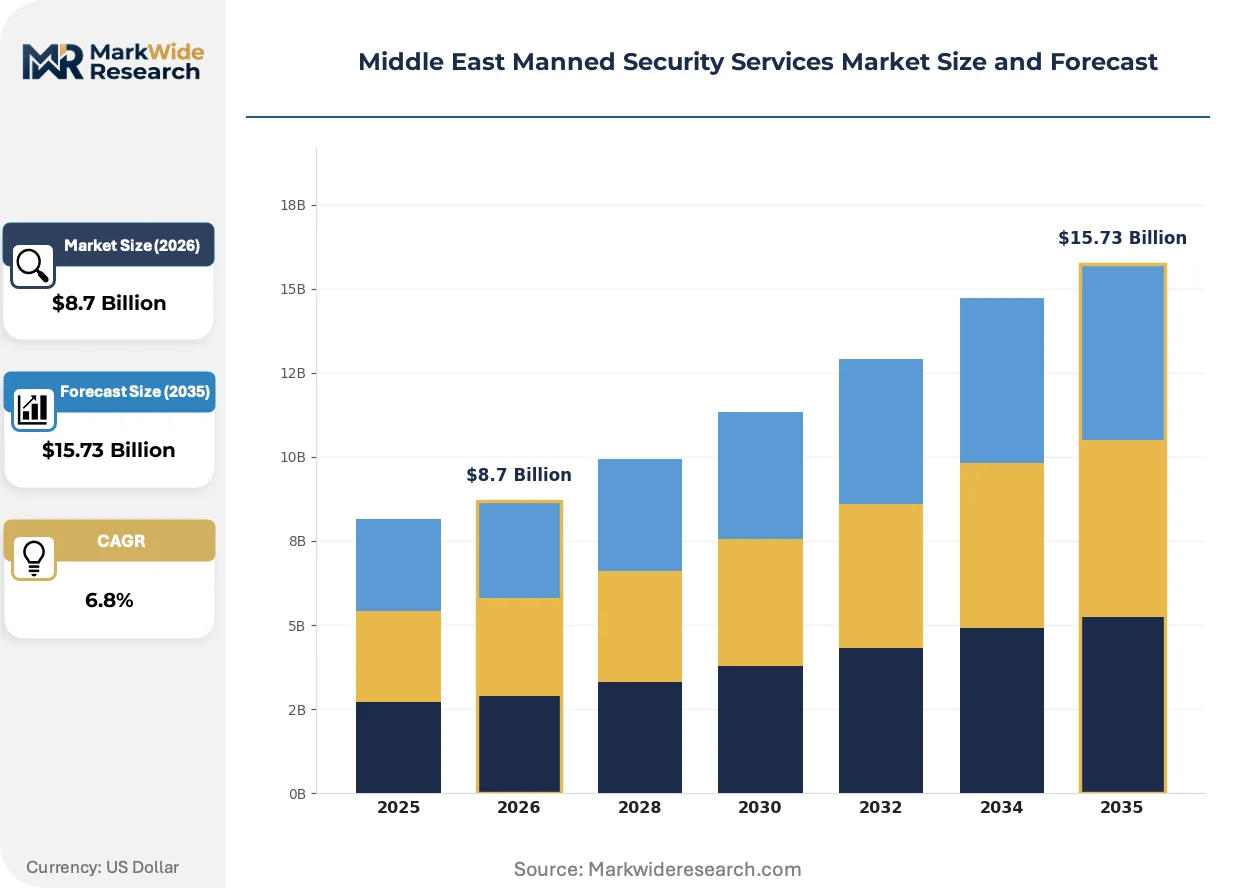
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Site Security, Event Security, Mobile Patrols, Residential Security Industry Vertical: Hospitality, Retail, Construction, Government Client Type: Corporate, Private Residences, Educational Institutions, Healthcare Facilities Operational Model: Contract-Based, On-Demand, Integrated Services, Outsourced Solutions |
| Companies Covered | Spark Security Services LLC, Arabian Security & Safety Services Co. Limited, Hemaya Security Services Co., Royal Falcon Security, Jond Security, Transguard Group LLC, Vanguards Safety & Security Services, Sharaf Din Group of Companies, G4S plc, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Manned Security Services Market Shifts & Advancements
Technology convergence and regulatory tightening are compressing the traditional separation between physical guarding and digital surveillance across Middle East security operations. Service providers are rebuilding operating models around integrated human-machine interfaces rather than standalone personnel deployment.
Command center software is virtualizing guard tour management and incident reporting across Dubai's commercial towers and Riyadh's government complexes. Facility managers are adopting these platforms to consolidate visibility across dispersed assets. The technology is virtualizing supervisory overhead and enabling centralized response coordination that reduces on-site headcount requirements without coverage degradation.
The UAE's Security Industry Regulatory Agency has mandated standardized training curricula and equipment specifications that determine market access for all licensed providers. This framework is consolidating supplier eligibility and raising capital barriers for new entrants. Mid-sized operators across Dubai and Abu Dhabi are responding through consortium bidding and shared training academy investments to spread compliance costs.
Buyers are unbundling security from bundled facilities management contracts and re-tendering on performance-based metrics rather than input-based staffing levels. Oil and gas majors and diplomatic compounds are leading this transition. The shift is most visible in Saudi Arabia's megaproject procurement, where operators compete on response-time guarantees and incident-resolution outcomes rather than guard counts alone.
Middle East Manned Security Services Market Segmentation
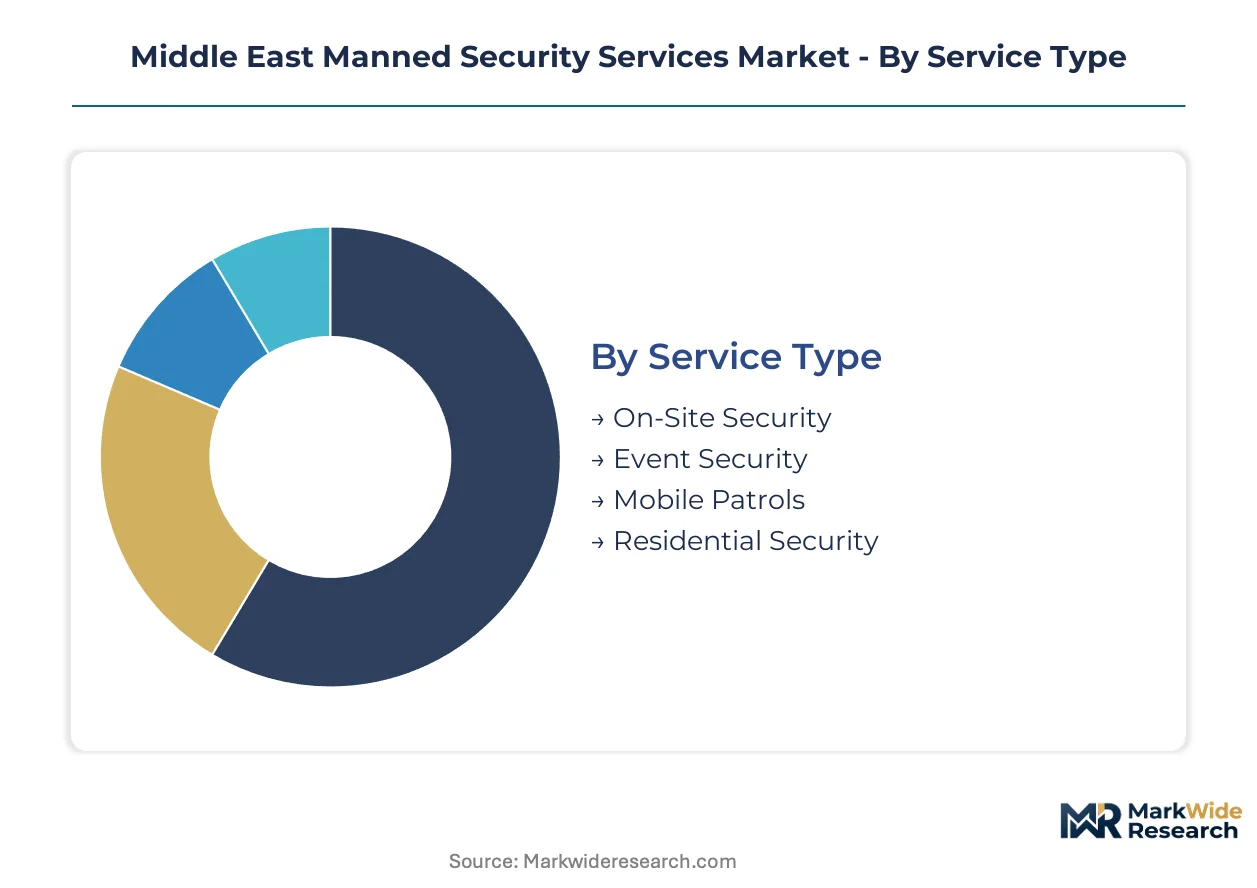
Segmentation in the Middle East manned security services market reveals distinct procurement patterns across service delivery modes and client risk profiles. Each category exposes different margin structures, regulatory exposure, and technology integration requirements that shape competitive positioning.
Service Type:
After-sales service intensity varies sharply across service types, with on-site deployments requiring continuous workforce management and event security demanding rapid mobilization capabilities.
- On-Site Security:Armed and unarmed personnel stationed permanently at fixed facilities including oil refineries, diplomatic compounds, and commercial towers. Demand concentrates in Saudi Arabia's downstream refining complexes and Abu Dhabi's strategic petroleum reserves, driven by asymmetric threat assessments and mandatory Emiratisation quotas reshaping workforce composition.
- Event Security:Crowd management, access control, and VIP protection for temporary gatherings. Saudi Arabia's Vision 2030 entertainment calendar expansion in Riyadh and the Red Sea coast is accelerating procurement for integrated guarding and electronic surveillance at scale.
- Mobile Patrols:Vehicle-based perimeter coverage and randomized inspection routes serving dispersed industrial and logistics assets across Dubai's Jebel Ali corridor.
- Residential Security:Gated community guarding and concierge security for luxury developments in Dubai's Palm Jumeirah and Riyadh's diplomatic quarter.
By volume, On-Site Security leads. By growth pace, Event Security is ahead.
Industry Vertical:
Cost tier differentiation separates premium-protected government contracts from price-sensitive retail deployments.
- Hospitality:Guest-facing security and loss prevention for hotels and resorts. Full treatment: Concierge-trained personnel managing access control and emergency response protocols. Saudi Arabia's Red Sea giga-projects and Dubai's luxury hotel pipeline are concentrating demand for bilingual guarding with customer service accreditation.
- Retail:Shopfloor surveillance and shrinkage control for malls and luxury boutiques. Full treatment: Uniformed and plainclothes personnel deployed across Dubai Mall and Abu Dhabi Galleria assets. The UAE's mandatory licensing under SIRA frameworks is elevating training investments and compressing margins for mid-tier operators.
- Construction:Site perimeter guarding and equipment protection for megaproject developments across Riyadh's Qiddiya and Diriyah Gate.
- Government:Critical infrastructure protection and diplomatic compound security under long-term federal contracts in multiple Gulf states.
Hospitality and Government capture premium pricing tiers. Retail faces the steepest cost compression from technology substitution.
Client Type:
Application complexity escalates from standardized corporate protocols to specialized healthcare compliance requirements.
- Corporate:Headquarters guarding, executive protection, and facility access management for multinational and regional enterprises.
- Private Residences:Family office security and residential estate protection for high-net-worth individuals in Emirates Hills and Riyadh's Al Yasmin district.
- Educational Institutions:Campus perimeter control and student safety protocols for universities and international schools across the UAE and Saudi Arabia.
- Healthcare Facilities:Patient area monitoring, emergency department security, and pharmaceutical storage protection under MOHAP and SFDA regulatory frameworks.
Corporate clients dominate contract value. Healthcare Facilities are expanding most quickly due to hospital privatization programs.
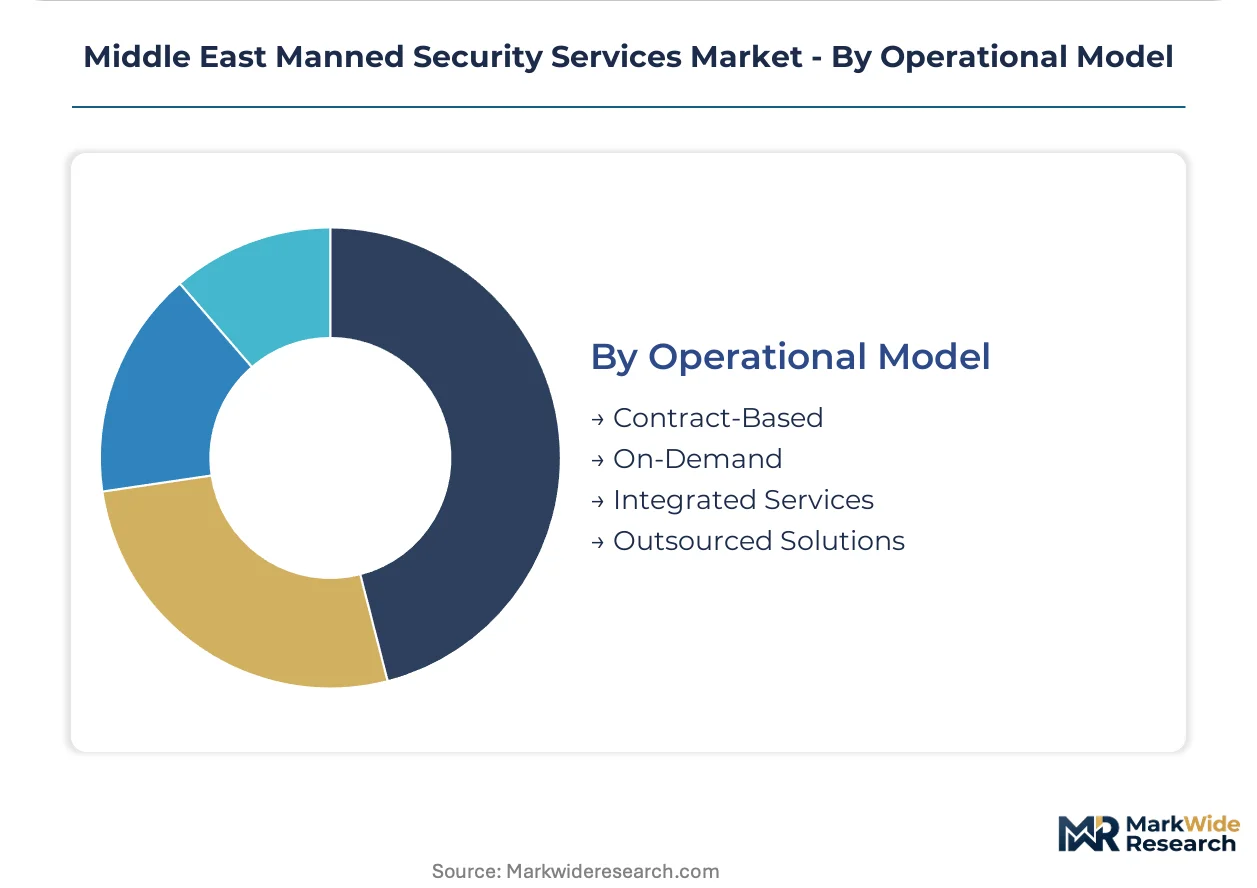
Operational Model:
Margin concentration favors integrated multi-service contracts over transactional on-demand arrangements.
- Contract-Based:Multi-year facility management agreements embedding security within broader service portfolios. Full treatment: Long-term accountability for staffing, training, and equipment under single-provider arrangements. Saudi Arabia's megaproject procurement is shifting toward performance-based metrics with response-time guarantees rather than input-based guard counts.
- On-Demand:Short-notice personnel deployment for temporary requirements and emergency coverage. Full treatment: Rapid mobilization capabilities without long-term workforce commitment. Dubai's event calendar and construction project spikes create intermittent demand that strains recruitment pipelines under Emiratisation constraints.
- Integrated Services:Bundled security with logistics, aviation, and soft facilities management under unified command structures.
- Outsourced Solutions:Third-party guarding replacing in-house security departments for cost and compliance optimization.
Contract-Based models lock in the deepest margin pools. On-Demand is gaining share fastest as event security procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Private Security Departments Directorate and the UAE's Security Industry Regulatory Agency anchor procurement frameworks across the Gulf Cooperation Council, with national localization mandates reshaping workforce economics and competitive eligibility throughout the region.
United Arab Emirates
Dubai's Safe City initiatives and Abu Dhabi's command-and-control centers concentrate demand for integrated manned guarding and electronic surveillance solutions. SIRA-mandated training curricula and equipment specifications determine market access for all licensed providers. Dubai Mall and Jebel Ali logistics corridor anchor commercial security deployment at scale.
Saudi Arabia
Vision 2030 megaprojects along the Red Sea coast and in Riyadh are generating procurement for event security and VIP protection capabilities. The Private Security Departments Directorate enforces weapon authorization tiers and duty-cycle limitations that extend time-to-deployment for new personnel. NEOM and Qiddiya developments concentrate integrated facilities management bundling opportunities.
Kuwait
Downstream refining complexes and strategic petroleum reserves drive armed guarding contracts against asymmetric threat assessments. The country's national security regulator mandates licensing frameworks that parallel Gulf Cooperation Council standards. Al-Ahmadi industrial zone anchors oil and gas infrastructure protection demand.
Qatar
Diplomatic compound security and hospitality guarding concentrate procurement around Doha's diplomatic quarter and luxury hotel pipeline. National training accreditation requirements align with broader Gulf localization objectives. Lusail City development embeds security personnel within smart city monitoring architectures.
Bahrain
Financial district guarding and port security operations concentrate demand in Manama's banking hub and Khalifa Bin Salman Port. The country's security licensing authority maintains workforce composition standards consistent with regional Emiratisation-equivalent programs. Sitra industrial area anchors petrochemical facility protection contracts.
Middle East Manned Security Services Market Competitive Landscape
Integrated facilities management conglomerates and specialized security operators split the market across divergent capability requirements. The vendor base organizes around three strategic archetypes: bundled service platforms combining security with logistics and aviation, pure-play guarding specialists with regulatory compliance depth, and event-centric mobilization providers. Dominant competitive moves include multi-year government tender pursuit and shared training academy investments to spread localization compliance costs.
Within the integrated services tier, Transguard Group LLC and G4S plc exemplify operators embedding security within broader facilities management portfolios. Spark Security Services LLC occupies a position among specialists targeting event security and VIP protection capabilities. These three anchors represent divergent responses to Saudi Arabia's performance-based procurement shift and UAE Emiratisation workforce restructuring.
| Leading Market Players |
|---|
| Spark Security Services LLC |
| Arabian Security & Safety Services Co. Limited |
| Hemaya Security Services Co. |
| Royal Falcon Security |
| Jond Security |
| Transguard Group LLC |
| Vanguards Safety & Security Services |
| Sharaf Din Group of Companies |
| G4S plc |
| Others |
Supply & Pricing Matrix
Jebel Ali logistics corridor freight costs cascade through Middle East manned security services, concentrating supply-side power among integrated facilities management operators while forcing price stratification between premium-certified and economy-tier guarding contracts across Dubai and Riyadh.
Pricing Analysis
Price spreads between Saudi Arabia and the UAE reach three-to-one for equivalent event security mobilizations. Contract-based operational models embed security within broader facilities management portfolios, commanding premium positioning through multi-year accountability structures. Cost compression in mid-tier retail guarding intensifies because AI-powered surveillance substitutes routine patrol functions. Government and oil and gas clients exhibit lowest price sensitivity; retail mall operators face acute margin pressure from technology substitution.
Supply Chain Analysis
Personnel recruitment pipelines draw from India, Pakistan, and the Philippines for expatriate labor pools, though Emiratisation and Saudization mandates are restructuring citizen workforce development. Training infrastructure, uniform and equipment procurement, and technology platform licensing constitute critical input dependencies. Single-source vulnerability concentrates in SIRA-mandated certification academies controlling market access eligibility. Distribution runs through direct government tender pursuit and consortium bidding arrangements spreading compliance costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes this market as performance-based procurement unbundles security from legacy facilities management contracts, creating specialized niches for event-centric and technology-integrated operators across Saudi megaprojects and UAE commercial assets.
For Market Incumbents: Entrench competitive position through shared training academy investments that spread Emiratisation compliance costs across consortium partners. Deepen backward integration into proprietary command center software platforms to embed human response protocols within electronic surveillance architectures. AI-powered video analytics substitution threatens routine patrol revenue; vertical control over technology licensing creates defensive moats.
For New Entrants and Emerging Players: Kuwait's downstream refining corridor offers underpenetrated white space for armed guarding specialists with asymmetric threat assessment capabilities. Target event security procurement in Riyadh's entertainment district through rapid mobilization capabilities and VIP protection accreditation. Regulatory compliance advisory services around SIRA and Private Security Departments Directorate frameworks provide low-capital entry path.
For Investors and Strategic Acquirers: Specialist operators with event security depth and crowd management certification represent priority acquisition archetypes. Long-term viability hinges on positioning within Saudi Vision 2030 procurement pipelines and UAE smart city integration mandates. Watch for inflection when performance-based tendering shifts from pilot programs to standard megaproject procurement protocol.
| Strategic Initiative | Industry Significance |
|---|---|
| Shared Training Academy Investment | Spreads SIRA-mandated Emiratisation compliance costs across consortium partners in Dubai. |
| Command Center Software Integration | Virtualizes guard tour management and consolidates visibility across Riyadh government complexes. |
| Event Security Specialization Buildout | Captures Vision 2030 entertainment calendar procurement with crowd management capabilities. |
| Performance-Based Contract Transition | Aligns pricing with response-time guarantees rather than input-based staffing levels. |
| Regulatory Compliance Advisory Services | Creates recurring revenue streams around licensing and accreditation support frameworks. |
Research Methodology
Operator-level perspectives from security operations directors, SIRA licensing officers, government procurement managers, and facilities management executives anchored the qualitative base. Primary fieldwork combined with secondary validation through Private Security Departments Directorate regulatory filings, UAE Security Industry Regulatory Agency training curricula, Gulf Cooperation Council labor mobility agreements, and oil and gas operator tender documentation. Bottom-up contract enumeration and top-down sectoral allocation triangulated market sizing across service type, industry vertical, and operational model dimensions.
Scenario-bracketing framed analytical approach across the projection horizon, modeling sensitivity to localization mandate acceleration and technology substitution pace. Segmentation dimensions included service delivery mode, client risk profile, weapon authorization tier, and performance metric structure. CAGRs derived from trend extrapolation against workforce supply constraints and megaproject procurement pipeline visibility. Forecast inputs incorporated Emiratisation quota trajectories and smart city integration spending patterns.
The forecast holds incumbent behavior within observed patterns; aggressive consolidation moves by integrated facilities management conglomerates would shift outcomes beyond modeled ranges. Cross-checking against Saudi Arabia's Private Security Departments Directorate licensing issuance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Bot Security Market
Security and Surveillance
Europe Cargo and Vehicle Screening Market
Security and Surveillance
X-Ray Security Screening System Market
Security and Surveillance
Global Security Policy Management Market
Security and Surveillance
APAC Security Testing Market
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
Sirens Market
Security and Surveillance
India CCTV Market
Security and Surveillance
Global Security As a Service Market
Security and Surveillance
Multi-Layer Security Market
Security and Surveillance
Security Services Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Europe People Screening Market
Security and Surveillance
Security Product Integration Services Market
Security and Surveillance
Europe Baggage and Parcel Screening Market
Security and Surveillance
Home Security Solution Market