
 North America Wireless Monitoring and Surveillance Market | 2026-2036
North America Wireless Monitoring and Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wireless Monitoring and Surveillance Market Insights
Systems integrator channels are reshaping how wireless surveillance hardware reaches municipal and enterprise buyers across North America. Honeywell International Inc. leverages its building automation footprint to bundle wireless monitoring into integrated security contracts. Motorola Solutions (Avigilon) anchors its position through command-center software that ties field sensors to real-time crime analytics. Axis Communications AB specializes in open-architecture camera platforms that interoperate across third-party wireless networks.
Wireless monitoring and surveillance encompasses distributed sensor networks, video endpoints, and cloud-native platforms that transmit telemetry and audiovisual data without fixed cabling, typically operating across unlicensed ISM bands or licensed public-safety spectrum at sub-6 GHz frequencies. These systems serve perimeter protection, asset tracking, and situational awareness missions for facilities operators and public agencies. Cameras and software currently command the largest revenue pools, while RFID and Zigbee deployments in industrial settings represent the fastest-expanding technology tier. Cloud-based installation models are displacing traditional professional deployment in mid-market commercial accounts, compressing upfront capital requirements while extending recurring revenue streams.
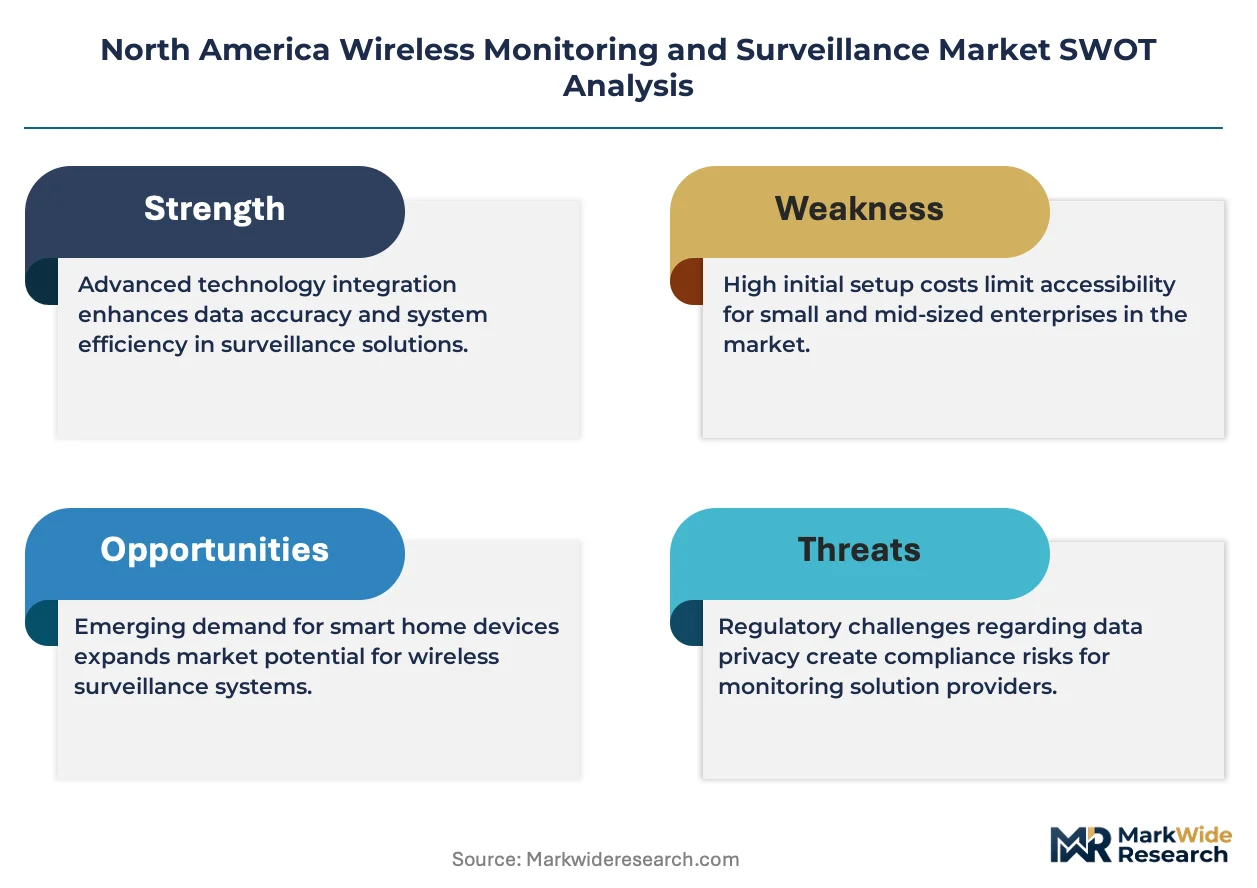
FCC Part 90 rules governing public-safety spectrum access, NIST cybersecurity frameworks for IoT devices, and evolving state-level biometric privacy statutes in Illinois and Texas collectively dictate product certification burdens and procurement eligibility across the United States. Canadian regulators under ISED enforce similar equipment authorization standards that vendors must parallel-certify to serve cross-border customers. Stakeholders must weigh spectrum auction outcomes against municipal procurement cycles to align R&D roadmaps with buyer budget windows.
Market Dynamics
FCC spectrum reallocations for public safety bands are compressing deployment timelines for municipal wireless surveillance networks while private LTE infrastructure investments by critical infrastructure operators create parallel demand channels for integrated monitoring systems.
Growth Catalysts
- Border security infrastructure mandates:Federal procurement programs across southwestern U.S. states are accelerating fixed wireless sensor deployments for perimeter detection applications.
- FCC Part 90 rule modernizations:Expanded licensed spectrum access for public safety agencies enables higher-fidelity video transmission without interference from commercial traffic.
- Cloud-native platform architectures:Software-defined surveillance systems reduce on-premise hardware requirements for mid-market commercial buyers.
Market Restraints
- Semiconductor supply concentration:RF component fabrication relies heavily on concentrated Asian foundry capacity, creating lead time volatility for sub-6 GHz transceiver modules.
- Illinois Biometric Information Privacy Act:Stringent consent requirements for facial recognition analytics create compliance friction for video analytics vendors serving multi-state accounts.
- Lithium-ion battery cost exposure:Wireless camera and sensor endpoints face input cost pressure from cathode material price swings.
Strategic Opportunities
- Canadian metropolitan corridor expansion:Toronto and Vancouver integrated transit-security programs represent underpenetrated demand for mobile video streaming infrastructure.
- Private LTE-5G convergence:Critical infrastructure operators in energy and transportation verticals seek unified platforms combining licensed spectrum reliability with unlicensed band flexibility.
- Outcome-based service contracting:Municipal buyers in Texas and Arizona are piloting subscription models that bundle hardware, connectivity, and analytics into per-camera monthly fees.
Industry Challenges
- Cybersecurity certification bottlenecks:NIST IoT device frameworks require extensive third-party testing, extending product launch timelines for firmware-heavy endpoints.
- Legacy analog integration complexity:Hybrid environments force vendors to maintain backward compatibility with coaxial infrastructure while delivering cloud-native feature sets.
- RF engineering talent scarcity:Specialized expertise in sub-6 GHz antenna design and spectrum optimization commands premium compensation, constraining R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wireless Monitoring and Surveillance Market |
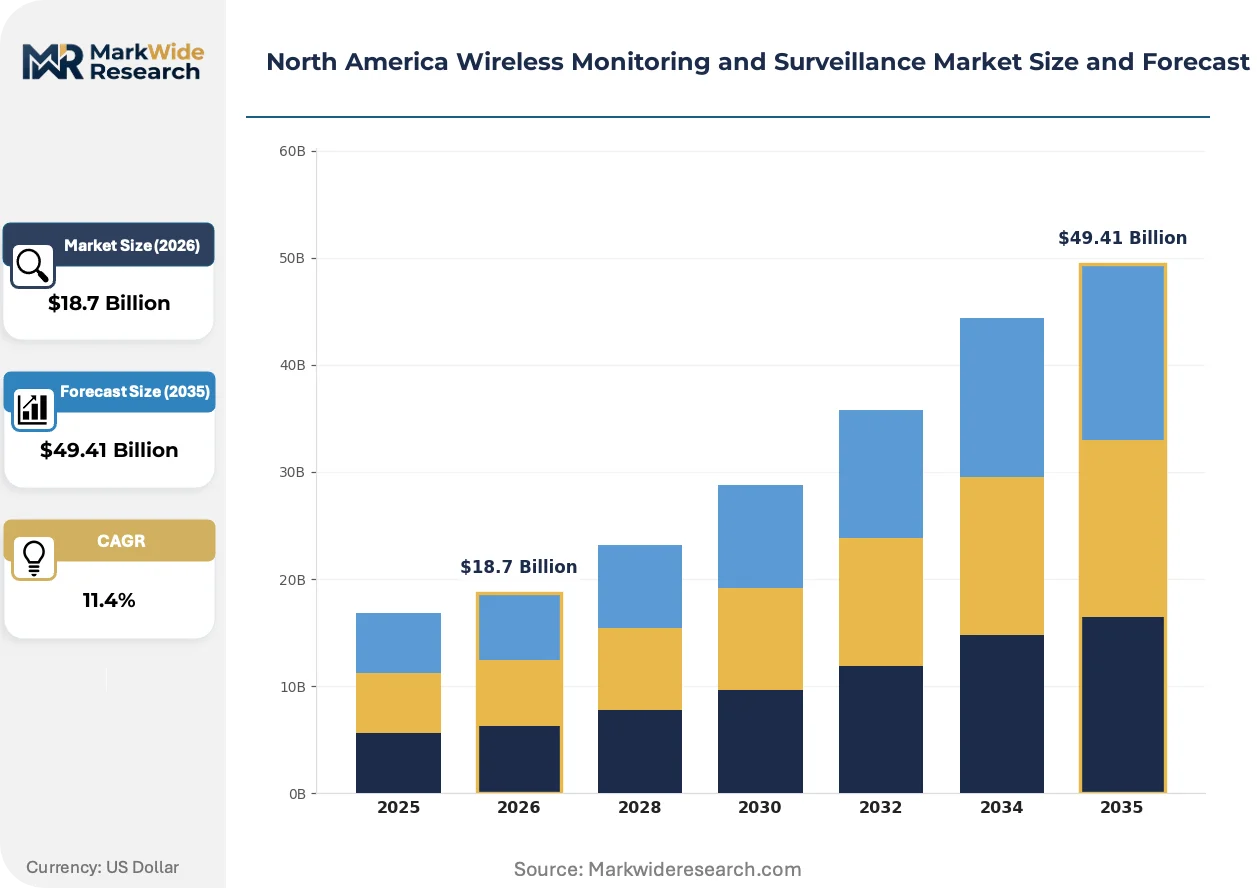
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Sensors, Alarms, Software Technology: Wi-Fi, Bluetooth, Zigbee, RFID End User: Residential, Commercial, Industrial, Healthcare Installation: DIY, Professional, Hybrid, Cloud-Based |
| Companies Covered | Genetec Inc., Hanwha Vision, Honeywell International Inc., FLIR Systems, Inc., Bosch Security Systems, Motorola Solutions (Avigilon), Johnson Controls International plc, Panasonic i-PRO, Axis Communications AB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wireless Monitoring and Surveillance Market Trends and Innovations
Edge computing architectures are redistributing processing loads across wireless surveillance networks, enabling real-time analytics without persistent backhaul dependency while compressing bandwidth costs for high-resolution video streams.
AI-accelerated video analytics is migrating from centralized cloud servers to on-camera inference engines, reducing latency for object detection and behavioral classification. Law enforcement agencies in California and Florida are deploying these endpoints for real-time alerting. The shift is compressing demand for high-capacity backhaul infrastructure while elevating silicon content per camera unit.
ISED equipment authorization harmonization with FCC Part 15 and Part 90 standards is streamlining cross-border certification for vendors serving U.S.-Canada integrated security programs. Canadian municipal buyers gain access to U.S.-tested product portfolios without parallel approval cycles. Border-state procurement contracts now explicitly require dual-jurisdiction compliance documentation.
Municipal procurement departments are consolidating vendor relationships through master service agreements that bundle wireless surveillance with adjacent building automation and access control systems. Systems integrators in Chicago and Houston displace direct hardware purchasing for mid-size city accounts. Texas state procurement frameworks now favor multi-technology umbrella contracts over standalone surveillance tenders.
North America Wireless Monitoring and Surveillance Market Segmentation
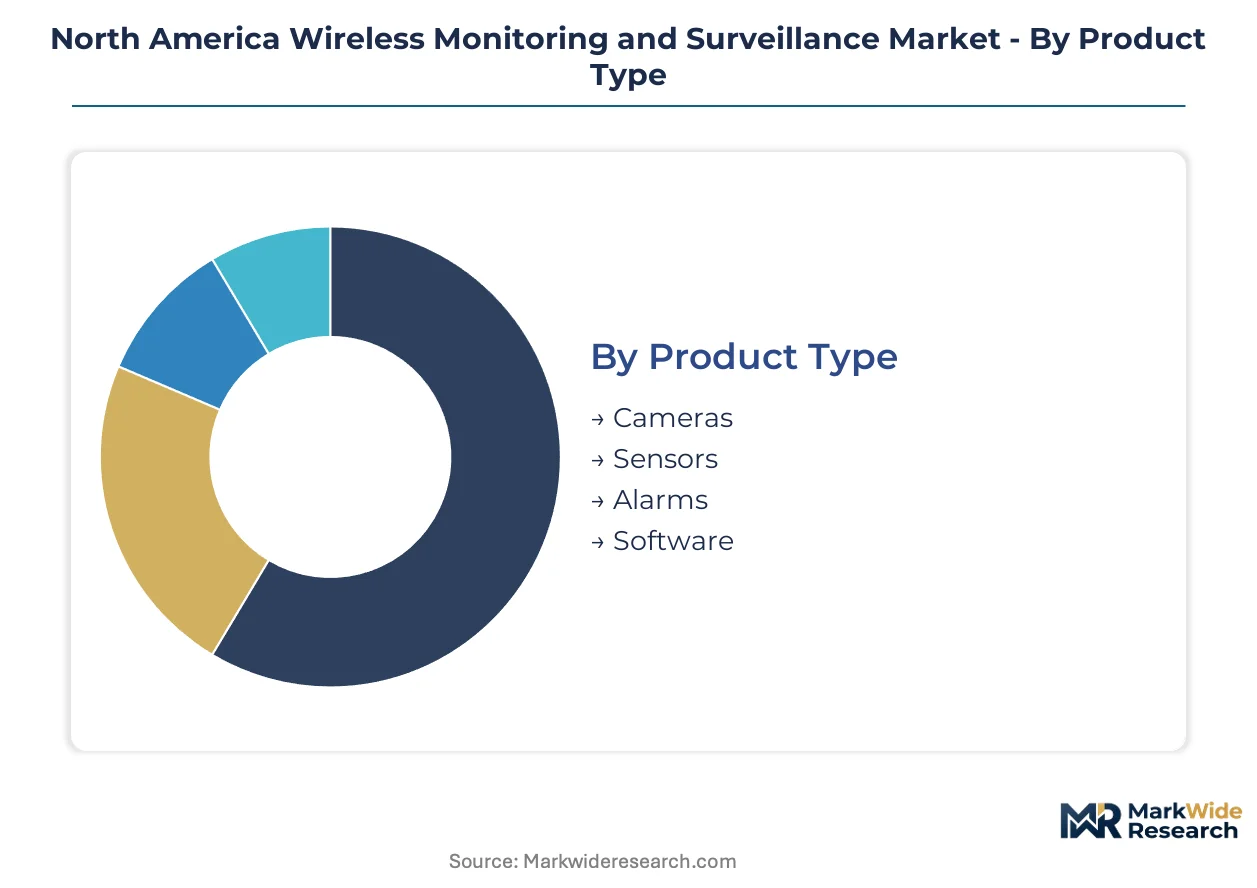
Segmentation in wireless monitoring and surveillance reveals how procurement priorities diverge across buyer sophistication, connectivity requirements, and deployment scale. Understanding these fault lines helps vendors align product roadmaps with the specific constraints of municipal agencies, industrial operators, and residential consumers.
Product Type:
Cost tiers separate hardware-centric offerings from software-defined platforms, with capital intensity and margin profiles varying substantially across the four product categories.
- Cameras:Fixed and pan-tilt-zoom units with integrated IR illumination and edge processing capabilities dominate municipal procurement in Texas and Arizona border corridors. Federal perimeter security programs specify hardened enclosures with sub-6 GHz wireless backhaul for remote desert installations.
- Sensors:Distributed acoustic, seismic, and environmental detectors form the detection layer for critical infrastructure protection. Canadian energy operators in Alberta deploy battery-powered multi-sensor nodes across pipeline rights-of-way where cabled infrastructure proves cost-prohibitive.
- Alarms:Intrusion detection panels with cellular failover connectivity serve residential and small commercial accounts. California and Florida building codes increasingly mandate wireless alarm redundancy for seismic and hurricane resilience.
- Software:Cloud-native video management platforms with AI-accelerated analytics command recurring revenue premiums. Mid-market commercial buyers in Chicago and Toronto are displacing on-premise servers with subscription-based command-center interfaces.
Cameras hold installed capacity. Software is rotating up the share rankings.
Technology:
Application requirements dictate spectrum selection, with range, bandwidth, and power constraints pushing deployments toward specific wireless protocols.
- Wi-Fi:Unlicensed 2.4 GHz and 5 GHz bands support high-definition video streaming in enterprise and campus environments. Dense urban deployments in Vancouver and Montreal face congestion management challenges requiring channel optimization and mesh architectures.
- Bluetooth:Low-energy beacons enable proximity-based asset tracking and personnel authentication in healthcare and industrial settings. Texas hospital networks deploy BLE wristbands for patient flow monitoring and equipment location services.
- Zigbee:Mesh networking at sub-GHz frequencies supports long-range, low-power sensor grids. Industrial facilities in Ohio and Michigan utilize Zigbee for predictive maintenance monitoring across sprawling manufacturing footprints.
- RFID:Passive and active radio-frequency identification tags automate inventory and access control. Arizona logistics hubs integrate UHF RFID with wireless surveillance networks for unified asset visibility.
Wi-Fi maintains deployment volume leadership. Zigbee is climbing the fastest in industrial verticals.
End User:
Customer type determines procurement sophistication, with contract structures and compliance requirements varying sharply across the four end-user categories.
- Residential:Consumer-grade cameras and alarm systems sold through retail and direct-to-consumer channels. California and Texas homeowners drive replacement cycles as legacy analog DVR systems reach end-of-life.
- Commercial:Multi-site retail, hospitality, and office deployments requiring centralized management. Chicago and Houston municipal procurement frameworks favor umbrella contracts bundling surveillance with access control and building automation.
- Industrial:Harsh-environment monitoring for energy, transportation, and manufacturing infrastructure. Canadian oil sands operators in Alberta specify explosion-proof wireless cameras with private LTE backhaul for remote facility monitoring.
- Healthcare:Patient safety, wander prevention, and pharmaceutical cold chain monitoring. Illinois and Texas biometric privacy statutes create compliance friction for facial recognition deployments in hospital environments.
Commercial accounts generate contract volume. Industrial is gaining share fastest as critical infrastructure operators modernize.
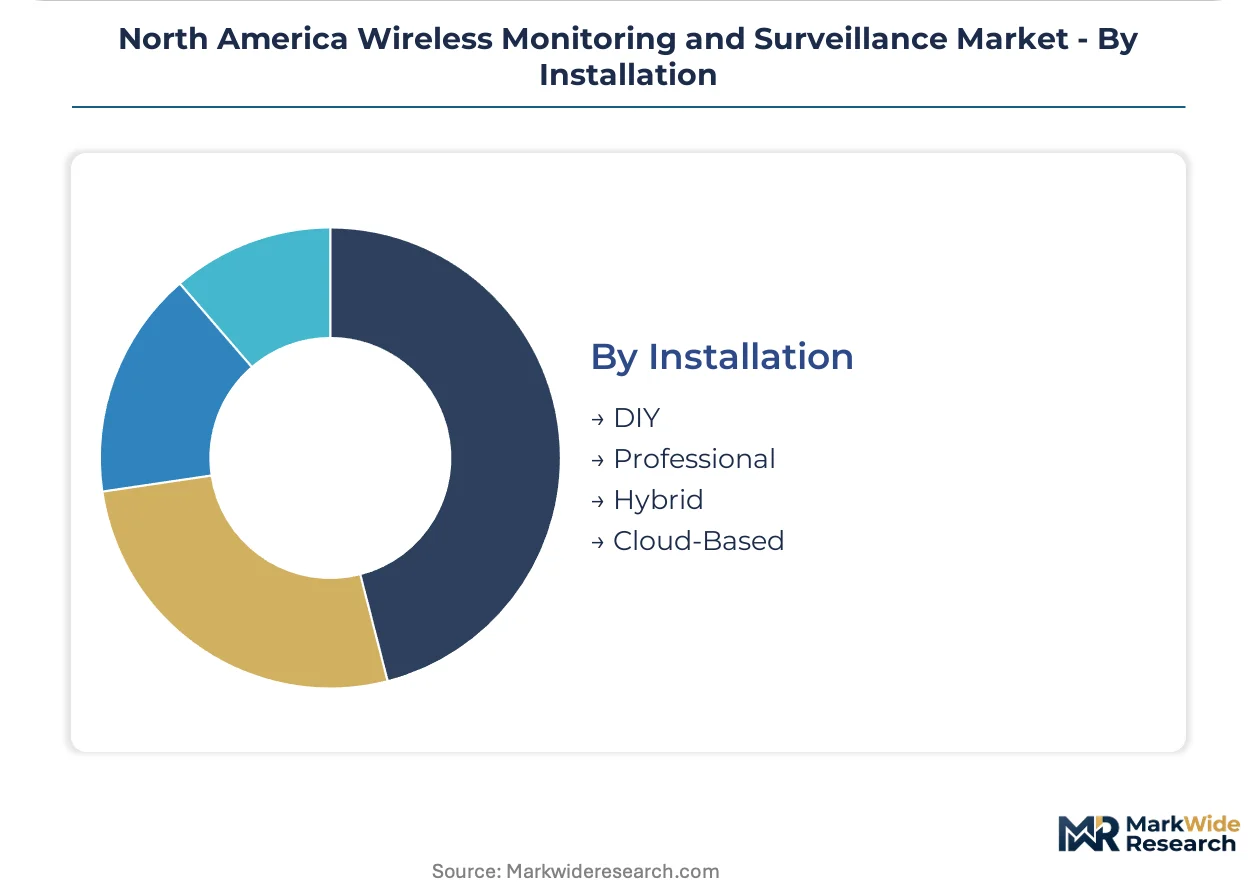
Installation:
Deployment model selection reflects buyer technical capacity, with cloud-native architectures compressing upfront capital requirements for mid-market accounts.
- DIY:Self-installed consumer systems with smartphone-guided configuration. Retail channels in California and Florida emphasize wireless simplicity to reduce product return rates.
- Professional:Dealer-installed systems with customized sensor placement and network optimization. Southwestern U.S. border security programs require certified integrators for federal compliance documentation.
- Hybrid:On-premise recording with cloud backup and remote management capabilities. Toronto and Vancouver transit authorities deploy hybrid architectures balancing local latency requirements with centralized command visibility.
- Cloud-Based:Fully managed platforms with zero on-site server infrastructure. Arizona and Texas municipal pilots are testing subscription models bundling hardware, connectivity, and analytics into per-camera monthly fees.
Professional installation holds project value concentration. Cloud-Based is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S.-Mexico border corridor's 1,954-mile infrastructure underwrites North American demand for wireless perimeter detection systems. Canadian transcontinental rail networks and Great Lakes shipping lanes create parallel monitoring requirements across the northern tier.
United States
Southwestern border states drive federal procurement of hardened wireless cameras with sub-6 GHz backhaul for desert installations. FCC Part 90 rule modernizations expand licensed spectrum access for public safety agencies transmitting high-fidelity video. Texas and Arizona municipal pilots test subscription models bundling hardware, connectivity, and analytics into per-camera monthly fees.
Canada
Toronto and Vancouver integrated transit-security programs generate underpenetrated demand for mobile video streaming infrastructure. ISED equipment authorization harmonization with FCC standards streamlines cross-border certification for vendors serving U.S.-Canada integrated security programs. Alberta oil sands operators specify explosion-proof wireless cameras with private LTE backhaul for remote facility monitoring.
Mexico
Northern border states concentrate maquiladora industrial parks requiring perimeter protection for high-value manufacturing assets. Mexican telecommunications regulators enforce equipment authorization standards that parallel FCC frameworks for cross-border spectrum coordination. Tijuana and Ciudad Juárez logistics hubs integrate UHF RFID with wireless surveillance networks for unified asset visibility.
North America Wireless Monitoring and Surveillance Market Competitive Landscape
On the supply side, the industry is consolidating around systems integrators that bundle wireless surveillance hardware with adjacent building automation and access control contracts. Three strategic archetypes dominate: diversified industrial conglomerates leveraging building automation footprints, specialized video infrastructure vendors anchoring positions through command-center software, and open-architecture camera platform specialists. M&A activity concentrates on video analytics capabilities, while strategic partnerships focus on private LTE-5G network integration.
Among diversified technology conglomerates, Honeywell International Inc. and Johnson Controls International plc occupy positions that exemplify the building-automation-anchored archetype. Motorola Solutions (Avigilon) represents the command-center software tier. Axis Communications AB sits within the open-architecture specialist category. These three companies illustrate how vendor positioning diverges across integration depth, software centrality, and hardware interoperability strategies.
| Leading Market Players |
|---|
| Genetec Inc. |
| Hanwha Vision |
| Honeywell International Inc. |
| FLIR Systems, Inc. |
| Bosch Security Systems |
| Motorola Solutions (Avigilon) |
| Johnson Controls International plc |
| Panasonic i-PRO |
| Axis Communications AB |
| Others |
Pricing and Supply Chain Analysis
Taiwanese foundry capacity for RF transceiver modules determines downstream pricing leverage for wireless surveillance vendors serving North American public safety agencies. Cost compression in edge-processing camera tiers intensifies as lithium-ion cathode material price swings transmit through battery-dependent sensor endpoints.
Pricing Analysis
Volume-discount tiering separates municipal master service agreements from transactional commercial accounts. Three-tier pricing structure across premium, standard, and economy levels differentiates hardened border-security cameras from retail DIY units. Certification under FCC Part 90 and NIST cybersecurity frameworks commands measurable premiums. Cloud-native subscription models are displacing perpetual licenses, compressing upfront capital requirements while extending recurring revenue streams. Mid-market commercial buyers in Chicago and Toronto exhibit highest price sensitivity; federal perimeter security programs demonstrate lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for wireless surveillance hardware vendors. RF component fabrication draws from Taiwan, South Korea, and mainland China foundry capacity. Sub-6 GHz transceiver modules, edge AI accelerators, and lithium-ion battery cells constitute critical input dependencies. Single-source vulnerability in advanced semiconductor lithography constrains R&D scaling for on-camera inference engines. Distribution runs through systems integrator channels that bundle hardware with building automation and access control contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-architecture platform economics are reshaping competitive positioning as ISED-FCC harmonization enables cross-border product portability without parallel certification cycles.
For Market Incumbents: Build switching-cost moats through command-center software that ties field sensors to real-time crime analytics. Deepen backward integration into edge AI silicon to secure supply of inference-accelerated camera modules. Defend against cloud-native entrants by bundling wireless surveillance with Honeywell-style building automation footprints. Invest in NIST cybersecurity certification ahead of procurement eligibility tightening. For New Entrants and Emerging Players: Canadian metropolitan corridor expansion represents underpenetrated white space for mobile video streaming infrastructure. Target Alberta oil sands operators with explosion-proof wireless cameras featuring private LTE backhaul. Pilot outcome-based service contracting with Arizona and Texas municipal buyers testing per-camera monthly fee structures. Lead with subscription models that compress upfront capital barriers for mid-market commercial accounts. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because cloud-native platform architectures are displacing on-premise servers across municipal and enterprise accounts. Acquisition targets should command video analytics capabilities that migrate processing from centralized servers to on-camera inference engines. Watch private LTE-5G convergence pilots in energy and transportation verticals as inflection signal for unified platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Open-architecture camera platforms interoperate across third-party wireless networks per Axis Communications model. |
| Private LTE-5G Convergence | Critical infrastructure operators seek unified platforms combining licensed spectrum reliability with unlicensed flexibility. |
| Geographic Expansion | ISED-FCC harmonization streamlines cross-border certification for Toronto and Vancouver transit-security programs. |
| Acquisition of Specialist Firm | Video analytics capabilities compress latency for object detection in California and Florida law enforcement deployments. |
| Strategic Partnership | Systems integrators in Chicago and Houston displace direct hardware purchasing through multi-technology umbrella contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal procurement officers, systems integrator channel managers, RF engineering specialists, and critical infrastructure security directors. Secondary validation drew from FCC equipment authorization databases, ISED certification records, SEC 10-K filings of diversified technology conglomerates, and municipal procurement contract disclosures. Bottom-up triangulation across product-type shipment estimates and top-down reconciliation against end-user budget cycles anchored volume and value outputs.
Calibration against historical spectrum auction outcomes and municipal budget appropriation cycles refined the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, wireless technology protocol, end-user vertical, and installation deployment model. CAGRs were derived from slope analysis of technology adoption curves and procurement cycle timing. Forecast inputs incorporated private LTE infrastructure investment disclosures and border security infrastructure mandate appropriation trajectories.
Macroeconomic conditions sit as an overlay; deviation in municipal tax revenue cycles and lithium-ion commodity price indices would shift the trajectory. Forecasts reflect assumptions regarding ISED-FCC regulatory harmonization persistence and semiconductor foundry capacity expansion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
Europe Cargo and Vehicle Screening Market
Security and Surveillance
Speed Limit Radar Signs Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Electronic Alarms Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Global Firearm Sight Market
Security and Surveillance
Burglar Alarm Systems Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
Security Services Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
Seaport Security Management Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
Private Security Market
Security and Surveillance
Home Security Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market