
 Alarm Monitoring Software Market | 2026-2036
Alarm Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Alarm Monitoring Software Market Analysis
Buyer concentration among large security service providers is pivoting toward fragmented demand from mid-sized facility management firms and multi-site retail operators. Honeywell International Inc. leverages its building automation ecosystem to bundle alarm monitoring with HVAC and access control platforms. Johnson Controls International Plc anchors its position through deep integration with fire suppression and life safety systems. Bosch Security Systems differentiates via edge-computing video verification modules that reduce false dispatch rates.
Alarm monitoring software comprises centralized platforms that ingest signals from intrusion sensors, fire panels, environmental detectors, and video analytics engines, processing events through rules-based escalation protocols to dispatch operators or emergency responders. Cloud-based solutions are capturing the fastest expansion as central stations abandon on-premises server farms for elastic compute capacity and geographic redundancy. Retail and banking verticals represent mature, high-volume segments where margin pools now depend on add-on cyber-physical threat correlation services rather than basic signal relay.
FDA patient-safety guidelines and HIPAA breach-notification rules shape healthcare facility alarm monitoring requirements in the United States, while the EU AI Act and GDPR constrain automated video analytics deployments across European installations. Stakeholders must weigh regulatory latency against cloud migration timelines when selecting deployment architectures that satisfy data sovereignty obligations without fragmenting operational visibility.
Market Dynamics
Cloud migration is compressing capital requirements for central station operators while fragmenting procurement authority toward facility-level IT managers who prioritize API interoperability over bundled hardware contracts.
Growth Catalysts
- FDA patient-safety mandates:US healthcare facilities must deploy integrated alarm monitoring for clinical deterioration detection, creating mandatory upgrade cycles across hospital networks.
- Edge-computing video verification:On-device analytics reduce false dispatch rates below 2%, cutting operator labor costs and insurance premiums for commercial security deployments.
- Germany's critical infrastructure protection framework:Federal requirements for redundant signaling paths accelerate replacement of analog PSTN-dependent systems with IP-based monitoring platforms.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries produce 90% of advanced video encoding chips, exposing hardware vendors to geopolitical disruption risks.
- GDPR data localization friction:EU cloud deployments require sovereign infrastructure that fragments operational visibility for multinational security providers.
- Cellular backup cost volatility:5G module pricing swings of 15-20% annually compress margins on monitored intrusion systems sold through retail channels.
Strategic Opportunities
- India's smart city infrastructure:Municipal command centers in Mumbai, Delhi, and Bangalore seek unified platforms combining fire, intrusion, and environmental monitoring.
- Cyber-physical threat correlation:Convergence of IT security operations centers with physical alarm monitoring creates premium service tiers for financial institutions.
- Japan's aging care facility mandate:METI guidelines require wander-prevention and fall-detection integration in nursing homes by 2027.
Industry Challenges
- Cloud-to-legacy integration complexity:Hybrid deployments demand specialized engineering talent scarce outside major metropolitan technology clusters.
- UL 827 central station certification timelines:12-18 month approval cycles delay go-to-market for software updates incorporating AI-based dispatch prioritization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alarm Monitoring Software Market |
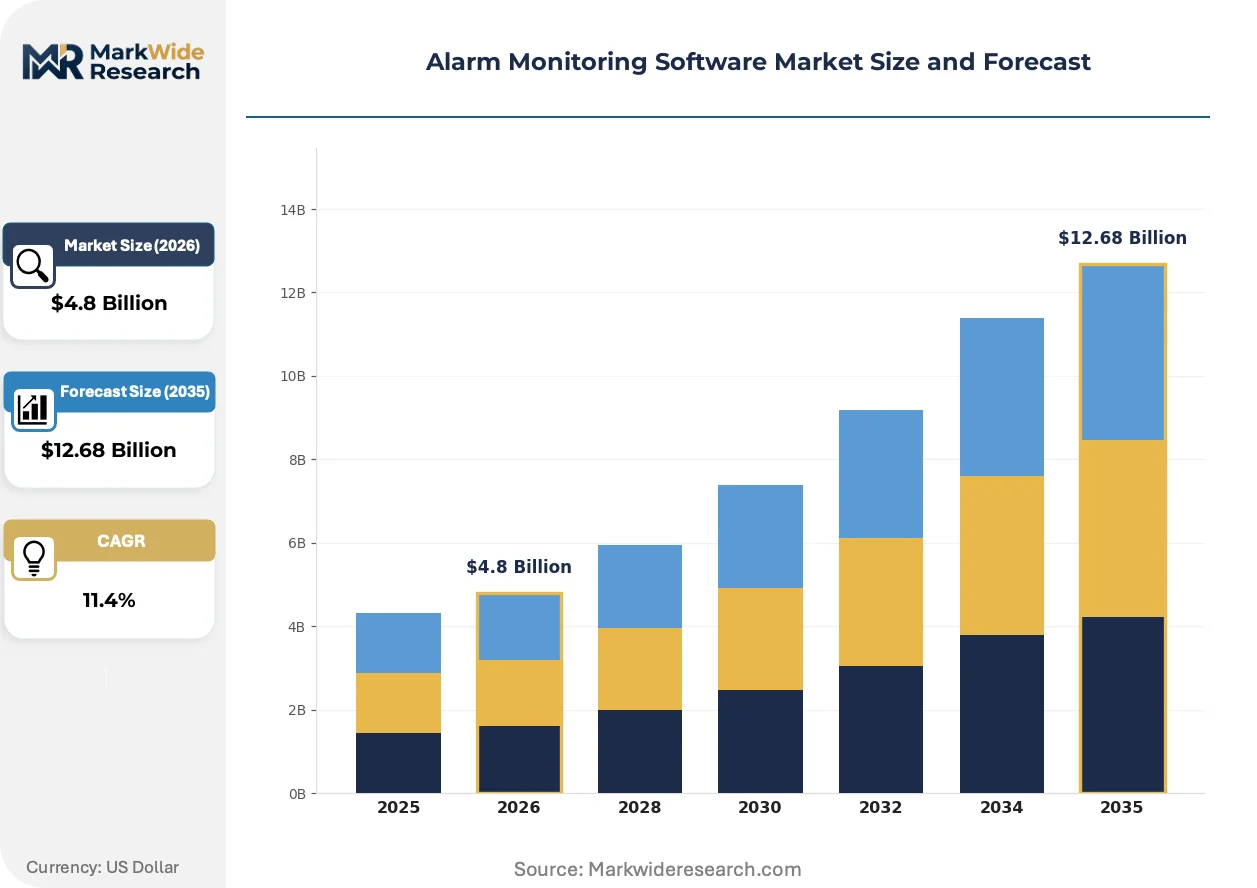
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-Based, On-Premises, Hybrid, Managed Services Industry Vertical: Retail, Healthcare, Banking, Education Deployment Model: Private Cloud, Public Cloud, Multi-Tenant, Dedicated Server User Type: Homeowners, Security Companies, Facility Managers, Emergency Services |
| Companies Covered | Honeywell International Inc., Johnson Controls International Plc, ADT Inc., Tyco International, Schneider Electric SE, Siemens AG, ABB Ltd., Rockwell Automation Inc., Bosch Security Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alarm Monitoring Software Market Emerging Trajectories
Software-defined signal processing is displacing purpose-built hardware at the network edge, while regulatory pressure on data sovereignty forces architectural decisions that trade operational efficiency against compliance coverage.
Multi-protocol signal aggregation platforms is unifying inputs from proprietary intrusion panels, open-standard fire systems, and ONVIF-compliant video analytics into normalized event streams. Mid-sized central stations in Texas, Ontario, and Bavaria are adopting these platforms fastest, typically replacing three separate monitoring workstations with browser-based dashboards. This consolidation is unifying previously siloed operator pools and compressing per-seat training costs by 40%.
The EU AI Act's risk classification framework for automated decision-making systems imposes documentation and human-in-the-loop requirements on video analytics that trigger emergency dispatch. European security providers must now maintain algorithmic audit trails and designate qualified persons for override authority. German and French installations face the steepest compliance costs, with some operators retreating to rule-based event correlation to avoid high-risk system classification.
Facility management firms are unbundling alarm monitoring from long-term hardware leases, instead procuring software subscriptions directly and sourcing sensors through separate IT procurement channels. This disintermediation pressures traditional integrators who historically captured margin through bundled equipment financing. The pattern is most pronounced among US multi-site retail operators with centralized security operations centers in Dallas, Chicago, and Atlanta.
Alarm Monitoring Software Market Segmentation
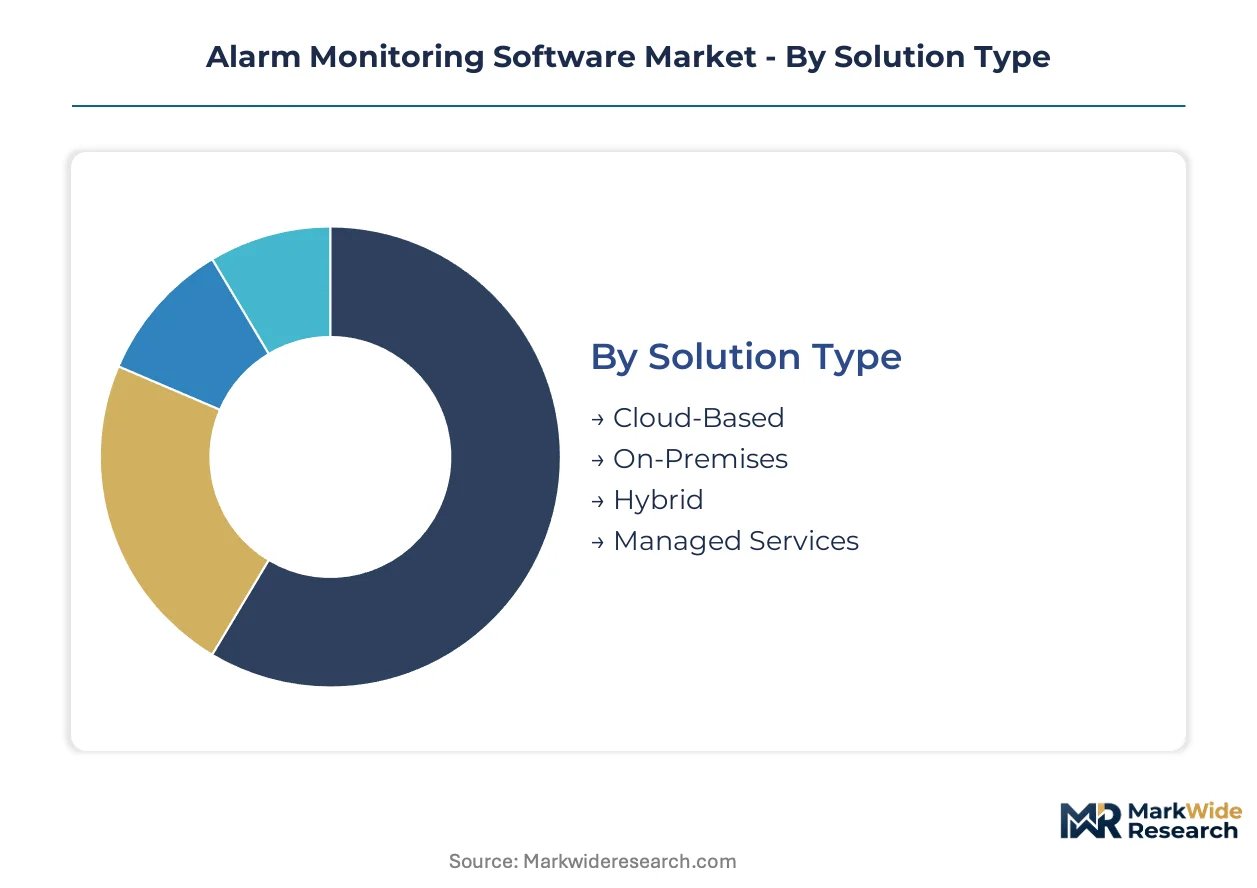
Alarm monitoring software procurement splits across technical architecture, operational context, and buyer sophistication. Each segmentation axis reveals distinct margin structures and vendor competitive requirements.
Solution Type:
Supply concentration in hyperscaler infrastructure is compressing deployment economics for cloud-native platforms while fragmenting on-premises hardware vendor pools.
- Cloud-Based:Elastic compute architectures eliminate capital expenditure for central station operators. Demand concentrates among mid-sized security providers in Texas and Ontario replacing legacy server farms with AWS or Azure instances to achieve geographic redundancy.
- On-Premises:Dedicated server installations persist in German critical infrastructure and US federal facilities where data sovereignty mandates prohibit third-party cloud access. High upfront licensing and 5-year refresh cycles define procurement patterns.
- Hybrid:Split architectures route sensitive video analytics through local edge nodes while pushing archival storage to cloud tiers. Japanese nursing homes and Indian municipal command centers adopt this pattern to balance latency against compliance.
- Managed Services:Fully outsourced monitoring operations bundle software, staffing, and liability under per-site subscription fees. European facility management firms disaggregate this from long-term hardware leases.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Industry Vertical:
Application-specific regulatory burdens are forcing vertical specialization among software vendors rather than horizontal platform plays.
- Healthcare:FDA patient-safety mandates and HIPAA breach-notification rules require integrated clinical deterioration detection. US hospital networks drive mandatory upgrade cycles with alarm correlation engines that suppress nuisance notifications.
- Banking:Cyber-physical threat correlation services command premium pricing as financial institutions converge IT security operations with physical monitoring. Mature segment where margin pools depend on add-on analytics rather than basic signal relay.
- Retail:Multi-site operators with centralized security operations in Dallas and Chicago unbundle software from hardware procurement. High volume, compressed margins, and demand for API interoperability define this segment.
- Education:Campus-wide emergency mass notification integration drives procurement for K-12 districts and university systems. Budget constraints favor subscription models over capital-intensive on-premises deployments.
Healthcare captures the steepest expansion trajectory. Banking retains the densest margin concentration.
Deployment Model:
Customer type and risk tolerance determine infrastructure tenancy choices more than technical capability differentials.
- Private Cloud:Single-tenant virtualized environments serve German operators navigating GDPR data localization requirements and EU AI Act algorithmic audit obligations.
- Public Cloud:Shared hyperscaler resources deliver lowest unit economics for price-sensitive retail and residential monitoring providers.
- Multi-Tenant:Segregated logical partitions within shared infrastructure balance cost efficiency against client data isolation needs. Popular among mid-sized central stations scaling beyond 50,000 monitored accounts.
- Dedicated Server:Physical hardware assignments satisfy US federal and defense contractor requirements for controlled access and chain-of-custody documentation.
Private Cloud commands compliance premiums. Public Cloud scales fastest among new entrants.
User Type:
Procurement authority fragmentation is shifting software purchasing from bundled security contracts toward direct IT channel relationships.
- Security Companies:Traditional central station operators seek unified dashboards replacing multiple monitoring workstations. Browser-based platforms compress per-seat training costs by 40%.
- Facility Managers:Corporate real estate teams in multi-site retail and logistics operations procure software subscriptions directly, sourcing sensors through separate IT procurement channels.
- Homeowners:Residential DIY installations favor mobile-app-centric monitoring with self-service configuration. Lowest price point, highest churn vulnerability.
- Emergency Services:Municipal and regional dispatch centers demand standardized data feeds from disparate alarm sources to reduce call-handling variance.
Facility Managers represent the fastest-growing procurement authority. Security Companies defend the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Boston, Munich, and Tokyo anchor alarm monitoring software development. These metropolitan centers concentrate firmware architects and regulatory compliance specialists who bridge embedded systems with cloud-native architectures. Cross-border data governance expertise now differentiates regional competitive positioning.
United States
Hospital networks across Texas and Florida drive FDA-mandated clinical alarm integration projects. HIPAA breach-notification rules compel healthcare facilities to upgrade legacy paging systems to encrypted cloud platforms. The Dallas-Fort Worth corridor hosts centralized security operations for multi-site retail operators unbundling software from hardware procurement.
Germany
Federal critical infrastructure protection frameworks require redundant IP-based signaling paths for energy and transport facilities. GDPR data localization obligations and EU AI Act algorithmic audit requirements constrain cloud deployment architectures. Bavarian central stations adopt hybrid edge-cloud configurations to satisfy sovereign data requirements while maintaining operational visibility.
Japan
METI guidelines mandate wander-prevention and fall-detection integration in nursing homes by 2027. Aging care facility operators in Osaka and Nagoya prioritize latency-sensitive edge analytics for resident safety monitoring. Domestic semiconductor vendors supply encoding chips that reduce dependence on Taiwan-based foundries for video verification modules.
India
Municipal command centers in Mumbai, Delhi, and Bangalore seek unified platforms combining fire, intrusion, and environmental monitoring for smart city infrastructure. BIS standards for building automation systems create compliance pathways for imported alarm monitoring technologies. Domestic IT services firms partner with global vendors to localize cloud deployments for data sovereignty requirements.
United Kingdom
Financial institutions in London converge physical security operations with IT security centers for cyber-physical threat correlation services. The Information Commissioner's Office enforces GDPR-aligned accountability for automated video analytics triggering emergency dispatch. Cambridge and Oxford technology clusters supply machine learning talent for false-alarm reduction algorithms.
Alarm Monitoring Software Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Building automation conglomerates leverage cross-selling ecosystems to bundle alarm monitoring with HVAC and access control platforms. Pure-play security software vendors differentiate through API interoperability and vertical-specific compliance modules. Dominant competitive moves include strategic partnerships for edge-computing integration and portfolio diversification into cyber-physical threat correlation services.
Within the building automation tier, Honeywell International Inc. and Johnson Controls International Plc exemplify conglomerate strategies that embed alarm monitoring within broader facility management ecosystems. Bosch Security Systems occupies a specialist position representing edge-computing video verification capabilities that reduce false dispatch rates. These three anchors illustrate divergent paths: bundled ecosystem leverage versus modular software specialization.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Johnson Controls International Plc |
| ADT Inc. |
| Tyco International |
| Schneider Electric SE |
| Siemens AG |
| ABB Ltd. |
| Rockwell Automation Inc. |
| Bosch Security Systems |
| Others |
Supply Flow & Price Mechanics
Firmware architects and regulatory compliance specialists concentrated in Boston, Munich, and Tokyo command wage premiums that compress margins on economy-tier alarm monitoring deployments while widening spreads between premium certified platforms and basic signal-relay services.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the alarm monitoring software landscape. Three-tier pricing structure across premium, standard, and economy levels separates UL 827-certified central station platforms from API-only software licenses and basic residential monitoring subscriptions. Price differentiation rests on certification grade and vertical-specific compliance module depth. Pricing pressure stems from facility managers disaggregating software procurement from long-term hardware leases. Multi-site retail operators in Dallas and Chicago exhibit highest price sensitivity; banking cyber-physical correlation services demonstrate lowest.
Supply Chain Analysis
Workforce availability constraints in Taiwanese semiconductor foundries and German industrial automation clusters limit encoding chip and edge-computing module production. Supply concentrates in Taiwan for advanced video analytics processors, Japan for domestic nursing home sensor integration, and Germany for critical infrastructure edge nodes. Raw material dependencies include 5G cellular modules, ONVIF-compliant camera chipsets, and sovereign cloud infrastructure. Single-source vulnerability from Taiwan-based foundries producing 90% of video encoding chips exposes hardware vendors to geopolitical disruption. Distribution runs through hyperscaler marketplaces and direct IT procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alarm monitoring software market represents a late-cycle quality story as healthcare facility buyers prioritize FDA-compliant clinical alarm correlation over basic intrusion detection, forcing vendors toward premium specification tiers.
For Market Incumbents: Hedge against margin compression from unbundled procurement by deepening integration with building automation ecosystems and acquiring edge-computing verification specialists. Cloud-native entrants threaten traditional central station operators through API-first deployment models. Certification investment in EU AI Act algorithmic audit capabilities protects European revenue streams.
For New Entrants and Emerging Players: Launch via direct software subscriptions to facility management firms bypassing traditional security integrators. India's municipal smart city command centers offer the most penetrable geography for unified fire-intrusion-environmental platforms. Vertical specialization in HIPAA-compliant healthcare alarm correlation commands premium positioning.
For Investors and Strategic Acquirers: Building automation conglomerates are the most active acquirer in this space, seeking API interoperability capabilities to complete bundled ecosystem offerings. Long-term viability favors pure-play software vendors with healthcare vertical depth over hardware-dependent legacy operators. Watch FDA enforcement intensity on clinical alarm integration mandates as inflection indicator for healthcare segment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies intrusion, fire, and video analytics into browser-based dashboards for central station consolidation. |
| Acquisition of Specialist Firm | Captures edge-computing video verification capabilities that reduce false dispatch rates below 2%. |
| Geographic Expansion | Establishes sovereign cloud infrastructure in Germany to satisfy GDPR data localization requirements. |
| Strategic Partnership | Links alarm monitoring platforms with IT security operations centers for cyber-physical threat correlation. |
| Product Launch | Introduces wander-prevention and fall-detection modules for Japan's 2027 nursing home mandate compliance. |
Methodological Framework
Multiple input streams — central station operator interviews, facility manager procurement surveys, regulatory filing analysis, and hyperscaler deployment disclosures — were reconciled to construct market estimates. Primary conversations with central station technical directors, healthcare biomedical engineers, retail security operations managers, and municipal smart city planners informed demand-side validation. Secondary sources included FDA 510(k) submissions for clinical alarm systems, EU AI Act implementation guidance, BIS building automation standards, and SEC filings from building automation conglomerates. Bottom-up account-level aggregation and top-down vertical market sizing were cross-checked for consistency.
Data-stream reconciliation across deployment model, organization size, vertical application, integration complexity, and regional adoption pattern enabled segmentation-level forecasting. Growth trajectories were derived from installed base migration rates, mandatory upgrade cycle timing, and elasticity estimates against pricing tier spreads. Cloud migration velocity in Texas and Ontario, EU AI Act compliance cost assumptions, and Japan METI guideline enforcement intensity anchored the analytical framework across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or accelerated PSTN sunset timelines. Projections reflect assumptions regarding regulatory latency, cloud sovereignty negotiation outcomes, and central station consolidation pace. Material deviation in FDA enforcement intensity or Taiwan foundry capacity utilization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Commercial Security Market
Security and Surveillance
Europe Urban Security Screening Market
Security and Surveillance
Security Services Market
Security and Surveillance
Global Security Policy Management Market
Security and Surveillance
Asia-Pacific Security Screening Market
Security and Surveillance
Global Adaptive Security Market
Security and Surveillance
Global Cargo Inspection Market
Security and Surveillance
Global Traveler Security Services Market
Security and Surveillance
Europe Rockfall Radar Market
Security and Surveillance
Face Smart Lockers Market
Security and Surveillance
Global Wireless Doorbells Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Smart Home Security Market
Security and Surveillance
Electronic Alarms Market
Security and Surveillance
Full Body Scanner Market
Security and Surveillance
Consumer Security Market