
 Europe Security Services Market | 2026-2036
Europe Security Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Security Services Market Insights
The shift from single-source guarding contracts to multi-vendor integrated security ecosystems is decoupling traditional manned services from technology platforms. Securitas AB leverages its scale across Nordic and Continental operations to anchor physical guarding revenue while building remote monitoring capabilities. Orange Cyberdefense competes by converging cyber and physical security under unified service-level agreements for enterprise clients. G4S Ltd sustains market presence through specialized risk consulting that extends beyond commoditized patrol services.
Europe security services encompass the design, deployment, and management of protective systems spanning electronic surveillance, access control, intrusion detection, and manned guarding, typically operating through networked command centers with real-time response protocols. These services protect assets, personnel, and information across commercial, governmental, and critical infrastructure environments where threat profiles span physical breach, cyber intrusion, and operational disruption. Video surveillance and remote monitoring command the largest share of technology-enabled spending, while biometric access control represents the fastest-expanding service category as organizations replace credential-based entry with fingerprint, facial recognition, and iris verification systems. The commercial client segment dominates contract value, though government and critical infrastructure accounts yield superior margins due to compliance complexity and certification requirements.
GDPR, the EU AI Act, and national critical infrastructure directives from Germany's BSI and France's ANSSI shape product standards, data handling protocols, and market access conditions across member states. ECHA chemical restrictions and CE marking requirements further govern the material composition and electromagnetic compatibility of installed security hardware. Stakeholders must monitor how the EU AI Act's risk-classification framework for biometric systems will reshape procurement criteria and vendor qualification standards for public-sector security contracts.
Market Dynamics
Biometric access control systems are displacing credential-based entry across European commercial real estate, forcing security providers to restructure service delivery around integrated cyber-physical platforms rather than standalone manned guarding contracts.
Growth Catalysts
- EU AI Act risk-classification framework:Public-sector procurement criteria now mandate biometric verification standards, accelerating replacement cycles for legacy access systems in government facilities.
- Critical infrastructure operators in France:ANSSI protocols require integrated cyber-physical security, creating bundled demand for unified threat detection and response capabilities.
- Building automation convergence:German and French commercial real estate portfolios are expanding contracted coverage as property management platforms integrate physical security with HVAC and energy systems.
Market Restraints
- GDPR biometric data handling costs:Compliance infrastructure for facial recognition and fingerprint storage adds operational overhead that compresses margins on mid-market security contracts.
- CE marking and ECHA chemical restrictions:Hardware manufacturers face extended certification timelines for electromagnetic compatibility and restricted substance compliance in installed security equipment.
- Specialized cyber-physical skill scarcity:The talent pool for technicians proficient in both network security and physical access systems remains concentrated in Nordic urban centers.
Strategic Opportunities
- Polish and Romanian commercial markets:Underpenetrated mid-size enterprise segments offer first-mover positioning for integrated remote monitoring services ahead of regulatory harmonization.
- EU Green Deal building retrofit mandates:Energy efficiency upgrades in existing commercial stock create natural insertion points for modernized access control and surveillance infrastructure.
- AI-powered video analytics convergence:Edge computing deployment in surveillance cameras enables real-time threat classification without centralized processing latency.
Industry Challenges
- BSI and ANSSI certification timelines:Critical infrastructure security clearances require 12-18 month validation cycles that delay contract mobilization and strain working capital.
- Legacy access control integration friction:Credential-based systems in existing building stock resist seamless connectivity with cloud-managed biometric platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Security Services Market |
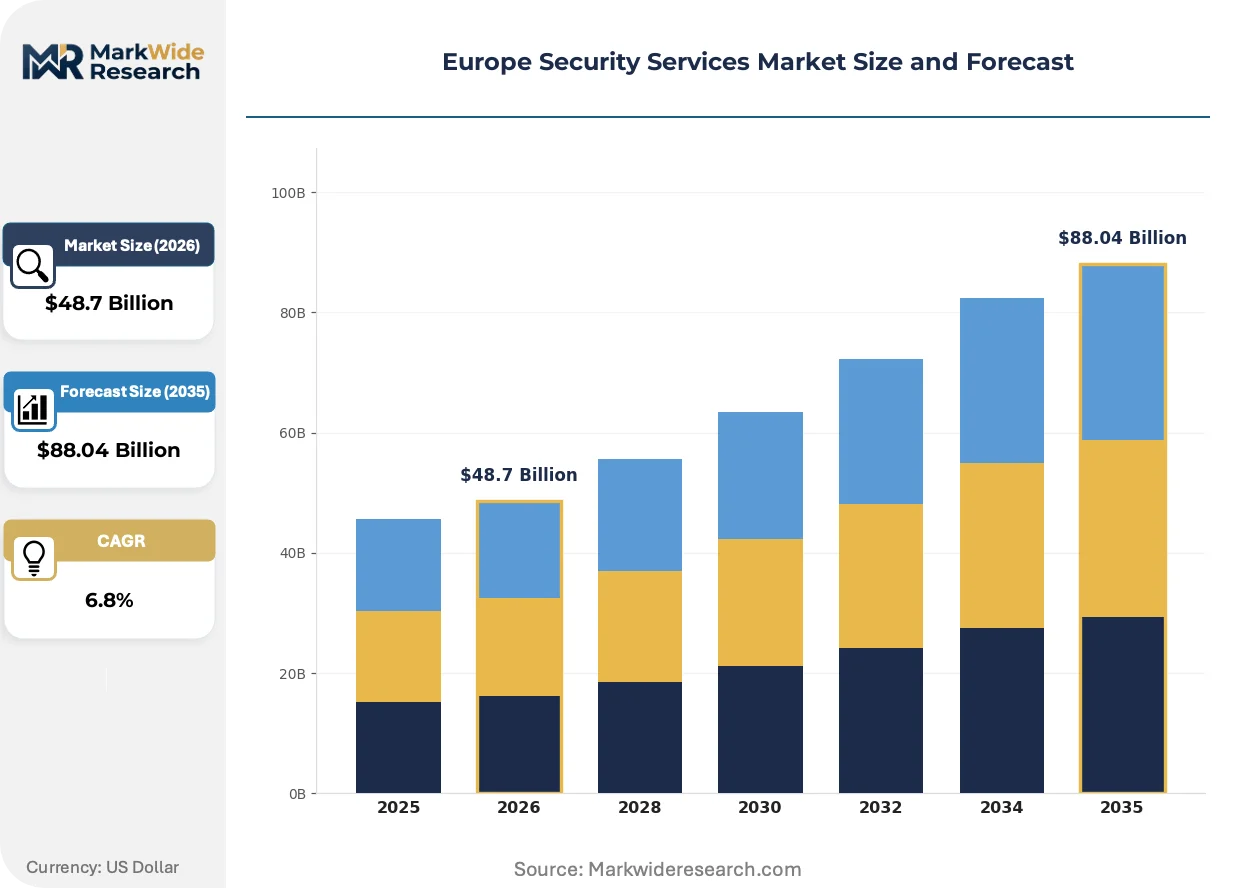
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Access Control, Video Surveillance, Alarm Systems, Intrusion Detection Client Type: Government, Residential, Commercial, Industrial Technology: Biometrics, IoT Security, Cybersecurity Solutions, Remote Monitoring End User: Healthcare Facilities, Educational Institutions, Banks, Retail Stores |
| Companies Covered | Deutsche Telekom AG, Orange Cyberdefense, Securitas AB, BT Group plc, Accenture PLC, G4S Ltd, Atos SE, Prosegur Compañía de Seguridad, ASSA ABLOY AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Security Services Market Trends and Innovations
Artificial intelligence is compressing the boundary between detection and response in European security operations, shifting value capture from labor hours to algorithmic accuracy and platform uptime guarantees.
Computer vision systems with embedded edge processors are automating real-time threat classification in video surveillance networks. Logistics operators and retail chains across Germany and the Netherlands are deploying these systems at scale, replacing centralized monitoring stations with distributed intelligence that flags anomalies without human review. This architecture is automating the tier-one response layer that previously consumed the majority of manned guarding labor budgets.
France's CNIL has tightened biometric data retention limits under GDPR-aligned national enforcement, requiring security providers to implement automated deletion protocols for facial recognition templates. Industrial consequence includes mandatory privacy-by-design architecture in new access control deployments. Critical infrastructure operators in energy and transportation are responding by procuring systems with on-device processing that never transmits raw biometric data to external servers.
Enterprise buyers are consolidating vendor relationships around unified service-level agreements that bundle cyber and physical security under single accountability structures. This displaces the traditional model of separate contracts for guarding, electronic surveillance, and IT security. French banking and insurance headquarters are the most visible adopters, with procurement teams mandating integrated incident response across previously siloed security functions.
Europe Security Services Market Segmentation
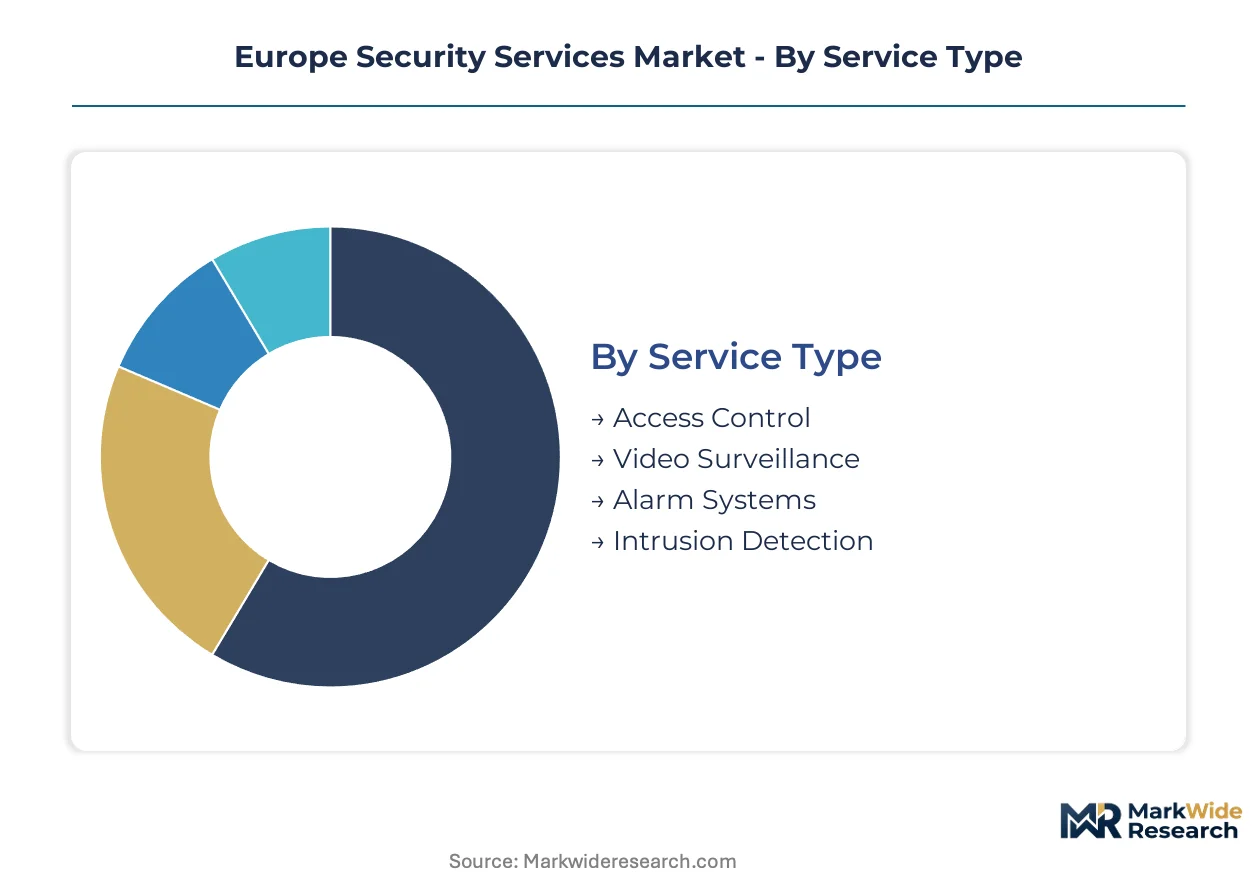
Security service providers across Europe structure their offerings around distinct operational layers that determine contract value, margin profiles, and regulatory exposure. Segment boundaries are blurring as biometric systems and remote monitoring platforms displace standalone manned guarding, reshaping how vendors organize their commercial and technology portfolios.
Service Type:
Replacement cycles for legacy security infrastructure are accelerating across European commercial real estate as building automation platforms demand interoperable digital endpoints rather than siloed analog systems.
- Access Control:Electronic entry management systems span credential readers, biometric scanners, and cloud-managed identity platforms. German banking headquarters and French government facilities are driving demand for fingerprint and facial recognition systems that comply with GDPR data minimization requirements.
- Video Surveillance:Camera networks with edge-based analytics automate threat detection without centralized processing. Logistics operators in the Netherlands and retail chains across Germany deploy these systems to reduce manned guarding hours while maintaining coverage density.
- Alarm Systems:Intrusion alerts integrated with mobile dispatch protocols.
- Intrusion Detection:Perimeter sensors and motion detection for facility protection.
Video surveillance sits at the top of the volume ranking, with access control climbing the fastest as biometric verification displaces card-based entry.
Client Type:
Contract economics diverge sharply across client categories, with compliance complexity and certification timelines creating tiered margin structures that favor specialized providers.
- Government:Public-sector security procurement mandates biometric verification standards under the EU AI Act risk-classification framework. ANSSI and BSI certification requirements extend mobilization timelines to 12-18 months, filtering out vendors lacking critical infrastructure clearances.
- Commercial:Office portfolios and retail chains across Germany and France bundle physical security with building automation platforms. Property management convergence with HVAC and energy systems creates natural insertion points for modernized access control during Green Deal-mandated retrofits.
- Industrial:Manufacturing and energy facilities requiring integrated cyber-physical protocols.
- Residential:Multi-tenant housing and private estate security services.
Commercial contracts dominate absolute volume, with government accounts yielding superior margins due to certification barriers.
Technology:
Technology selection determines whether security providers capture value through labor hours or platform uptime guarantees and algorithmic accuracy metrics.
- Biometrics:Fingerprint, facial recognition, and iris verification systems with on-device processing. France's CNIL has tightened data retention limits, forcing privacy-by-design architecture that processes templates locally without external server transmission.
- Remote Monitoring:Networked command centers with real-time response protocols replacing physical patrol presence. Polish and Romanian commercial markets show underpenetrated demand for these services ahead of regulatory harmonization.
- IoT Security:Sensor networks and connected device protection for smart buildings.
- Cybersecurity Solutions:Network security layered with physical access management.
Biometric systems command premium pricing tiers, while remote monitoring platforms are gaining share fastest among mid-market enterprise segments.
End User:
End-use environments impose distinct threat profiles and compliance obligations that shape procurement criteria and vendor qualification standards.
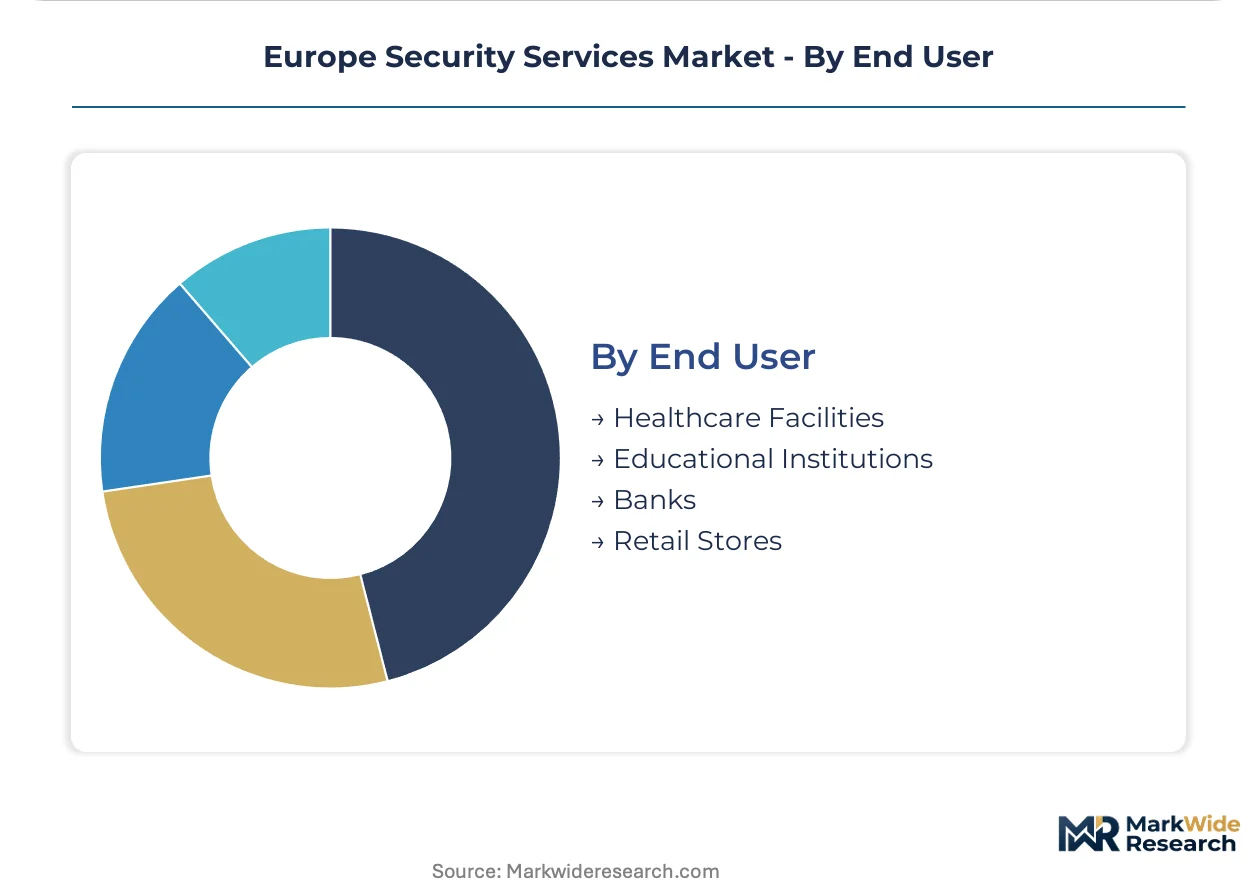
- Banks:Financial headquarters in France and Germany consolidate vendor relationships under unified service-level agreements bundling cyber and physical security. Procurement teams mandate integrated incident response across previously siloed guarding, surveillance, and IT security functions.
- Healthcare Facilities:Hospital networks and clinic chains requiring patient data protection alongside physical access control. GDPR biometric handling costs add operational overhead that compresses margins on mid-market contracts in this segment.
- Educational Institutions:Universities and school districts with campus-wide security requirements.
- Retail Stores:Chain operators deploying edge-computing video analytics to automate loss prevention.
Banks anchor premium contract value, with healthcare facilities expanding most quickly as patient data protection mandates intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor positioning across Europe as compliance cost differentials between member states influence contract migration patterns. Security providers are relocating service delivery infrastructure toward jurisdictions with streamlined certification timelines while maintaining client proximity in high-demand markets.
Germany
Commercial real estate portfolios in Frankfurt and Munich are expanding contracted security coverage as building automation platforms converge with physical guarding services. Germany's BSI mandates strict critical infrastructure certification protocols that extend vendor mobilization timelines to 12-18 months. The Rhine-Ruhr industrial corridor concentrates demand for integrated cyber-physical security systems among energy and manufacturing facilities.
France
ANSSI protocols require critical infrastructure operators to implement unified cyber-physical security frameworks, creating bundled demand for threat detection and response capabilities. France's CNIL has tightened biometric data retention limits under GDPR-aligned enforcement, forcing privacy-by-design architecture in new access control deployments. Paris and Lyon anchor premium contract value as banking headquarters consolidate vendor relationships under single accountability structures.
United Kingdom
Financial services firms in the City of London are mandating integrated incident response across previously siloed guarding, surveillance, and IT security functions. The UK's post-Brexit regulatory framework maintains GDPR-equivalent data protection standards for biometric systems while introducing distinct procurement procedures for government contracts. Manchester and Birmingham commercial districts show expanding demand for remote monitoring services as property managers seek to reduce manned guarding hours.
Netherlands
Logistics operators and retail chains are deploying edge-computing video analytics at scale to automate threat detection without centralized processing. Dutch data protection authority guidelines align with EU AI Act risk-classification frameworks for biometric verification in public-sector facilities. The Rotterdam port complex and Amsterdam logistics corridor concentrate demand for automated surveillance systems with embedded intelligence.
Poland
Mid-size enterprise segments in Warsaw and Krakow offer first-mover positioning for integrated remote monitoring services ahead of full regulatory harmonization with EU directives. Polish commercial property markets show underpenetrated demand for technology-enabled security relative to Western European benchmarks. The country's central location within European supply chains is attracting security providers seeking to establish regional service hubs.
Europe Security Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent cybersecurity and building automation spaces. The vendor base clusters around three maturity tiers: multinational guarding incumbents with technology platform investments, telecommunications-derived cyber-physical integrators, and specialized risk consultancies. Dominant competitive moves include portfolio diversification into converged security offerings and strategic partnerships bridging physical access and network security domains.
Within the integrated services tier, Securitas AB and Orange Cyberdefense exemplify divergent paths toward unified security delivery. Securitas leverages Nordic and Continental scale to anchor physical guarding revenue while building remote monitoring capabilities. Orange Cyberdefense competes through converged cyber and physical security under unified service-level agreements. G4S Ltd occupies a specialized position in risk consulting that extends beyond commoditized patrol services.
| Leading Market Players |
|---|
| Deutsche Telekom AG |
| Orange Cyberdefense |
| Securitas AB |
| BT Group plc |
| Accenture PLC |
| G4S Ltd |
| Atos SE |
| Prosegur Compañía de Seguridad |
| ASSA ABLOY AB |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up guarding specialists across Germany and France are consolidating fragmented regional operators to extract procurement scale on biometric hardware and cloud-monitoring platforms. This ownership pattern concentrates purchasing power among fewer buyers while compressing vendor margins through multi-year bundled contracts that span physical guarding and electronic surveillance.
Pricing Analysis
Distributor margins on biometric access hardware typically absorb 15-25 percent of end-user contract value before system integrators apply project-based installation pricing. Pricing stratifies across premium, standard, and economy tiers based on ANSSI certification grade and after-sales response guarantees. Cost compression in mid-market commercial contracts is intensifying because GDPR compliance infrastructure adds operational overhead without commensurate pricing power. Healthcare facilities and educational institutions exhibit highest price sensitivity, while critical infrastructure operators accept premium positioning for BSI-validated systems.
Supply Chain Analysis
France's national cybersecurity certification mandates and Germany's BSI procurement rules are reshaping sourcing patterns toward domestic system integrators with cleared personnel. Hardware manufacturing concentrates in Taiwan, South Korea, and China for camera sensors, edge processors, and biometric readers. Component supply draws from specialized semiconductor foundries, optical lens fabricators, and encrypted storage module producers. Single-source vulnerability runs through Taiwanese chip fabrication for AI-enabled video analytics. Distribution runs through certified security integrators with direct relationships to end-user facilities rather than open-channel distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric verification platforms are shifting contract economics from labor-hour billing toward uptime-guarantee premiums, expanding service margins for vendors with integrated cyber-physical capabilities. Cloud-native access control architectures reduce marginal delivery costs while commanding subscription pricing multiples above traditional guarding.
For Market Incumbents: Extend remote monitoring platform investments to displace competitor guarding contracts during building automation retrofits. Consolidate vendor relationships around unified SLAs before telecommunications-derived cyber-physical integrators capture banking and insurance headquarters. Defensive priority rests on ANSSI and BSI certification maintenance to preserve critical infrastructure access against emerging cloud-native entrants lacking clearance timelines. For New Entrants and Emerging Players: Mid-size Polish and Romanian enterprises with limited legacy access control infrastructure represent the most penetrable buyer archetype for integrated remote monitoring services. White-space targets include Green Deal-mandated commercial retrofits in Warsaw logistics corridors and Krakow manufacturing zones. Go-to-market positioning should emphasize rapid deployment without 12-18 month certification delays that handicap Western European competition. For Investors and Strategic Acquirers: Valuations sit cheapest among family-owned mid-cap guarding operators with underdeveloped technology platforms but established client relationships in German commercial real estate. Long-term viability hinges on successful convergence with cyber-physical capabilities over a multi-year transformation window. Acquisition priority targets specialists with ANSSI or BSI clearances and existing critical infrastructure accounts. The signal to watch is procurement team consolidation of cyber and physical security budgets under single accountability structures.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies cyber and physical security under single SLAs for French banking headquarters. |
| Acquisition of Specialist Firm | Captures ANSSI-certified teams and accelerates critical infrastructure market entry. |
| Geographic Expansion | Establishes regional hubs in Poland ahead of EU regulatory harmonization completion. |
| Strategic Partnership | Links biometric hardware vendors with cloud-monitoring providers for bundled offerings. |
| Product Launch | Introduces edge-computing video analytics with GDPR-compliant on-device processing. |
Research Methodology
Coverage spans Western Europe, Central Europe, and Nordic markets, with primary inputs from each region validating demand patterns. Security service executives, critical infrastructure procurement officers, facility management directors, and biometric system integrators provided operational perspectives. Secondary validation drew from ANSSI certification registries, BSI technical guidelines, EU AI Act implementation documents, and commercial property retrofit databases. Bottom-up contract value analysis triangulated against top-down market sizing from regulatory filings and industry association reports.
Rate-of-change decomposition separated volume expansion from pricing evolution across the projection horizon. Segmentation modeling incorporated service type, client category, technology platform, and end-use environment dimensions. CAGRs were derived from fitted trend analysis calibrated to replacement cycle acceleration and regulatory mandate timelines. Forecast inputs included building automation convergence rates, GDPR compliance cost trajectories, and critical infrastructure security spending commitments.
Underlying measurement precision varies by segment; government and critical infrastructure contracts carry tighter precision than fragmented mid-market commercial accounts. Forecasts reflect assumptions about regulatory harmonization progress and certification timeline stability. Cyber-physical skill scarcity, legacy system integration friction, and biometric data retention rule changes could materially revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Forensic Technologies Market
Security and Surveillance
Security Product Integration Services Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Global X-Ray Security Scanner Market
Security and Surveillance
Smart Security Market
Security and Surveillance
Global Bot Security Market
Security and Surveillance
Ballistic Protection Scanners Market
Security and Surveillance
Security Analytics Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
5G-Enhanced Surveillance Market
Security and Surveillance
Face Smart Lockers Market
Security and Surveillance
Night Vision Scopes Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Home Security Sensors Market
Security and Surveillance
Smart Home Security Market