
 Global Mobile User Authentication Market | 2026-2036
Global Mobile User Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile User Authentication Market Foresight
Multi-source procurement of authentication modules is consolidating as enterprises reduce vendor fragmentation and streamline identity stack management. Thales Group leverages its hardware security module heritage to anchor high-assurance government and financial contracts. Okta Inc. competes through cloud-native directory services that extend across hybrid enterprise environments. IDEMIA specializes in biometric sensor integration, sustaining differentiation through liveness detection and document verification depth.
Mobile user authentication encompasses credential verification methods executed on smartphones and tablets, combining cryptographic protocols, biometric sensors, and behavioral analytics to validate claimant identity against registered templates. The primary purpose is to secure digital service access, financial transactions, and corporate data against credential theft and device compromise. Biometric methods now lead in consumer-facing deployments, while behavioral authentication represents the fastest-growing segment as continuous risk scoring displaces static password gates. Cloud-based deployment dominates margin pools by converting perpetual license revenue into recurring subscription streams, though federated architectures gain traction in multi-organization consortia.
FDA guidelines on mobile health application security, EU GDPR data minimization requirements, and NIST digital identity guidelines collectively shape product standards and market access conditions for authentication vendors. EMA-aligned data integrity frameworks in Europe and HIPAA security rule enforcement in the United States further constrain how biometric and health-adjacent identity data may be collected, stored, and processed. Stakeholders must monitor evolving AI Act conformity assessment procedures and zero-trust architecture mandates to anticipate procurement specification shifts.
Market Dynamics
Zero-trust security mandates from NIST and EU AI Act conformity assessments are compressing authentication deployment cycles, forcing enterprises to retire password-centric architectures before end-of-life.
Growth Catalysts
- GDPR data minimization mandates:European financial institutions must deploy privacy-preserving biometric templates that cannot be reverse-engineered, accelerating tokenized identity infrastructure procurement.
- Behavioral biometrics:Continuous authentication based on keystroke dynamics and gait analysis is displacing static session timeouts in mobile banking applications.
- United States federal zero-trust directives:OMB memoranda require agencies to eliminate passwords for workforce access by fiscal year deadlines, creating immediate demand for phishing-resistant credentials.
Market Restraints
- Silicon supply concentration:Secure element manufacturing for hardware-backed authentication keys clusters in Taiwan and South Korea, exposing procurement to geopolitical disruption.
- EU AI Act conformity costs:High-risk biometric systems require notified body assessment and ongoing post-market monitoring, extending time-to-revenue for new product launches.
- Template storage limitations:On-device biometric matching against encrypted templates demands specialized neural processing units absent from mid-tier smartphone chipsets.
Strategic Opportunities
- India digital public infrastructure:Aadhaar-linked authentication APIs and DigiLocker integration create embedded identity verification demand for fintech and healthcare applications.
- Convergence of passkeys and verifiable credentials:W3C standards enable wallet-based identity presentation without centralized identity providers, opening decentralized architecture revenue pools.
- Brazil's PIX instant payment expansion:Regulatory requirements for strong customer authentication on high-value transactions drive biometric enrollment at merchant points of sale.
Industry Challenges
- FIDO2 certification bottlenecks:Interoperability testing against multiple authenticator implementations extends engineering cycles and strains quality assurance resources.
- Legacy IAM migration complexity:Enterprises maintaining Active Directory forests with decades of accumulated group policies face identity federation architecture redesigns measured in quarters.
- Biometric algorithm bias remediation:Demographic performance variation in facial recognition systems requires ongoing dataset curation and fairness auditing to meet emerging regulatory expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile User Authentication Market |
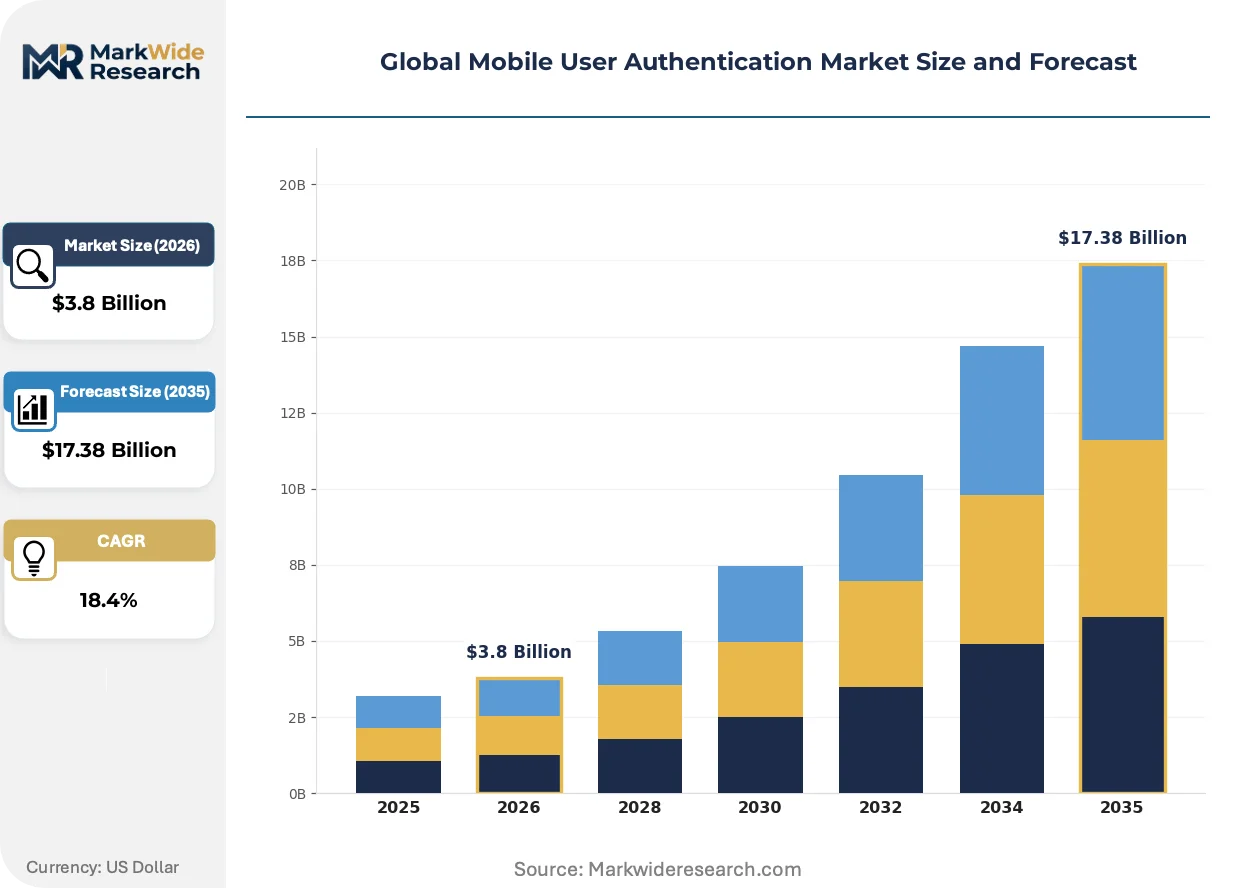
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Authentication Method: Biometric, OTP, Password, Token, Behavioral, Certificate Deployment Mode: Cloud-based, On-premise, Hybrid, Federated End User: BFSI, Telecommunications, Government, Manufacturing, Education, Hospitality Application: Secure Access, Transaction Verification, Device Unlock, Data Protection, Identity Management, Fraud Prevention |
| Companies Covered | Thales Group, OneSpan Inc., Okta Inc., Broadcom Inc., Entrust Corporation, Cisco Systems Inc., Ping Identity Holding Corp., IDEMIA, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile User Authentication Market Shifts & Advancements
Authentication modalities are fragmenting across device form factors and risk contexts, with vendors racing to unify disparate verification signals into coherent trust scores without adding user friction.
Passkey credential synchronization is rewriting how consumer-facing services manage account recovery and cross-device continuity. Major platform operators are embedding FIDO2 authenticators into operating system keystores, eliminating separate hardware security key purchases for mass-market users. This compression of credential management into platform-native services threatens standalone password manager revenue models while expanding addressable market for biometric liveness detection.
EU AI Act risk classification for biometric identification systems is forcing architectural pivots toward on-device inference and federated template matching. Systems deployed in public spaces or workplace monitoring contexts now require fundamental rights impact assessments and human oversight mechanisms. German and French data protection authorities are interpreting these obligations most stringently, creating compliance complexity for vendors serving multinational enterprise accounts.
Outcome-based security service contracts are displacing per-seat licensing in large enterprise procurement. Chief information security officers at United States healthcare systems and financial institutions now specify authentication effectiveness metrics—phishing resistance rates, false acceptance ratios, mean time to compromise—within master service agreements. This performance accountability shift concentrates vendor selection on measurable security outcomes rather than feature checklists, favoring providers with telemetry infrastructure and incident response integration.
Global Mobile User Authentication Market Segmentation
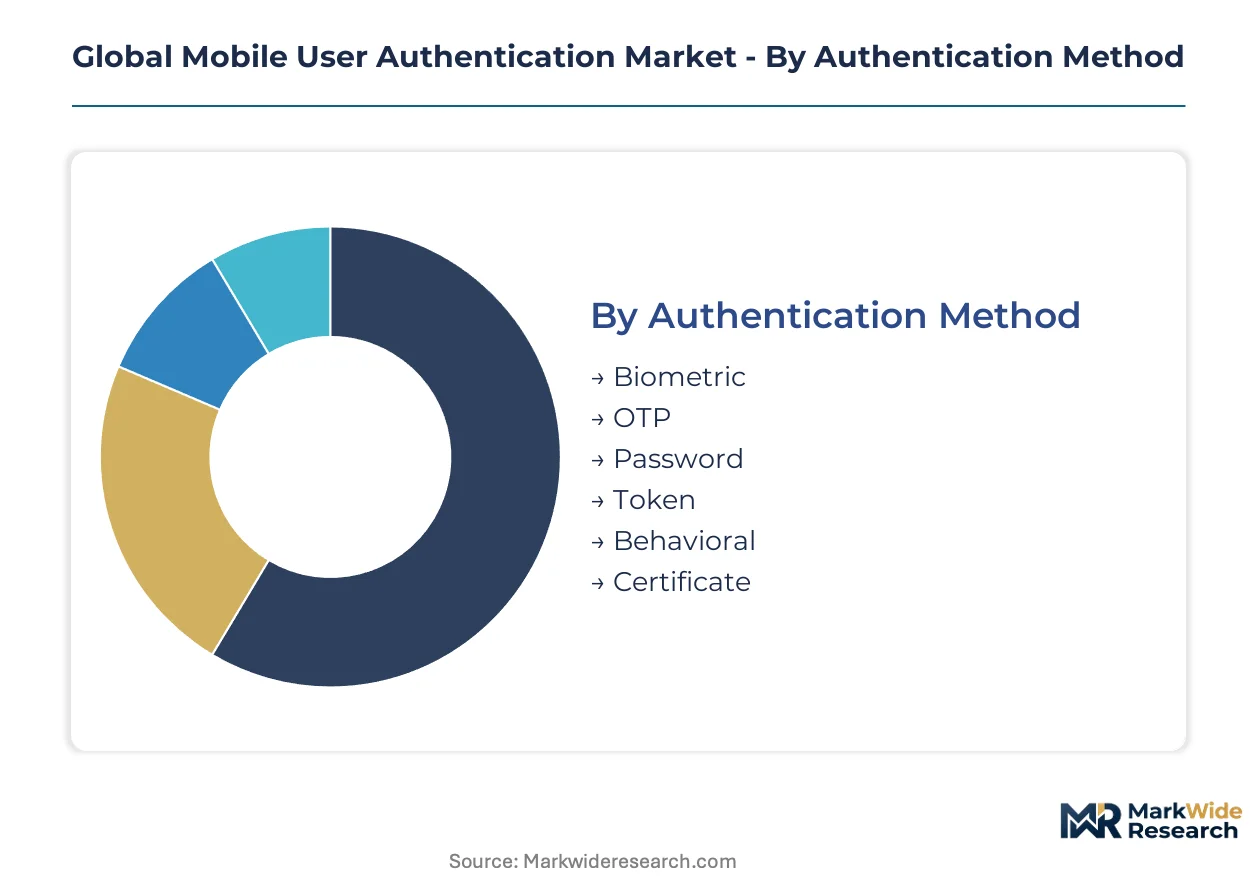
Authentication vendors structure product portfolios around four intersecting dimensions that determine integration complexity, recurring revenue potential, and regulatory exposure. Deployment mode and end-user industry particularly concentrate margin pools and shape competitive positioning.
Authentication Method:
Buyers differ fundamentally in their tolerance for user friction versus their exposure to credential theft and replay attacks.
- Biometric:Fingerprint, facial, and iris matching against encrypted templates stored in secure enclaves or trusted execution environments. Financial services firms in the United States deploy liveness detection to meet NIST phishing-resistant credential mandates for high-value transactions.
- Behavioral:Continuous risk scoring through keystroke dynamics, gait analysis, and touchscreen interaction patterns without explicit user action. Mobile banking applications in Germany and France adopt this to satisfy CNIL and BfDI expectations for minimal data collection under GDPR data minimization principles.
- OTP:Time-synchronized or event-based one-time codes delivered via SMS, email, or authenticator applications.
- Password:Knowledge-based credentials with salted hash storage, rapidly contracting in enterprise procurement due to zero-trust directives.
- Token:Hardware or software security keys generating cryptographic proof-of-possession signatures.
- Certificate:PKI-based identity credentials bound to device or user through trusted certificate authority chains.
Biometric leads volumes today; behavioral is gaining share fastest as continuous authentication displaces static session gates.
Deployment Mode:
Margin structure varies sharply between perpetual license conversion and native platform integration.
- Cloud-based:Multi-tenant identity platforms delivering authentication-as-a-service with API-first integration. Healthcare systems across the United States prefer this model to outsource HIPAA security rule compliance and incident response liability.
- Hybrid:Split processing with sensitive operations on-premise and scalability through cloud burst capacity. German automotive manufacturers deploy this architecture to keep biometric templates within EU jurisdiction while leveraging global CDN performance.
- On-premise:Dedicated infrastructure within customer data centers with full operational control.
- Federated:Cross-organizational trust frameworks enabling single sign-on across consortium members without centralized identity stores.
Cloud-based dominates recurring revenue; hybrid is climbing the fastest as data residency requirements harden.
End User:
Procurement sophistication and compliance burden separate regulated industries from commercial adopters.
- BFSI:Banks, insurers, and payment processors with strict strong customer authentication mandates under PSD2 and equivalent frameworks. Brazilian institutions integrate PIX instant payment requirements with biometric enrollment at merchant points of sale.
- Government:National identity programs and workforce access systems with classified data handling requirements. India's Aadhaar-linked authentication APIs create embedded verification demand for DigiLocker-integrated services.
- Telecommunications:Subscriber identity verification and SIM swap fraud prevention.
- Manufacturing:Operational technology access control and supply chain partner onboarding.
- Education:Campus-wide single sign-on and remote examination proctoring.
- Hospitality:Guest service personalization and payment tokenization.
BFSI leads absolute spending; government is expanding most quickly through digital public infrastructure investments.
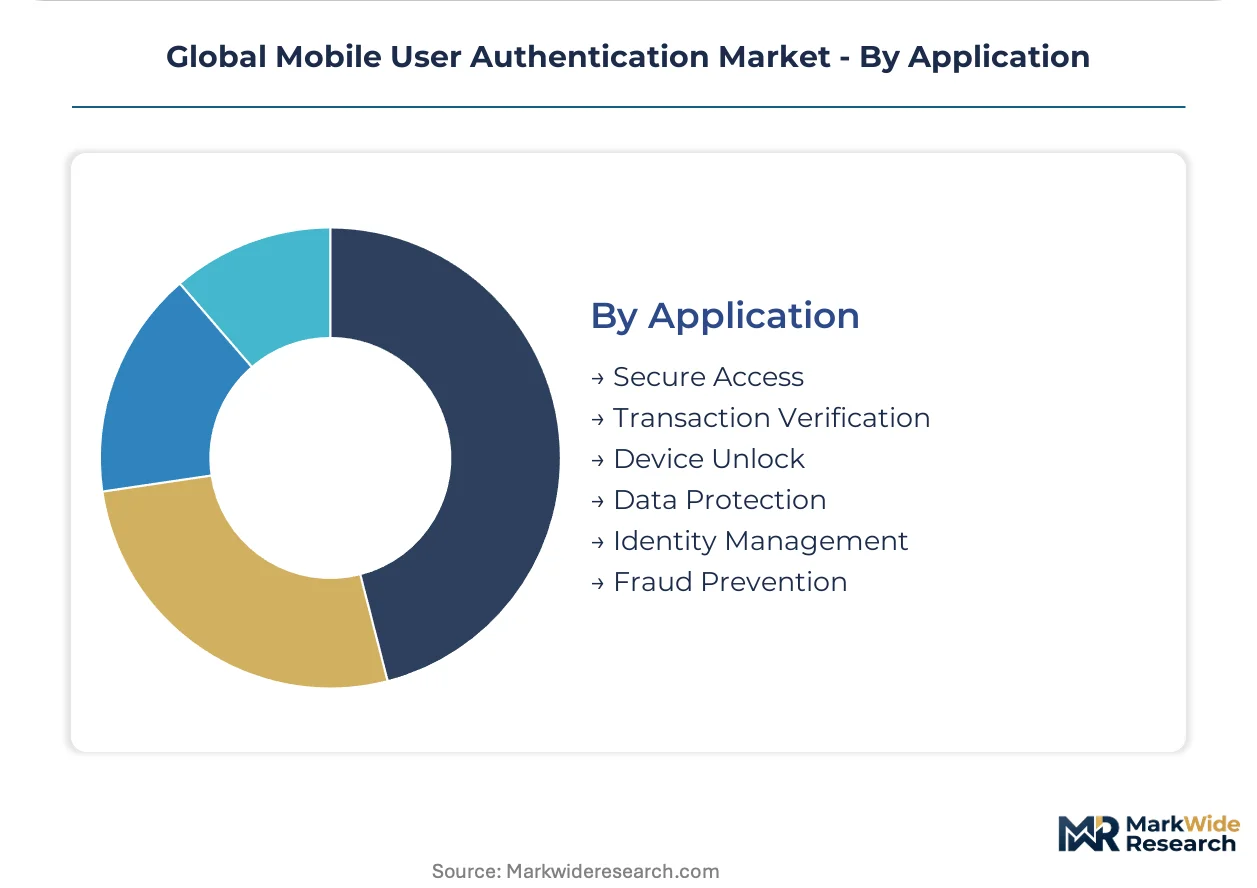
Application:
Use case specificity determines whether buyers prioritize low-latency matching, audit granularity, or cross-platform continuity.
- Secure Access:Workforce and consumer login protection against credential stuffing and phishing. United States federal agencies eliminate passwords entirely under OMB zero-trust memoranda deadlines.
- Fraud Prevention:Real-time transaction risk scoring and synthetic identity detection. European payment service providers tune behavioral models to EU AI Act fundamental rights impact thresholds.
- Transaction Verification:High-assurance confirmation for payments and account modifications.
- Device Unlock:Consumer smartphone and tablet access with platform-native biometric stores.
- Data Protection:Encryption key release contingent on authenticated identity.
- Identity Management:Lifecycle provisioning, deprovisioning, and attribute verification.
Secure access anchors current procurement; fraud prevention shows the steepest expansion trajectory as real-time scoring becomes mandatory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cybersecurity cluster generates substantial authentication R&D investment, while regulatory divergence across major economies fragments deployment standards and procurement timelines.
United States
Federal zero-trust mandates and healthcare digitization drive enterprise authentication procurement. OMB memoranda require agencies to eliminate passwords by fiscal deadlines, accelerating phishing-resistant credential adoption. Boston's healthcare security cluster concentrates HIPAA-compliant identity infrastructure development for hospital systems.
Germany
Automotive digitalization and industrial IoT access control expand behavioral biometrics demand. BfDI interpretations of GDPR data minimization compel on-device template processing rather than cloud storage. Munich's automotive cybersecurity ecosystem develops liveness detection systems for connected vehicle authentication.
India
Aadhaar-linked verification APIs and DigiLocker integration create embedded identity demand across fintech and healthtech. RBI strong customer authentication guidelines for digital payments mandate biometric enrollment at scale. Bangalore's technology corridor hosts concentrated development of voice and facial matching for regional language users.
Brazil
PIX instant payment expansion and merchant point-of-sale biometric requirements reshape financial authentication. Central bank regulations for high-value transaction verification drive hardware security module deployment. São Paulo's fintech district concentrates liveness detection integration for retail banking applications.
United Kingdom
Open banking API security standards and financial services regulatory mandates accelerate tokenized identity adoption. FCA guidance on strong customer authentication shapes procurement specifications for challenger banks. London's financial technology cluster develops behavioral analytics for real-time transaction risk scoring.
Global Mobile User Authentication Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue privacy-preserving architectures and decentralized credential frameworks. The vendor base clusters around three strategic archetypes: hardware security module heritage players, cloud-native identity platform operators, and biometric sensor integration specialists. Consolidation pressure intensifies as enterprise procurement favors unified identity stacks over fragmented point solutions. Dominant competitive moves include strategic partnerships for FIDO2 certification alignment and portfolio diversification into continuous authentication telemetry.
Within the hardware-rooted assurance tier, Thales Group and Broadcom Inc. exemplify established European and North American positions in secure element manufacturing. IDEMIA occupies a specialist position in biometric sensor integration, reflecting French industrial concentration in liveness detection and document verification systems. Okta Inc. anchors the cloud-native platform segment, representing the shift toward API-first directory services across hybrid enterprise environments.
| Leading Market Players |
|---|
| Thales Group |
| OneSpan Inc. |
| Okta Inc. |
| Broadcom Inc. |
| Entrust Corporation |
| Cisco Systems Inc. |
| Ping Identity Holding Corp. |
| IDEMIA |
| Microsoft Corporation |
| Others |
Supply & Pricing Matrix
Federal zero-trust procurement deadlines in the United States are compressing vendor selection cycles and forcing authentication providers to absorb certification costs upfront, reshaping how margin pools distribute across hardware-backed and cloud-native tiers.
Pricing Analysis
Secure element manufacturing costs in Taiwan and South Korea feed directly into hardware security key pricing, with FIDO2 certification tiers separating premium government-grade offerings from standard enterprise subscriptions. Cloud-native authentication-as-a-service providers compete on API call volume scales, while on-premise deployments command customization premiums for data residency compliance. Pricing pressure stems from platform operators embedding FIDO2 authenticators into operating system keystores at no marginal cost, eroding standalone hardware key margins. Mid-tier financial institutions exhibit highest price sensitivity, while classified government contracts tolerate premium positioning for tamper-resistant assurance.
Supply Chain Analysis
Regional distribution centers in Singapore, Frankfurt, and Dallas anchor hub-and-spoke fulfillment for hardware security modules, with inventory positioning dictated by data residency requirements rather than pure logistics optimization. Secure element fabrication concentrates in Taiwan and South Korea, with final assembly and personalization distributed to Germany, the United States, and India to satisfy local content expectations. Neural processing units for on-device biometric matching draw from TSMC and Samsung foundry capacity, exposing procurement to semiconductor cycle volatility. Single-source vulnerability in EUV lithography equipment for advanced secure enclaves represents the dominant structural risk. Distribution runs through value-added resellers with FIDO2 certification expertise and direct enterprise sales forces for large government accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile user authentication market functions as a regulatory compounder, with EU AI Act conformity assessments and NIST zero-trust mandates generating sustained procurement velocity regardless of macroeconomic cycles.
For Market Incumbents: To counter platform operator credential embedding, Thales Group and hardware-rooted specialists must deepen government certification moats through Common Criteria EAL6+ investments while accelerating cloud-native service line buildout to capture hybrid deployment demand. Channel control through exclusive FIDO2 testing laboratory partnerships limits emerging competitor access to financial services procurement shortlists. For New Entrants and Emerging Players: API-first behavioral biometrics integration presents the lowest friction entry path, with German and French mobile banking applications under CNIL and BfDI enforcement offering immediate addressable demand. Target India's DigiLocker-embedded verification ecosystem through Aadhaar-linked authentication APIs, where regulatory mandates create procurement pull without incumbent saturation. Go-to-market execution should prioritize outcome-based security service contracts with measurable phishing resistance metrics. For Investors and Strategic Acquirers: Asymmetric upside sits with privacy-preserving authentication architecture specialists possessing federated template matching capabilities and EU AI Act conformity assessment infrastructure already operational. Long-term viability hinges on regulatory tailwind durability rather than technology differentiation alone. Watch FIDO2 certification bottleneck resolution as the inflection signal—accelerated interoperability testing capacity indicates incumbent vulnerability to platform-native substitution.| Strategic Initiative | Industry Significance |
|---|---|
| FIDO2 Certification Acceleration | Expedited interoperability testing against multiple authenticator implementations compresses emerging competitor time-to-revenue. |
| Outcome-Based Security Contracting | Phishing resistance rate guarantees within master service agreements shift procurement criteria toward measurable security outcomes. |
| Privacy-Preserving Architecture Investment | On-device inference and federated template matching satisfy EU AI Act fundamental rights impact thresholds for biometric systems. |
| Digital Public Infrastructure Integration | Aadhaar-linked APIs and DigiLocker embedding capture embedded identity verification demand across Indian fintech and healthtech. |
| Behavioral Biometrics Platform Launch | Continuous keystroke dynamics and gait analysis scoring displace static session timeouts in GDPR-constrained European deployments. |
Research Methodology
Bottom-up financial services and government procurement modeling reconciled against top-down secure element manufacturing capacity tracking forms the analytical core of this study. Primary interviews with chief information security officers, identity infrastructure architects, FIDO Alliance certification engineers, and healthcare system procurement directors combined with secondary validation against NIST digital identity guideline publications, EU AI Act implementing act drafts, and SEC 10-K disclosures from publicly traded identity platform operators. Triangulation between demand-side deployment timelines and supply-side foundry capacity constraints ensures forecast coherence.
Input-output matrices map authentication method adoption curves against deployment mode infrastructure requirements across the projection horizon. Segmentation dimensions modeled include authentication modality, deployment architecture, end-user industry vertical, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to historical procurement velocity and adjusted for mandate-driven acceleration effects. Industry-specific forecast inputs encompass OMB zero-trust memoranda implementation pacing and EU notified body assessment capacity expansion.
The model assumes a particular technology adoption path; alternative pathways for passkey credential synchronization would alter the outlook if platform operators extend native authenticator capabilities to enterprise contexts faster than projected. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and semiconductor supply normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
Out-Of-Band Authentication Market
Biometrics & Identity Management
North America Biometrics in Government Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Europe Enterprise Biometrics Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Identity Verification Market
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
Global Authentication and Brand Protection Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market