
 Homeland Security Market | 2026-2036
Homeland Security Market Size, Share, and Industry Trends Forecast 2026-2036
Homeland Security Market Intelligence
The EU AI Act is realigning compliance costs for biometric and surveillance vendors serving European public safety agencies. Lockheed Martin leverages its integrated command center expertise to anchor large-scale border protection contracts across multiple continents. Northrop Grumman sustains R&D intensity in autonomous threat detection systems that differentiate its portfolio from platform-centric rivals.
Homeland security encompasses integrated systems for threat identification, border control, critical infrastructure protection, and emergency response coordination, typically incorporating sensor fusion algorithms, multi-factor biometric authentication, and real-time data analytics operating across classified and unclassified networks. Surveillance cameras and threat detection software represent the fastest-expanding solution categories as municipal and federal buyers prioritize predictive analytics over reactive monitoring. Border protection applications command the deepest procurement budgets among application areas, while cloud-based and hybrid deployment modes are displacing legacy on-premises architectures in mid-tier agency upgrades.
The Department of Homeland Security, CISA, and the TSA collectively shape product certification requirements, procurement timelines, and interoperability standards for domestic vendors. The EU AI Act and GDPR impose parallel constraints on biometric data processing and automated surveillance deployments across European member states. Stakeholders must monitor evolving classification thresholds for AI-enabled systems, as regulatory fragmentation between jurisdictions threatens to fragment addressable market segments and complicate product roadmaps.
Market Dynamics
AI-enabled threat detection platforms are compressing procurement cycles across federal and municipal agencies, forcing legacy vendors to re-architect sensor fusion capabilities around real-time analytics pipelines or face displacement from cloud-native challengers.
Growth Catalysts
- CISA Critical Infrastructure Directives:Updated federal mandates accelerate AI procurement timelines for power grid and water treatment operators seeking predictive threat identification.
- Perimeter defense budgets:Congressional appropriations prioritize biometric border infrastructure, concentrating demand for multi-factor authentication systems at land and maritime entry points.
- Sensor fusion algorithms:Advances in correlating thermal, radar, and optical inputs enable single-platform threat classification that reduces false-positive rates for airport and stadium operators.
Market Restraints
- Semiconductor supply concentration:Specialized ASIC fabrication for edge AI inference depends on Taiwan-based foundry capacity, creating single-source vulnerability for domestic system integrators.
- EU AI Act compliance friction:Biometric surveillance classification as high-risk AI imposes conformity assessment costs that deter European municipal pilot programs.
- Legacy system substitution:Analog CCTV infrastructure persists in mid-tier agencies, slowing full-platform replacement cycles despite software-defined analytics availability.
Strategic Opportunities
- India smart city mandates:Ministry of Home Affairs urban safety programs create first-mover advantage for integrated command-and-control platform vendors in Delhi, Mumbai, and Bangalore metro corridors.
- Cloud-hybrid deployment models:FedRAMP-authorized edge-to-cloud architectures unlock mid-sized state and local agencies previously excluded from classified network solutions.
- Drone detection convergence:RF sensing fused with computer vision addresses counter-UAS gaps at critical infrastructure sites lacking integrated airspace monitoring.
Industry Challenges
- Cleared workforce scarcity:TS/SCI-cleared data scientists and systems engineers command premium compensation, constraining R&D velocity for mid-tier contractors.
- Interoperability certification timelines:DHS SAFETY Act and NIAP Common Criteria evaluations extend product launch windows by 18-24 months.
- Cross-domain solution integration:Bridging classified and unclassified networks for real-time threat sharing introduces architectural complexity that inflates deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homeland Security Market |
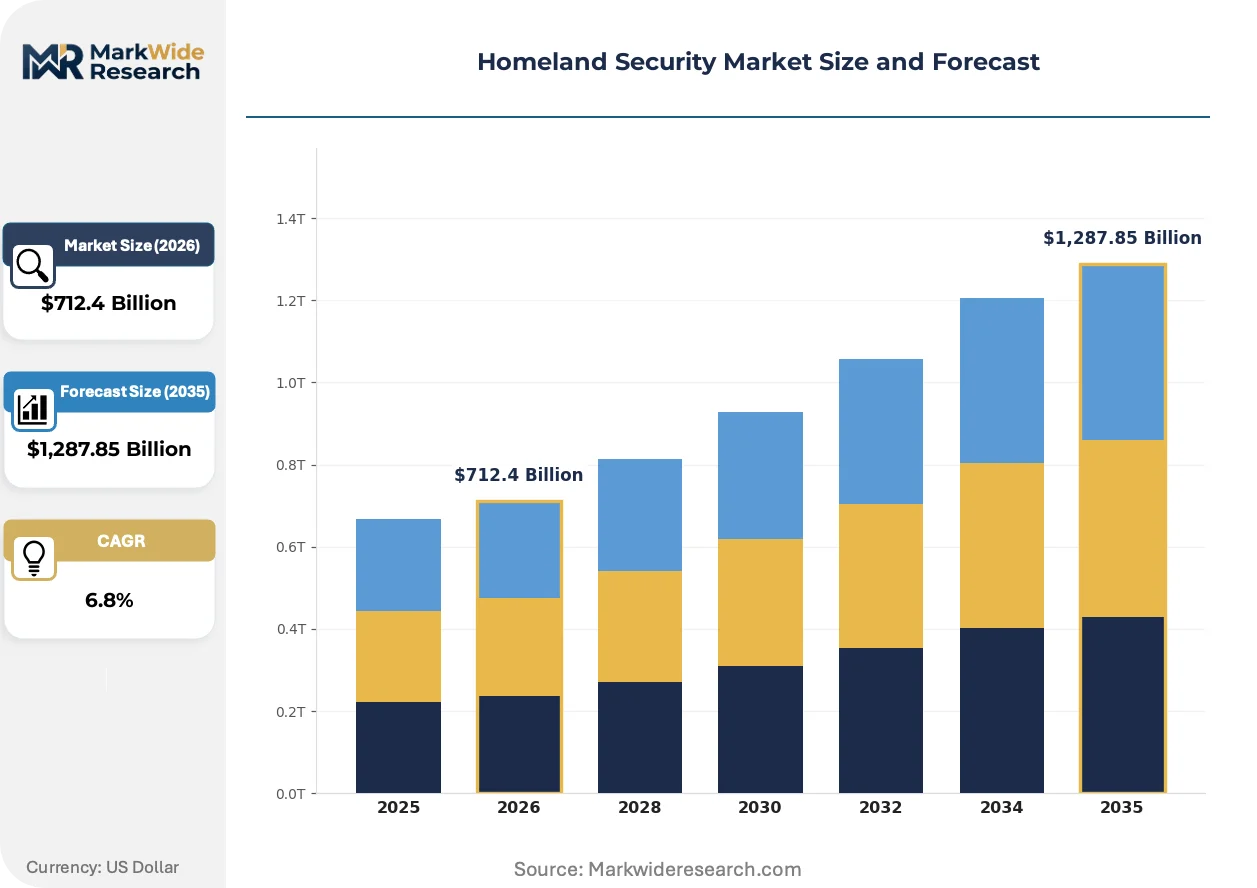
| Market Size in 2026 | $712.4 Billion |
| Market Size in 2035 | $1,287.85 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Biometric Systems, Surveillance Cameras, Threat Detection Software, Access Control Systems, Cybersecurity Platforms Application Area: Border Protection, Critical Infrastructure Defense, Emergency Response, Public Safety Monitoring, Transportation Security End User: Government Agencies, Law Enforcement, Military Divisions, Intelligence Organizations, Emergency Management Teams Deployment Mode: On-Premises, Cloud-Based, Hybrid Systems, Mobile Units, Command Centers |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, Boeing, BAE Systems, General Dynamics Corporation, Thales Group, RTX Corporation, Elbit Systems Ltd., Leidos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homeland Security Market Strategic Shifts & Innovations
Real-time analytics pipelines are displacing batch-processed intelligence workflows across federal fusion centers, compressing the gap between sensor detection and operator response from minutes to seconds.
Edge AI inference engines are expanding into battery-powered field sensors, enabling autonomous threat classification at remote border segments lacking fiber connectivity. U.S. Customs and Border Protection pilots in Arizona and Texas deploy these units for vehicle and personnel detection without backhaul dependency. The technology is expanding into maritime domain awareness, where satellite bandwidth constraints previously limited analytics to shore-side processing.
The EU AI Act's high-risk system classification imposes mandatory conformity assessments on biometric identification products sold to European law enforcement agencies. Vendors must maintain technical documentation, human oversight protocols, and accuracy testing records subject to market surveillance authority audits. France, Germany, and Italy represent the largest affected procurement pools, with national regulators interpreting classification thresholds inconsistently.
Subscription-based platform licensing is displacing perpetual software purchases among municipal fusion centers and regional emergency operations hubs. Annual recurring revenue models align vendor incentives with uptime performance and feature velocity, replacing capital-intensive refresh cycles. California, Texas, and Florida metro agencies lead this transition, with state procurement offices rewriting RFP templates to accommodate operational expenditure structures.
Homeland Security Market Segmentation
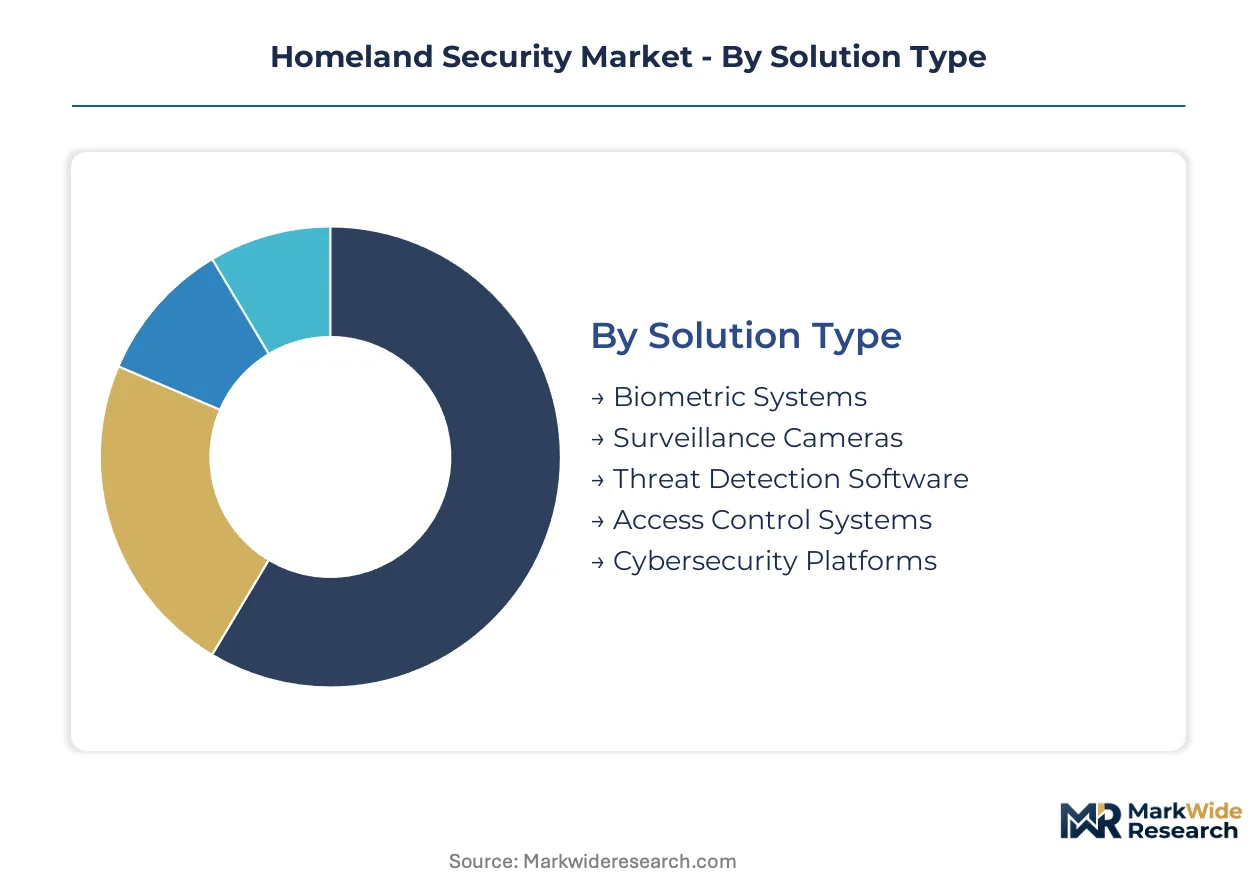
Homeland security procurement operates through distinct technical and operational lenses that reshape vendor positioning. Buyers prioritize interoperability certifications and real-time analytics integration over standalone feature sets, compressing the competitive field to platform-centric suppliers.
Solution Type:
Agency budget cycles and certification timelines determine solution selection, with multi-year appropriations favoring capital-intensive hardware over recurring software licenses.
- Biometric Systems:Multi-factor authentication platforms incorporating fingerprint, iris, and facial recognition modalities for high-throughput border checkpoints. CBP procurement at land ports of entry in Arizona and Texas concentrates demand as pedestrian processing volume climbs. DHS certification requirements for accuracy thresholds and anti-spoofing protocols extend vendor qualification timelines.
- Surveillance Cameras:Optical and thermal imaging arrays with edge AI inference for autonomous threat classification in stadium and transit environments. Municipal fusion centers in California and Florida drive replacement cycles as legacy analog infrastructure reaches end-of-life. FedRAMP authorization for cloud-connected feeds unlocks mid-tier agency adoption previously blocked by security clearance constraints.
- Threat Detection Software:Sensor fusion platforms correlating disparate inputs into unified operator dashboards.
- Access Control Systems:Physical and logical perimeter defense integrating credential verification with behavioral analytics.
- Cybersecurity Platforms:Network monitoring and incident response tools for critical infrastructure operator environments.
Volume sits with Surveillance Cameras; growth tilts toward Threat Detection Software.
Application Area:
Threat actor sophistication and attack surface exposure determine where federal appropriations concentrate, with perimeter defense commanding the deepest procurement pools.
- Border Protection:Integrated land, maritime, and aerial surveillance for customs and immigration enforcement spanning ports of entry and remote detection corridors. Congressional appropriations for southern border infrastructure sustain multi-billion dollar program continuity. Thermal and radar sensor fusion at unmanned sectors reduces personnel deployment costs while maintaining detection efficacy.
- Critical Infrastructure Defense:Power grid, water treatment, and telecommunications protection against physical and cyber intrusion. CISA directive implementation compels operator investment in predictive threat identification as regulatory compliance deadlines tighten. Electric utility procurement concentrates in Texas and California where grid density intersects with extreme weather exposure.
- Emergency Response:Coordinated multi-agency communication and resource deployment platforms for natural disaster and mass casualty events.
- Public Safety Monitoring:Urban surveillance and crowd analytics for municipal law enforcement command centers.
- Transportation Security:Aviation and mass transit passenger and baggage screening systems.
Procurement depth concentrates in Border Protection; Critical Infrastructure Defense climbs the fastest as regulatory mandates harden.
End User:
Classification level and operational tempo segment buyer requirements, with cleared environments demanding specialized supply chain and personnel vetting.
- Government Agencies:Civilian departments including DHS components, CISA, and TSA operating at unclassified through secret network tiers. FedRAMP and NIAP certification requirements shape vendor eligibility for federal contracts above simplified acquisition thresholds. Procurement centralization through GSA schedules and indefinite delivery vehicles compresses vendor qualification overhead.
- Law Enforcement:State and municipal police departments with fusion center integration requirements and CJIS security policy compliance. Subscription licensing models gain traction as operational expenditure structures replace capital-intensive refresh cycles. California and Texas metro agencies lead this transition with rewritten state procurement templates.
- Military Divisions:Department of Defense components with TS/SCI network integration and cross-domain solution requirements.
- Intelligence Organizations:Civilian and military agencies with specialized compartmented program access demands.
- Emergency Management Teams:State and local coordinators with mutual aid interoperability and mobile command post needs.
Contract value peaks with Military Divisions; Law Enforcement expands most quickly as municipal analytics procurement accelerates.
Deployment Mode:
Connectivity constraints and data sovereignty requirements determine architecture selection, with classified network isolation perpetuating on-premises persistence.
- On-Premises:Air-gapped installations for classified networks and critical infrastructure control systems requiring physical isolation from external connectivity. Nuclear and defense facilities mandate this architecture regardless of cloud capability maturity. Legacy infrastructure persistence in mid-tier agencies sustains replacement demand despite hybrid alternatives.
- Cloud-Based:FedRAMP-authorized SaaS platforms for unclassified fusion centers and regional emergency operations hubs. Elastic compute scaling aligns cost structures with incident-driven usage spikes rather than peak-load capacity planning. State procurement offices in Florida and Virginia pilot operational expenditure frameworks for these deployments.
- Hybrid Systems:Edge-to-cloud architectures partitioning sensitive processing from analytics aggregation.
- Mobile Units:Rapidly deployable command and sensor platforms for disaster response and temporary border surge operations.
- Command Centers:Fixed-site integrated operations facilities with multi-agency coordination and video wall infrastructure.
Installed base concentrates in On-Premises; Cloud-Based gains share fastest as FedRAMP authorization timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense industrial zones in the United States and European aerospace corridors concentrate homeland security procurement, with special economic zones in Israel and India emerging as secondary clusters for surveillance technology development.
United States
Congressional border infrastructure appropriations and CISA critical infrastructure directives drive federal procurement volume. The Cybersecurity and Infrastructure Security Agency mandates predictive threat identification for power grid operators. Arizona and Texas land ports of entry deploy thermal-radar sensor fusion for unmanned border segments.
United Kingdom
Integrated command center modernization and counter-UAS programs anchor defense spending. The UK National Security Strategic Investment Fund accelerates domestic capabilities in autonomous threat detection. London and Southeast England fusion centers pilot subscription-based analytics platforms for municipal law enforcement.
Germany
Critical infrastructure protection budgets expand under EU network security directives and domestic terrorism prevention frameworks. The Federal Office for Information Security certifies cross-domain solutions for classified network integration. Bavaria and Baden-Württemberg host aerospace clusters developing sensor fusion algorithms for airport operators.
Israel
Counter-terrorism technology exports and domestic perimeter defense requirements sustain R&D intensity. The Israel National Cyber Directorate mandates security standards for critical infrastructure software procurement. Tel Aviv metropolitan area startups specialize in edge AI inference for battery-powered field sensors.
India
Smart city safety mandates and border surveillance modernization concentrate demand in urban corridors. The Ministry of Home Affairs urban safety programs fund integrated command-and-control platforms. Delhi, Mumbai, and Bangalore metro areas deploy multi-factor biometric authentication at transit hubs and government facilities.
Homeland Security Market Key Industry Players
United States producers anchor the prime contractor tier; Israeli and European specialists hold differentiated positions in sub-systems and export markets. The vendor base concentrates around platform-centric integrators with cleared supply chains and long-cycle certification experience. Two strategic archetypes dominate: diversified aerospace conglomerates with integrated command center expertise, and mid-tier specialists in autonomous detection and biometric sub-systems. Competitive moves center on FedRAMP authorization acceleration and cross-border technology licensing to navigate EU AI Act compliance.
Within the diversified prime tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify platform-centric positioning with established border protection program continuity. Elbit Systems Ltd. represents the export-oriented specialist archetype, anchoring technology transfer relationships in European and Asia-Pacific markets.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Boeing |
| BAE Systems |
| General Dynamics Corporation |
| Thales Group |
| RTX Corporation |
| Elbit Systems Ltd. |
| Leidos |
| Others |
Cost & Logistics Intelligence
Federal fusion centers and municipal emergency operations hubs concentrate procurement volume, anchoring a subscription-based pricing model that replaces capital-intensive refresh cycles with annual recurring revenue structures aligned to uptime performance.
Pricing Analysis
Short lead-time premiums apply to FedRAMP-authorized edge-to-cloud architectures demanded by state agencies facing compressed deployment windows under CISA directive deadlines. Three-tier pricing structure across premium, standard, and economy levels separates cleared supply chain vendors from commercial-grade competitors, with certification tier and volume scale as primary differentiation drivers. Cost compression in mid-tier biometric sub-systems is intensifying because cloud-native challengers re-architect sensor fusion around real-time analytics pipelines. Municipal law enforcement buyers exhibit highest price sensitivity due to operational expenditure constraints, while military divisions with TS/SCI requirements show lowest sensitivity.
Supply Chain Analysis
Domestic-content mandates in the United States, India, and Israel reshape sourcing patterns for critical infrastructure components, compelling vendors to establish local assembly or technology transfer partnerships. Specialized ASIC fabrication for edge AI inference draws from Taiwan-based foundry capacity, gallium nitride substrates for radar systems, and rare earth elements for thermal imaging arrays. Single-source vulnerability in semiconductor fabrication creates structural exposure to geopolitical disruption. Distribution runs through prime contractor integrators with long-cycle certification experience, feeding into GSA schedules and indefinite delivery vehicles for federal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification for biometric surveillance creates a cost-of-compliance moat that favors incumbent vendors with established conformity assessment infrastructure and technical documentation protocols.
For Market Incumbents: Anticipate displacement pressure from cloud-native challengers by accelerating FedRAMP authorization timelines for hybrid deployment architectures. Fortify position through backward integration into edge AI inference chip design, reducing Taiwan foundry dependency. Invest in cross-border technology licensing capabilities to navigate fragmented EU AI Act interpretation across France, Germany, and Italy.
For New Entrants and Emerging Players: Drone detection convergence platforms offer a technology-first wedge into critical infrastructure sites lacking integrated airspace monitoring. Target India smart city mandates in Delhi, Mumbai, and Bangalore metro corridors where Ministry of Home Affairs urban safety programs create first-mover advantage for integrated command-and-control platforms. Pursue partnership-based go-to-market models with established prime contractors to bypass DHS SAFETY Act and NIAP Common Criteria evaluation barriers.
For Investors and Strategic Acquirers: The window for entry favors mid-tier specialists with autonomous detection or biometric sub-system expertise and cleared supply chain infrastructure. Over a multi-year horizon, consolidation will reward vendors with cross-domain solution integration capabilities bridging classified and unclassified networks. Monitor CISA critical infrastructure directive implementation velocity as the inflection indicator for predictive threat identification procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Unlocks mid-sized state and local agencies previously excluded from classified network solutions. |
| Cross-Border Technology Licensing | Navigates inconsistent EU AI Act interpretation across French, German, and Italian national regulators. |
| Edge AI Inference Engine Development | Enables autonomous threat classification at remote border segments lacking fiber connectivity in Arizona and Texas. |
| Cloud-Hybrid Deployment Architecture | Aligns vendor incentives with uptime performance through subscription-based platform licensing models. |
| Cleared Workforce Pipeline Investment | Addresses TS/SCI-cleared data scientist scarcity constraining R&D velocity for mid-tier contractors. |
Research Approach
Independent corroboration across primary interviews with federal procurement officers, CISA directive implementation leads, municipal fusion center directors, and prime contractor program managers underwrites the qualitative findings. Secondary validation draws from DHS budget justification documents, GSA schedule contract awards, FedRAMP authorization databases, and EU AI Act implementation guidance. Bottom-up segmentation modeling triangulates against top-down federal appropriations analysis to anchor volume estimates.
Comparable-period anchoring to historical CISA directive implementation cycles and border infrastructure appropriation timelines structures the projection methodology. The analytical framework segments by solution type, application area, end user classification level, and deployment architecture across the modeling period. CAGRs derive from procurement cycle compression rates, certification timeline elasticity, and technology substitution curves. Forecast inputs incorporate sensor fusion algorithm advancement trajectories and cloud-hybrid adoption velocity among state and local agencies.
Several conditions sit outside the modeled scope, including classified program compartmented expenditures, emergency supplemental appropriations for border surge operations, and geopolitical disruption to Taiwan semiconductor fabrication capacity. Forecasts reflect documented assumptions about regulatory implementation consistency and certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
National Security
US Bulletproof Glass Market
National Security
Asia-Pacific Non-Lethal Weapons Market
National Security
North America Non Lethal Weapons Market
National Security
Asia-Pacific Border Security Market
National Security
Radiological and Nuclear Security Market
National Security
Global Security Assessment Market
National Security
Europe Non-Lethal Weapons Market
National Security
Chemical, Biological, Radiological and Nuclear (CBRN) Security Market
National Security
Global Non Lethal Weapons Market
National Security
Service Handgun Market
National Security
Saudi Arabia Manned Security Market
National Security
Research Department Explosive (RDX) Market