
 Home Security Solution Market | 2026-2036
Home Security Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Home Security Solution Market Intelligence
The European Union's upcoming Cyber Resilience Act is shifting the cost-of-entry calculus for manufacturers of connected security hardware. This regulation mandates stringent cybersecurity-by-design principles, increasing compliance burdens for new and existing market participants. In this environment, established provider ADT leverages its extensive professional installation network and brand trust. Competitor Vivint Smart Home differentiates by offering a deeply integrated smart home ecosystem that extends beyond traditional security into automation and energy management.
Home security solutions are integrated systems of electronic devices designed to detect and deter unauthorized entry and other hazards. These systems often incorporate passive infrared (PIR) sensors and communicate via protocols like Z-Wave or Wi-Fi to a central hub. The integration of AI-powered analytics within video surveillance products is creating new value through features like person detection and false alarm reduction. While traditional motion detectors and alarm systems constitute a mature product category, smart locks are experiencing significant uptake in residential applications.
Product design and market access are governed by a complex web of regional regulations. In the United States, the FCC sets standards for wireless device emissions, while the EU's GDPR imposes strict rules on the handling of personal data collected by cloud-based services. In China, hardware must comply with national GB standards for interoperability and safety. Stakeholders must continuously balance the push for advanced, AI-driven features against a tightening global landscape of cybersecurity and data privacy compliance.
Market Dynamics
The home security market is defined by a central tension between the rapid integration of AI-powered analytics and a tightening global regulatory landscape for cybersecurity and data privacy. This dynamic forces manufacturers to innovate on features while simultaneously increasing investment in compliance infrastructure.
Growth Catalysts
- AI-Powered Analytics:The integration of artificial intelligence for features like person detection, package recognition, and vehicle identification is reducing false alarms and creating tangible value for consumers, driving upgrade cycles for existing systems.
- Smart Villa Construction:Growth in the luxury residential and smart villa segment is a significant catalyst, as developers increasingly specify fully integrated security and home automation systems as a standard offering to attract high-net-worth buyers.
- Insurance Premium Reductions:Homeowners in markets like the United States and the UK are motivated by discounts on insurance premiums offered for properties with professionally monitored security systems, creating a direct financial incentive for adoption.
Market Restraints
- Regulatory Compliance Burden:Mandates like the EU's Cyber Resilience Act impose stringent cybersecurity-by-design requirements, increasing R&D costs and time-to-market for hardware manufacturers, which can act as a barrier to entry for smaller firms.
- Protocol Fragmentation:The lack of a single, universally adopted communication standard beyond Wi-Fi, with competition between protocols like Z-Wave and Zigbee, creates interoperability challenges and consumer confusion, hindering seamless ecosystem development.
- Data Privacy Concerns:Consumer apprehension regarding the collection and storage of personal data, particularly video footage, by cloud services creates a restraint on adoption, especially in regions with strong data protection laws like GDPR in Europe.
Strategic Opportunities
- Adjacent Service Expansion:Providers have an opportunity to move beyond core security by integrating features for energy management, elder care monitoring through non-intrusive sensors, and water leak detection, creating new recurring revenue streams.
- Emerging Market Penetration:Rapid urbanization and a growing middle class in countries across Southeast Asia and Latin America represent significant untapped markets for affordable, mobile-first home security solutions.
- Edge AI and 5G Convergence:The convergence of 5G connectivity with powerful edge computing allows for sophisticated on-device AI processing, enabling real-time analytics without sending sensitive data to the cloud, directly addressing privacy concerns.
Industry Challenges
- Cybersecurity Talent Scarcity:A persistent shortage of qualified cybersecurity professionals makes it difficult for manufacturers to secure connected devices and cloud platforms against evolving threats, increasing vulnerability and compliance risk.
- Legacy System Integration:Installers face operational challenges when integrating modern wireless security systems with the existing, often outdated, hardwired infrastructure found in older homes, complicating deployments and increasing labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Security Solution Market |
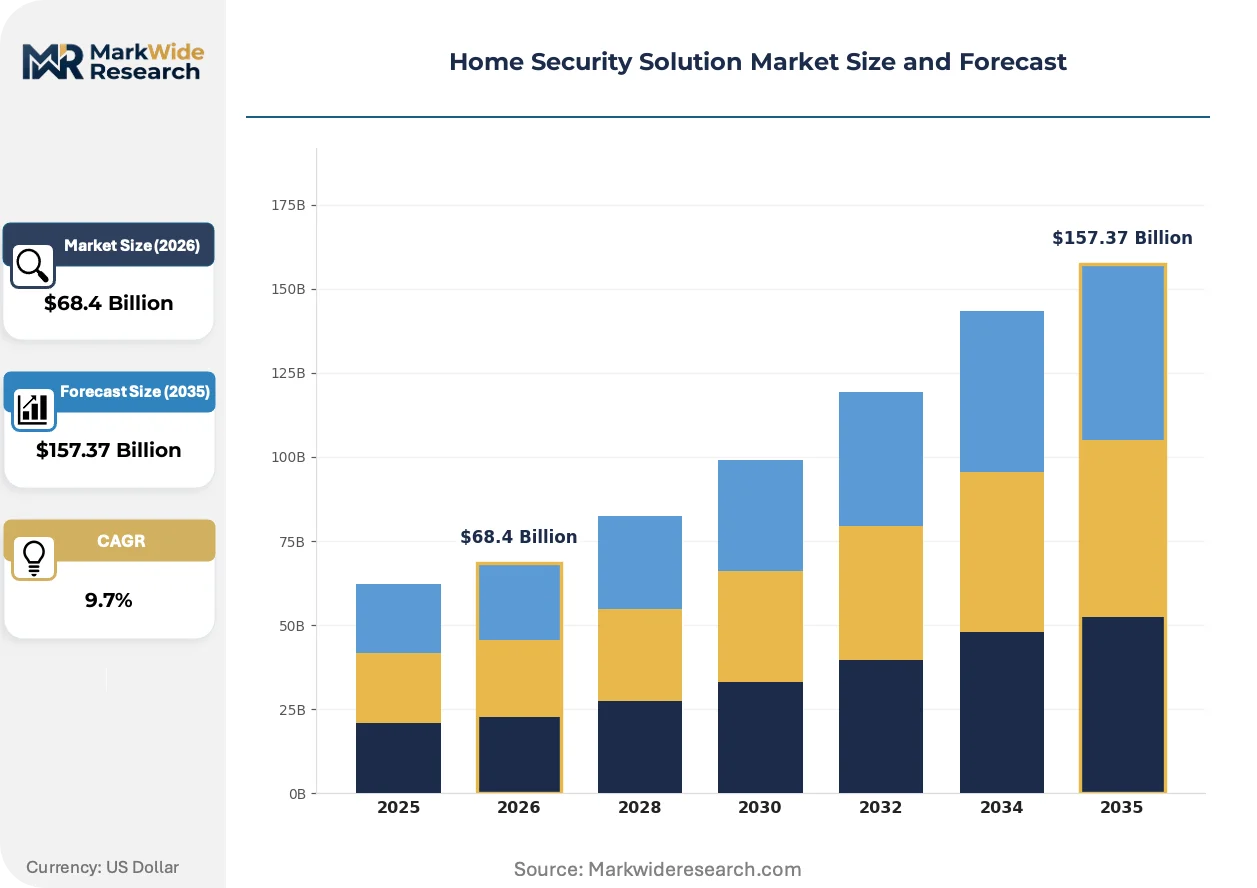
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $157.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alarm Systems, Video Surveillance, Access Control, Motion Detectors, Smart Locks Technology: Wireless, Wired, Cloud-Based, AI-Powered, Biometric Application: Residential Houses, Vacation Homes, Apartments, Condominiums, Smart Villas End User: Homeowners, Property Managers, Real Estate Developers, Security Service Providers |
| Companies Covered | Cove Security, Frontpoint Home Security, ADT, Ring Alarm, Brinks Home Security, SimpliSafe, Alder Security, Abode, Vivint Smart Home, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Security Solution Market Strategic Shifts & Innovations
The market's evolution is characterized by a fundamental shift from passive, reactive alarm systems to proactive, intelligent ecosystems. This transformation is driven by on-device processing capabilities and shaped by new global standards for algorithmic transparency and data security.
Edge AI, which embeds processing directly into devices like cameras and video doorbells, is a key technology. Residential users are adopting systems with on-device analytics to gain more relevant alerts and reduce the volume of false notifications from environmental triggers. This on-device intelligence is consolidating the value proposition around proactive event detection, shifting focus from simple motion alerts to specific, verified incidents.
Regulations such as the EU AI Act are establishing new global benchmarks for product development. The act mandates risk assessments and transparency for AI systems, compelling manufacturers to document and validate their algorithms to maintain access to the European market. Video surveillance products utilizing advanced analytics are most impacted, requiring design adjustments to align with new compliance obligations for accuracy and fairness.
A significant demand-side shift is occurring toward subscription-based service models. This "security-as-a-service" approach, which bundles hardware with professional monitoring, cloud video storage, and access to advanced AI features, is gaining favor over the traditional one-time hardware sale. The trend is most pronounced in North America and Western Europe, where consumers show a strong propensity for recurring payment models.
Home Security Solution Market Segmentation
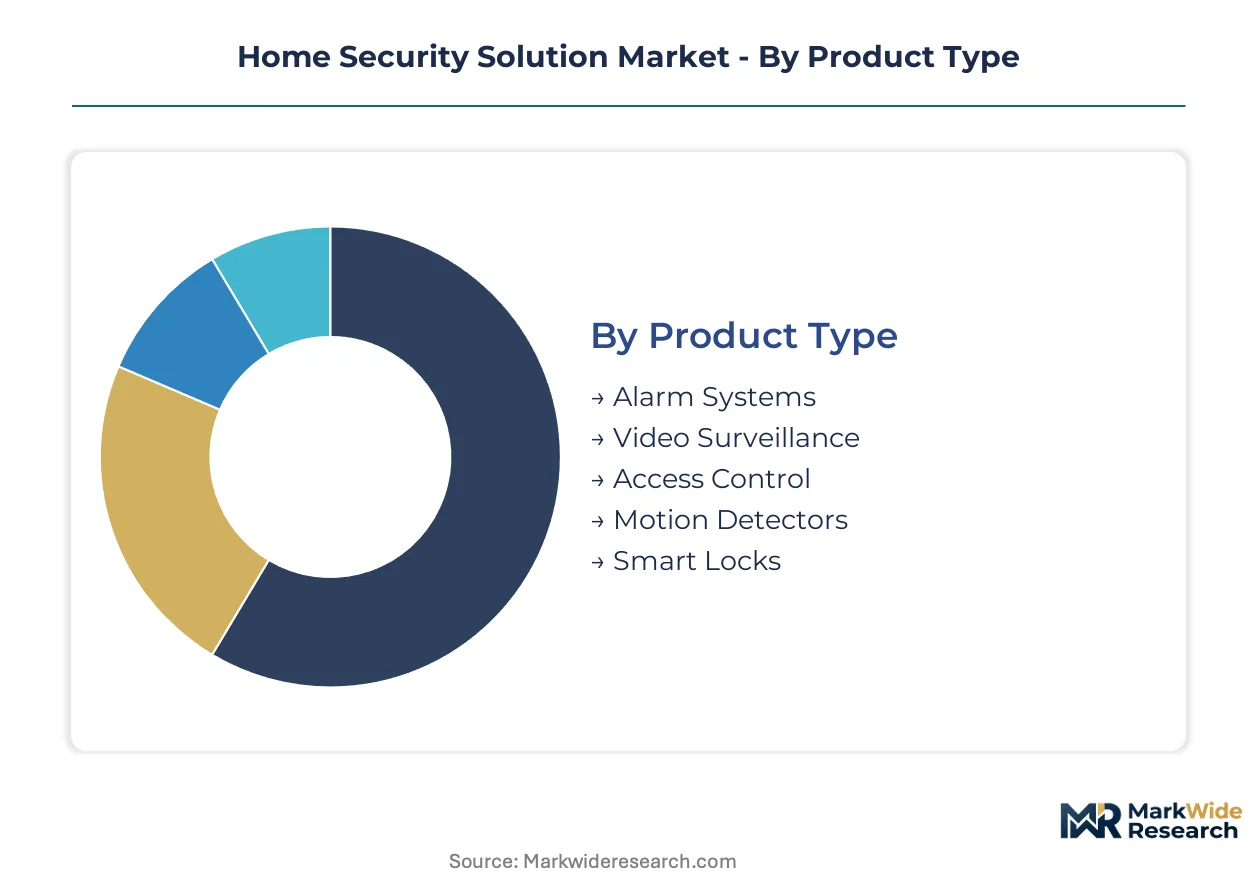
The home security solution market is segmented to reflect the diverse product offerings, underlying technologies, varied application environments, and distinct end-user profiles. This detailed breakdown helps in understanding demand patterns and identifying specific areas of innovation and market concentration within the industry.
Product Type:
The market for home security solutions is delineated by the core functionalities and hardware specifications of its offerings.
- Video Surveillance:These systems integrate cameras with recording and monitoring capabilities, often utilizing AI for advanced analytics like person detection and false alarm reduction. Demand concentrates in urban areas of the United States due to high consumer technology adoption and increasing property ownership rates.
- Smart Locks:Smart Locks provide keyless entry and remote access control, integrating with broader smart home ecosystems through protocols like Z-Wave or Wi-Fi. Uptake is significant in residential applications across Western Europe, driven by convenience and enhanced security features.
- Alarm Systems:These traditional systems detect unauthorized entry using sensors and trigger audible alerts or transmit signals to monitoring centers.
- Access Control:Solutions managing and restricting entry to properties through methods like keypads, biometric scanners, or remote systems.
- Motion Detectors:Devices, often using passive infrared (PIR) technology, sense movement within a designated area to trigger alarms or alerts.
Alarm Systems lead on scale; Smart Locks lead on momentum.
Technology:
Segmentation by technology highlights the underlying communication methods and processing capabilities that define system performance.
- AI-Powered:AI-Powered technologies embed advanced algorithms into devices for features such as facial recognition, object detection, and false alarm reduction. These solutions are gaining traction in smart villas, where integrated systems demand sophisticated, proactive security.
- Wireless:Wireless technologies utilize radio frequencies like Wi-Fi or Z-Wave for communication between sensors, cameras, and central hubs, offering flexible installation. Adoption is widespread across all residential segments, driven by ease of deployment and minimal structural intrusion.
- Wired:These systems rely on physical cabling for power and data transmission, often preferred for their robustness and resistance to interference.
- Cloud-Based:Solutions that store data and perform processing on remote servers, enabling remote access and management of security systems.
- Biometric:Technologies that use unique biological characteristics, such as fingerprints or facial scans, for secure identification and access control.
Wireless solutions dominate adoption, while AI-Powered technologies represent the fastest-growing trajectory.
Application:
The market is segmented by the specific residential environments where these security solutions are deployed, reflecting diverse user needs.
- Smart Villas:Smart Villas integrate comprehensive security with home automation, often featuring bespoke systems tailored to luxury properties. This segment shows pronounced growth in affluent markets like the United States and the Middle East.
- Residential Houses:Residential Houses represent the largest application segment, encompassing single-family homes requiring scalable and often professionally monitored security systems. This category drives significant volume in established markets like the UK and Germany.
- Vacation Homes:Properties used seasonally or periodically, often requiring remote monitoring and management capabilities.
- Apartments:Multi-dwelling units where security solutions need to address shared entry points and individual unit protection.
- Condominiums:Individually owned units within a larger building, often benefiting from centralized building security alongside private unit systems.
Residential Houses drive the largest volume, with Smart Villas exhibiting significant growth.
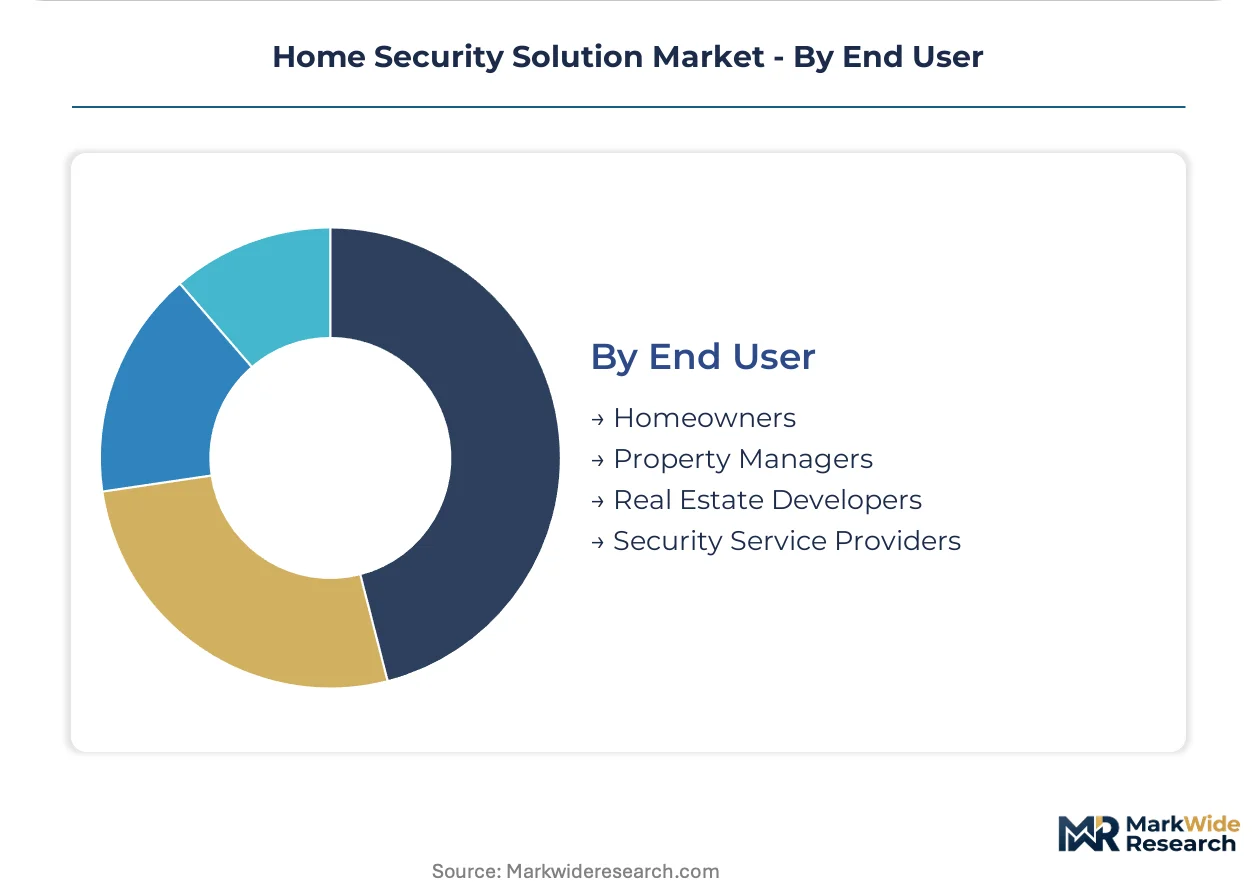
End User:
Segmentation by end user identifies the primary purchasers and beneficiaries of home security solutions, influencing distribution channels.
- Homeowners:Homeowners directly purchase and manage security systems for their primary residences, often seeking solutions that offer ease of use and remote access. This group forms the largest customer base in North America, motivated by property protection and insurance incentives.
- Security Service Providers:Security Service Providers offer comprehensive monitoring, installation, and maintenance services, bundling hardware with recurring subscriptions. They play a critical role in market access and professional system deployment, particularly in the United States.
- Property Managers:Entities responsible for overseeing residential properties, often implementing security systems for multiple units or complexes.
- Real Estate Developers:Companies that build and sell new residential properties, frequently integrating security solutions as standard features.
Homeowners constitute the primary demand base, while Security Service Providers influence broader market trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The home security solution market initially scaled in regions with high property ownership and early technology adoption. Early systems focused on traditional alarm functionalities, evolving rapidly with wireless communication and smart home integration. This foundational development shaped distinct regional approaches to security infrastructure and consumer preferences.
United States
The United States anchors significant demand, driven by high property ownership rates and consumer technology adoption. FCC standards govern wireless device emissions, while state-level privacy laws influence data handling. Innovation hubs like Silicon Valley develop advanced AI-powered analytics and integrated smart home ecosystems.
United Kingdom
Homeowners in the United Kingdom actively adopt security systems, motivated by insurance premium discounts for professionally monitored properties. UK data protection regulations influence personal data handling for cloud-based services. Urban centers like London see strong uptake of subscription-based security-as-a-service models.
Germany
Germany represents a substantial market for residential security systems, particularly in traditional houses. The EU's GDPR and upcoming EU AI Act mandate stringent data privacy and algorithmic transparency. Industrial regions such as Bavaria emphasize robust, wired systems for enhanced security and reliability.
China
China's home security market expands with rapid urbanization and a growing middle class seeking integrated smart solutions. Hardware must comply with national GB standards for interoperability and safety, alongside data localization requirements. Manufacturing hubs like Shenzhen are critical for producing affordable, mobile-first security hardware.
United Arab Emirates
The United Arab Emirates exhibits pronounced growth in the smart villas segment, where integrated security systems are standard for luxury properties. Local regulations prioritize data security for cloud-based services and smart home ecosystems. Dubai's advanced infrastructure projects drive demand for AI-powered analytics and sophisticated access control.
Home Security Solution Market Key Industry Players
The competitive structure tilts toward integrated service providers offering comprehensive solutions. Established players leverage extensive installation networks and brand trust, while newer entrants focus on deeply integrated smart home ecosystems. Key archetypes include traditional monitoring giants, smart home integrators, and agile DIY system providers. Companies pursue portfolio diversification and strategic partnerships to expand their service offerings and market reach.
Within the established service provider tier, ADT exemplifies a legacy of professional installation and monitoring services. Vivint Smart Home represents the archetype of a deeply integrated smart home ecosystem specialist, extending beyond security into automation and energy management. Meanwhile, SimpliSafe occupies a position among the agile DIY system providers, catering to consumers seeking flexible, self-installed security solutions with optional professional monitoring. These companies collectively illustrate the diverse approaches to market penetration and customer engagement.
| Leading Market Players |
|---|
| Cove Security |
| Frontpoint Home Security |
| ADT |
| Ring Alarm |
| Brinks Home Security |
| SimpliSafe |
| Alder Security |
| Abode |
| Vivint Smart Home |
| Others |
Cost & Logistics Intelligence
Vertical integration in the home security market, particularly for service providers controlling installation and monitoring, anchors both supply position and pricing power. This integration allows companies to manage service quality and offer bundled solutions that command premium pricing.
Pricing Analysis
Bundled security-as-a-service models dominate pricing, combining hardware, professional monitoring, and advanced AI features into recurring subscriptions. Price differentiation stems from the inclusion of specific AI-powered analytics and the extent of professional monitoring services. Pricing softness affects basic DIY systems due to intense competition and consumer access to affordable hardware. Homeowners seeking basic property protection exhibit higher price sensitivity, while smart villa developers prioritize comprehensive, integrated solutions over cost.
Supply Chain Analysis
Workforce availability in manufacturing hubs like China significantly influences the supply chain for home security hardware. The industry depends on a consistent supply of semiconductors, sensors, and wireless communication modules. Geopolitical tensions impacting component sourcing from Asia represent a structural supply chain risk. Distribution runs primarily through a dual model of professional installers for complex systems and direct-to-consumer channels for DIY solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, leveraging lower hardware manufacturing costs in China against the premium pricing for integrated services in North America and Western Europe.
For Market Incumbents: Lock in existing customer bases through expanded subscription offerings that integrate adjacent services like energy management and elder care monitoring. This defends against agile DIY providers and regulatory burdens from evolving data privacy laws. Invest in edge AI R&D to enhance on-device processing capabilities, reducing reliance on cloud infrastructure for sensitive data.
For New Entrants and Emerging Players: Enter via underserved emerging markets in Southeast Asia and Latin America with affordable, mobile-first security solutions. This targets underpenetrated homeowner segments seeking basic, accessible protection. Focus go-to-market strategies on subscription bundles that offer essential monitoring and cloud storage, leveraging local mobile payment ecosystems.
For Investors and Strategic Acquirers: Roll-up economics work for regional security service providers because fragmented local markets allow for consolidation of customer bases and operational efficiencies. Focus on acquiring companies with strong local installation networks and established subscription revenue streams. The sustained growth in subscription-based service models serves as a key signal for long-term viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI-Powered Analytics | Enhances system intelligence, reduces false alarms, and creates new value for homeowners. |
| Expand Subscription Service Offerings | Secures recurring revenue streams and improves customer lifetime value for security providers. |
| Invest in Edge AI Development | Addresses consumer data privacy concerns by enabling on-device processing without cloud reliance. |
| Target Emerging Market Penetration | Captures new customer segments in rapidly urbanizing regions with affordable solutions. |
| Acquire Cybersecurity Expertise | Strengthens defense against evolving cyber threats and ensures compliance with new regulations. |
Research Approach
Coverage spans North America, Europe, Asia-Pacific, and the Middle East, with primary inputs from each region. The analysis combines extensive primary interviews with security system integrators, AI algorithm developers, regulatory compliance officers, and property developers. Secondary validation draws from government regulations like the EU AI Act, FCC standards, GB standards, and industry association reports, along with company annual reports. Both bottom-up and top-down triangulation methods ensured data consistency.
The forecast framework models market dynamics at a granular level across product type, technology, application, end-user, and regional regulatory environment. Compound annual growth rates were derived by analyzing historical trends and projecting future market drivers over the projection horizon. Industry-specific forecast inputs included consumer technology adoption rates and evolving regulatory compliance costs.
The model holds under current macroeconomic stability and a consistent regulatory trajectory; deviation in geopolitical tensions or significant shifts in data privacy legislation would shift market outcomes. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
Airport Security Market
Security and Surveillance
Security Services Market
Security and Surveillance
Security Intelligence Market
Security and Surveillance
Perimeter Security Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Smart Security in Healthcare Market
Security and Surveillance
Air Cargo Security Equipment Market
Security and Surveillance
Burglar Alarm Systems Market
Security and Surveillance
Intelligent Fencing Market
Security and Surveillance
Global Law Enforcement Software Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Global School and Campus Security Market
Security and Surveillance
Global Wireless Monitoring and Surveillance Market
Security and Surveillance
Integrated Security Services Market