
 Split Air Conditioning Systems Market | 2026-2036
Split Air Conditioning Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Split Air Conditioning Systems Market Intelligence
Rising procurement from large-scale property developers and facility management firms is redrawing the competitive landscape, shifting focus from individual consumer sales. Daikin Industries leverages its deep portfolio in inverter and VRF technologies to secure large commercial contracts. Carrier sustains its market position through a robust distribution network and established relationships in the North American commercial building sector.
A split air conditioning system comprises an outdoor unit with a compressor and an indoor air-handling unit connected by refrigerant lines. This configuration allows for zoned climate control without requiring extensive ductwork. Wall-mounted units continue to dominate the residential application segment. Inverter technology is rapidly displacing non-inverter models due to its superior energy efficiency, a key purchasing criterion for both commercial and residential end users.
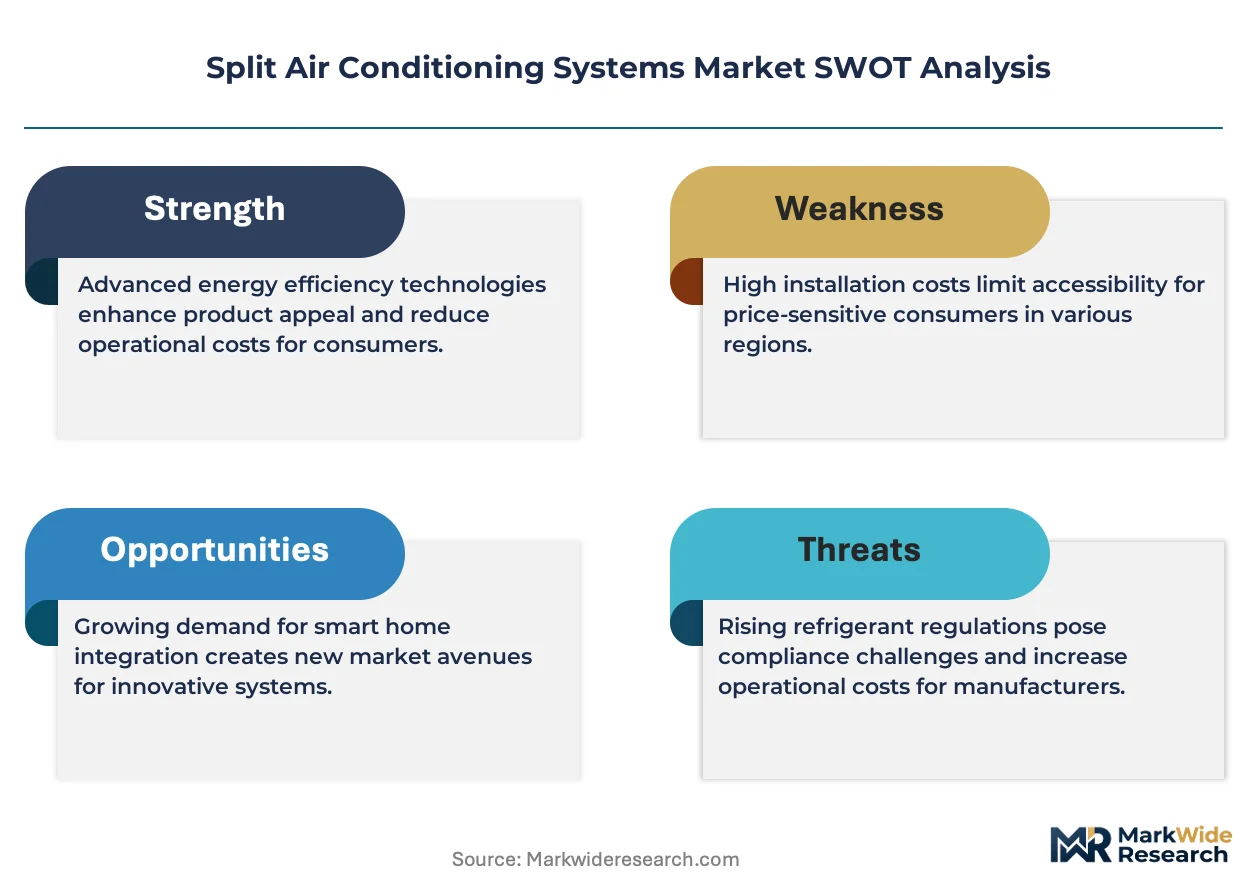
Regulatory frameworks, including the US EPA's refrigerant management programs and the EU's F-Gas Regulation, mandate a shift away from high-GWP refrigerants. These policies directly influence product design and component sourcing for manufacturers like Mitsubishi Electric and LG Electronics. The critical decision for market participants involves balancing investment in next-generation refrigerant R&D against regional variations in energy efficiency labeling standards.
Market Dynamics
The imperative to phase out high-GWP refrigerants under global environmental protocols is the central force shaping the split air conditioning systems market. This pressure compels a fundamental redesign of core system components, from compressors to heat exchangers, across all product tiers.
Growth Catalysts
- Regulatory Mandates:The EU's F-Gas Regulation accelerates the replacement cycle in the commercial sector, creating demand for systems compliant with lower GWP refrigerant standards, particularly in data center and retail applications.
- Urbanization in India:Rapid urban development and expanding middle-class disposable income in India are creating a surge in first-time buyers for residential wall-mounted split air conditioning units.
- Inverter Technology Adoption:Superior energy efficiency makes inverter-based systems a primary choice for both commercial and residential end-users, driven by a focus on reducing operational electricity costs.
Market Restraints
- High R&D Costs:The significant investment required to research, develop, and commercialize systems using next-generation low-GWP refrigerants, such as HFOs, creates a high barrier to entry and slows adoption.
- Component Supply Concentration:A heavy reliance on a few suppliers in East Asia for critical components like high-efficiency inverter compressors exposes the global supply chain to geopolitical and logistical risks.
- Fragmented Efficiency Standards:Divergent energy efficiency labeling programs, such as SEER in the United States and different metrics in other regions, increase design complexity and manufacturing costs for global OEMs.
Strategic Opportunities
- Smart Home Integration:Embedding IoT connectivity and AI-driven predictive maintenance capabilities into split systems opens new revenue streams through subscription-based services and enhanced energy management for homeowners.
- Government Incentives:Financial incentives for high-efficiency home improvements, such as tax credits available under the US Inflation Reduction Act (IRA), can spur the replacement of older, inefficient air conditioning units.
- Market Penetration in Southeast Asia:Rising electrification rates and growing household incomes in countries like Vietnam and Indonesia present significant untapped markets for residential split AC systems.
Industry Challenges
- Technician Skill Gaps:A shortage of HVAC professionals trained to safely handle and service systems using mildly flammable or higher-pressure next-generation refrigerants impedes market transition and deployment.
- Compliance Complexity:Navigating disparate and evolving regional refrigerant phase-out schedules and documentation requirements, such as those managed by the US EPA, creates a significant administrative burden.
- Retrofitting Older Buildings:Integrating modern, ductless split systems into existing building stock with legacy HVAC infrastructure often presents significant architectural and installation cost challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Split Air Conditioning Systems Market |
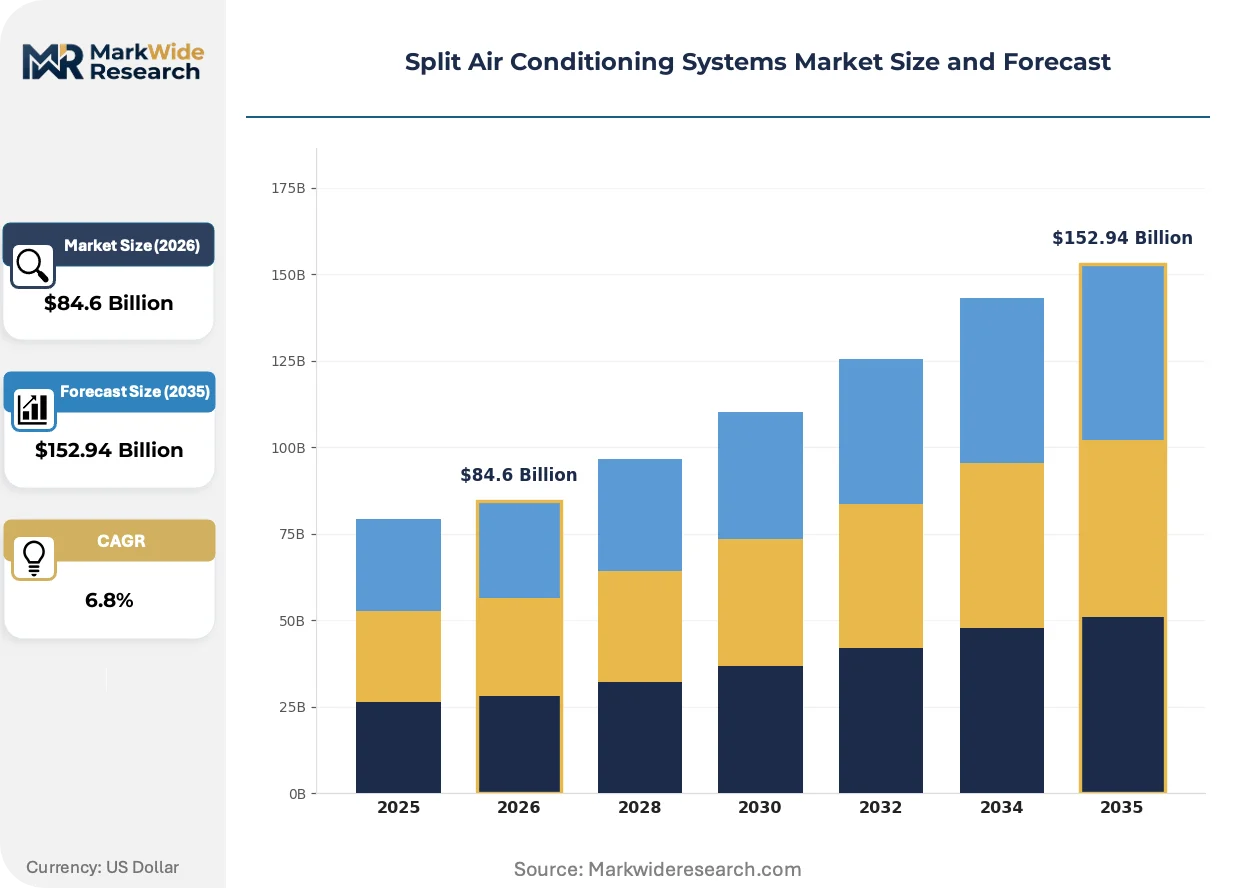
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Floor-Standing, Ceiling Cassette, Ducted, Ceiling Suspended Technology: Inverter, Non-Inverter, Variable Refrigerant Flow, Smart AC, Dual Compressor Application: Residential Buildings, Commercial Complexes, Educational Institutes, Data Centers, Government Establishments End User: Property Developers, Facility Management, Hospitality Operators, Retail Stores, Corporate Offices |
| Companies Covered | Trane Technologies, Gree Electric Appliances, Daikin Industries, Fujitsu General, Panasonic, Mitsubishi Electric, LG Electronics, Lennox International, Carrier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Split Air Conditioning Systems Market Strategic Shifts & Innovations
Product development is increasingly defined by the twin pressures of decarbonization and digitalization. This is driving a new generation of split AC systems designed for intelligent operation, regulatory compliance, and superior energy performance throughout their lifecycle.
Microchannel heat exchangers are a key component innovation designed to improve thermal transfer efficiency using a smaller refrigerant charge. Commercial real estate developers and operators of high-density residential buildings are the primary adopters, seeking to reduce both operational costs and system footprint. This technology is miniaturizing the physical size of outdoor condenser units, enabling more flexible installation options in space-constrained urban environments.
The US EPA's phasedown of HFC refrigerants, mandated by the AIM Act, is forcing a rapid product line transition. This regulatory action compels manufacturers to shift their entire portfolios toward lower-GWP alternatives like R-32 and R-454B. The residential and light commercial segments are most impacted, necessitating a complete redesign of systems to accommodate the different thermodynamic and safety properties of these new refrigerants.
A notable behavioral shift is occurring from transactional equipment sales toward long-term service-oriented contracts that bundle maintenance and performance monitoring. This trend is disrupting the traditional sales model in the commercial sector, where facility management companies and property portfolios now often procure systems directly. This purchasing pattern is most evident in North American and European commercial real estate, where energy efficiency is a core operational and investment metric.
Split Air Conditioning Systems Market Segmentation
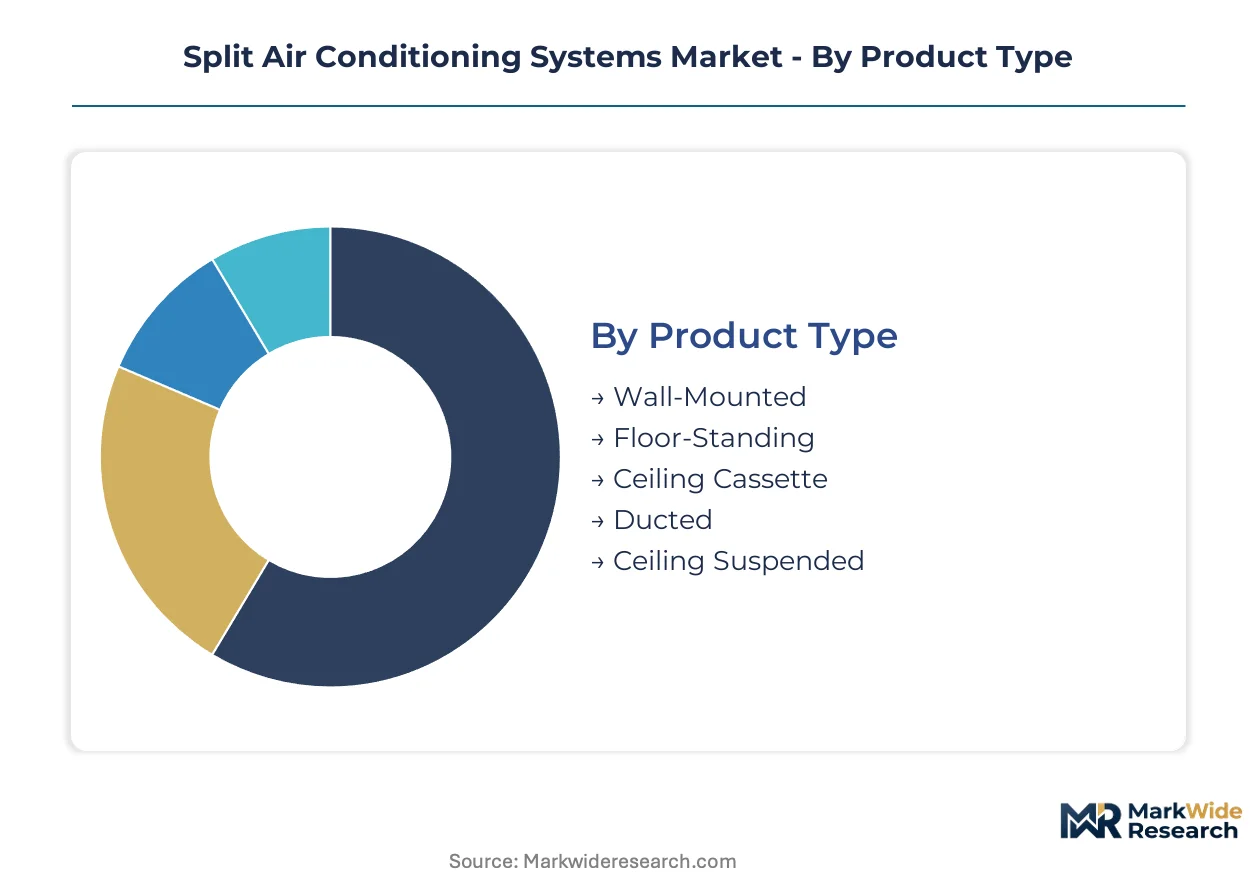
The segmentation of the split air conditioning systems market highlights distinct demand patterns and procurement strategies across various product types, technologies, applications, and end-users. Understanding these divisions is essential for manufacturers to tailor product development and market penetration efforts effectively. Each segment reflects unique operational requirements and investment priorities, influencing system design and refrigerant choice.
Product Type:
Margin pools within this category often sit with specialized commercial systems requiring complex installation and higher capacity. These systems cater to specific architectural and functional demands, driving premium pricing for advanced features and custom solutions.
- Wall-Mounted:These units consist of an indoor air handler installed high on a wall, connected to an outdoor compressor unit. Demand concentrates in residential buildings and small commercial spaces in India due to ease of installation and cost-effectiveness for first-time buyers.
- Ducted:Ducted systems distribute conditioned air through a network of ducts to multiple rooms or zones from a single outdoor unit. Commercial complexes and high-end residential projects in North America increasingly adopt these for discreet integration and uniform climate control.
- Floor-Standing:These units are designed to be placed on the floor, offering a powerful cooling solution for larger rooms or open-plan areas.
- Ceiling Cassette:Ceiling cassette units are installed flush within the ceiling, providing four-way airflow for even distribution in commercial offices and retail environments.
- Ceiling Suspended:Suspended from the ceiling, these units are suitable for spaces with high ceilings or where wall and floor space is limited, common in workshops or larger retail outlets.
The dominant share belongs to Wall-Mounted units, while Ducted systems are closing the gap fastest in terms of commercial value.
Technology:
The application focus heavily influences technology adoption, with energy efficiency and precise climate control driving the selection of advanced systems. Regulatory pressures from the EU's F-Gas Regulation also compel shifts towards lower GWP refrigerants, impacting technology design.
- Inverter:Inverter technology allows the compressor to vary its speed, optimizing energy consumption and maintaining a consistent temperature. Residential and commercial users globally prioritize these systems for lower operational electricity costs, especially with rising energy prices in Europe.
- Variable Refrigerant Flow:VRF systems connect multiple indoor units to a single outdoor unit, offering individual zone control and simultaneous heating and cooling capabilities. Large-scale property developers and facility management firms in Japan and China leverage VRF for efficient climate management in multi-story buildings.
- Non-Inverter:These traditional systems operate at a fixed compressor speed, cycling on and off to maintain temperature. They remain a budget-friendly option for price-sensitive residential buyers in emerging markets.
- Smart AC:Integrating IoT connectivity, smart AC systems allow remote control, scheduling, and energy monitoring via mobile applications. Homeowners in the United States and Germany adopt these for enhanced convenience and energy management.
- Dual Compressor:Featuring two compressors, these systems offer enhanced performance and redundancy, often found in larger commercial or industrial applications where reliability is critical.
Inverter technology leads in market penetration, while Variable Refrigerant Flow systems show the steepest expansion trajectory in commercial applications.
Application:
Customer type dictates the scale and complexity of split AC system deployments within this segment. Residential buyers focus on individual unit performance, while commercial entities prioritize system-wide efficiency and regulatory compliance.
- Residential Buildings:This segment includes single-family homes, apartments, and condominiums, primarily utilizing wall-mounted and small ducted split systems. Urbanization and expanding middle-class disposable income in India are creating a surge in first-time residential buyers.
- Data Centers:Critical infrastructure facilities requiring precise temperature and humidity control to protect sensitive IT equipment. Operators of data centers in the United States and Ireland demand high-efficiency, reliable systems to manage extreme heat loads.
- Commercial Complexes:Multi-story office buildings, shopping malls, and mixed-use developments that require robust and scalable climate control solutions.
- Educational Institutes:Schools, colleges, and universities installing split systems for comfort and improved learning environments, often driven by government funding in countries like South Korea.
- Government Establishments:Public sector buildings, administrative offices, and defense facilities that procure systems based on long-term reliability and energy efficiency standards.
Residential Buildings represent the largest volume segment, with Data Centers expanding most quickly due to critical cooling requirements.
End User:
Supply concentration for end-users highlights the growing influence of large-scale procurement entities. These firms often dictate purchasing terms and demand advanced, integrated solutions, shifting focus from individual consumer sales.
- Property Developers:Large-scale real estate companies involved in constructing new residential, commercial, or mixed-use projects. These developers in China and the UAE engage in bulk procurement of systems for entire buildings or complexes.
- Facility Management:Firms responsible for the upkeep and operation of commercial and institutional buildings, managing HVAC systems as part of broader operational contracts. These firms in the United Kingdom and France increasingly seek long-term service agreements for performance monitoring.
- Hospitality Operators:Hotels, resorts, and restaurants that require comfortable indoor environments for guests and staff. These operators in Thailand prioritize quiet operation and energy efficiency for guest satisfaction.
- Retail Stores:Commercial establishments, from small boutiques to large department stores, needing effective climate control for customer comfort and product preservation.
- Corporate Offices:Business workplaces that install split AC systems to ensure a productive and comfortable environment for employees.
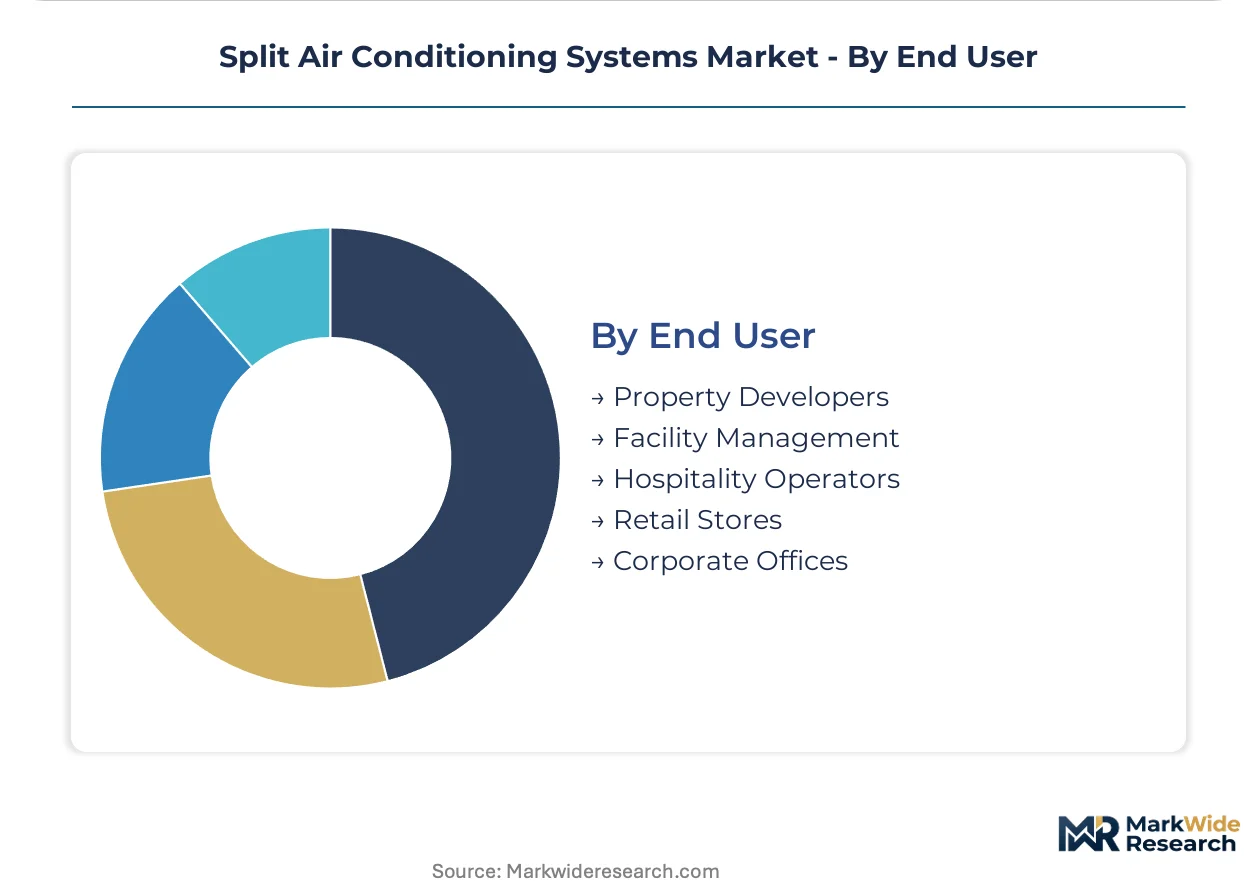
Property Developers account for significant initial installations, while Facility Management firms are gaining share fastest through long-term maintenance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and South Korean manufacturers actively export advanced split air conditioning systems to growing markets in India and North America. The global market is expanding due to urbanization, regulatory shifts, and energy efficiency demands. These dynamics influence product development and regional adoption patterns across key geographies.
India
Urbanization and expanding middle-class disposable incomes are driving significant demand for residential wall-mounted units in India. Government initiatives supporting infrastructure development further stimulate market growth through new construction projects. Major metropolitan areas like Delhi-NCR and Mumbai exhibit high procurement rates for cost-effective split AC systems.
United States
Data centers and residential replacement cycles generate substantial demand for high-efficiency split systems across the United States. The US EPA's AIM Act mandates a rapid shift to lower-GWP refrigerants, reshaping product offerings. States like California and Texas are seeing increased adoption, driven by energy efficiency incentives under the Inflation Reduction Act.
Germany
The commercial sector in Germany increasingly procures split systems for energy efficiency and regulatory compliance. The EU's F-Gas Regulation accelerates the replacement of high-GWP refrigerant systems, particularly in retail and data center applications. Cities such as Munich and Frankfurt show strong demand for advanced, inverter-based units in new and retrofitted office buildings.
China
Large-scale property developers in China are major consumers of VRF and ducted split systems for commercial and residential projects. National energy efficiency standards, overseen by the MEE, influence product design and market availability. Manufacturing and demand clusters in the Yangtze River Delta drive significant production and adoption of diverse AC technologies.
Japan
Japan exhibits high adoption of advanced VRF systems for precise climate control in multi-story commercial and residential buildings. METI's stringent energy efficiency targets compel manufacturers to innovate in inverter and heat pump technologies. Urban centers like Tokyo and Osaka lead in deploying sophisticated split AC solutions, integrating smart home functionalities.
Split Air Conditioning Systems Market Key Industry Players
Player mix skews toward established global players dominating the commercial segment, alongside a fragmented base of regional specialists serving local residential markets. The market exhibits a tiered structure, with a few large multinational corporations controlling advanced technology segments and setting industry benchmarks. Key archetypes include global technology leaders focused on inverter and VRF systems, and regional market specialists with strong distribution networks. Competitive moves center on portfolio diversification into lower-GWP refrigerants and strategic partnerships to expand geographic reach and secure large-scale property developer contracts.
Within the global technology leader archetype, Daikin Industries exemplifies deep expertise in inverter and Variable Refrigerant Flow (VRF) technologies, anchoring its strong position in securing large commercial contracts worldwide. Carrier, conversely, occupies a significant market position through its robust distribution network and established relationships, particularly within the North American commercial building sector. Mitsubishi Electric also sits within this tier, representing manufacturers compelled to redesign entire product lines due to evolving refrigerant regulations and increasingly stringent energy efficiency standards across various global regions.
| Leading Market Players |
|---|
| Trane Technologies |
| Gree Electric Appliances |
| Daikin Industries |
| Fujitsu General |
| Panasonic |
| Mitsubishi Electric |
| LG Electronics |
| Lennox International |
| Carrier |
| Others |
Cost & Logistics Intelligence
Four-month lead times for high-efficiency inverter compressors impact system pricing, reflecting concentrated East Asian manufacturing and limited buffer stock.
Pricing Analysis
The technology-generation pricing gap differentiates non-inverter systems as budget-friendly options from premium inverter and VRF models. Per-unit transactional pricing dominates residential sales, while commercial projects often use value-based contracts for large-scale deployments. Price differentiation stems from superior energy efficiency ratings and advanced features like smart home integration. Pricing pressure intensifies due to significant R&D investments in low-GWP refrigerants. Residential buyers in emerging markets exhibit high price sensitivity, contrasting with data center operators who prioritize system reliability over initial cost.
Supply Chain Analysis
Reliance on East Asian foundries for high-efficiency inverter compressors creates a critical chokepoint in the split AC supply chain. Component manufacturing centers in China, Japan, and South Korea, drawing from global refrigerant chemical suppliers. A structural risk involves single-source vulnerability for advanced microchannel heat exchangers, impacting global availability. Distribution runs through established wholesale networks for residential units, while commercial systems often involve direct procurement by property developers and facility management firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The split air conditioning market presents a significant service-attach opportunity, with subscription-based predictive maintenance and energy management services expanding faster than core hardware sales.
For Market Incumbents:Consolidate R&D efforts on next-generation low-GWP refrigerants to mitigate regulatory obsolescence risk from the EU's F-Gas Regulation. Deepen vertical integration into high-efficiency inverter compressor production to control critical component supply. Expand service-oriented contracts for commercial clients to counter transactional sales commoditization. Investment in training programs for technicians handling mildly flammable refrigerants is essential to address skill gaps.
For New Entrants and Emerging Players:Unaddressed demand for AI-driven predictive maintenance in residential smart homes offers a significant service-layer gap for new entrants. Target market penetration in Southeast Asia, leveraging rising electrification rates for residential wall-mounted units. Offer bundled solutions combining energy-efficient hardware with subscription-based energy monitoring and remote diagnostics. Focus on ease of installation and user-friendly mobile interfaces to differentiate from established players.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across the low-GWP refrigerant R&D sub-segment, driven by regulatory compliance mandates. Long-term viability remains strong, anchored by global urbanization and climate control needs. Seek acquisition targets with deep expertise in next-generation refrigerants or advanced microchannel heat exchanger technology. Watch for accelerated product line transitions in the US residential market as a signal of broader regulatory impact.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in R-32 and R-454B product lines | Ensures compliance with US EPA's AIM Act and EU's F-Gas Regulation. |
| Develop AI-driven smart AC platforms | Captures new revenue streams through subscription-based energy management for homeowners. |
| Expand service contracts for commercial clients | Secures long-term relationships with facility management firms in Europe. |
| Acquire microchannel heat exchanger specialists | Mitigates supply chain concentration risks for critical components from East Asia. |
| Establish technician training for new refrigerants | Addresses technician skill gaps, facilitating market transition to lower-GWP systems. |
Research Approach
Cross-validation between primary interviews with HVAC engineers and secondary regulatory reports anchors the qualitative findings for this market analysis. Insights were gathered from property developers, facility managers, and refrigerant chemical suppliers. Secondary validation drew from US EPA documents, EU F-Gas Regulation texts, and national energy efficiency standards. A bottom-up and top-down triangulation approach ensured data consistency and robustness.
Sensitivity analysis informed the forecast framework, evaluating the impact of varying regulatory compliance timelines and raw material costs on market trajectories. The analytical framework modeled segmentation across product type, technology, application, end-user, and refrigerant type over the projection horizon. Compound annual growth rates were derived from historical data extrapolation and expert consensus. Urbanization rates in India and energy price volatility in Europe served as key forecast inputs.
Forecasts assume regulatory continuity in US EPA and EU F-Gas regimes; material policy shifts would require re-modeling. Unforeseen geopolitical events or accelerated technological breakthroughs in cooling could revise projections. Practitioners should keep alternative scenarios live as global refrigerant policies and energy prices evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Aeration System Market
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
Roof Insulation Market
HVAC Systems
North America Scrubber System Market
HVAC Systems
Marine HVAC Market
HVAC Systems
Global Ductless Heating and Cooling Systems Market
HVAC Systems
Hydronic Control Market
HVAC Systems
Cooling Tower Fans Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
Corrugated Air Duct Market