
 AC Mitigation System Market | 2026-2036
AC Mitigation System Market Size, Share, and Industry Trends Forecast 2026-2036
AC Mitigation System Market Outlook
Modular retrofit kits bundled with remote monitoring capabilities is repositioning procurement patterns for pipeline operators seeking faster deployment cycles. MATCOR, Inc leverages its proprietary anode sled designs to anchor long-term service contracts across midstream infrastructure corridors. Mears Group, Inc sustains geographic dominance through integrated installation crews that control project timelines from engineering through commissioning. Elsyca NV differentiates with simulation-driven design platforms that optimize grounding grid configurations before field deployment.
An AC mitigation system is an engineered assembly of grounding electrodes, polarization cells, solid-state decoupling devices, and conductive coatings that shunt induced alternating current away from cathodically protected steel structures while maintaining DC isolation, typically rated for fault currents exceeding 15 kA and operating frequencies from 50 to 60 Hz. Its primary industrial purpose is preventing AC corrosion and step-touch voltage hazards on pipelines, tanks, and wellheads that parallel high-voltage transmission corridors. Passive Systems occupy the mature volume tier where standardized zinc grounding cells and resistor-capacitor networks serve conventional pipeline crossings with predictable interference profiles. Hybrid Systems represent the fastest-expanding configuration as operators integrate real-time current monitoring with automatic reconfiguration capability to address variable load conditions on shared rights-of-way. Smart Controls within the technology dimension concentrate margin pools through firmware-enabled predictive maintenance and cloud-based threshold alerting that reduces field inspection frequency.
FERC interstate pipeline safety regulations and NACE International standards collectively mandate documented AC interference surveys before new pipeline construction, directly shaping engineering procurement specifications and vendor qualification requirements in the United States. IEEE 80 and IEEE 837 provide the technical foundation for grounding system design and exothermic welding acceptance that governs installation quality across North American utility corridors. Stakeholders must monitor evolving state public utility commission rulings on transmission corridor co-location fees and cathodic protection cost allocation frameworks that will determine project economics for decades.
Market Dynamics
High-voltage transmission corridor expansion across North American oil and gas basins is forcing pipeline operators to retrofit existing cathodic protection infrastructure with engineered AC mitigation assemblies, compressing project timelines and elevating specification complexity for grounding system vendors.
Growth Catalysts
- FERC interstate pipeline safety regulations:Mandated AC interference surveys before new construction are hardening engineering procurement specifications and disqualifying uncertified vendors from bidding on federally regulated projects.
- Permian Basin gathering network density:Overlapping 345 kV transmission buildouts and hydrocarbon infrastructure corridors in West Texas and southeastern New Mexico are generating concentrated demand for hybrid mitigation systems with real-time reconfiguration capability.
- NACE SP0169 standard tightening:Updated cathodic protection coordination requirements are compelling operators to replace passive zinc grounding cells with solid-state decoupling devices rated for higher fault current thresholds.
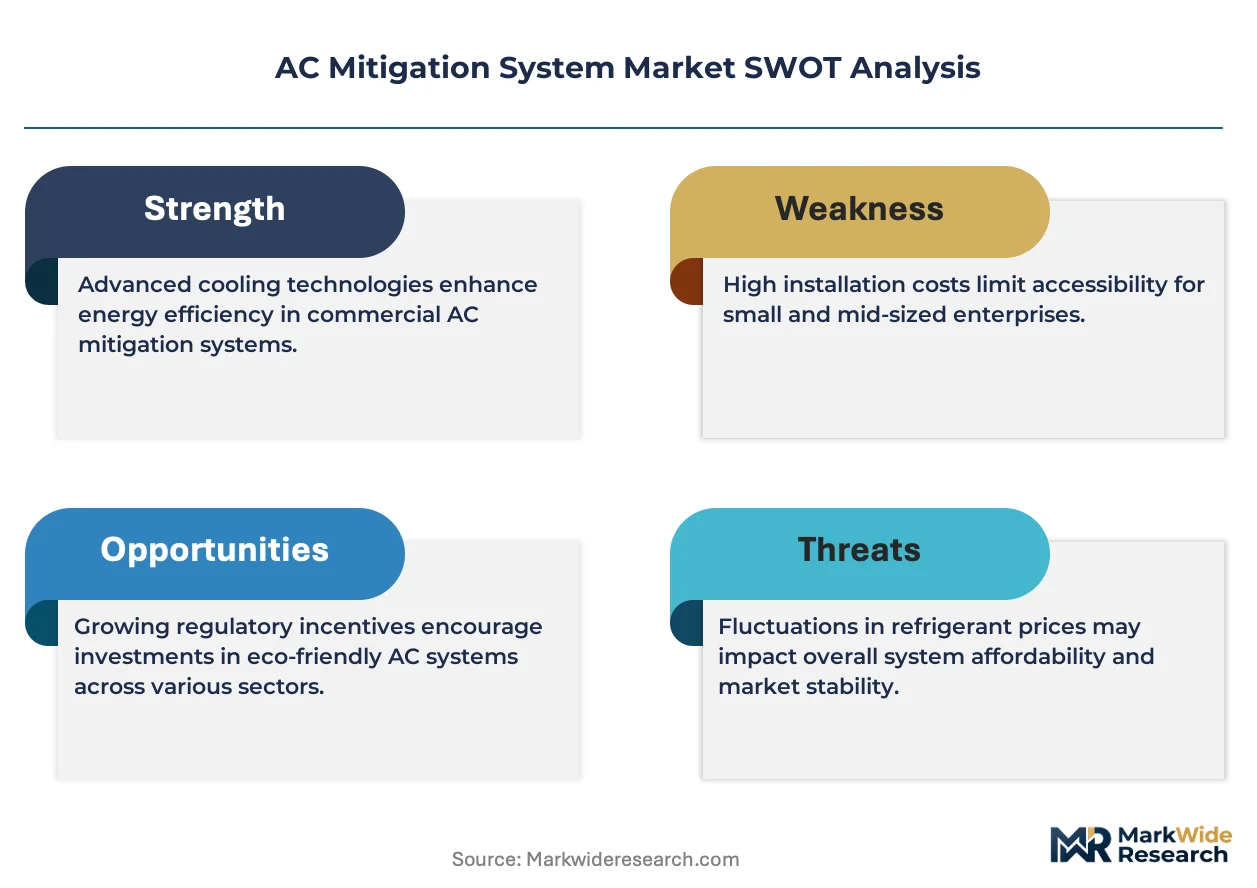
Market Restraints
- Copper and zinc price volatility:Grounding electrode raw material costs fluctuate with commodity cycles, squeezing margins for system integrators locked into fixed-price EPC contracts.
- Specialized welding technician scarcity:IEEE 837-compliant exothermic welding certification programs graduate insufficient technicians to match Permian and Appalachian infrastructure buildout schedules.
- Passive system longevity:Zinc grounding cells with 20-30 year design lives delay replacement cycles in mature pipeline corridors, constraining recurring revenue streams for equipment suppliers.
Strategic Opportunities
- Appalachian Basin electrification:Natural gas pipeline operators in Pennsylvania and Ohio face emerging AC interference from renewable transmission interconnects, creating fresh demand for retrofit assessment services.
- Cloud-based threshold alerting:Firmware-enabled predictive maintenance platforms reduce field inspection frequency for midstream operators managing dispersed rights-of-way across multiple states.
- State public utility commission rulings:Evolving cost allocation frameworks for cathodic protection in shared transmission corridors will determine project economics and vendor contract structures for decades.
Industry Challenges
- Legacy CP system integration:Retrofitting AC mitigation onto decades-old impressed current cathodic protection networks requires custom engineering that extends commissioning timelines and strains project management capacity.
- IEEE 80 grounding grid design complexity:Variable soil resistivity across alluvial floodplains and rocky highland terrain demands site-specific modeling that slows standardization efforts and inflates engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AC Mitigation System Market |
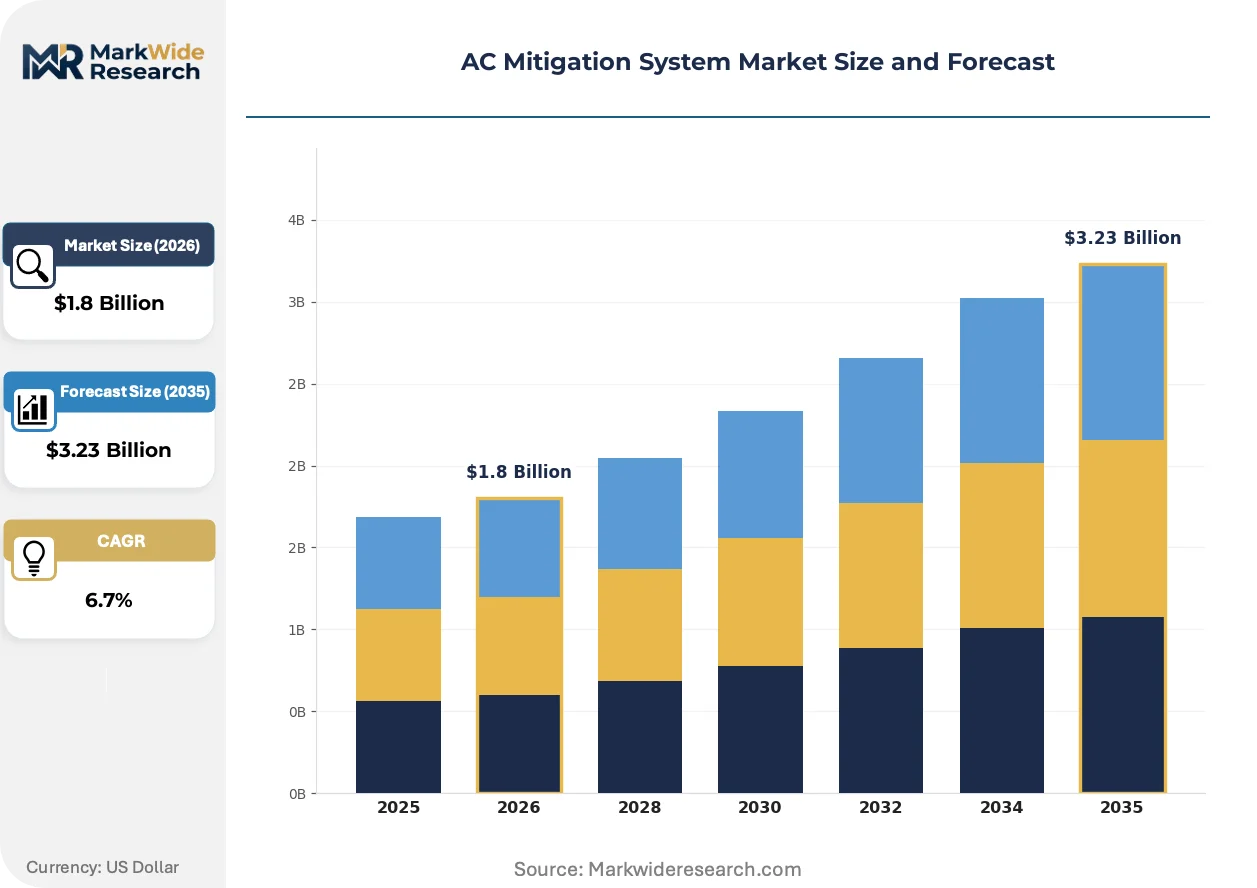
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Systems, Passive Systems, Hybrid Systems, Portable Systems Application: Commercial Buildings, Residential Buildings, Industrial Facilities, Data Centers Technology: Thermal Management, Heat Pumps, Ventilation Solutions, Smart Controls End User: Facility Managers, Contractors, Engineers, Homeowners |
| Companies Covered | MATCOR, Inc, Mears Group, Inc, Chapman Engineering, Inc, Elsyca NV, Corrpro Companies, Inc, SAE Inc, Bass Engineering, APS Materials, Inc, BSS Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC Mitigation System Market Strategic Shifts
Real-time monitoring convergence with automatic reconfiguration capability is compressing the operational boundary between passive grounding hardware and active control systems, forcing vendors to recalibrate R&D roadmaps and service delivery models simultaneously.
Solid-state decoupling devices with embedded current sensors and cellular telemetry modules is rewriting the competitive landscape for pipeline integrity management. Midstream operators in the Permian Basin are deploying these systems at shared-corridor crossings where variable transmission loading previously required manual intervention. The technology is compressing response times to induced voltage excursions from hours to seconds while generating continuous data streams that feed predictive corrosion models.
EPA enforcement of NACE SP0169 documentation requirements is hardening compliance thresholds for AC interference mitigation on interstate natural gas pipelines. The industrial consequence is elevated vendor qualification barriers that favor integrated engineering-procurement-construction firms over component suppliers. Gulf Coast petrochemical corridor operators are responding by consolidating procurement under single-source accountability contracts that bundle design, installation, and long-term monitoring.
Asset owners are unbundling after-sales service from initial equipment supply, creating standalone recurring revenue streams for specialized monitoring firms. This pattern displaces traditional manufacturer-captive service arrangements in favor of third-party pipeline integrity management providers. The shift is most visible among master limited partnerships operating multi-state gathering systems who prioritize operational expenditure flexibility over capital-intensive ownership models.
AC Mitigation System Market Segmentation
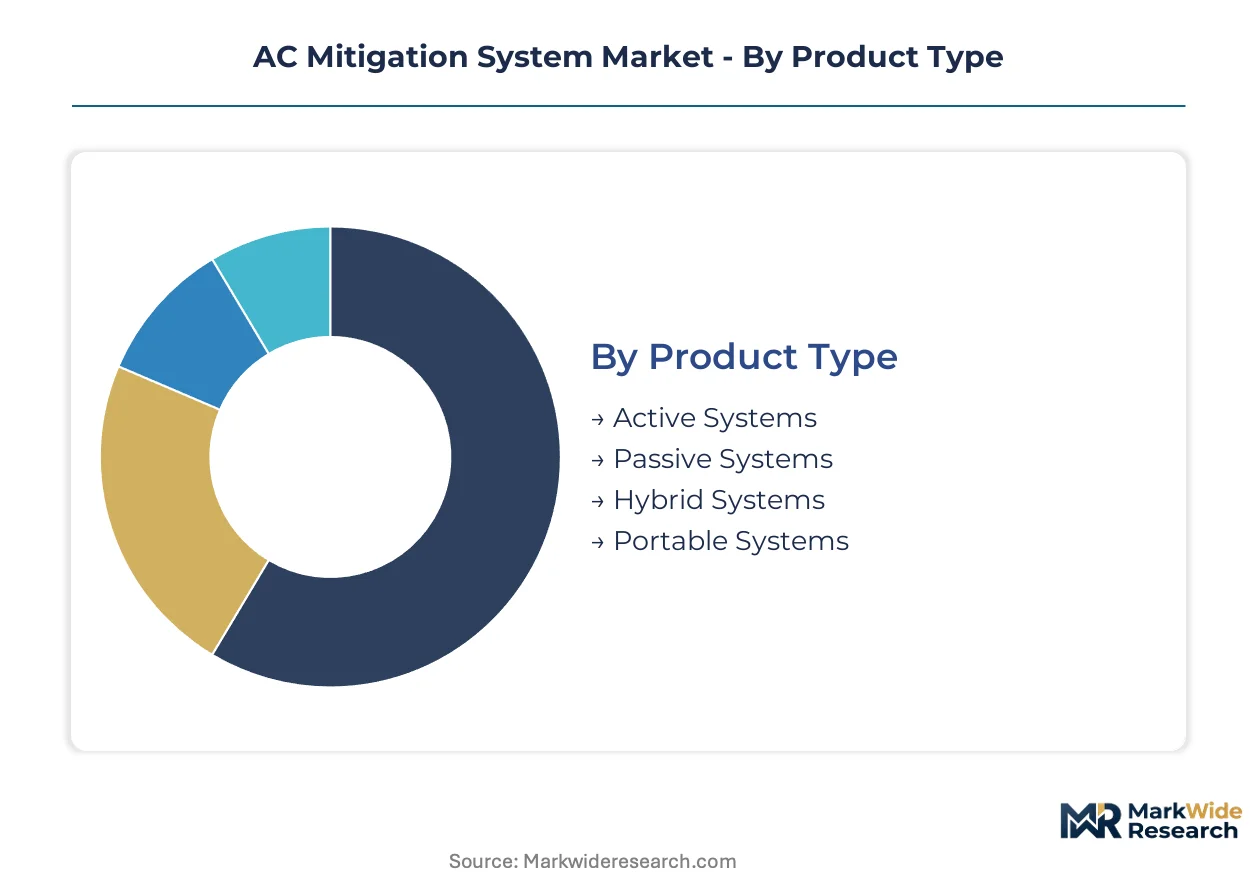
AC mitigation system procurement patterns diverge sharply across product architectures and deployment contexts. Specification complexity intensifies where high-voltage transmission corridors intersect with aging pipeline infrastructure, forcing vendors to align engineering capabilities with distinct operational requirements.
Product Type:
Active and passive architectures anchor fundamentally different procurement economics and service life expectations.
- Active Systems:Solid-state decoupling devices with embedded current sensors enable real-time voltage threshold monitoring and automatic reconfiguration. Demand concentrates among Permian Basin operators managing variable 345 kV transmission loads across shared rights-of-way, driven by FERC-mandated survey documentation requirements.
- Passive Systems:Standardized zinc grounding cells and resistor-capacitor networks deliver predictable interference shunting without external power. Deployment dominates mature Appalachian pipeline corridors where transmission loading profiles remain stable, constrained by 20-30 year replacement cycles that compress recurring revenue.
- Hybrid Systems:Integrated assemblies combining passive grounding hardware with modular sensor packages for selective monitoring activation.
- Portable Systems:Temporary deployment kits for construction-phase interference assessment and emergency response scenarios.
Mature deployment sits with Passive Systems. Newer deployment is concentrated in Hybrid Systems.
Application:
Facility scale and electrical load density determine grounding grid complexity and regulatory scrutiny intensity.
- Industrial Facilities:Pipeline compressor stations, processing plants, and tank farms require engineered grounding assemblies rated for fault currents exceeding 15 kA. Procurement clusters along Gulf Coast petrochemical corridors where EPA NACE SP0169 enforcement has hardened vendor qualification barriers.
- Data Centers:Hyperscale computing facilities demand precision grounding to protect sensitive electronic infrastructure from induced voltage transients. Growth concentrates in Northern Virginia and Dallas-Fort Worth utility corridors where transmission expansion outpaces dedicated substation construction.
- Commercial Buildings:Mid-rise structures with shared utility easements requiring baseline AC interference protection.
- Residential Buildings:Single-family and small multi-family developments with minimal exposure to high-voltage transmission proximity.
Industrial Facilities anchor current procurement volume. Data Centers are climbing the fastest as digital infrastructure expansion accelerates.
Technology:
Thermal and ventilation integration is reshaping how grounding systems coordinate with broader building mechanical infrastructure.
- Smart Controls:Firmware-enabled platforms with cellular telemetry modules feed continuous current data into cloud-based corrosion prediction models. Adoption concentrates among master limited partnerships operating dispersed multi-state gathering systems, driven by operational expenditure flexibility priorities over capital ownership.
- Thermal Management:Heat dissipation engineering for solid-state decoupling devices operating at sustained fault current levels. Deployment focuses on West Texas and New Mexico corridors where summer ambient temperatures stress component longevity.
- Heat Pumps:Ground-source and air-source systems with integrated grounding coordination for electrified building envelopes.
- Ventilation Solutions:Enclosure designs managing humidity and contaminant exposure for exposed grounding hardware.
Basic hardware configurations dominate current installation stock. Smart Controls are gaining share fastest as predictive maintenance platforms displace scheduled field inspection regimes.
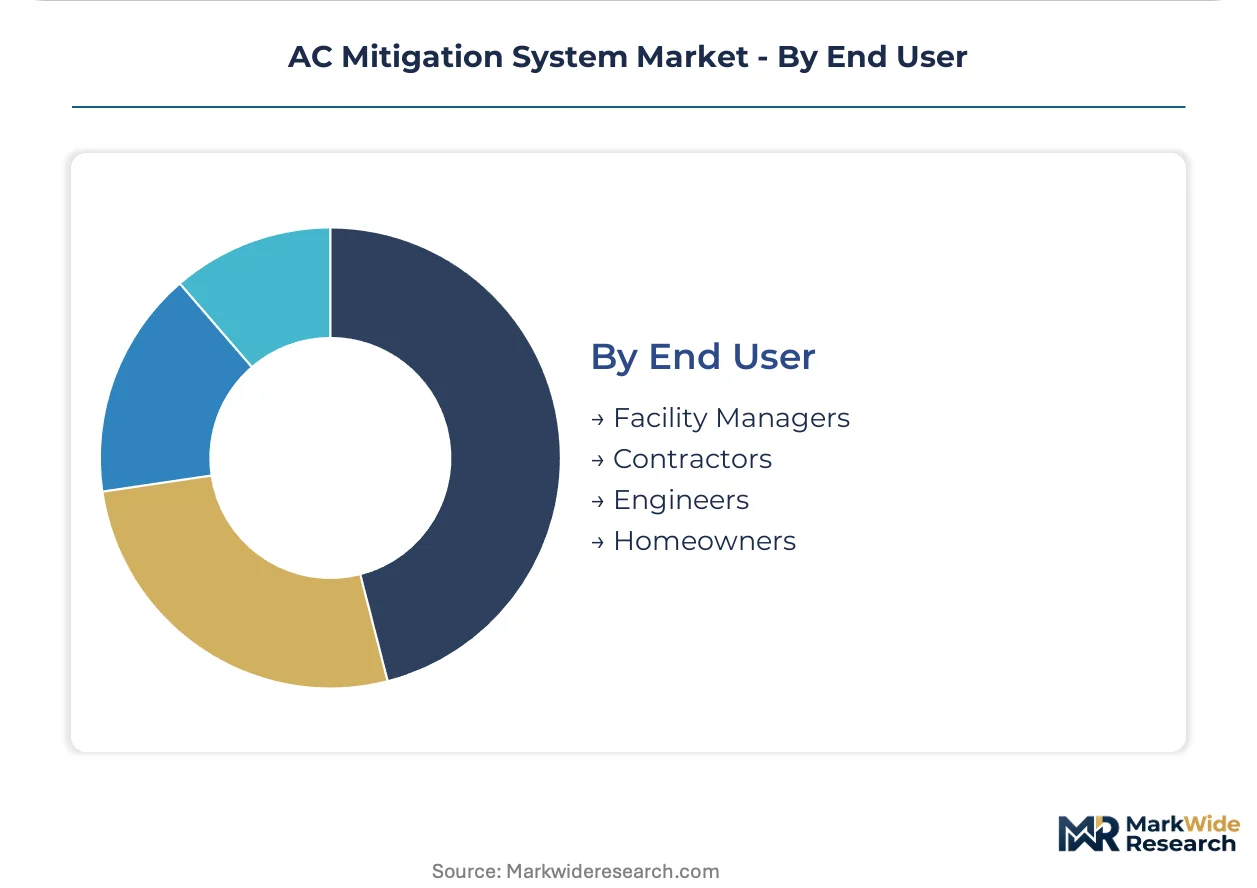
End User:
Technical sophistication and procurement authority fragmentation create distinct vendor engagement patterns.
- Facility Managers:Operating personnel at midstream pipeline and storage terminals with direct accountability for cathodic protection compliance. Procurement authority concentrates among Permian and Appalachian operators consolidating integrity management under centralized technical teams.
- Engineers:Design consultants and owner’s engineers specifying IEEE 80-compliant grounding grids with site-specific soil resistivity modeling. Demand clusters where alluvial floodplain and rocky highland terrain complexity extends engineering timelines.
- Contractors:Installation crews with IEEE 837-compliant exothermic welding certification executing field deployment.
- Homeowners:Individual property owners with minimal technical specification involvement in residential grounding decisions.
Contractor-channel procurement dominates volume throughput. Facility Manager direct engagement is expanding most quickly as operators unbundle after-sales monitoring from initial equipment supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for AC mitigation hardware concentrates in the United States and Germany, while consumption patterns track high-voltage transmission expansion across North American oil basins and European industrial corridors.
United States
FERC interstate pipeline safety regulations and NACE SP0169 documentation mandates are hardening vendor qualification barriers for federally regulated projects. The Permian Basin corridor in West Texas and southeastern New Mexico generates concentrated demand where 345 kV transmission buildouts overlap dense hydrocarbon gathering networks. Midstream operators here are consolidating procurement under single-source accountability contracts.
Canada
TransCanada pipeline network expansion and Alberta oil sands infrastructure maintenance are driving retrofit assessments for aging cathodic protection systems. The country's national energy regulator enforces documentation requirements for AC interference surveys on federally regulated pipelines. Calgary-based engineering firms are capturing assessment service contracts across the Western Canadian Sedimentary Basin.
Germany
Industrial facility grounding upgrades and chemical corridor infrastructure modernization are sustaining demand for IEEE 80-compliant grid designs. The country's national standardization body and EU CE marking requirements govern equipment acceptance for pipeline and tank farm applications. The Rhine-Ruhr industrial cluster anchors procurement volume for fault-current-rated assemblies.
Australia
Mining infrastructure electrification and LNG export facility expansion are creating specifications for AC mitigation on buried steel in remote terrain. The country's national electrical safety regulator mandates grounding system compliance for high-voltage proximity installations. The Pilbara iron ore region and Queensland coal seam gas fields are deploying portable assessment kits for construction-phase surveys.
Saudi Arabia
Petrochemical corridor expansion and renewable transmission interconnects are emerging demand centers for engineered grounding assemblies. The country's national standards body and Gulf Cooperation Council technical regulations are aligning procurement specifications with international IEEE guidelines. The Eastern Province industrial cities of Jubail and Yanbu are integrating AC mitigation into new pipeline construction.
AC Mitigation System Market Competitive Environment
The competitive structure tilts toward integrated engineering-procurement-construction firms over component specialists. Vendor qualification barriers under FERC and NACE regimes are compressing the qualified bidder pool for federally regulated projects. Three archetypes dominate: full-service EPC contractors controlling project timelines, simulation-driven design platforms optimizing configurations pre-deployment, and specialized monitoring firms unbundling after-sales service from equipment supply. Dominant competitive moves include geographic crew consolidation and firmware-enabled predictive maintenance platform development.
Among North American integrated service providers, MATCOR, Inc and Mears Group, Inc exemplify the EPC archetype through control of field installation capacity. Elsyca NV represents the simulation-specialist position with design platform differentiation. These three occupy distinct competitive vectors rather than direct overlap, with MATCOR anchoring long-term service contracts, Mears sustaining geographic dominance through crew control, and Elsyca capturing engineering-intensive specifications requiring site-specific modeling.
| Leading Market Players |
|---|
| MATCOR, Inc |
| Mears Group, Inc |
| Chapman Engineering, Inc |
| Elsyca NV |
| Corrpro Companies, Inc |
| SAE Inc |
| Bass Engineering |
| APS Materials, Inc |
| BSS Technologies |
| Others |
Value Chain & Pricing Dynamics
FERC-mandated AC interference survey documentation is compressing procurement timelines for pipeline operators, forcing supply chains to pre-position certified hardware inventory closer to Permian and Appalachian infrastructure corridors and elevating pricing power for vendors with ready availability.
Pricing Analysis
Margin tightening in passive zinc grounding cell tiers reflects copper and zinc commodity volatility squeezing integrators locked into fixed-price EPC contracts. Three-tier pricing structure across premium solid-state decoupling, standard hybrid assemblies, and economy passive cells tracks certification grade and after-sales monitoring bundling. Cost compression accelerates in the standard tier as master limited partnerships consolidate procurement under single-source accountability contracts. Facility managers at dispersed gathering systems exhibit highest price sensitivity, while Gulf Coast petrochemical operators prioritize vendor qualification over unit cost.
Supply Chain Analysis
Regional distribution centers in Houston, Calgary, and Dusseldorf anchor hub-and-spoke patterns for grounding electrode hardware and solid-state decoupling devices. Manufacturing concentrates in the United States, Germany, and China for resistor-capacitor networks and cellular telemetry modules. Raw material flows draw from Chilean copper cathode, Australian zinc concentrate, and Taiwanese semiconductor components. Single-source vulnerability sits with IEEE 837-certified exothermic welding consumables. Distribution runs through integrated EPC contractors controlling field installation capacity rather than component wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized welding technician scarcity constrains field deployment capacity across North American oil basins, propping vendor pricing power for qualified installation crews and compressing margins for hardware-only suppliers.
For Market Incumbents: Anchor long-term service contracts through proprietary anode sled designs and firmware-enabled predictive maintenance platforms. Defend against unbundling trends by integrating cloud-based threshold alerting with initial equipment supply. Deepen backward integration into exothermic welding certification programs to control crew availability bottlenecks. For New Entrants and Emerging Players: Simulation-driven design platforms for site-specific IEEE 80 grounding grid optimization represent the most penetrable wedge. Target Appalachian Basin retrofit assessments where renewable transmission interconnects generate fresh demand for engineering-intensive specifications. Pursue direct engagement with facility managers at master limited partnerships prioritizing operational expenditure flexibility. For Investors and Strategic Acquirers: The window for entry favors integrated engineering-procurement-construction firms with captive installation capacity. Long-term viability hinges on consolidation of fragmented regional contractors under platforms with FERC and NACE compliance credentials. Monitor state public utility commission rulings on cathodic protection cost allocation as the inflection signal for contract structure economics.| Strategic Initiative | Industry Significance |
|---|---|
| Exothermic Welding Certification Program | Captures scarce technician capacity and locks out uncertified competitors from FERC-regulated projects. |
| Firmware-Enabled Predictive Maintenance Platform | Generates recurring revenue streams that displace scheduled field inspection regimes for pipeline operators. |
| Single-Source Accountability Contracting | Consolidates procurement under integrated EPC firms with design-through-commissioning control. |
| Site-Specific Soil Resistivity Modeling Service | Captures engineering-intensive specifications where alluvial floodplain complexity extends project timelines. |
| Regional Distribution Center Expansion | Pre-positions certified hardware inventory closer to Permian and Appalachian infrastructure corridors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with pipeline integrity managers, cathodic protection engineers, and EPC procurement officers combined with NACE International technical standards, FERC enforcement databases, and IEEE publication archives. Bottom-up equipment shipment tracking and top-down infrastructure investment forecasts were triangulated against utility transmission expansion schedules and pipeline construction permitting data.
Reconciliation of vendor shipment records, transmission corridor mapping data, and cathodic protection retrofit project announcements informed the analytical framework across the projection horizon. Segmentation modeling spanned product architecture, application facility scale, technology integration level, and end-user procurement authority. CAGRs were derived from fitted growth curves calibrated to documented infrastructure buildout timelines and regulatory compliance phase-in schedules. Forecast inputs included Permian Basin 345 kV transmission load projections and NACE SP0169 documentation enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price volatility spikes and IEEE 837 certification program graduation shortfalls. Forecasts reflect documented assumptions regarding transmission corridor co-location rates and state public utility commission ruling timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
HVAC Control System Market
HVAC Systems
Roof Insulation Market
HVAC Systems
Regenerative Heat Exchanger Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
North America Residential Ductwork Design Software Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
Tunnel and Metro Fans Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Roof Vents Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
North America Building Thermal Insulation Market