
 APAC Commercial Glazing System Market | 2026-2036
APAC Commercial Glazing System Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Commercial Glazing System Market Outlook
The gap between premium smart-glazing specifications and commodity tempered glass is shifting procurement patterns across APAC commercial construction. NSG Group leverages its float glass manufacturing scale to anchor supply contracts for large-scale office developments in Tokyo and Sydney. Saint-Gobain competes through specialized low-emissivity coatings that dominate high-performance building envelopes in Southeast Asian humidity zones. AGC Inc. differentiates via integrated production of both substrate and coated glass, sustaining margin control across the value chain.
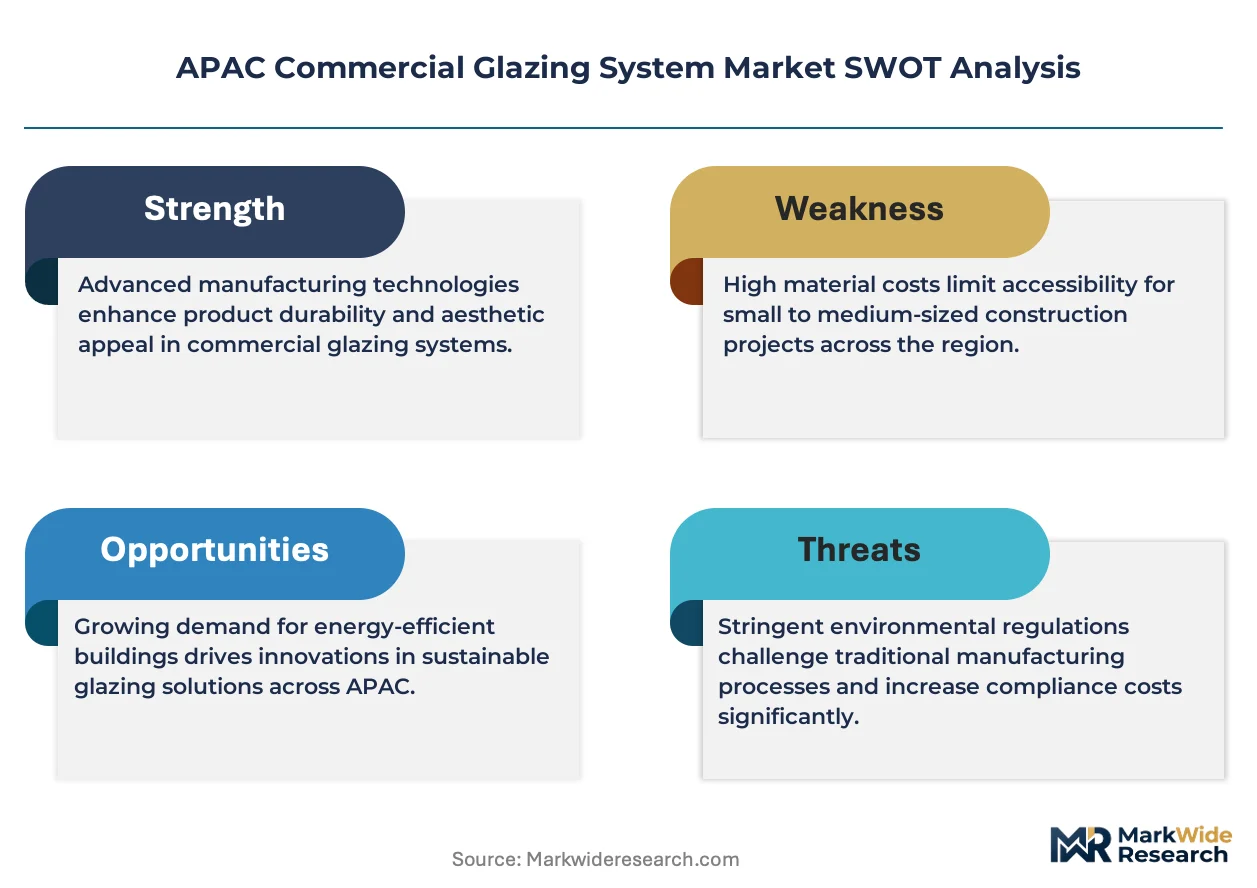
APAC commercial glazing systems encompass engineered glass assemblies, framing hardware, and sealing components designed to manage thermal transmittance, solar heat gain, and structural wind loads in non-residential envelopes. These systems typically achieve U-values below 1.8 W/m²K through multi-cavity insulated configurations with argon or krypton gas fills, serving the primary purpose of reducing HVAC energy consumption while maximizing daylight penetration. Low-E glass captures the fastest expansion as green building codes tighten across the region, while insulated glass units remain the volume backbone due to retrofit demand in aging office stock. Curtain wall systems concentrate the highest margin pools where engineering complexity and installation risk create barriers to commoditization.
China's GB 50189 standard for public building energy efficiency and Japan's METI building carbon intensity targets are reshaping product certification requirements and market access conditions for imported glazing systems. Australia's NCC Section J energy efficiency provisions and India's ECBC code are similarly elevating thermal performance thresholds that disqualify single-pane and basic tempered offerings. Stakeholders must monitor how rapidly evolving national building codes fragment technical specifications across jurisdictions, forcing decisions on whether to develop region-specific product lines or pursue harmonized platforms that trade optimal local compliance against manufacturing complexity.
Market Dynamics
China's GB 50189 energy efficiency standard and Japan's METI carbon-neutral building roadmap are compressing specification cycles across APAC commercial construction, forcing glazing suppliers to recertify product lines against tightening thermal performance thresholds every 18-24 months.
Growth Catalysts
- Curtain wall retrofits:Aging office towers in Shanghai and Singapore require full facade replacement, creating sustained demand for high-performance insulated glass units with sub-1.8 W/m²K U-values.
- Green building certification mandates:China's tier-one cities now tie development approvals to LEED or Three-Star ratings, embedding low-E coated glazing into base specifications rather than optional upgrades.
- Electrochromic smart glass:High-rise commercial developers in Sydney and Tokyo are specifying dynamic tinting systems that cut peak cooling loads by 20-30 percent compared to static low-E alternatives.
Market Restraints
- Float glass supply concentration:Southeast Asian project developers face single-source dependency on Thai and Indonesian float glass producers, exposing schedules to furnace turnaround delays.
- Silver and tin input volatility:Low-E coating production relies on precious metal sputtering targets; spot price swings in silver directly compress coating margins within 60-day contract windows.
- Basic tempered glass substitution:Budget-constrained retail and logistics warehouse developers in India and Vietnam continue specifying single-pane tempered glass, undermining premium glazing penetration in sub-5-story segments.
Strategic Opportunities
- Philippines commercial construction acceleration:Manila's central business district expansion and Cebu IT park developments lack established local glazing supply chains, creating first-mover advantage for integrated system providers.
- Building-integrated photovoltaics convergence:Transparent solar glazing technology is reaching 15-20 percent visible light transmission with 8-12 percent conversion efficiency, opening new revenue streams for facade contractors.
- Australia NCC Section J compliance services:The 2025 National Construction Code updates require whole-building thermal modeling, creating demand for glazing suppliers who bundle performance simulation with product supply.
Industry Challenges
- Facade engineering talent scarcity:Complex curtain wall projects require structural engineers fluent in both wind-load calculations and thermal bridge modeling; APAC universities produce fewer than 400 such specialists annually.
- Multi-jurisdiction certification timelines:A single low-E coating formulation requires separate testing against China's GB/T 18915, Japan's JIS R 3106, and Australia's AS/NZS 4666, stretching product launch cycles to 14-18 months.
- Legacy building structural constraints:1980s-era office towers in Hong Kong and Singapore lack the mullion capacity to support triple-glazed unit weights, forcing costly structural reinforcement or performance compromises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Commercial Glazing System Market |
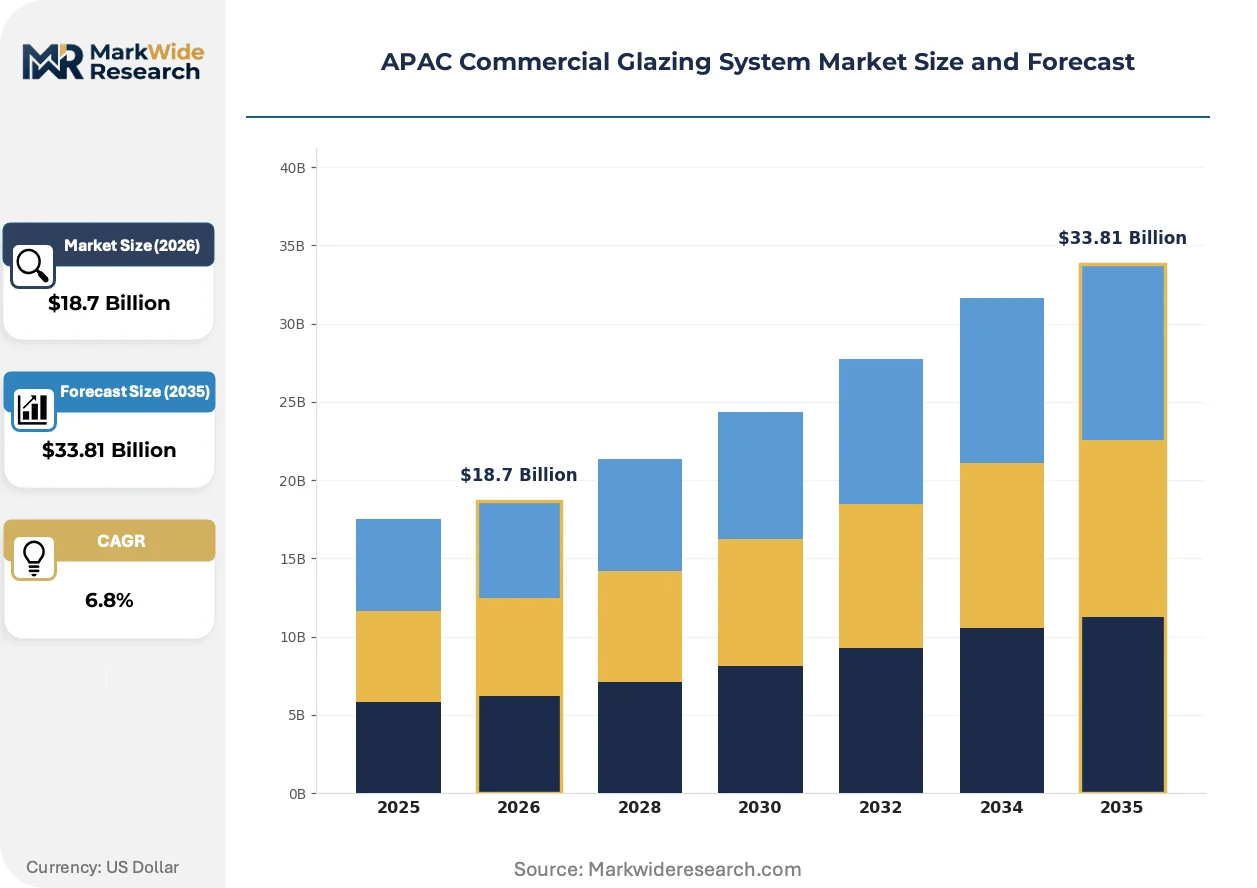
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Glass Units, Laminated Glass, Low-E Glass, Tempered Glass Application: Office Buildings, Retail Stores, Hotels, Educational Institutions Installation Type: New Construction, Renovation, Retrofit, Curtain Wall Systems End User: Architects, Contractors, Developers, Building Owners |
| Companies Covered | NSG Group, Vitro Architectural Glass, Saint-Gobain, Solar Innovations, SageGlass, AGC Inc., Permasteelisa Group, Bayer, Guardian Glass, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Commercial Glazing System Market Strategic Shifts
Active glazing technologies and digital specification tools are compressing the traditional 36-month product development cycle, while regulatory harmonization efforts across ASEAN markets promise to reduce compliance fragmentation for multi-national suppliers.
Vacuum-insulated glazing is overtaking conventional triple-pane units in premium commercial segments. These systems achieve center-of-glass U-values below 0.5 W/m²K using micro-pillars and edge seals rather than gas fills. Tokyo and Singapore developers are specifying vacuum units for net-zero tower projects where floor-to-floor height constraints prohibit 50mm+ triple-pane thicknesses. The technology is overtaking argon-filled triple glazing in markets where space optimization commands premium rents.
China's MIIT building materials efficiency roadmap and Japan's METI carbon intensity disclosure rules are mandating embodied carbon calculations for facade systems. Suppliers must now provide Environmental Product Declarations covering cradle-to-gate emissions for aluminum framing, glass substrate, and sealant components. Australian projects pursuing Climate Active certification are prioritizing suppliers with verified EPDs, shifting competitive advantage from unit pricing to lifecycle transparency.
Developer procurement teams are consolidating glazing specifications across multi-tower portfolios, replacing project-by-project bidding with master service agreements. Singapore-based REITs and Australian superannuation fund developers are locking in 3-5 year supply contracts with fixed escalation clauses. This consolidation is visible most acutely in Sydney's Barangaroo and Melbourne's Docklands precincts, where single glazing contractors now envelope entire districts rather than individual towers.
APAC Commercial Glazing System Market Segmentation
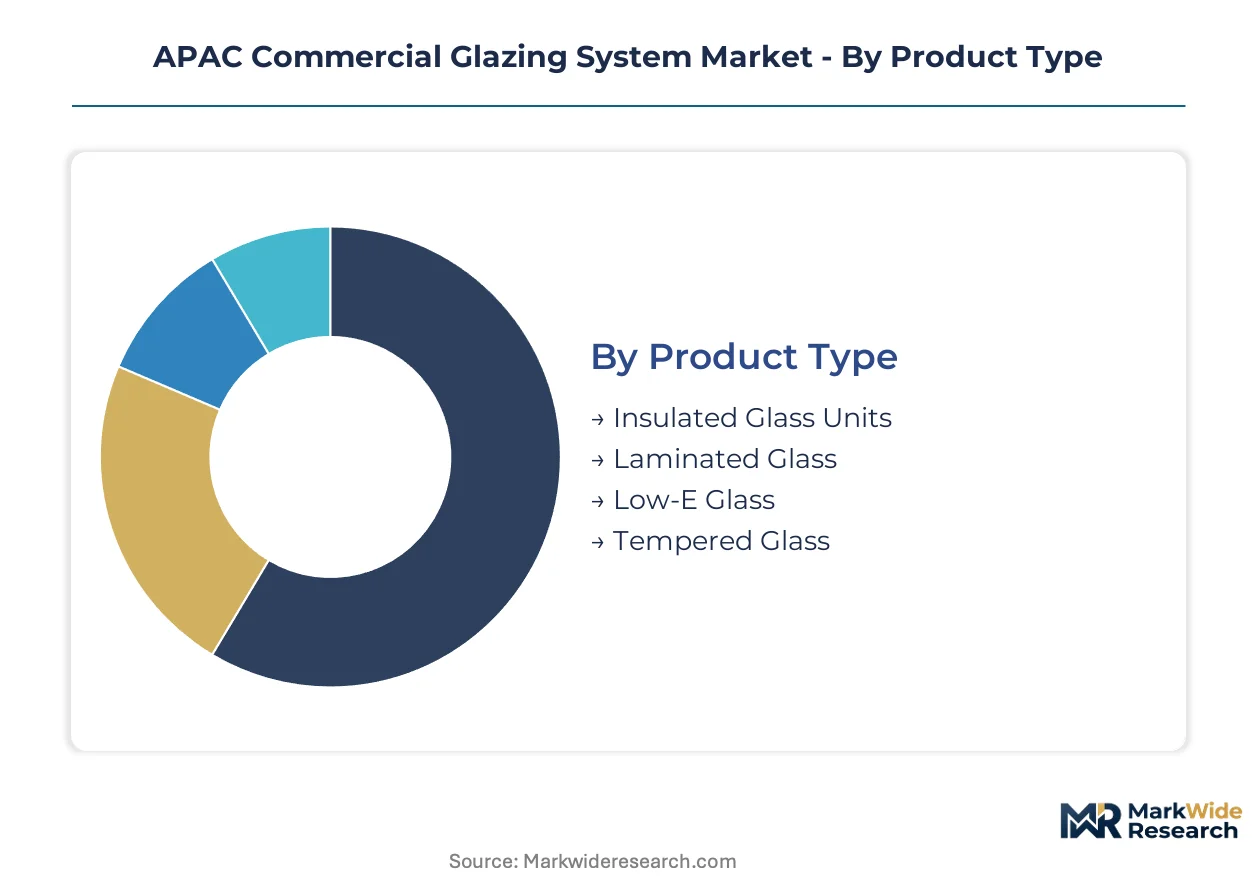
APAC commercial glazing procurement splits across technical performance tiers, project delivery modes, and specification authority chains. Understanding these divisions reveals where margin pools concentrate and which buyer types drive technology adoption versus commodity volume.
Product Type:
Building envelope engineers select glazing products based on thermal performance targets, structural load requirements, and facade integration complexity.
- Insulated Glass Units:Multi-cavity configurations with argon or krypton gas fills achieve U-values below 1.8 W/m²K. Demand concentrates in Shanghai and Singapore curtain wall retrofits where aging office stock requires full facade replacement to meet China's GB 50189 and Singapore's Green Mark standards.
- Low-E Glass:Sputter-coated surfaces with silver-based layers reduce solar heat gain coefficients while maintaining visible light transmission. Tier-one Chinese cities now embed this specification into base building codes rather than optional upgrades, accelerating displacement of uncoated alternatives in LEED and Three-Star certification pathways.
- Laminated Glass:Polyvinyl butyral interlayers bond glass plies for post-breakage retention and acoustic damping.
- Tempered Glass:Heat-strengthened substrates serve structural and safety requirements in low-rise commercial and interior applications.
Volume sits with Insulated Glass Units; growth tilts toward Low-E Glass.
Application:
End-use verticals impose distinct performance hierarchies, with energy intensity and tenant quality expectations determining specification premiums.
- Office Buildings:High-rise towers dominate premium glazing consumption, with Sydney and Tokyo developers specifying electrochromic systems that cut peak cooling loads by 20-30 percent. Net-zero commitments and REIT portfolio standardization are compressing procurement cycles toward master service agreements.
- Hotels:Guest comfort and brand positioning drive acoustic and thermal performance requirements. Luxury properties in Manila's central business district and Melbourne's Docklands prioritize vacuum-insulated glazing where floor-to-floor height constraints prohibit conventional triple-pane thicknesses.
- Retail Stores:Display visibility and security requirements shape laminated and tempered specifications.
- Educational Institutions:Public procurement budgets and extended facility lifecycles favor durable, maintainable insulated configurations.
Revenue concentrates in Office Buildings; steepest expansion trajectory appears in Hotels.
Installation Type:
Project delivery mode determines supply chain configuration, with stick-built versus unitized systems demanding different fabrication and logistics capabilities.
- Curtain Wall Systems:Factory-fabricated unitized panels integrate glazing, framing, and seals off-site, reducing field labor and weather risk. Singapore-based contractors dominate high-complexity tower envelopes where engineering talent scarcity limits competitor entry.
- Retrofit:Full facade replacement of 1980s-era towers in Hong Kong and Singapore faces structural constraints—legacy mullions lack capacity for triple-glazed unit weights, forcing reinforcement costs or performance compromises.
- New Construction:Greenfield developments allow optimized envelope design from structural conception.
- Renovation:Partial facade upgrades preserve existing framing while improving thermal performance.
Margin pools concentrate in Curtain Wall Systems; retrofit volumes are climbing fastest as building stock ages.
End User:
Specification authority chains determine which stakeholder controls glazing selection, with consequences for supplier sales strategy and technical support investment.
- Developers:Portfolio-scale REITs and Australian superannuation funds are consolidating procurement across multi-tower programs, replacing project bidding with 3-5 year master service agreements with fixed escalation clauses.
- Architects:Design authority in premium commercial segments requires facade engineers fluent in wind-load calculations and thermal bridge modeling; APAC universities produce fewer than 400 such specialists annually, constraining project throughput.
- Contractors:Installation risk and warranty exposure drive preference for proven system providers with regional service networks.
- Building Owners:Post-occupancy energy cost accountability is shifting some specification influence from first-cost developers to long-term asset holders.
Contractor relationships anchor current volume; developer direct engagement represents the fastest-climbing influence channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Lujiazui financial district and Singapore's Marina Bay precinct anchor premium glazing demand across APAC, with high-rise retrofits and net-zero tower developments compressing specification cycles.
China
Curtain wall retrofits in Beijing and Shanghai drive volume for sub-1.8 W/m²K insulated glass units. GB 50189 energy efficiency standards mandate thermal performance upgrades for public buildings. The Yangtze River Delta corridor concentrates fabrication capacity and tier-one city project pipelines.
Japan
Tokyo's Otemachi and Marunouchi districts specify electrochromic systems for peak load reduction. METI carbon-neutral building roadmap mandates embodied carbon disclosure for facade materials. Osaka's Umeda Sky Building district exemplifies vacuum-insulated glazing adoption for height-constrained towers.
Australia
Sydney's Barangaroo and Melbourne's Docklands precincts consolidate procurement under master service agreements. NCC Section J energy efficiency provisions require whole-building thermal modeling. New South Wales and Victoria dominate specification authority for commercial envelope engineering.
Singapore
Green Mark certification mandates embed low-E glazing into base specifications for Marina Bay and Tanjong Pagar developments. Building and Construction Authority codes tighten U-value thresholds for commercial retrofits. The city-state's REITs pioneer 3-5 year supply contracts with fixed escalation clauses.
India
Mumbai's Bandra Kurla Complex and Delhi-NCR office towers accelerate LEED certification pathways. ECBC code adoption in Maharashtra and Karnataka elevates thermal performance requirements. Budget-constrained logistics warehouse developers in Gujarat and Tamil Nadu sustain tempered glass demand in sub-5-story segments.
APAC Commercial Glazing System Market Competitive Environment
Premium-margin players sit above commodity-margin players across coating technology and fabrication integration. Float glass manufacturers with captive coating capacity command supply security advantages in project bidding. Two strategic archetypes dominate: integrated substrate-coating producers leveraging raw material scale, and specialized facade contractors capturing installation risk premiums. Competitive moves concentrate on regional certification acceleration and master service agreement capture with portfolio-scale developers.
Among Japan- and Europe-based material science conglomerates, NSG Group, Saint-Gobain, and AGC Inc. occupy positions exemplifying integrated production archetypes. These entities anchor supply relationships through float glass manufacturing scale and coating technology ownership. Specialist electrochromic technology developers including SageGlass represent the dynamic-tinting vector, while Vitro Architectural Glass and Guardian Glass sit within North American-origin coating technology tiers serving APAC project specifications.
| Leading Market Players |
|---|
| NSG Group |
| Vitro Architectural Glass |
| Saint-Gobain |
| Solar Innovations |
| SageGlass |
| AGC Inc. |
| Permasteelisa Group |
| Bayer |
| Guardian Glass |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed float glass producers in Thailand and Indonesia anchor regional supply, translating furnace-scale economies into pricing discipline that resists commodity erosion even when silver coating costs spike. This ownership pattern concentrates bargaining power over Southeast Asian project developers while forcing independent coating specialists to absorb margin compression from precious metal volatility.
Pricing Analysis
Value-based pricing anchored to energy performance outcomes dominates premium segments, with electrochromic and vacuum-insulated glazing commanding premiums tied to measured cooling load reductions. Three-tier pricing structure across premium, standard, and economy levels separates certified low-E systems from basic insulated units and single-pane tempered alternatives. Price differentiation hinges on GB 50189 compliance grade and master service agreement volume scale. Cost compression in economy-tier tempered glass is intensifying because Indian and Vietnamese warehouse developers prioritize first-cost minimization over lifecycle energy savings. Logistics warehouse developers in Gujarat and Tamil Nadu exhibit highest price sensitivity; Singapore REITs and Australian superannuation funds show least.
Supply Chain Analysis
Freight cost exposure runs through maritime routes from Thai and Indonesian float glass furnaces to Manila, Sydney, and Melbourne project sites, with container rate volatility directly impacting landed costs for unitized curtain wall panels. Geographic supply concentrates in China, Thailand, and Indonesia for float substrate; Japan and South Korea for sputtering target refining. Raw material dependencies draw from silver for low-E coatings, tin for float glass production, and aluminum extrusions for framing systems. Single-source vulnerability from Southeast Asian furnace concentration exposes schedules to turnaround delays. Distribution runs through facade contractors with captive installation crews in Singapore and Sydney.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with coating technology ownership and captive float glass supply emerging as the decisive lever for margin defense against commodity glass traders.
For Market Incumbents: Cement supply security through backward integration into float glass production or forward integration into installation services, insulating against Thai and Indonesian furnace bottlenecks. Secure GB 50189 and JIS R 3106 certification acceleration to disqualify coating-only competitors from tier-one city projects. Prioritize master service agreement capture with Singapore REITs and Australian superannuation funds before portfolio consolidation locks out challengers. For New Entrants and Emerging Players: Boutique hotel developers in Manila's central business district and Cebu IT parks represent an underserved buyer archetype lacking established local glazing supply chains and receptive to performance-guaranteed vacuum-insulated solutions. Target Philippines commercial construction acceleration where first-mover advantage remains available for integrated system providers. Pursue Australia NCC Section J compliance bundling—performance simulation services paired with product supply—as the go-to-market angle to bypass entrenched contractor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap coating specialists with stranded silver-sputtering capacity in Japan and South Korea as silver price volatility forces consolidation. Long-term viability over the projection horizon rests on Environmental Product Declaration verification capability as China's MIIT and Japan's METI mandate embodied carbon disclosure. Watch for inflection when Australian Climate Active certification thresholds tighten to exclude non-EPD suppliers from premium precincts like Barangaroo and Docklands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float Glass | Captive substrate supply secures bidding position against Thai and Indonesian furnace bottlenecks in Southeast Asian projects. |
| Master Service Agreement Capture | Three-to-five year contracts with Singapore REITs lock out competitors before portfolio standardization completes. |
| Multi-Jurisdiction Certification Acceleration | Parallel GB/T 18915, JIS R 3106, and AS/NZS 4666 testing compresses product launch cycles from eighteen months toward twelve. |
| Environmental Product Declaration Investment | Verified cradle-to-gate emissions data becomes mandatory for Australian Climate Active and Japan METI carbon disclosure compliance. |
| Facade Engineering Talent Acquisition | Structural engineers fluent in wind-load and thermal bridge modeling command premium as APAC universities produce fewer than four hundred annually. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with curtain wall contractors, facade engineers, building envelope consultants, and procurement directors at Singapore-based REITs. Bottom-up project pipeline analysis across Shanghai Lujiazui, Tokyo Otemachi, Sydney Barangaroo, and Melbourne Docklands triangulated against top-down construction spend forecasts from national statistical agencies. Secondary validation drew from China's MIIT building materials efficiency disclosures, Japan's METI carbon intensity reports, Australia's NCC Section J compliance databases, and ASEAN customs import records for float glass and coated glass shipments.
Granularity-level framing modeled product type at the coating technology and gas-fill configuration level, application at the building height and certification tier level, installation type at the stick-built versus unitized panel level, and end user at the developer archetype level across the analysis window. CAGRs derived from segment-level volume builds calibrated to green building code adoption curves and curtain wall retrofit replacement cycles. Industry-specific forecast inputs included GB 50189 enforcement timelines in China's tier-one cities and METI carbon-neutral building roadmap implementation phases in Tokyo and Osaka.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silver price volatility, ASEAN regulatory harmonization progress, and vacuum-insulated glazing manufacturing yield improvements. Forecasts reflect assumptions about code enforcement consistency, furnace turnaround schedules, and embodied carbon calculation standardization that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
GCC Faucet Market
Building & Construction Materials
Industrial Flooring Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
North America Siding and Decking Market
Building & Construction Materials
Roofing Materials Market
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
ASEAN Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
Turkey Ceramic Tiles Market