
 South Korea Commercial HVAC Market | 2026-2036
South Korea Commercial HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Commercial HVAC Market Insights
Equipment distribution through South Korea's construction-linked dealer networks is narrowing as EPC contractors consolidate preferred vendor lists. Daikin Industries leverages its localized manufacturing footprint to secure multi-year service contracts with major developers. LG Electronics sustains domestic brand loyalty through integrated building management software bundled with hardware sales. Samsung Electronics competes aggressively on smart diagnostics and IoT-enabled predictive maintenance platforms.
South Korea Commercial HVAC encompasses engineered thermal systems designed to regulate temperature, humidity, and air quality within non-residential structures, typically operating at capacities from 5 tons to over 1,000 tons for centralized plant configurations. These systems employ vapor-compression or absorption refrigeration cycles with specified coefficient of performance thresholds mandated under national building codes, serving primarily to maintain occupant comfort and protect temperature-sensitive operations in commercial environments. Chillers retain the dominant share of product type revenue due to their ubiquity in Seoul's high-rise commercial towers, though heat pumps are gaining fastest penetration as building codes tighten carbon intensity limits. Variable Refrigerant Flow technology leads technology category margin pools through premium positioning in boutique retail and medical office fit-outs, while ductless systems occupy a mature niche in smaller commercial retrofits where structural constraints prohibit full ductwork installation.
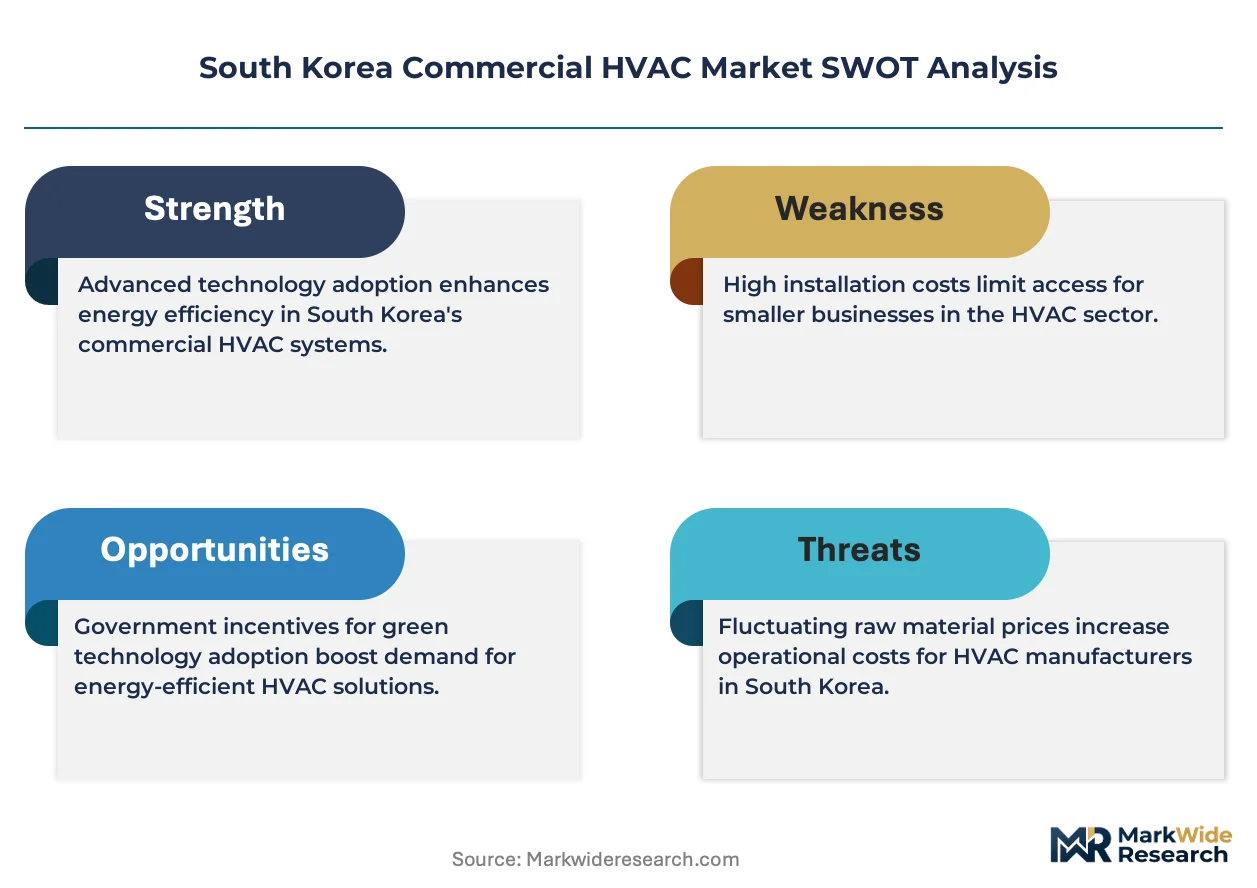
MFDS equipment safety certifications and KEMCO energy efficiency labeling programs jointly determine market access for imported and domestically manufactured HVAC components, with non-compliant units barred from public procurement channels. The Korean Green New Deal framework and building energy codes administered by the Ministry of Land, Infrastructure and Transport are accelerating replacement cycles for legacy systems below current efficiency thresholds. Stakeholders must monitor pending carbon border adjustments and local content requirements that could reshape supplier economics for foreign equipment manufacturers serving Korean commercial projects.
Market Dynamics
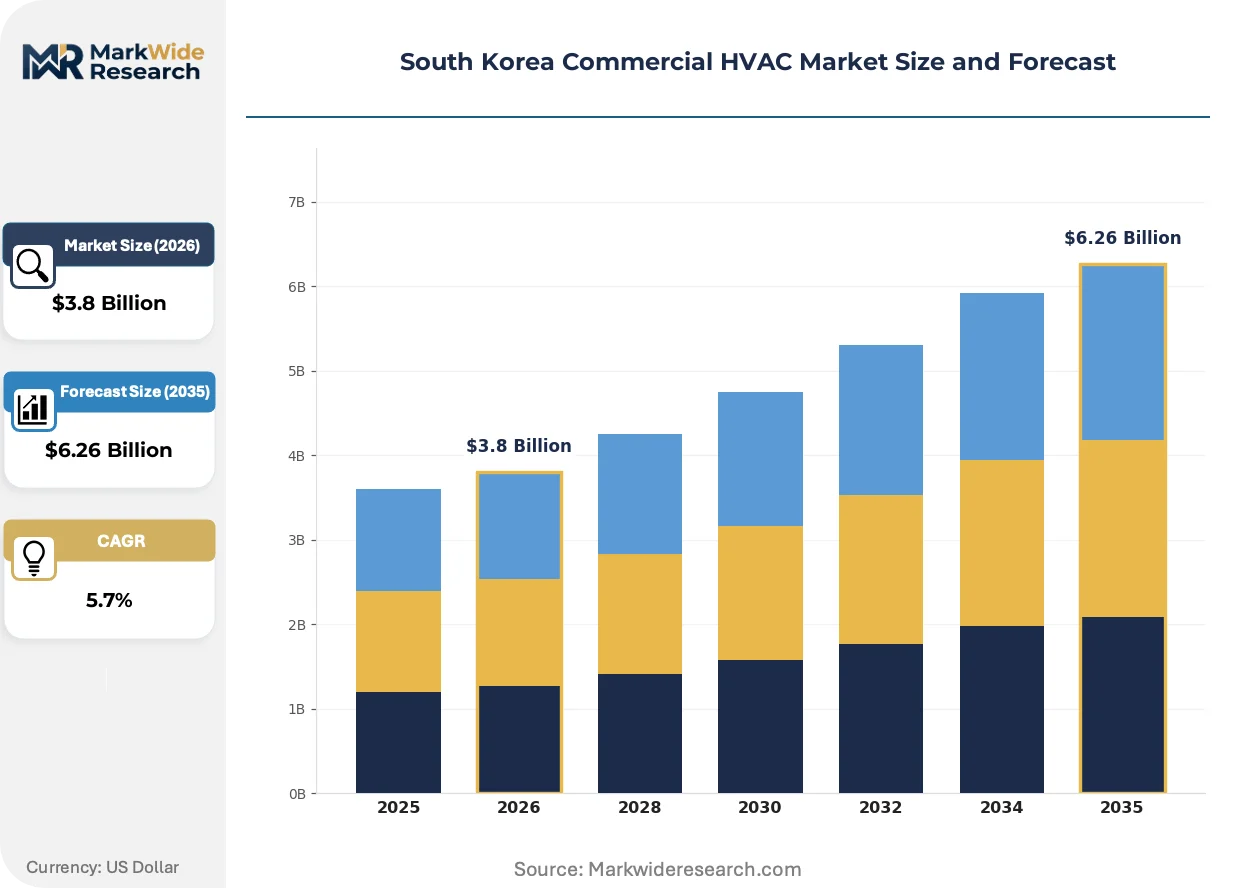
The Korean Green New Deal framework is compressing replacement cycles for legacy HVAC systems as building energy codes administered by the Ministry of Land, Infrastructure and Transport tighten carbon intensity thresholds. Seoul's commercial district redevelopment zone concentrates demand for centralized plant configurations exceeding 500 tons capacity.
Growth Catalysts
- Hospital Infrastructure Modernization:Seoul and Busan medical campuses are accelerating adoption of centralized climate systems to protect temperature-sensitive surgical and pharmaceutical operations. These facilities require redundant chiller configurations with 99.9% uptime specifications.
- KEMCO Energy Labeling Mandates:The national efficiency labeling program administered by the Korean Energy Agency is disqualifying sub-threshold equipment from public procurement channels. This regulatory mechanism forces accelerated replacement of legacy systems in government-leased commercial space.
- Heat Pump Technology Maturation:Vapor-compression heat pumps are capturing fastest penetration in new mixed-use towers as building codes tighten operational carbon limits. Busan's coastal developments favor these systems for simultaneous heating and cooling load management.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchanger manufacturing faces margin compression from base metal price swings on the London Metal Exchange. Korean fabricators lack long-term offtake agreements with Chilean and Australian mining consortia.
- Refrigerant Supply Concentration:HFO-1234ze and R-32 supply chains concentrate among Chinese and Japanese chemical producers. Korean equipment assemblers face allocation risk during peak construction seasons in Seoul's Gangnam and Yeouido districts.
- Absorption Chiller Efficiency Ceiling:Lithium bromide absorption cycles hit thermodynamic limits below electric vapor-compression alternatives. This technical constraint restricts deployment in high-rise towers where footprint efficiency determines system selection.
Strategic Opportunities
- Gwangju and Daejeon Secondary Markets:These metropolitan zones lag Seoul's penetration of smart diagnostics platforms. Local developers seek first-mover positioning in predictive maintenance service contracts for aging commercial stock.
- Carbon Border Adjustment Preparation:The EU's developing CBAM framework creates preemptive demand for lifecycle carbon documentation in Korean export-oriented manufacturing facilities. Equipment suppliers can capture premium positioning through embodied carbon certification.
- VRF-Ductless Convergence:Variable Refrigerant Flow systems are hybridizing with ductless terminal configurations for boutique retail fit-outs. This technology pairing addresses structural constraints in heritage building renovations across Seoul's Bukchon and Insadong districts.
Industry Challenges
- Controls Integration Talent Scarcity:Building automation system programmers with BACnet and Modbus protocol expertise command wage premiums exceeding 40% above mechanical installation trades. Technical institutes in Gyeonggi Province struggle to graduate sufficient cohorts.
- MFDS Certification Timeline Compression:Equipment safety approvals for electromagnetic compatibility and pressure vessel integrity now average fourteen months. This regulatory lag misaligns with developer construction schedules in Seoul's fast-track district redevelopment projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Commercial HVAC Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Boilers, Heat Pumps, Air Handlers End User: Commercial Buildings, Retail Spaces, Hospitals, Educational Institutions Technology: Variable Refrigerant Flow, Centralized Systems, Packaged Units, Ductless Systems Installation Type: New Construction, Retrofit, Replacement, Expansion |
| Companies Covered | Johnson Controls International, Daikin Industries, Carrier Global Corporation, Trane Technologies, Midea Group, LG Electronics, Samsung Electronics, Mitsubishi Electric, Robert Bosch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Commercial HVAC Market Trends and Innovations
Seoul's commercial district redevelopment is accelerating technology hybridization across thermal system architectures. Three distinct vectors are reshaping equipment specification and service delivery models.
Heat pump technology is hybridizing with thermal storage configurations to manage peak demand charges in Seoul's high-rise commercial towers. Major developers in Yeouido and Gangnam districts specify ice-storage or chilled-water tanks paired with electric heat pumps. This architecture compresses operational carbon intensity while maintaining redundancy for financial trading floors and data center operations.
KEMCO's tightening efficiency thresholds under the Green New Deal framework are disqualifying single-speed compressor technologies from new construction permits. The Ministry of Land, Infrastructure and Transport mandates variable-frequency drives for all systems exceeding 20 tons capacity. Premium office fit-outs in Busan's Haeundae district respond by specifying magnetic-bearing centrifugal chillers with integrated power factor correction.
Building operators now unbundle predictive maintenance contracts from original equipment procurement, compressing traditional ten-year service agreements into three-year performance-based renewals. Seoul's institutional investors and REITs drive this shift through asset-level ESG reporting requirements. The separation of hardware capital expenditure from operational service expenditure is most visible in Songdo International Business District's smart city developments.
South Korea Commercial HVAC Market Segmentation
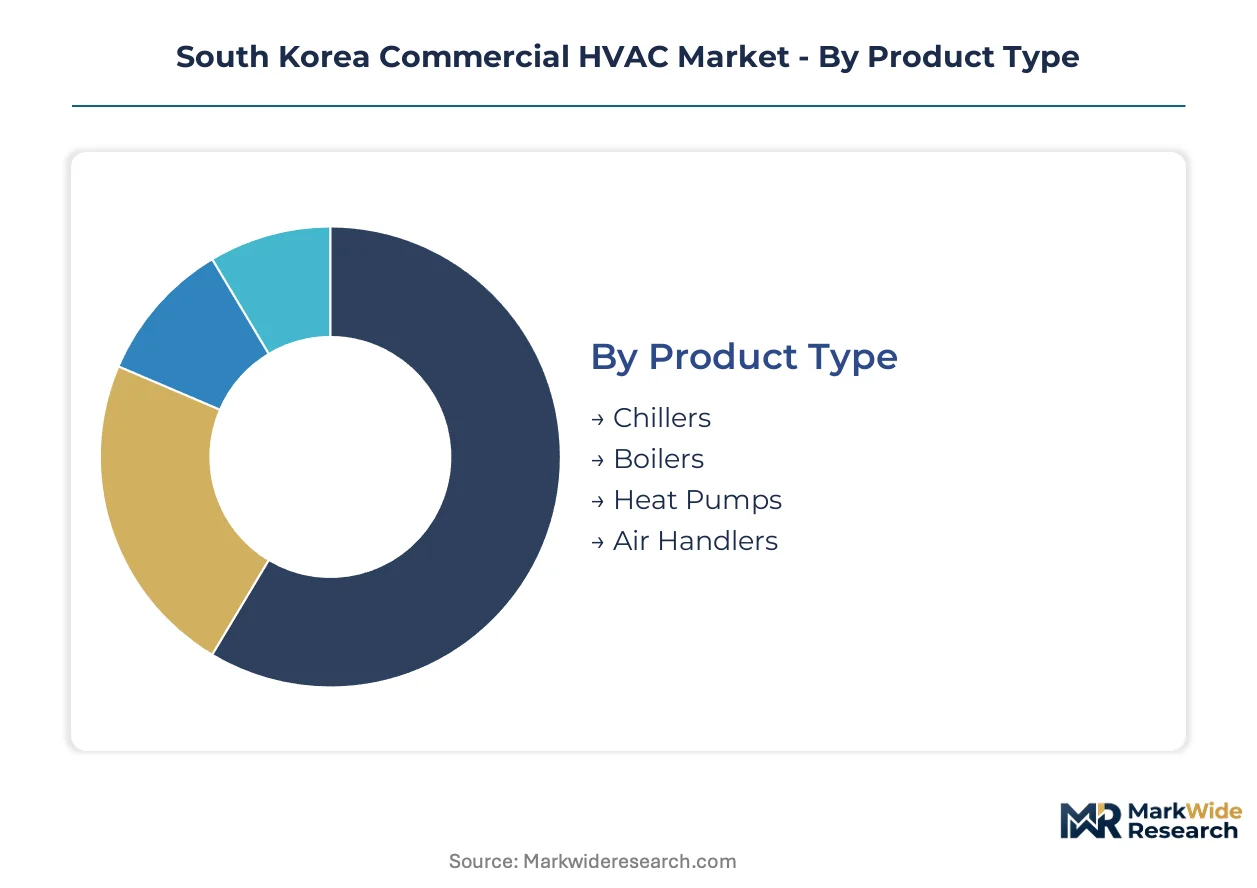
Equipment specification in South Korea's commercial HVAC sector diverges sharply across building vintage, operational load profiles, and regulatory compliance tiers. Procurement patterns cluster around centralized plant configurations for new high-rise developments while retrofit demand favors modular, footprint-constrained alternatives.
Product Type:
Commercial thermal systems span vapor-compression cycles, combustion-based heat generation, and hybrid configurations calibrated to Seoul's tightening carbon intensity benchmarks.
- Chillers:Electric vapor-compression and absorption cycles dominate capacity installations above 500 tons. Seoul's Yeouido and Gangnam commercial towers specify redundant chiller plants with 99.9% uptime guarantees for financial trading floors and data centers.
- Heat Pumps:Vapor-compression systems with reversible refrigerant cycles capture fastest penetration in Busan's coastal mixed-use developments. KEMCO efficiency labeling mandates and Green New Deal carbon thresholds are displacing legacy boiler-only configurations in new construction permits.
- Boilers:Condensing natural gas and electric resistance units retain installed base in legacy commercial stock across Gwangju and Daejeon secondary markets.
- Air Handlers:Centralized fan-coil and dedicated outdoor air systems integrate with chiller plants in hospital and laboratory environments requiring precise humidity control.
The dominant share belongs to Chillers, while Heat Pumps are closing the gap fastest.
End User:
Demand intensity correlates with regulatory scrutiny, operational redundancy requirements, and exposure to public procurement channels.
- Commercial Buildings:High-rise office towers and mixed-use complexes in Seoul's district redevelopment zone specify centralized plant configurations. MFDS safety certifications and KEMCO efficiency labels filter equipment eligibility for these developments.
- Hospitals:Medical campuses in Seoul and Busan require redundant climate systems with continuous temperature control for surgical suites and pharmaceutical storage. These installations command premium specifications for uptime reliability.
- Retail Spaces:Boutique fit-outs in heritage districts favor Variable Refrigerant Flow and ductless configurations where structural constraints prohibit full ductwork installation.
- Educational Institutions:University campuses and public school facilities fall under government lease agreements with accelerated replacement cycles driven by energy code compliance deadlines.
Commercial Buildings generate the highest absolute equipment volume, though Hospitals sustain the steepest expansion trajectory as medical infrastructure modernizes.
Technology:
System architecture selection hinges on capacity requirements, zoning flexibility, and integration with building automation protocols.
- Variable Refrigerant Flow:Refrigerant-based zoning systems with inverter-driven compressors lead margin pools in premium retail and medical office fit-outs. Seoul's Bukchon heritage renovations specify VRF-ductless hybrids to navigate structural constraints.
- Centralized Systems:Chiller plants with distributed air handling dominate new high-rise construction. These configurations align with Seoul commercial district redevelopment timelines and long-term service contract structures.
- Ductless Systems:Mini-split and multi-split configurations occupy mature demand in smaller commercial retrofits. Structural limitations in aging building stock across secondary metropolitan zones sustain this segment.
- Packaged Units:Self-contained rooftop and split systems serve single-tenant commercial properties with lower complexity requirements.
Centralized Systems command the largest installed base, yet Variable Refrigerant Flow is gaining share fastest through premium positioning.
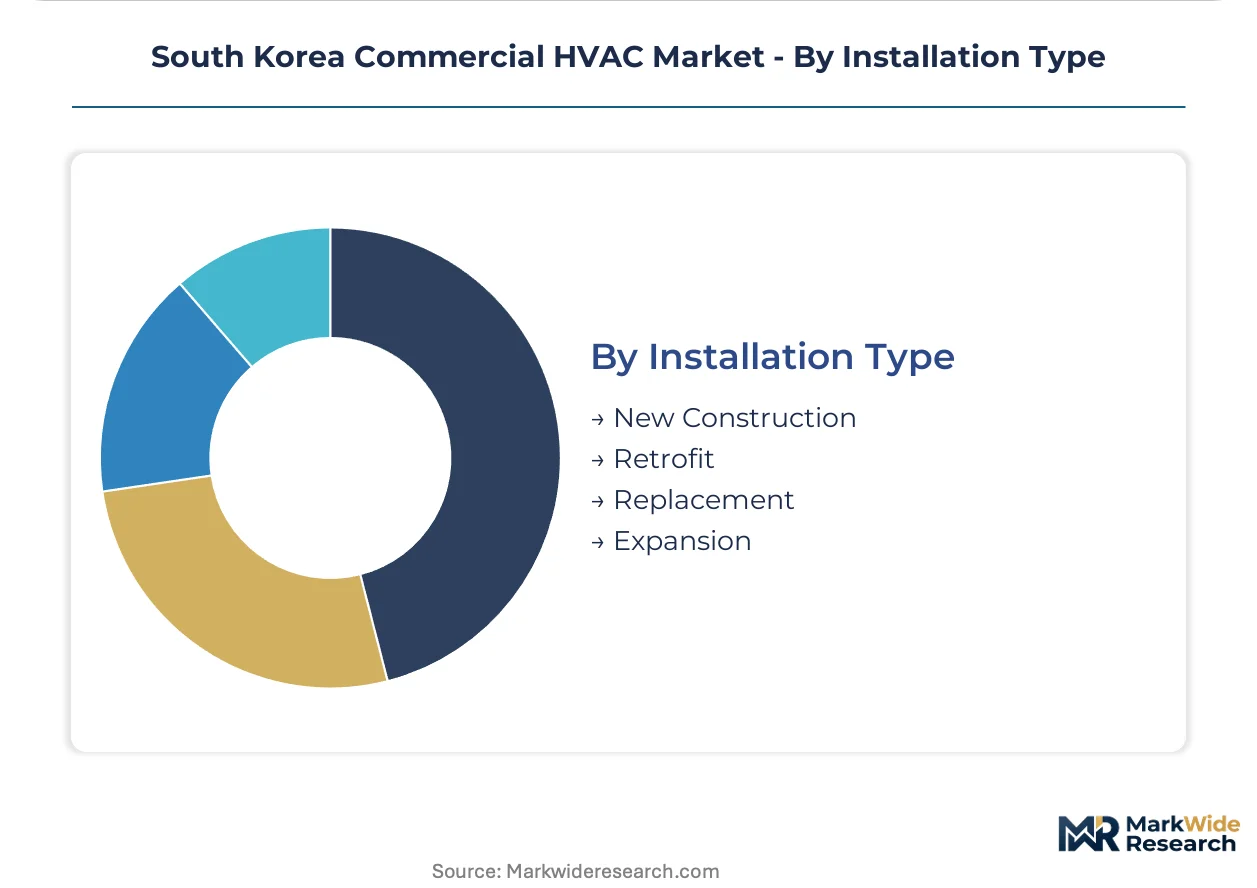
Installation Type:
Project origin determines equipment specification flexibility, financing structures, and regulatory compliance pathways.
- New Construction:Greenfield developments in Seoul's commercial district redevelopment zone specify integrated thermal plants from foundation phase. These projects align with KEMCO's most stringent efficiency tiers under current building energy codes.
- Replacement:Accelerated swap-out of legacy systems below current efficiency thresholds dominates public procurement channels. Government-leased commercial space faces compressed replacement cycles under Green New Deal mandates.
- Retrofit:Equipment upgrades in occupied buildings favor modular, footprint-constrained technologies. Structural limitations in Seoul's Insadong and Bukchon heritage districts drive demand for ductless and VRF configurations.
- Expansion:Capacity additions to existing plants serve data center and laboratory expansions with redundant load requirements.
New Construction absorbs the dominant share of capital expenditure, while Replacement installations are climbing the fastest as regulatory deadlines compress equipment lifecycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area commands premium pricing power over Busan-Ulsan, where hospital infrastructure modernization and coastal mixed-use development concentrate procurement volumes at divergent efficiency tiers.
Seoul Capital Area
High-rise commercial towers in Yeouido and Gangnam districts specify centralized chiller plants exceeding 500 tons capacity. MFDS safety certifications and KEMCO efficiency labeling filter equipment eligibility for financial trading floors requiring 99.9% uptime guarantees. District redevelopment zones absorb dominant capital expenditure on integrated thermal systems.
Busan-Ulsan
Coastal mixed-use developments favor vapor-compression heat pumps for simultaneous heating and cooling load management. The Korean Energy Agency administers efficiency mandates that disqualify sub-threshold equipment from public hospital procurement. Haeundae district premium office fit-outs specify magnetic-bearing centrifugal chillers with integrated power factor correction.
Daegu-Gyeongbuk
Medical campuses accelerate adoption of redundant climate systems for surgical suites and pharmaceutical storage. Green New Deal carbon targets compress replacement cycles for legacy systems below current thresholds. Daegu metropolitan health infrastructure sustains steepest expansion trajectory for uptime-critical specifications.
Daejeon-Sejong
Government-leased commercial space faces accelerated replacement cycles under building energy code compliance deadlines. The Ministry of Land, Infrastructure and Transport mandates variable-frequency drives for systems exceeding 20 tons capacity. Sejong administrative city developments align procurement with KEMCO's most stringent efficiency tiers.
Gwangju-Honam
Secondary metropolitan zones lag Seoul's penetration of smart diagnostics platforms. Local developers seek first-mover positioning in predictive maintenance service contracts for aging commercial stock. Heritage building renovations in Bukchon and Insadong drive demand for VRF-ductless hybrid configurations navigating structural constraints.
South Korea Commercial HVAC Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in heat exchanger and compressor fabrication. The vendor base consolidates around three to five dominant equipment assemblers with localized manufacturing footprints, while mid-scale fabricators compete on retrofit responsiveness. Two strategic archetypes predominate: diversified electronics conglomerates leveraging building management software integration, and dedicated climate equipment specialists securing multi-year service contracts. Competitive moves concentrate on preferred vendor list consolidation by EPC contractors and unbundling of predictive maintenance contracts from hardware procurement.
Within the diversified electronics tier, LG Electronics and Samsung Electronics occupy positions shaped by domestic brand loyalty and smart diagnostics platform development. Daikin Industries anchors the dedicated climate specialist archetype through localized manufacturing and service contract structures. These three exemplify contrasting pathways to procurement influence in Seoul's commercial district redevelopment pipeline.
| Leading Market Players |
|---|
| Johnson Controls International |
| Daikin Industries |
| Carrier Global Corporation |
| Trane Technologies |
| Midea Group |
| LG Electronics |
| Samsung Electronics |
| Mitsubishi Electric |
| Robert Bosch |
| Others |
Pricing and Supply Chain Analysis
Gyeonggi Province's compressor and heat exchanger fabrication clusters concentrate capacity for Seoul's commercial tower developments, translating upstream component scarcity into asymmetric pricing power for integrated equipment assemblers. Korean EPC contractors now consolidate preferred vendor lists around localized manufacturing footprints, compressing margin pools for import-dependent distributors.
Pricing Analysis
The customization-premium spread separates configured-to-order chiller plants with KEMCO Tier-1 efficiency ratings from standard catalog equipment. Project-based pricing dominates new construction in Seoul's district redevelopment zone, where magnetic-bearing centrifugal specifications command substantial premiums over fixed-speed alternatives. Cost compression in the standard equipment tier is intensifying because Chinese manufacturers are penetrating Busan's secondary market through aggressive distributor financing. Government-leased commercial space exhibits highest price sensitivity due to fixed-budget procurement protocols, while hospital infrastructure projects show lowest sensitivity given 99.9% uptime redundancy requirements.
Supply Chain Analysis
Extended payment terms from Korean construction-linked dealer networks now stretch to 180 days, forcing equipment assemblers to activate supply-chain finance facilities with domestic banking consortia. Manufacturing concentration centers on South Korea, China, and Japan for compressor assemblies and refrigerant chemicals. Copper coil and aluminum finstock draw from Chilean and Australian mining operations. Single-source vulnerability concentrates in HFO-1234ze and R-32 refrigerant supply chains among Japanese and Chinese chemical producers. Distribution runs through EPC contractor preferred vendor lists rather than open dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Seoul's district redevelopment EPC contractors as they narrow preferred vendor lists to three dominant equipment assemblers, fragmenting pricing leverage for mid-scale fabricators.
For Market Incumbents: Harden service contract structures against unbundling pressure from institutional investors and REITs demanding asset-level ESG reporting. Deepen backward integration into heat exchanger fabrication to offset copper and aluminum input volatility from London Metal Exchange swings. Prioritize MFDS certification pipeline acceleration to compress fourteen-month approval timelines that misalign with fast-track construction schedules. For New Entrants and Emerging Players: Gwangju and Daejeon's aging commercial stock offers first-mover positioning in predictive maintenance service contracts where smart diagnostics penetration lags Seoul. Target hospital infrastructure modernization in Daegu-Gyeongbuk medical campuses requiring redundant chiller configurations with premium uptime specifications. Pursue carbon border adjustment documentation services for export-oriented manufacturing facilities as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors controls integration specialists with BACnet and Modbus protocol expertise amid acute talent scarcity in Gyeonggi Province technical institutes. Long-term viability hinges on predictive maintenance platform economics unbundled from hardware procurement. Monitor MFDS certification timeline compression as inflection indicator for regulatory lag misalignment with construction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Manufacturing Footprint Expansion | Secures multi-year service contracts with Seoul district redevelopment EPC contractors. |
| Predictive Maintenance Platform Development | Captures unbundled service expenditure from Songdo International Business District REITs. |
| Heat Pump Technology Licensing | Addresses KEMCO efficiency mandates displacing legacy boiler configurations in Busan. |
| Backward Integration into Heat Exchangers | Insulates margin pools from London Metal Exchange copper and aluminum volatility. |
| Carbon Border Adjustment Documentation Services | Captures premium positioning for EU-facing Korean export manufacturing facilities. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with HVAC equipment procurement managers, EPC contractor project directors, and building automation system programmers, alongside secondary validation through KEMCO efficiency labeling databases, MFDS certification registries, and Ministry of Land, Infrastructure and Transport building energy code filings. Bottom-up equipment shipment estimates triangulated against top-down construction permit data across Seoul, Busan, and secondary metropolitan zones.
Forecast inputs span product type segmentation by chiller, heat pump, boiler, and air handler configurations; technology architecture across centralized systems, Variable Refrigerant Flow, and ductless alternatives; and end-use intensity across commercial buildings, hospitals, retail spaces, and educational institutions. CAGRs were derived from regression analysis against construction pipeline data and regulatory compliance deadline schedules. Refrigerant phase-out timelines and carbon intensity threshold trajectories under the Green New Deal framework anchored scenario modeling.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese manufacturers or accelerated refrigerant supply chain regionalization would shift outcomes. Macroeconomic deviation, regulatory timeline compression, or heat pump technology cost breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
Spray Booth Ventilation System Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
Roof Vents Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
Aeration System Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
Global Ductless Heating and Cooling Systems Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Industrial Hood Ventilation Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Split Air Conditioning Systems Market
HVAC Systems
HVAC Control System Market