
 Household Mosaic Tiles Market | 2026-2036
Household Mosaic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Household Mosaic Tiles Market Outlook
Multi-source ceramic procurement is shifting toward vertically integrated supply networks among specialty manufacturers. Fap Ceramiche leverages captive quarry access to sustain margin control across premium stone mosaic lines. Guanyu Ceramics anchors volume production through automated kiln operations in China's Guangdong province. Country Floors differentiates via curated artisan partnerships that limit batch-to-batch color variation.
Household mosaic tiles are small-format decorative surfacing elements, typically measuring under 50 millimeters per side, composed of ceramic, glass, stone, or vinyl substrates bonded to mesh or paper backing for simplified installation. Their primary function delivers moisture-resistant, aesthetically customizable wall and floor coverage in residential wet zones and feature areas. Ceramic material commands the largest installed base due to cost scalability and glaze durability, while glass mosaic captures expanding share in backsplash applications where light reflectivity drives design preference. Geometric design styling is accelerating fastest among new product introductions, though rustic finishes retain margin concentration in heritage restoration segments.
REACH regulations in Europe restrict heavy metal content in ceramic glazes, compelling reformulation investments from export-oriented producers. The EPA's TSCA oversight in the United States governs vinyl substrate emissions, shaping material substitution patterns in budget-tier product lines. China's GB standards for ceramic tile water absorption and breaking strength set baseline compliance thresholds for factory-direct shipments. Stakeholders must monitor evolving chemical disclosure requirements across multiple jurisdictions to preempt supply chain disruption.
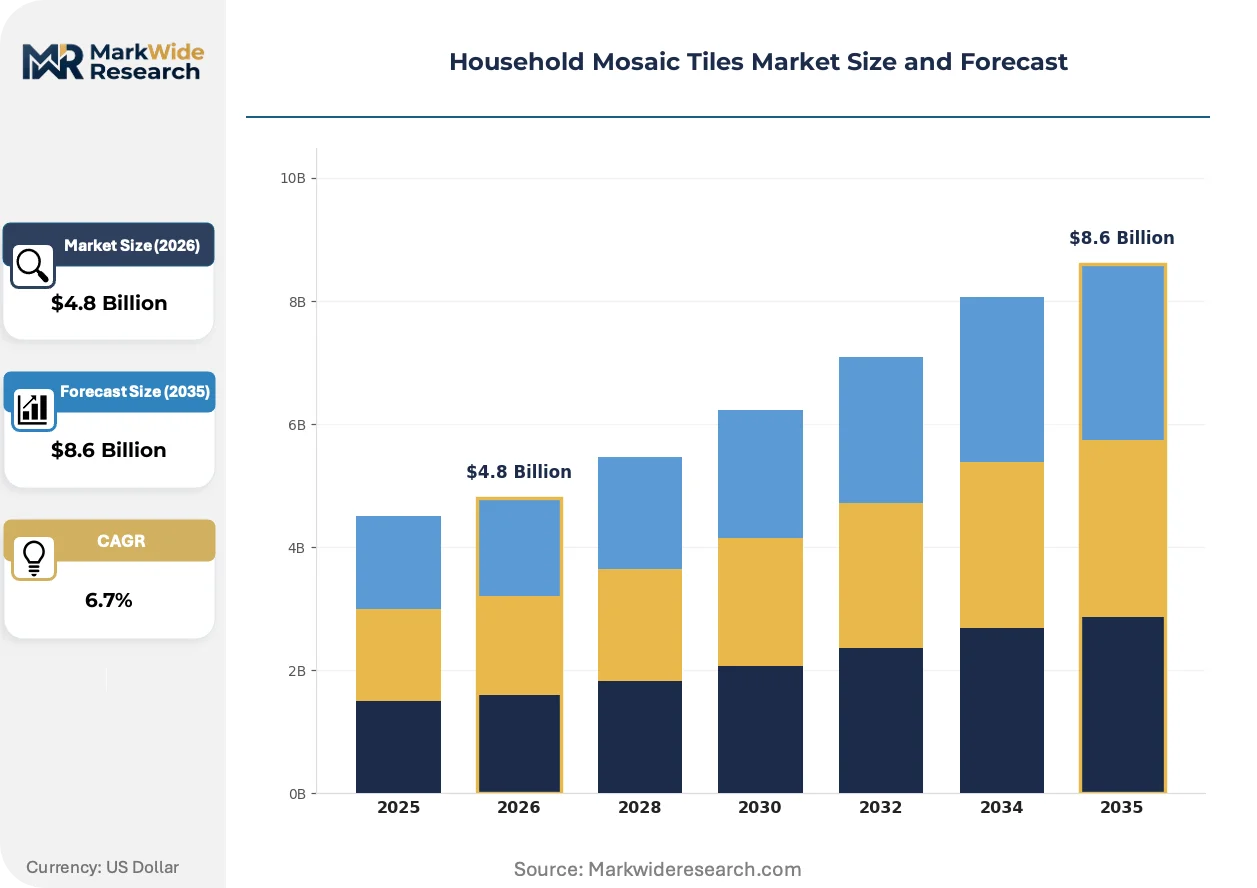
Market Dynamics
REACH compliance across Europe is tightening chemical content thresholds for imported ceramic glazes, forcing reformulation investments and reshaping supplier qualification criteria throughout the value chain.
Growth Catalysts
- Luxury bathroom renovations:Upscale residential properties in Italy's Emilia-Romagna tile manufacturing cluster are accelerating adoption of premium stone mosaic lines.
- REACH regulation enforcement:European chemical disclosure requirements are pushing export-oriented producers toward compliant glaze formulations, creating competitive moats for early adaptors.
- Glass substrate innovation:Light reflectivity properties in glass mosaic are displacing ceramic alternatives in backsplash applications across high-end kitchen installations.
Market Restraints
- Raw material concentration:Captive quarry access for premium stone inputs concentrates among vertically integrated Italian manufacturers, limiting second-tier supply security.
- Energy cost volatility:Automated kiln operations in China's Guangdong province face input cost pressure from natural gas price fluctuations.
- Vinyl substrate substitution:EPA TSCA oversight governing vinyl emissions is driving material substitution toward ceramic and glass alternatives in budget-tier segments.
Strategic Opportunities
- Heritage restoration vertical:Rustic finish mosaics retain margin concentration in building conservation projects across Mediterranean architectural preservation markets.
- Artisan partnership models:Curated batch-to-batch color consistency through direct craftsman relationships offers differentiation in bespoke residential specifications.
- Geometric design acceleration:New product introductions in angular patterning are capturing share among contemporary interior designers specifying feature walls.
Industry Challenges
- Multi-jurisdiction compliance:Stakeholders must monitor evolving chemical disclosure requirements across Europe's ECHA, the United States EPA, and China's GB standards simultaneously.
- Skill gap in artisan coordination:Curated production partnerships require specialized sourcing managers capable of evaluating traditional craftsmanship consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Mosaic Tiles Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Ceramic, Glass, Stone, Vinyl Installation Type: Wall, Floor, Backsplash, Pool Design Style: Modern, Rustic, Vintage, Geometric End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | Country Floors, 41zero42, Tile&Top, Fap Ceramiche, Coem, Guanyu Ceramics, Oasis Tile, Marca Corona, Direct Stone Source, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Mosaic Tiles Market Strategic Shifts
Production technology and regulatory chemistry are converging to reshape how mosaic tiles are manufactured, certified, and specified across residential construction.
Digital inkjet printing is automating glaze application precision on ceramic substrates. High-end bathroom renovators in North American metropolitan markets are specifying these digitally controlled surfaces at expanding volume. This technology is automating color matching consistency that previously required manual artisan intervention, compressing production lead times for custom orders.
ECHA's REACH restrictions on heavy metal content in ceramic glazes are compelling systematic reformulation across export-oriented production bases. Industrial consequence includes accelerated R&D expenditure for lead-free and cadmium-free colorant systems. Italian manufacturers serving European Union markets are responding fastest, leveraging in-house laboratory capabilities to maintain product registration compliance.
Builder procurement patterns are consolidating toward direct factory relationships that bypass traditional distributor markups. Specialty contractors in luxury residential segments are replacing wholesale channel purchasing with container-direct arrangements from Guangdong and Emilia-Romagna production centers. This channel compression is most visible in United States coastal metropolitan markets where project timelines demand shipment reliability over inventory depth.
Household Mosaic Tiles Market Segmentation
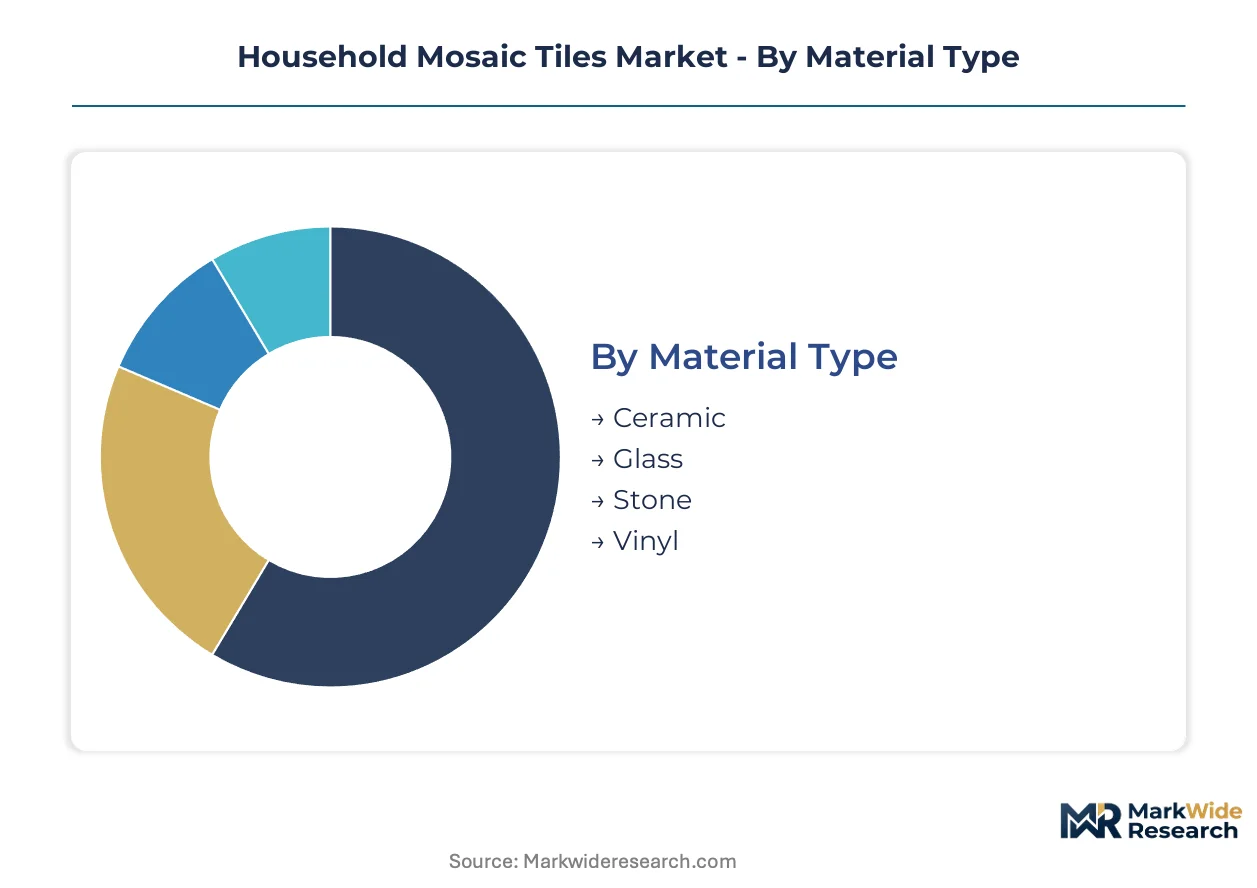
Material composition determines performance characteristics and regulatory exposure across household mosaic tiles. Installation context shapes moisture resistance requirements and aesthetic specifications. Design styling and end-user segments further stratify procurement patterns and margin structures.
Material Type:
Ceramic chemistry and glaze durability anchor specification decisions in wet-zone residential applications.
- Ceramic:Clay-based substrates with vitreous glaze finishes dominate volume production due to cost scalability and breaking strength compliance with China's GB standards. Italian manufacturers in Emilia-Romagna leverage automated kiln operations to supply European bathroom renovation demand.
- Glass:Light-transmitting silica-based tesserae capture expanding specification in kitchen backsplash installations where reflectivity drives contemporary design preference. ECHA REACH compliance on heavy metal content is forcing reformulation of colorant systems among export-oriented producers.
- Stone:Natural marble, travertine, and granite fragments bonded to mesh backing serve heritage restoration and luxury residential segments. Captive quarry access among vertically integrated Italian specialists limits supply security for second-tier procurement.
- Vinyl:PVC-based flexible sheets with adhesive backing target budget-tier residential retrofits. EPA TSCA emissions oversight is accelerating material substitution toward ceramic and glass alternatives in United States distribution.
Ceramic leads on scale; glass leads on momentum.
Installation Type:
Surface placement dictates water absorption thresholds, slip resistance ratings, and substrate preparation requirements.
- Wall:Vertical applications prioritize lightweight mesh-backed sheets with simplified adhesive bonding. North American metropolitan contractors are consolidating procurement toward direct factory relationships from Guangdong production centers.
- Floor:Horizontal load-bearing installations require enhanced breaking strength and abrasion resistance certification. Italian manufacturers maintain specification dominance in upscale European residential properties.
- Backsplash:Kitchen and bathroom counter protection zones favor small-format glass and ceramic tesserae for moisture resistance and cleaning accessibility. Digital inkjet printing is automating color consistency in custom orders.
- Pool:Immersion-grade installations demand frost-resistant glazes and chemical stability against chlorine exposure. Specialized epoxy setting systems differentiate this segment from standard thin-set applications.
Wall installation leads on volume concentration; backsplash leads on design innovation velocity.
Design Style:
Aesthetic categorization determines artisan labor intensity, batch consistency protocols, and target customer procurement channels.
- Modern:Clean lines and monochromatic palettes align with contemporary North American and Western European residential specifications. Digital printing technology compresses lead times for large-format custom orders.
- Rustic:Intentional surface variation and earth-tone coloration serve Mediterranean architectural preservation and heritage restoration markets. Curated artisan partnerships limit batch-to-batch inconsistency.
- Vintage:Period-accurate reproductions of historical patterns require specialized mold fabrication and hand-finishing techniques. Building conservation authorities in Italy and France maintain strict specification standards.
- Geometric:Angular patterning and mathematical repetition are climbing the fastest among new product introductions specified by interior designers for residential feature walls.
Modern styling leads on specification breadth; geometric patterning leads on growth trajectory.
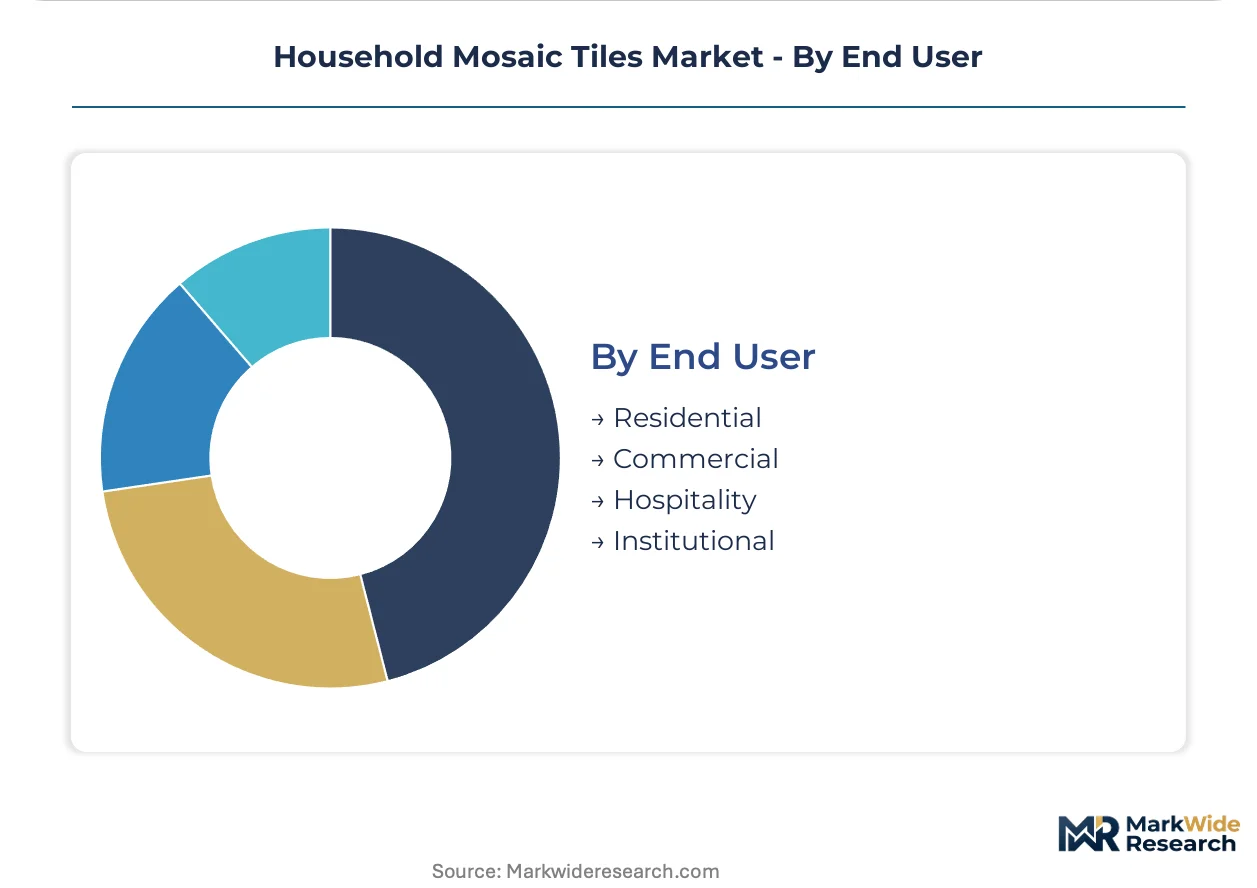
End User:
Customer type determines project scale, timeline flexibility, and compliance documentation requirements.
- Residential:Single-family and multi-unit housing renovations drive volume demand for standardized mesh-backed sheets. Direct container procurement is displacing wholesale channel purchasing in coastal United States markets.
- Commercial:Office and retail fit-outs prioritize durability certification and accelerated installation timelines. Budget-tier vinyl substitution faces regulatory pressure from EPA emissions oversight.
- Hospitality:Hotel and resort properties demand bespoke color matching and large-batch consistency for brand-standard implementation. Curated production partnerships with artisan workshops support this requirement.
- Institutional:Healthcare, education, and government facilities mandate slip resistance ratings, chemical resistance testing, and extended warranty coverage. Documentation intensity favors established European manufacturers with in-house laboratory capabilities.
Residential leads on absolute volume; hospitality leads on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Emilia-Romagna tile manufacturing cluster anchors production concentration for premium stone mosaic lines, with captive quarry access sustaining margin control across European export markets. REACH compliance enforcement by ECHA is tightening chemical content thresholds for imported ceramic glazes, reshaping supplier qualification criteria throughout the value chain. Demand signals from luxury bathroom renovations in upscale residential properties are accelerating adoption across multiple geographies.
Italy
Heritage restoration projects and luxury residential specifications drive demand for rustic finish mosaics in Mediterranean architectural preservation markets. ECHA REACH regulations restrict heavy metal content in ceramic glazes, compelling reformulation investments from export-oriented producers. The Emilia-Romagna manufacturing cluster leverages automated kiln operations and in-house laboratory capabilities to maintain product registration compliance.
United States
High-end bathroom renovators in coastal metropolitan markets are specifying digitally printed ceramic surfaces at expanding volume. EPA TSCA oversight governs vinyl substrate emissions, shaping material substitution patterns in budget-tier product lines. Specialty contractors are consolidating procurement toward direct factory relationships from Guangdong production centers, bypassing traditional distributor markups.
China
Volume production of ceramic mosaic tiles anchors global supply through automated kiln operations in Guangdong province. GB standards for ceramic tile water absorption and breaking strength set baseline compliance thresholds for factory-direct shipments. Guangdong manufacturers face input cost pressure from natural gas price fluctuations affecting automated kiln operations.
Germany
Institutional and healthcare construction mandates drive specification for slip resistance ratings and extended warranty coverage. ECHA REACH compliance requirements favor established European manufacturers with in-house laboratory capabilities for chemical disclosure documentation. North Rhine-Westphalia's industrial base supports precision manufacturing equipment for digital inkjet printing automation.
France
Building conservation authorities maintain strict specification standards for period-accurate reproductions in heritage restoration verticals. ECHA regulations on heavy metal content accelerate R&D expenditure for lead-free and cadmium-free colorant systems. Provence-Alpes-Côte d'Azur's architectural preservation markets retain margin concentration for rustic finish mosaics with intentional surface variation.
Household Mosaic Tiles Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue artisan partnership models and geometric design specialization. The vendor base stratifies across vertically integrated quarry operators, automated volume manufacturers, and curated craft coordinators. Three archetypes dominate: captive resource holders controlling premium stone inputs, scale-driven automated producers, and boutique coordinators managing batch-to-batch color consistency. Competitive moves concentrate on backward integration into raw material security and direct-to-contractor channel compression.
Among Italian specialists, Fap Ceramiche and Marca Corona exemplify the vertically integrated archetype with captive quarry access for premium stone mosaic lines. Guanyu Ceramics represents the scale-driven automated production model anchored in Guangdong province. Country Floors occupies a position within the curated artisan coordination tier, managing batch-to-batch color consistency through direct craftsman relationships for bespoke residential specifications.
| Leading Market Players |
|---|
| Country Floors |
| 41zero42 |
| Tile&Top |
| Fap Ceramiche |
| Coem |
| Guanyu Ceramics |
| Oasis Tile |
| Marca Corona |
| Direct Stone Source |
| Others |
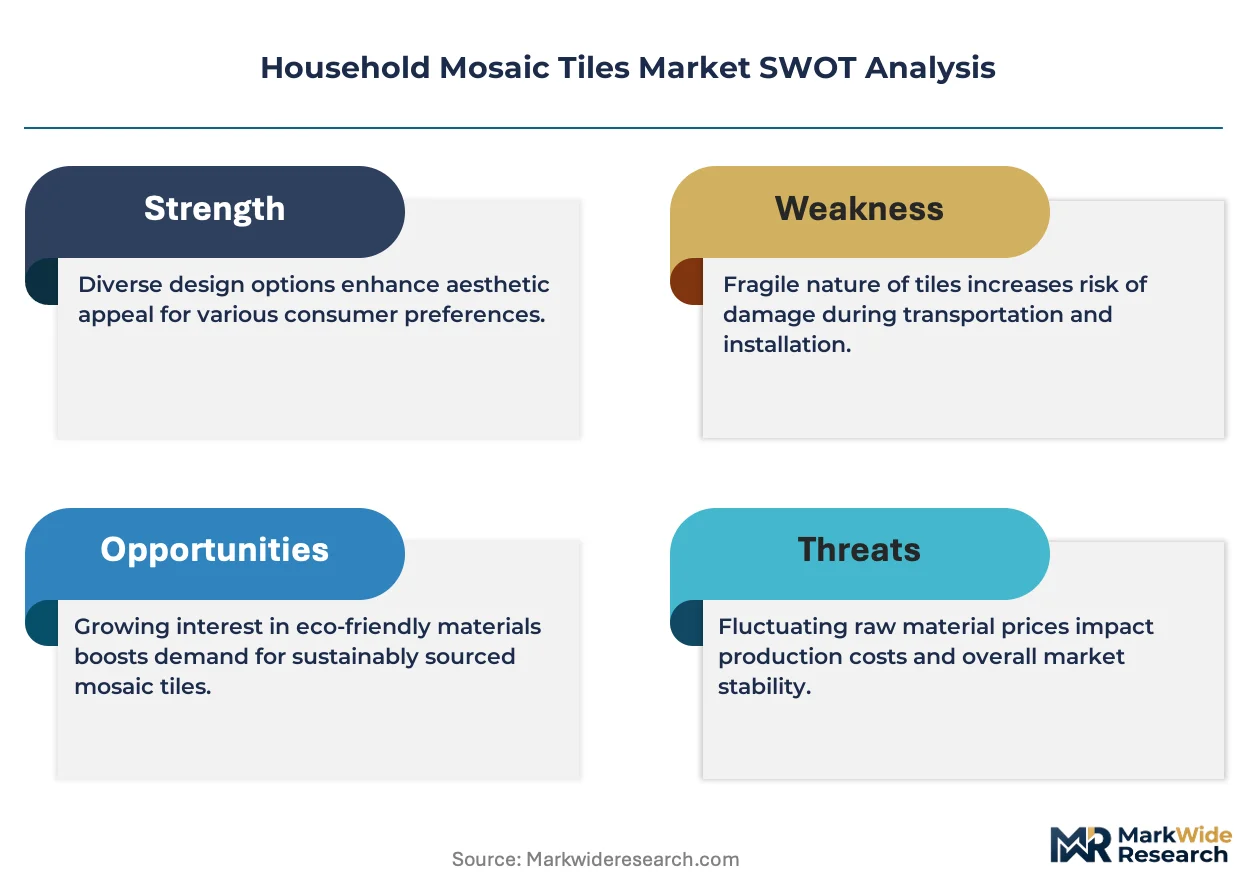
Value Chain & Pricing Dynamics
REACH compliance enforcement by ECHA gates qualified supply access for European market entry and anchors premium-tier pricing power among early-adapting Italian manufacturers with in-house laboratory capabilities. This regulatory filter compresses margins for non-compliant exporters while rewarding captive quarry operators who absorbed reformulation costs ahead of competitor qualification timelines.
Pricing Analysis
Natural gas price pass-through from Guangdong kiln operations is compressing standard-tier margins for volume ceramic producers while Italian stone mosaic specialists maintain pricing power through captive quarry access. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and artisan labor intensity. Pricing pressure stems from energy input volatility affecting automated production economics. Budget-tier vinyl substitution faces acute price sensitivity from residential retrofit contractors, while heritage restoration specifications exhibit minimal elasticity due to conservation authority mandates.
Supply Chain Analysis
Premium stone tesserae supply rests on captive quarry access concentrated among vertically integrated Italian producers in Emilia-Romagna, with volume ceramic production anchored in China's Guangdong province and glass substrate innovation clustering in specialized German manufacturers. Raw material dependencies span natural gas for kiln firing, lead-free colorant systems for REACH compliance, and epoxy setting compounds for pool-grade installations. Single-source vulnerability in artisan workshop partnerships for rustic finish mosaics creates batch consistency risk. Distribution runs through direct factory relationships displacing traditional wholesale channels in North American coastal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where ECHA's heavy metal content restrictions are accelerating demand migration toward compliant producers with certified glaze formulations.
For Market Incumbents: To counter channel compression from direct factory procurement, secure backward integration into captive quarry resources for stone mosaic lines and deepen in-house laboratory capabilities for multi-jurisdiction chemical disclosure documentation. Prioritize certification maintenance ahead of evolving GB standards and EPA TSCA oversight timelines. For New Entrants and Emerging Players: Capture geometric design acceleration in contemporary residential feature wall specifications where digital inkjet printing automation lowers artisan coordination barriers. Target hospitality segment white space demanding bespoke color matching with curated production partnerships. Lead with container-direct reliability messaging to coastal metropolitan contractors. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated mid-cap specialists because captive quarry access and in-house compliance capabilities create durable moats against price-competitive volume imports. Five-to-ten year viability hinges on regulatory adaptation velocity rather than scale alone. Watch ECHA enforcement intensity as inflection signal for compliant producer valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Assets | Captive stone supply secures margin control against raw material concentration risk in Emilia-Romagna. |
| Lead-Free Glaze Reformulation | REACH-compliant colorant systems unlock European market access and sustain product registration validity. |
| Direct Factory Channel Establishment | Container-direct procurement relationships bypass distributor markups in United States coastal metropolitan markets. |
| Artisan Partnership Formalization | Curated craftsman networks limit batch-to-batch color variation for hospitality bespoke specifications. |
| Digital Inkjet Printing Scale-Up | Automated glaze application compresses custom order lead times for geometric pattern demand surges. |
Study Parameters
Bottom-up residential renovation modeling reconciled against top-down ceramic production tracking forms the analytical core. Primary interviews with tile manufacturing plant managers, specialty contractor procurement leads, conservation authority specification officers, and distributor channel partners combined with secondary validation from customs trade data, ECHA chemical registration databases, SEC filings of listed building materials companies, and Italian ceramic industry association reports. Triangulation across supply-side capacity announcements and demand-side project pipelines calibrated volume estimates.
Input-output matrices mapped material flows from quarry extraction through kiln firing to end-use installation across the projection horizon. Segmentation dimensions modeled include material substrate type, installation surface placement, design style category, and end-user vertical. CAGRs derived from regression analysis of historical production data against renovation spending indices and regulatory compliance cost curves. Forecast inputs incorporated natural gas price volatility assumptions and REACH enforcement probability weightings.
Energy cost spikes, regulatory timeline accelerations, and artisan labor availability constraints are the dominant revision risks. Forecasts reflect documented assumptions on compliance cost absorption rates and channel shift velocity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Aluminum Curtain Wall Market
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
GCC Faucet Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market
Building & Construction Materials
GRC Conduit Fittings Market